
 India E-Commerce Warehousing Market | 2026-2036
India E-Commerce Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
India E-Commerce Warehousing Market Insights
Modular fulfillment configurations is restructuring buyer procurement across India's e-commerce warehousing sector. Delhivery leverages its multi-client fulfillment architecture to serve diverse platform requirements. Ekart Logistics anchors its operations through captive integration with parent ecosystem demand. XpressBees competes via specialized last-mile adjacency to its warehousing nodes.
India e-commerce warehousing encompasses facilities designed for inventory receipt, storage, order picking, and dispatch operations serving online retail fulfillment, typically incorporating rack-supported structures with 8-12 meter clear heights and throughput capacities exceeding 5,000 orders per day. Fulfillment centers command the dominant share of new capital allocation as platforms prioritize same-day and next-day delivery promises. Automated storage systems represent the fastest-expanding technology integration category, driven by labor cost inflation and order volume volatility. Warehouse management systems form the baseline infrastructure layer across all facility tiers, creating concentrated vendor relationships for software providers.
BIS standards for structural safety and fire suppression systems govern facility construction parameters, while India's CEA electrical clearance requirements shape power infrastructure design for automated installations. The PLI scheme administered by DPIIT channels subsidy support toward greenfield automated warehousing investments, altering project finance structures for developers. Stakeholders must evaluate land assembly timelines against state-level warehousing policy variations before committing capital to specific locations.
Market Dynamics
India's PLI scheme for logistics infrastructure is redirecting capital toward automated material handling equipment, compressing project payback periods and accelerating facility commissioning timelines across Maharashtra and Karnataka clusters.
Growth Catalysts
- Production-Linked Incentive Scheme:DPIIT-administered subsidies reduce capital burden for greenfield automated warehousing investments. Developers restructure project finance to capture these benefits.
- Same-day delivery promises:Online grocery platforms and horizontal marketplaces demand fulfillment centers with throughput capacities exceeding 5,000 orders per day. Third-party logistics providers expand footprint to serve this requirement.
- Labor cost inflation:Warehouse operators deploy automated storage systems to offset wage pressures in Mumbai-Pune and Bengaluru corridors. Technology integration accelerates across tier-1 facilities.
Market Restraints
- Land assembly timelines:State-level warehousing policy variations create permitting friction. Developers face extended pre-construction phases in Karnataka and Telangana.
- Power infrastructure requirements:CEA electrical clearance mandates shape design parameters for automated installations. Compliance adds capital intensity to facility upgrades.
- Specialized talent scarcity:Warehouse management system integration and automated equipment maintenance require technical skills concentrated in limited urban labor pools.
Strategic Opportunities
- Tier-2 city penetration:Underpenetrated markets in Ahmedabad, Jaipur, and Lucknow present white space for fulfillment center deployment. Platforms seek proximity to emerging consumer bases.
- Green building certification:BIS structural safety standards and evolving fire suppression requirements create differentiation for developers achieving premium compliance tiers.
- Multi-client fulfillment architecture:Shared infrastructure models reduce per-unit costs for mid-scale e-commerce platforms. Operators capture economies across diverse client portfolios.
Industry Challenges
- Legacy system integration:Established warehouse management systems resist seamless connectivity with new automated material handling equipment. Operators face downtime risks during migration.
- Certification timeline compression:BIS structural safety approvals and state-level fire department clearances create bottlenecks. Projects stall awaiting sequential regulatory sign-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India E-Commerce Warehousing Market |
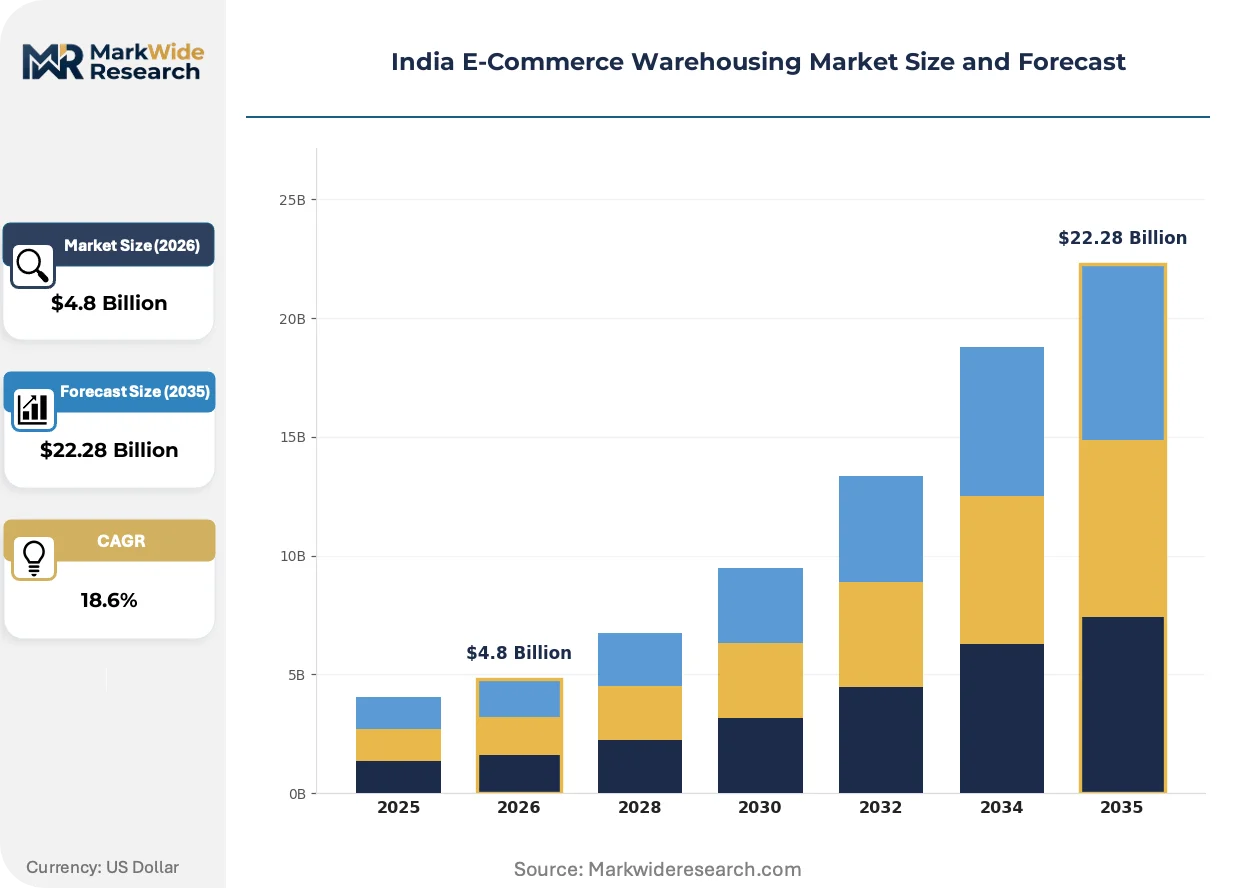
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Warehousing Type: Fulfillment Centers, Distribution Centers, Cross-Docking Terminals, Dark Stores Storage Solution: Racked Storage, Bulk Storage, Automated Storage, Refrigerated Storage Inventory Management: Just-in-Time, FIFO, LIFO, Consignment Stock Technology Integration: Warehouse Management Systems, Robotics, IoT, Artificial Intelligence |
| Companies Covered | Delhivery, Ekart Logistics, XpressBees, Blue Dart Express, Mahindra Logistics, Transport Corporation of India, Allcargo Logistics, Eshopbox, WareIQ, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India E-Commerce Warehousing Market Trends and Innovations
Automated technologies and regulatory incentives are compressing fulfillment timelines while reshaping facility design standards across Indian e-commerce warehousing.
Autonomous mobile robots are overtaking conventional conveyor-based sorting systems in high-throughput fulfillment centers. Large horizontal marketplaces and dedicated grocery platforms deploy these systems to manage order volume volatility. Labor dependency contracts as robotic density increases across Maharashtra and Karnataka facilities.
DPIIT's PLI scheme for logistics infrastructure channels subsidy support toward capital-intensive automation investments. Project developers restructure financing to front-load incentive capture during construction phases. Greenfield automated warehousing investments in Mumbai-Pune corridor respond most aggressively to this policy architecture.
Platform procurement of warehousing services compresses toward outcome-based contracts tied to delivery speed guarantees. Third-party logistics providers absorb inventory risk in exchange for volume commitments from parent ecosystem platforms. This shift concentrates most visibly in Bengaluru's cluster where captive and merchant fulfillment models compete directly.
India E-Commerce Warehousing Market Segmentation
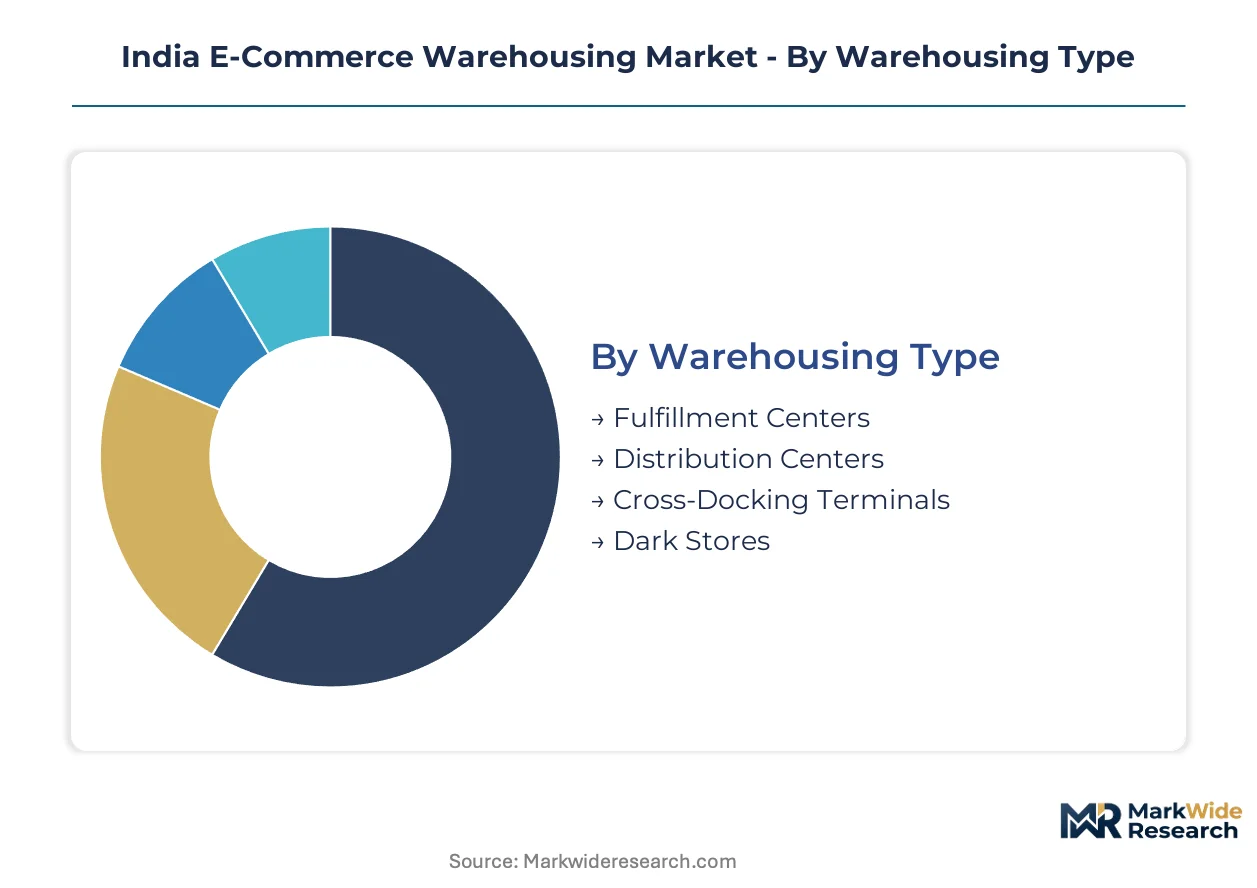
Segmentation reveals how India's e-commerce warehousing operators allocate capital across facility types and automation tiers. Procurement patterns diverge sharply between grocery platforms demanding refrigerated throughput and horizontal marketplaces optimizing for general merchandise velocity.
Warehousing Type:
Fulfillment centers capture volume leadership while dark stores command premium positioning for ultra-fast delivery promises.
- Fulfillment Centers:These rack-supported structures with 8-12 meter clear heights process over 5,000 orders daily through automated picking and packing workflows. Mumbai-Pune corridor developers prioritize these assets to serve same-day delivery commitments from horizontal marketplaces.
- Dark Stores:Micro-fulfillment nodes positioned within 3-5 kilometers of dense urban consumption zones enable 10-30 minute grocery delivery windows. Bengaluru cluster operators deploy these for perishable inventory holding with limited SKU depth.
- Distribution Centers:Regional consolidation hubs manage inbound freight from suppliers and outbound allocation to last-mile nodes.
- Cross-Docking Terminals:Flow-through facilities minimize inventory dwell time for high-velocity general merchandise.
Today's leader: Fulfillment Centers. Tomorrow's challenger: Dark Stores.
Storage Solution:
Automation intensity separates cost tiers as labor inflation forces capital redeployment away from conventional racked configurations.
- Automated Storage:Vertical lift modules and shuttle systems compress floor space requirements while accelerating retrieval speeds. Maharashtra developers leverage PLI scheme subsidies to offset capital intensity in greenfield deployments.
- Refrigerated Storage:Temperature-controlled chambers maintain 2-8°C for pharmaceuticals and frozen corridors for grocery platforms. Karnataka facilities face power infrastructure constraints under CEA electrical clearance mandates.
- Racked Storage:Conventional selective racking dominates existing facility stock across tier-2 cities.
- Bulk Storage:Floor-stacked configurations serve seasonal inventory surges and large-format merchandise.
Automated Storage is gaining share fastest as wage pressures mount in tier-1 corridors.
Inventory Management:
Velocity requirements determine methodology selection with perishable categories forcing strict rotation protocols.
- Just-in-Time:Cross-docked inventory minimizes carrying costs for high-turnover electronics and fashion SKUs. Platform procurement teams negotiate vendor-managed inventory terms to shift working capital burden upstream.
- FIFO:First-in-first-out rotation prevents obsolescence in grocery and pharmaceutical verticals where expiry tracking is mandatory.
- LIFO:Last-in-first-out suits non-perishable general merchandise with stable demand patterns.
- Consignment Stock:Supplier-owned inventory reduces balance sheet pressure for mid-scale platforms expanding SKU breadth.
Just-in-Time dominates capital-efficient operations. FIFO commands regulatory adherence in regulated verticals.
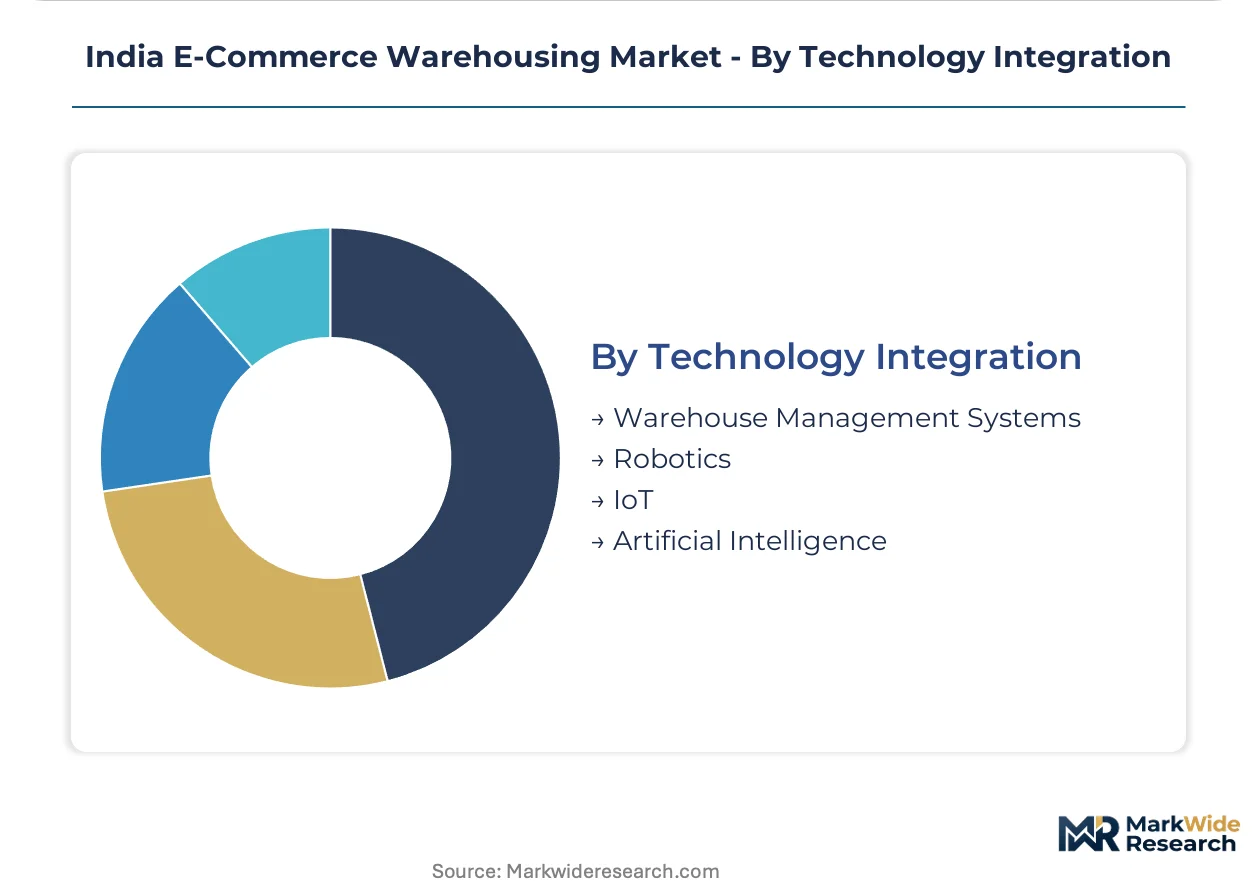
Technology Integration:
Software infrastructure forms the baseline layer while robotics deployments concentrate in high-throughput facilities.
- Warehouse Management Systems:These platforms coordinate inventory tracking, order orchestration, and labor allocation across facility tiers. WMS vendors maintain concentrated relationships with third-party logistics providers serving multiple client portfolios.
- Robotics:Autonomous mobile robots displace conveyor systems for flexible sortation and goods-to-person picking. Bengaluru cluster facilities lead deployment density as order volatility strains manual workflows.
- IoT:Sensor networks monitor environmental conditions and equipment performance for predictive maintenance.
- Artificial Intelligence:Demand forecasting and slotting optimization algorithms improve space utilization and labor routing.
Warehouse Management Systems anchor current operations. Robotics is climbing the fastest as labor scarcity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce warehousing in India traces its modern lineage to the 2010s scaling of horizontal marketplaces, which concentrated initial fulfillment infrastructure in Maharashtra's industrial corridors before radiating to Karnataka and Gujarat as smartphone penetration deepened.
Maharashtra
Mumbai-Pune corridor anchors the highest throughput fulfillment center density, driven by same-day delivery promises from grocery platforms and horizontal marketplaces. DPIIT's PLI scheme for logistics infrastructure accelerates automated material handling deployments across Thane and Pune districts. Developers in Chakan and Talegaon industrial zones front-load subsidy capture during greenfield construction phases.
Karnataka
Bengaluru cluster generates demand from technology sector employment density and elevated consumer expectations for rapid fulfillment. BIS structural safety standards and CEA electrical clearance mandates shape power infrastructure design for automated installations in Hoskote and Whitefield sub-markets. Dark store proliferation concentrates within 3-5 kilometer radii of Whitefield and Electronic City consumption zones.
Telangana
Hyderabad's pharmaceutical and electronics manufacturing base creates specialized cold chain and high-velocity fulfillment requirements. State-level warehousing policy variations extend land assembly timelines compared to Maharashtra, compressing developer margins. Shamshabad and Medchal industrial corridors attract automated storage investments targeting South Indian market access.
Gujarat
Ahmedabad-Surat corridor leverages port connectivity for import-dependent inventory consolidation. GIFT City regulatory framework and streamlined permitting attract third-party logistics providers seeking multi-client fulfillment architectures. Sanand industrial zone hosts captive fulfillment operations for automotive and consumer electronics platforms.
Haryana
Delhi-NCR spillover demand concentrates in Manesar and Sohna sub-markets as land scarcity and pollution control restrictions constrain core National Capital Territory expansion. DGFT export promotion schemes incentivize cross-docking terminal investments serving international e-commerce fulfillment. Developers navigate Haryana's distinct warehousing policy regime for fire suppression and structural certifications.
India E-Commerce Warehousing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automation intensity and client portfolio diversification. The market structures around three tiers: integrated third-party logistics providers with captive technology stacks, specialized last-mile adjacency operators, and legacy freight forwarders extending into fulfillment services. Consolidation pressures favor scale-driven capacity expansion and strategic partnerships over vertical integration.
Among integrated platform-anchored providers, Delhivery exemplifies multi-client fulfillment architecture, while Ekart Logistics occupies a position tied to parent ecosystem demand concentration. XpressBees represents specialized last-mile adjacency to warehousing nodes, competing via geographic density rather than automation scale.
| Leading Market Players |
|---|
| Delhivery |
| Ekart Logistics |
| XpressBees |
| Blue Dart Express |
| Mahindra Logistics |
| Transport Corporation of India |
| Allcargo Logistics |
| Eshopbox |
| WareIQ |
| Others |
Pricing and Supply Chain Analysis
Horizontal marketplace procurement teams concentrate buying power through outcome-based contracts tied to delivery speed guarantees. This buyer archetype dominance forces third-party logistics providers toward performance-tiered pricing structures across Maharashtra and Karnataka clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by automation intensity and throughput commitment. Premium tiers capture facilities with autonomous mobile robot density exceeding 50 units per center, while standard tiers serve conventional racked configurations in tier-2 cities. Price differentiation hinges on BIS structural safety certification tier and CEA electrical clearance compliance grade. Cost compression in the economy tier intensifies as legacy freight forwarders extend into fulfillment services with undifferentiated capacity. Grocery platforms exhibit highest price sensitivity due to perishable inventory carrying costs, whereas pharmaceutical verticals prioritize certification tiers over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for automated material handling equipment mandate multi-vendor qualification across Indian e-commerce warehousing. Equipment supply concentrates in Germany, Japan, and South Korea for vertical lift modules and shuttle systems. Steel racking systems and conveyor components draw from domestic mills and Chinese fabricators. Single-source vulnerability runs through specialized warehouse management system vendors maintaining concentrated relationships with third-party logistics providers. Distribution runs through project-based procurement channels where developers front-load PLI scheme subsidy capture during construction phases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India e-commerce warehousing represents a late-cycle quality story as platform procurement shifts toward automated throughput guarantees and BIS premium certification tiers.
For Market Incumbents: Anchor market position through captive technology stack deepening and multi-client fulfillment architecture expansion in Mumbai-Pune corridor. Defend against specialized last-mile adjacency competitors by accelerating autonomous mobile robot deployment density. Prioritize backward integration into warehouse management system development to reduce vendor concentration risk. For New Entrants and Emerging Players: Third-party logistics partnerships offer the most penetrable entry channel for mid-scale e-commerce platforms seeking shared infrastructure economics. Target Ahmedabad, Jaipur, and Lucknow white space with refrigerated storage capabilities for grocery platform demand. Pursue green building certification differentiation under evolving BIS fire suppression standards to command premium positioning. For Investors and Strategic Acquirers: Private equity firms with logistics infrastructure mandates are the most active acquirer in this space, consolidating regional operators with automation-ready land banks. Long-term viability centers on tier-2 city penetration depth and PLI scheme subsidy capture efficiency. Watch for inflection in state-level warehousing policy harmonization as signal for accelerated capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Material Handling Deployment | Autonomous mobile robot density separates premium-tier operators from commodity fulfillment providers in Maharashtra. |
| Multi-Client Fulfillment Architecture | Shared infrastructure models capture economies across diverse client portfolios while reducing per-unit costs. |
| Green Building Certification Program | BIS structural safety and fire suppression premium tiers create differentiation for developers commanding lease premiums. |
| Backward Integration into WMS Development | In-house software stacks reduce vendor concentration risk and enable seamless connectivity with automated equipment. |
| Tier-2 City Geographic Expansion | Ahmedabad, Jaipur, and Lucknow underpenetration offers white space for fulfillment center deployment near emerging consumer bases. |
Research Methodology
Multiple input streams — primary interviews with warehouse operators, platform procurement executives, and DPIIT policy administrators, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged third-party logistics development heads, automated equipment vendors, and state warehousing authority officials across Maharashtra, Karnataka, and Telangana. Secondary sources encompassed BIS certification databases, CEA electrical clearance filings, PLI scheme disbursement records, and state-level warehousing policy notifications.
Historical throughput capacity expansion patterns were cross-referenced against panel input from facility developers and equipment financiers. The analytical framework modeled segmentation dimensions including warehousing type, storage solution tier, inventory management methodology, and technology integration intensity across the projection horizon. CAGRs were derived from facility commissioning timelines, automation penetration curves, and platform fulfillment demand elasticity. Forecast inputs incorporated PLI scheme subsidy flow projections and state-level land assembly timeline variations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization pace and power infrastructure buildout delays. Forecasts reflect documented assumptions regarding subsidy continuity and automation cost curves. Deviation in BIS certification timeline compression or CEA clearance backlog would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Indonesia E-Commerce Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
China Online Trading Platform Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Retail E-Commerce Market
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
E-Commerce Apparel Market
E-Commerce Solutions
C2C E-Commerce Market
E-Commerce Solutions
North America Automotive E-Commerce Market
E-Commerce Solutions
Panama E-Commerce Market
E-Commerce Solutions
Latin America E-Commerce Logistics Market
E-Commerce Solutions
UK Ecommerce Market
E-Commerce Solutions
Resale E-Commerce Platform Market