
 US SMS Marketing Market | 2026-2036
US SMS Marketing Market Size, Share, and Industry Trends Forecast 2026-2036
US SMS Marketing Market Intelligence
California's technology corridor is fragmenting as new platform entrants challenge incumbent infrastructure. Twilio Inc. leverages its programmable communications cloud to sustain developer-first distribution across enterprise accounts. Sinch AB anchors high-volume A2P routing through direct carrier relationships. Infobip Ltd. competes on omnichannel convergence, embedding SMS alongside WhatsApp and voice in unified stacks.
US SMS Marketing denotes the practice of delivering permission-based text messages to mobile subscribers for commercial purposes, typically via short codes or long codes using SMPP or REST API protocols with throughput rates exceeding 100 messages per second. The primary purpose centers on direct-response customer communication, yielding open rates substantially above email benchmarks. Promotional Messaging generates the largest revenue pool among service types, though Transactional Messaging commands superior per-message pricing due to delivery reliability requirements. Retail and E-commerce verticals absorb the majority of platform spend, while API Integration deployments outpace web-based alternatives among technically sophisticated buyers seeking CRM connectivity.
The FCC enforces Telephone Consumer Protection Act provisions that mandate express written consent before commercial SMS transmission, with violations triggering statutory damages that reshape vendor liability structures. The CTIA publishes messaging guidelines that carriers enforce through downstream contract terms, effectively governing throughput allocation and content filtering. Stakeholders must monitor evolving state-level privacy legislation in California and Virginia that extends beyond federal minimums, while evaluating whether platform investments accommodate emerging rich communication services standards.
Market Dynamics
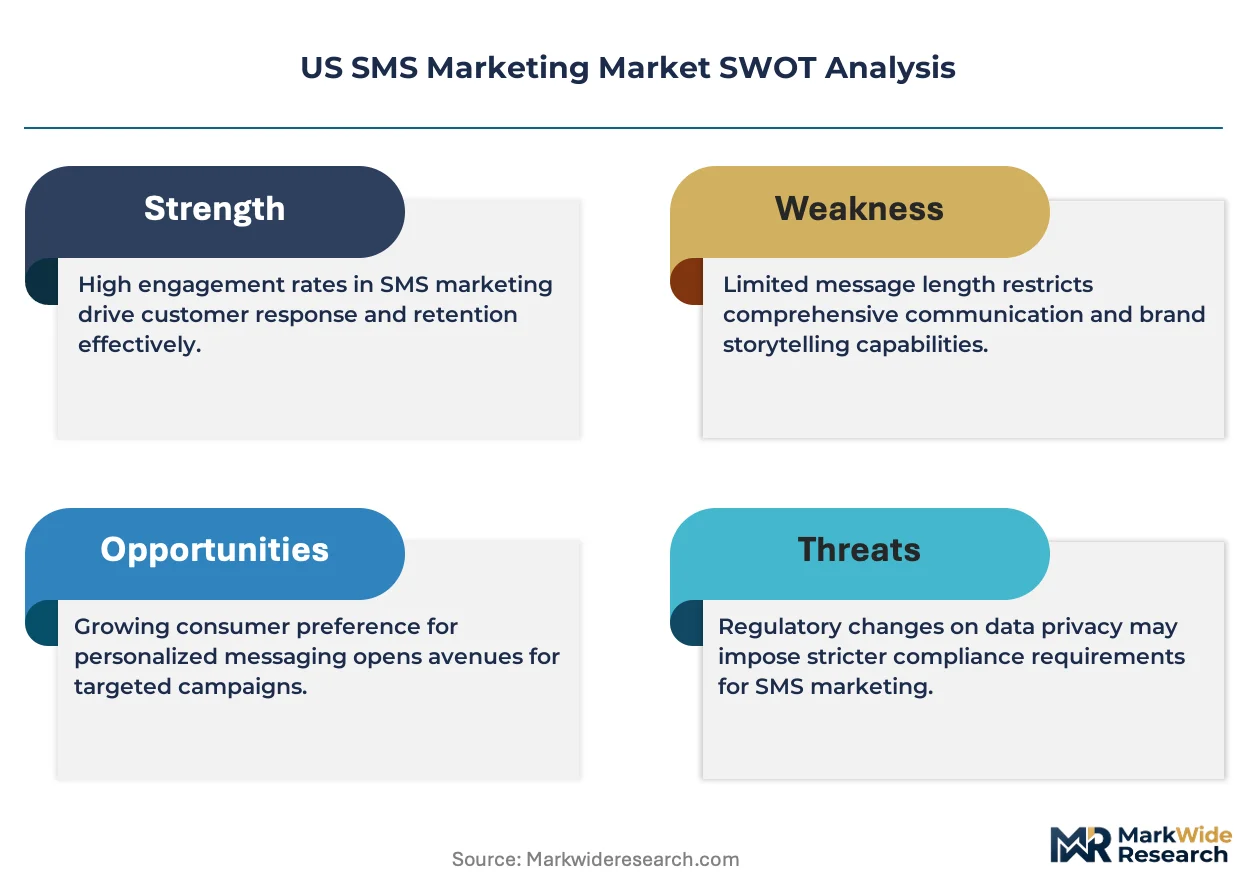
FCC TCPA enforcement is compressing vendor margins while forcing platform consolidation around compliant consent-management infrastructure. Carriers now audit downstream messaging partners quarterly, elevating operational costs for mid-tier providers.
Growth Catalysts
- California Consumer Privacy Act extensions:First-party data collection via SMS opt-ins gains strategic value as third-party cookies deprecate. Retailers in Los Angeles and San Francisco accelerate SMS list-building investments.
- Rich Communication Services (RCS) protocol adoption:Google's carrier partnerships enable branded interactive messaging with embedded carousels and payments. E-commerce deployers in Texas metropolitan corridors pilot RCS for abandoned-cart recovery.
- Mid-market B2C brand concentration:Subscription-box and direct-to-consumer apparel companies in Austin and Miami expand dedicated SMS marketing headcount. These firms prioritize API-integrated platforms over standalone campaign tools.
Market Restraints
- Carrier throughput allocation scarcity:Verizon, AT&T, and T-Mobile impose dynamic rate limits during peak retail periods. High-volume senders face message queuing delays that degrade time-sensitive campaign performance.
- Short code provisioning bottlenecks:CTIA-administered short code approvals stretch to 12-16 weeks. New market entrants cannot match incumbents' existing code inventories for immediate campaign deployment.
- Litigation exposure under TCPA private right of action:Class-action settlements exceed platform annual recurring revenue for non-compliant vendors. Insurance carriers now exclude SMS marketing liability from standard technology E&O policies.
Strategic Opportunities
- Texas metropolitan corridor expansion:Dallas-Fort Worth and Houston retail density remains underpenetrated relative to California. Platform providers establishing local sales presence capture mid-market accounts before saturation.
- Conversational AI-SMS hybrid workflows:Natural language processing enables two-way customer service automation within existing messaging threads. Telecom and utility verticals pilot these integrations for billing inquiries.
- State-level biometric privacy laws:Illinois BIPA and Texas CUBI create compliant messaging demand from healthcare and financial services. Vendors with built-in consent documentation capture regulated-sector contracts.
Industry Challenges
- Legacy CRM integration complexity:Enterprise Salesforce and Microsoft Dynamics instances require custom middleware development. Implementation timelines stretch 6-9 months, delaying platform revenue recognition.
- Deliverability engineering talent scarcity:SMPP protocol optimization and carrier relationship management skills concentrate among tenured engineers. Compensation inflation exceeds 25% annually for experienced routing specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US SMS Marketing Market |
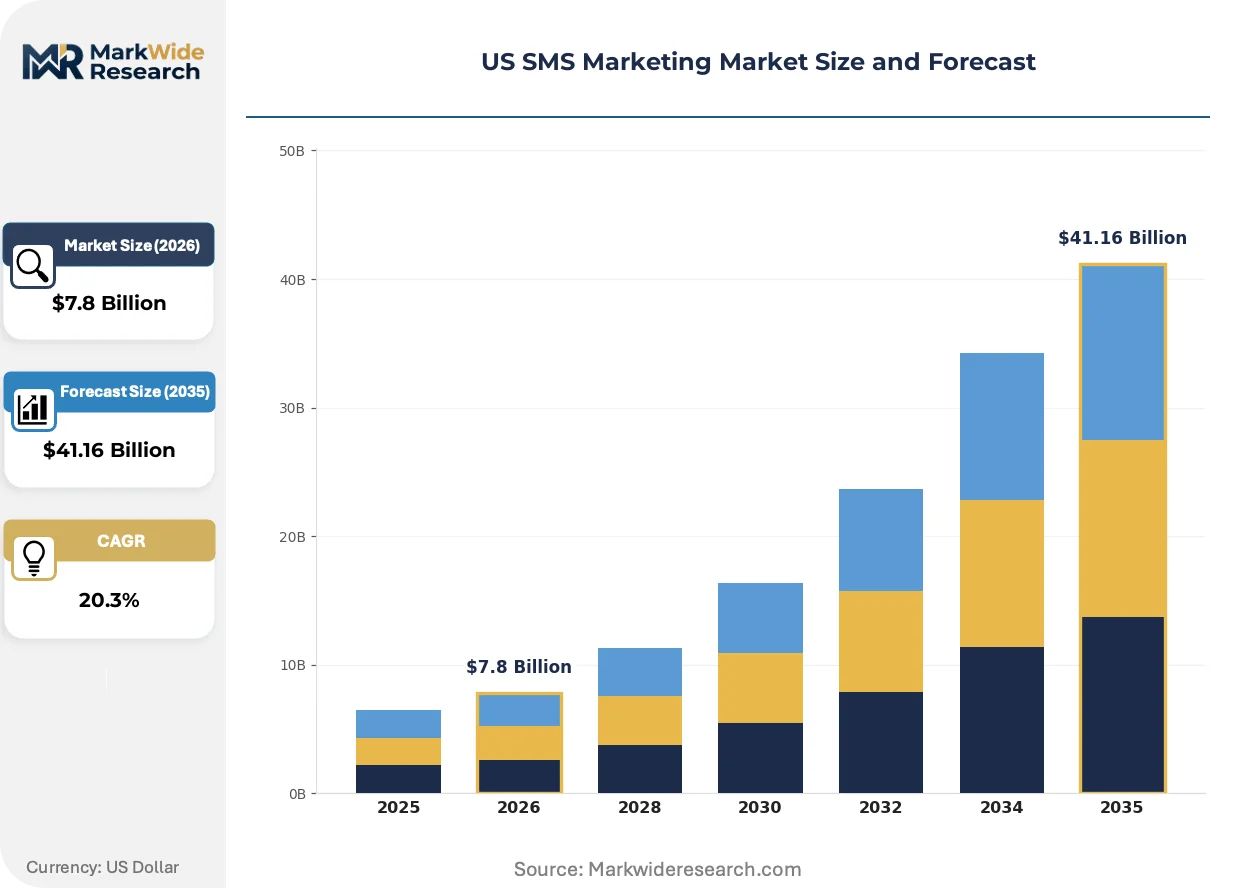
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $41.16 Billion |
| CAGR (2026 – 2036) | 20.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Promotional Messaging, Transactional Messaging, Customer Engagement, Alert Notifications Industry Vertical: Retail, E-commerce, Healthcare, Travel Customer Type: B2C, B2B, eCommerce, Non-Profit Messaging Platform: Web-based, API Integration, Mobile App, Third-party Tools |
| Companies Covered | Twilio Inc., Sinch AB, Infobip Ltd., Vonage Holdings Corp., EZ Texting, Klaviyo, SimpleTexting, SlickText, Textedly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US SMS Marketing Market Strategic Shifts & Innovations
Platform architecture is pivoting from campaign management to real-time data orchestration. Vendors now compete on latency and identity resolution rather than template libraries alone.
Application-to-Person (A2P) 10-digit long code (10DLC) registration systems are rendering obsolete shared short code deployments. Major retailers and quick-service restaurant chains completed 10DLC migrations during 2023-2024. The shift eliminates cross-brand contamination risks while enabling individualized throughput tiers based on trust scores.
FCC Chairwoman Jessica Rosenworcel's proposed robotext rules tighten opt-in documentation requirements for commercial SMS. The rulemaking would mandate single-purpose consent with explicit service identification. High-frequency senders in promotional messaging categories face compliance re-architecture costs while transactional messaging providers gain relative advantage.
Buyer procurement patterns favor outcome-based platform pricing tied to attributed revenue rather than message volume commitments. Mid-market e-commerce brands in California negotiate revenue-share arrangements replacing per-SMS fees. This compression pressures pure-play SMS vendors without adjacent attribution analytics capabilities.
US SMS Marketing Market Segmentation
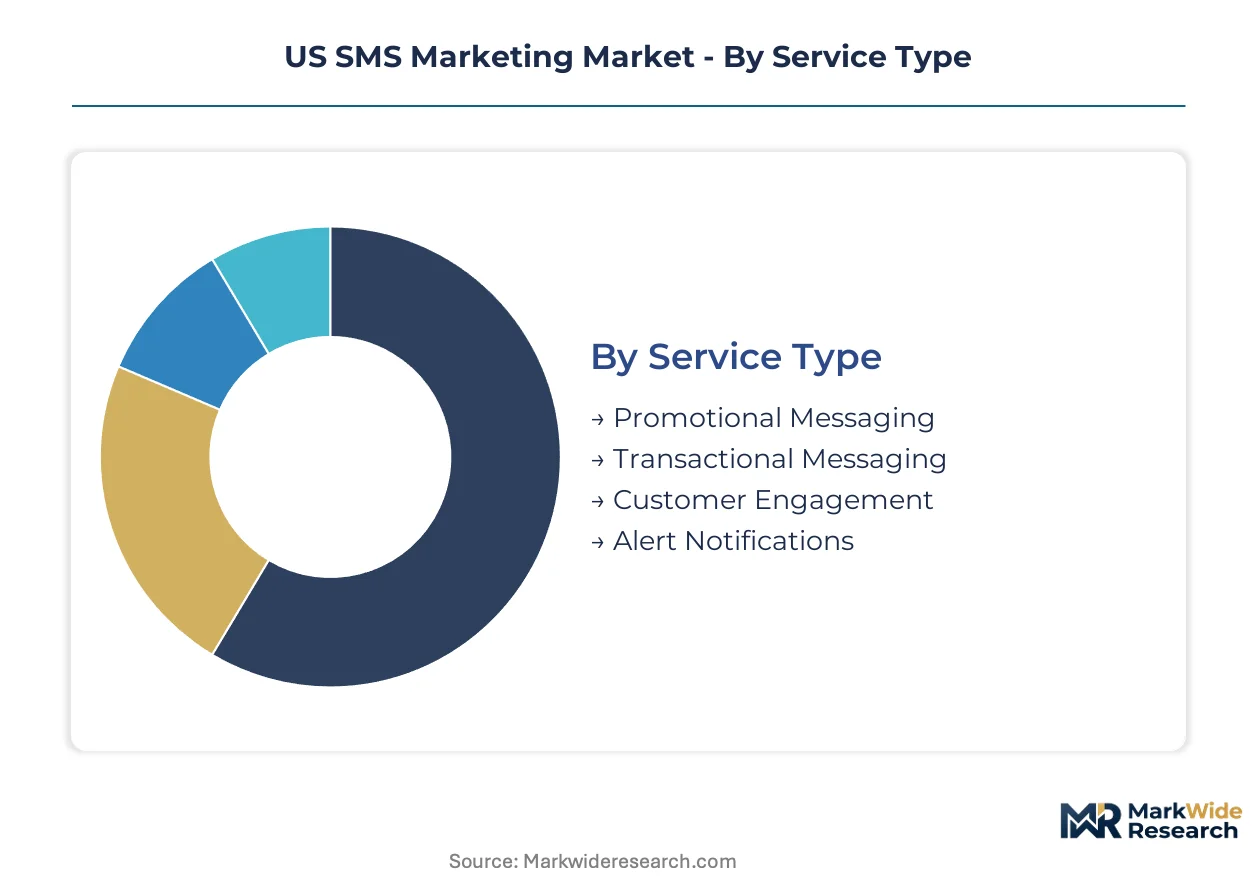
SMS marketing segmentation reveals how platform capabilities align with distinct operational requirements. Service type and customer sophistication determine API versus web-based deployment choices. Vertical-specific compliance needs further fragment vendor positioning across regulated and promotional use cases.
Service Type:
Cost tier differentiation separates high-volume promotional deployments from premium-priced transactional infrastructure.
- Promotional Messaging:Bulk broadcast campaigns deliver time-sensitive offers to opted-in subscriber lists. Retailers in Los Angeles and San Francisco deploy these for flash sales, though carrier rate limits constrain peak-period throughput.
- Transactional Messaging:Triggered notifications for order confirmations and shipping updates command superior per-message pricing due to delivery reliability requirements. E-commerce platforms prioritize these for abandoned-cart recovery workflows.
- Customer Engagement:Two-way conversational threads support loyalty program interactions and feedback collection.
- Alert Notifications:Critical service updates for banking and healthcare require hardened delivery SLAs.
Transactional Messaging holds installed capacity. Promotional Messaging is rotating up the share rankings.
Industry Vertical:
Application concentration varies sharply between regulated healthcare environments and high-velocity retail operations.
- Retail:In-store pickup notifications and loyalty point alerts drive repeat purchase frequency. Quick-service restaurant chains in Texas metropolitan corridors pilot location-triggered messaging.
- E-commerce:Subscription-box companies in Austin and Miami build dedicated SMS marketing teams. These firms demand API-integrated platforms with real-time inventory connectivity.
- Healthcare:Appointment reminders and prescription refill alerts face HIPAA consent documentation requirements.
- Travel:Flight disruption notifications and mobile boarding passes require carrier-grade delivery infrastructure.
E-commerce holds installed capacity. Healthcare is rotating up the share rankings.
Customer Type:
Volume scale distinguishes enterprise B2C deployments from constrained B2B procurement patterns.
- B2C:Direct-to-consumer brands generate the highest message volumes through promotional campaign cadences. California Consumer Privacy Act compliance elevates first-party SMS list value as third-party cookies deprecate.
- eCommerce:Pure-play digital retailers integrate SMS with attribution analytics for revenue-share platform pricing negotiations.
- B2B:Account-based notification systems serve lower message volumes with higher per-contact value.
- Non-Profit:Donation appeals and event mobilization operate under distinct FCC consent exemptions.
B2C holds installed capacity. eCommerce is rotating up the share rankings.
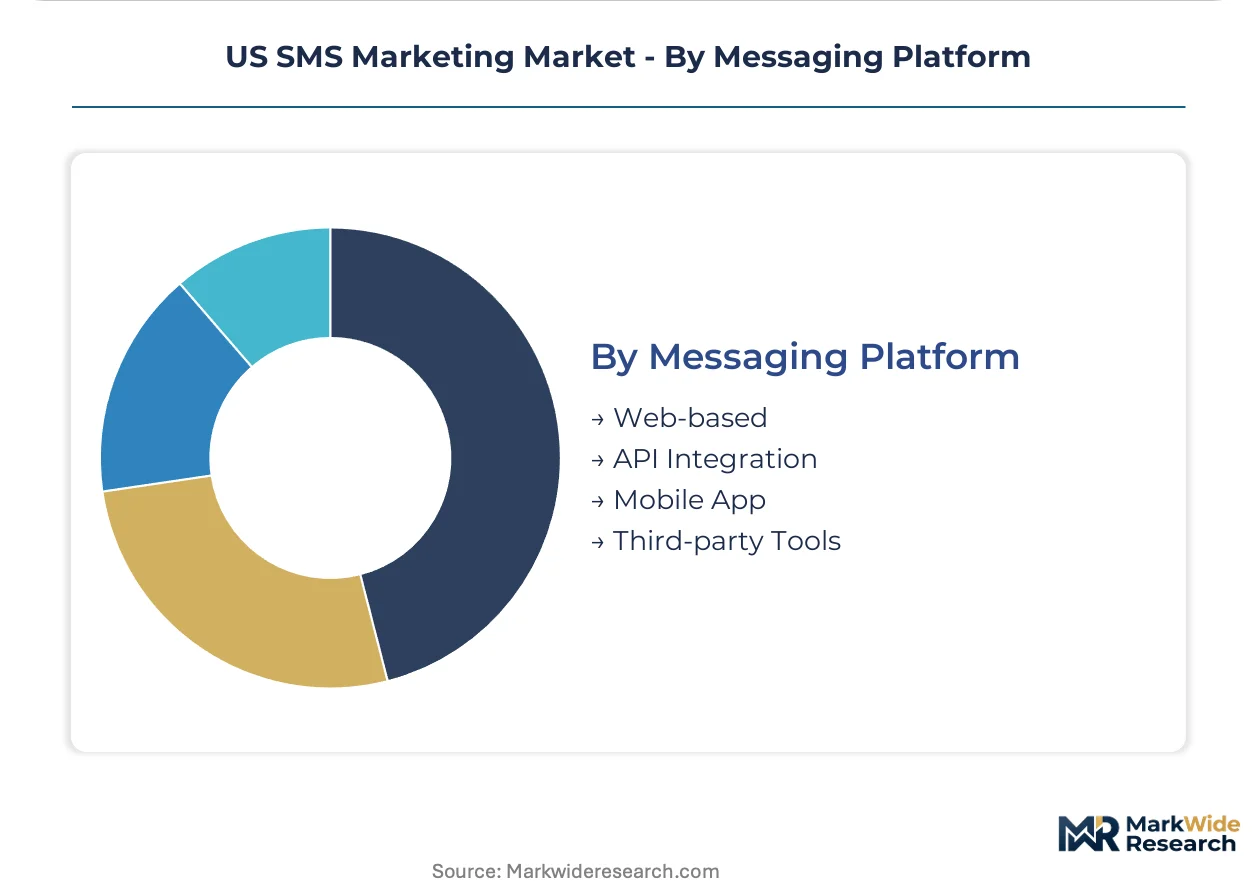
Messaging Platform:
Technical maturity determines deployment architecture selection across buyer segments.
- API Integration:REST and SMPP protocol connections enable CRM synchronization and automated workflow triggers. Mid-market brands with Salesforce instances prioritize these despite 6-9 month implementation timelines.
- Web-based:Browser-accessible campaign builders serve marketing teams without engineering resources.
- Mobile App:Native iOS and Android SDKs support in-app messaging channel consolidation.
- Third-party Tools:Pre-built connectors for Shopify and WooCommerce accelerate time-to-campaign for smaller merchants.
API Integration holds installed capacity. Third-party Tools is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Texas metropolitan corridors consume SMS marketing infrastructure differently from other US regions, with West Coast technology clusters prioritizing API-integrated platforms while Southern retail hubs favor high-volume promotional tooling.
California
Los Angeles and San Francisco anchor first-party data collection investments as retailers accelerate SMS list-building ahead of third-party cookie deprecation. The California Consumer Privacy Act mandates explicit opt-in documentation that elevates compliant platform valuations. Silicon Valley technology firms and San Diego direct-to-consumer brands drive API Integration deployment preferences.
Texas
Dallas-Fort Worth and Houston retail density remains underpenetrated relative to coastal markets, creating acquisition opportunities for platform providers establishing local sales presence. State-level biometric privacy laws under Texas CUBI generate compliant messaging demand from healthcare and financial services verticals. Austin subscription-box companies expand dedicated SMS marketing headcount with real-time inventory connectivity requirements.
New York Metro
Financial services and luxury retail concentration in Manhattan drives transactional messaging infrastructure spend for order confirmations and fraud alerts. New York's Department of Financial Services cybersecurity regulations extend to customer communication audit trails. Brooklyn and Queens direct-to-consumer brands negotiate revenue-share platform pricing tied to attributed revenue.
Florida
Miami's direct-to-consumer apparel and wellness verticals prioritize conversational AI-SMS hybrid workflows for customer service automation. The state's tourism-dependent hospitality sector deploys location-triggered messaging for guest engagement. Orlando quick-service restaurant chains pilot 10DLC migrations to eliminate cross-brand contamination risks.
Illinois
Chicago's healthcare and insurance concentration generates demand for HIPAA-compliant appointment reminder and billing notification systems. Illinois BIPA biometric privacy requirements create specialized consent documentation needs for patient messaging platforms. The city's manufacturing and logistics sectors adopt alert notification infrastructure for supply chain disruption communications.
US SMS Marketing Market Key Industry Players
Capability concentration sits with developer-first platform architects; scale advantage sits with direct carrier routing specialists. The market structures around three tiers: programmable communications clouds, high-volume A2P aggregators, and omnichannel convergence platforms. Dominant competitive moves include vertical integration into consent-management infrastructure and geographic sales expansion into underpenetrated metropolitan corridors.
Within the developer-first tier, Twilio Inc. exemplifies programmable communications cloud positioning through REST API distribution. Sinch AB and Infobip Ltd. occupy positions across the high-volume routing and omnichannel convergence archetypes respectively. These three entities anchor competitive dynamics as carriers tighten downstream audit requirements and buyers shift toward outcome-based pricing models.
| Leading Market Players |
|---|
| Twilio Inc. |
| Sinch AB |
| Infobip Ltd. |
| Vonage Holdings Corp. |
| EZ Texting |
| Klaviyo |
| SimpleTexting |
| SlickText |
| Textedly |
| Others |
Cost & Logistics Intelligence
Carrier throughput allocation scarcity compresses vendor margins while determining both API tier spreads and supply chain consolidation toward direct carrier relationships. FCC TCPA enforcement elevates compliance infrastructure costs that stratify platform pricing across consent-management sophistication levels.
Pricing Analysis
California metropolitan corridors command 15-20% platform pricing premiums over Texas corridors due to CCPA documentation requirements and developer talent concentration. SaaS-tiered subscription models dominate, with price differentiation hinging on API throughput tiers and HIPAA-grade certification bundles. Pricing pressure stems from outcome-based buyer negotiations tied to attributed revenue rather than per-message fees. Mid-market B2C brands in Austin and Miami exhibit highest price sensitivity; enterprise healthcare contracts in Chicago show lowest sensitivity due to compliance-driven procurement.
Supply Chain Analysis
Extended payment terms from Verizon, AT&T, and T-Mobile constrain working capital for downstream platform providers. Supply concentrates in US carrier infrastructure, Indian engineering centers, and Irish data residency hubs for EU-facing deployments. Raw material dependencies include SMPP protocol licenses, carrier interconnect agreements, and cloud compute instances. Single-source vulnerability sits with Tier 1 carrier direct routing relationships. Distribution runs through API marketplaces, Salesforce AppExchange, and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RCS protocol adoption and FCC robotext rulemaking constitute a dual inflection reshaping competitive viability and compliance architecture requirements.
For Market Incumbents: Entrench consent-management infrastructure as a moat against TCPA litigation exposure. Acquire specialized HIPAA-compliant messaging stacks to capture healthcare vertical contracts. Defensive API throughput guarantees with Tier 1 carriers lock out mid-tier challengers during peak retail periods. For New Entrants and Emerging Players: Texas metropolitan corridor underpenetration offers white-space acquisition before platform saturation. Target Dallas-Fort Worth quick-service restaurant chains with 10DLC migration services. Deploy Shopify-native third-party connectors to bypass 6-9 month Salesforce implementation timelines. For Investors and Strategic Acquirers: FCC Chairwoman Rosenworcel's proposed robotext rules reshape the acquisition landscape toward compliant consent-documentation platforms. Five-to-ten year viability favors vendors with omnichannel convergence capabilities spanning SMS, RCS, and WhatsApp. Target platforms with embedded attribution analytics for outcome-based pricing resilience. Monitor CTIA short code approval velocity as inflection indicator for incumbent inventory value.| Strategic Initiative | Industry Significance |
|---|---|
| 10DLC Migration Services | Eliminates cross-brand contamination risks while enabling individualized carrier trust scores. |
| Consent-Management Infrastructure | Captures healthcare and financial services contracts under BIPA and Texas CUBI requirements. |
| RCS Protocol Integration | Google carrier partnerships enable branded interactive messaging with embedded payment flows. |
| API-First Platform Architecture | Serves Austin subscription-box companies demanding real-time inventory connectivity. |
| Outcome-Based Pricing Models | Aligns platform revenue with attributed e-commerce revenue in California revenue-share negotiations. |
Research Approach
Cross-validation between FCC enforcement action databases and CTIA carrier guideline releases anchors the qualitative findings. Primary interviews with SMS platform CTOs, carrier wholesale account managers, retail marketing operations directors, and healthcare compliance officers combine with secondary validation against SEC 10-K filings, FCC docket records, and carrier transparency reports. Bottom-up deployment estimates triangulate against top-down platform revenue aggregation.
Calibration against historical A2P volume growth and carrier infrastructure capex disclosures shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, industry vertical, customer sophistication tier, and messaging platform architecture. CAGRs derive from carrier throughput expansion trajectories and RCS protocol adoption curves. Inputs include short code provisioning wait times and 10DLC registration velocity.
Macroeconomic conditions sit as an overlay; deviation in retail discretionary spending or carrier capital allocation would shift the trajectory. Forecasts reflect documented assumptions around TCPA enforcement intensity and state-level privacy law propagation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Australia E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Logistics Market
E-Commerce Solutions
North America Dropshipping Market
E-Commerce Solutions
Netherlands E-Commerce Market
E-Commerce Solutions
Agricultural E-Commerce Market
E-Commerce Solutions
Bahrain E-Commerce Market
E-Commerce Solutions
South Africa E-Commerce Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
Latvia E-Commerce Market
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
Singapore E-Commerce Market
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market