
 UAE Q-Commerce Industry Market | 2026-2036
UAE Q-Commerce Industry Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Q-Commerce Industry Market Insights
The gap between premium subscription models and pay-per-order commodity fulfillment is shifting as platform economics diverge. Talabat leverages its integrated restaurant and grocery ecosystem to sustain customer lock-in across multiple service verticals. Noon anchors its position through captive logistics infrastructure and direct inventory ownership in key Emirates. Careem differentiates by embedding q-commerce within its super-app architecture, cross-selling mobility and delivery services.
Q-commerce in the UAE denotes digitally orchestrated fulfillment of consumer goods within sub-60-minute windows through distributed micro-fulfillment centers, algorithmic dispatch engines, and gig-coordinated last-mile fleets. Mobile apps and automated dispatching systems coordinate real-time inventory visibility with dynamic rider allocation to minimize delivery latency. Food delivery and grocery delivery segments dominate transaction volume, while pharmaceuticals represents a margin-accretive niche constrained by CDSCO-aligned cold-chain requirements and prescription verification protocols. Subscription-based delivery models capture the highest lifetime value per user, whereas third-party logistics partnerships enable rapid geographic expansion without fixed asset commitment.
MOHAP governs pharmaceutical distribution licensing and cold-chain compliance for health-related q-commerce, while the UAE's consumer protection frameworks mandate transparent pricing and refund protocols across digital platforms. SAMR-aligned commercial regulations enforce fair competition standards that prevent predatory platform pricing in concentrated urban markets. Stakeholders must monitor evolving labor classification rules under Nafis and emerging data localization requirements that could reshape cloud infrastructure deployment for dispatch algorithms.
Market Dynamics
Dark store networks are consolidating around Dubai's high-density residential corridors, compressing delivery radii and forcing asset-light platforms to choose between captive fulfillment infrastructure or margin erosion.
Growth Catalysts
- Central bank digital payment frameworks:The UAE's instant payment rails reduce transaction friction for sub-60-minute orders. Settlement velocity improves cash conversion cycles for micro-fulfillment operators.
- Nafis citizen employment program:Government-subsidized Emirati hiring reshapes gig workforce economics. Platforms gain access to stable labor pools with lower churn than traditional contractor models.
- Pharmaceutical cold-chain protocols:CDSCO-aligned standards for prescription verification and temperature-controlled logistics open margin-accretive health categories. Specialized fulfillment commands premium pricing.
Market Restraints
- Real estate concentration in Business Bay and Jumeirah:Prime dark store locations face escalating commercial rents. New entrants confront barrier-to-entry costs that favor incumbents with existing leaseholds.
- Gig worker classification uncertainty:Evolving labor rules under Nafis create compliance exposure. Platforms risk cost structure disruption if contractor models face reclassification mandates.
- Third-party logistics dependency:Asset-light expansion relies on external fleet capacity. Rider availability bottlenecks during peak demand windows constrain service level guarantees.
Strategic Opportunities
- Abu Dhabi corridor expansion:Lower dark store density creates first-mover advantage for fulfillment network buildout. Residential clusters around Al Reem Island and Saadiyat remain underpenetrated.
- Subscription model penetration:Monthly delivery memberships lock in recurring revenue and reduce customer acquisition costs. Young professional segments show willingness to prepay for convenience bundling.
- Super-app service convergence:Cross-selling mobility, delivery, and financial services within unified interfaces reduces per-service acquisition spend. Careem's architecture demonstrates path to multi-vertical retention.
Industry Challenges
- Algorithmic dispatch talent scarcity:Machine learning engineers with real-time logistics optimization experience command premium compensation. Local universities lack specialized supply chain AI curricula.
- Data localization compliance:Emerging requirements for domestic cloud storage of customer and transaction data force infrastructure reconfiguration. Dispatch latency may degrade if edge computing cannot satisfy sovereignty rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Q-Commerce Industry Market |
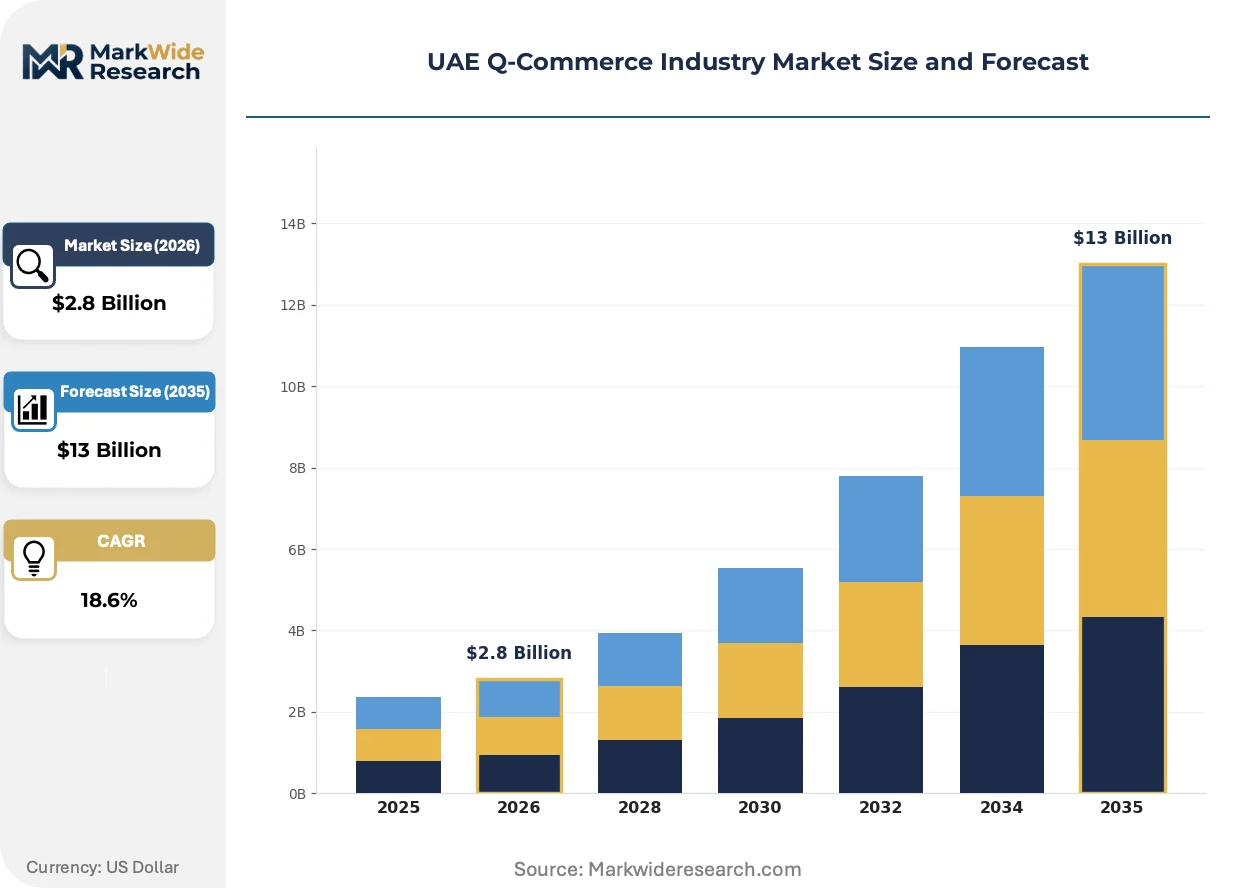
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food Delivery, Grocery Delivery, Pharmaceuticals, Personal Care Customer Type: Individual Consumers, Businesses, Restaurants, Retail Chains Technology: Mobile Apps, Web Platforms, Automated Dispatching, GPS Tracking Delivery Model: In-House Delivery, Third-Party Logistics, Partner Networks, Subscription Services |
| Companies Covered | Talabat, Noon, Careem, InstaShop, Deliveroo, Amazon, Kibsons, El Grocer, Nana, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Q-Commerce Industry Market Trends and Innovations
Automated micro-fulfillment and predictive inventory positioning are compressing the gap between order placement and doorstep arrival, reshaping capital deployment across the Emirates.
AI-powered demand forecasting is electrifying inventory placement decisions in Dubai's dark store networks. Talabat and Noon deploy machine learning models that predict neighborhood-level consumption patterns 48 hours forward. This capability is electrifying working capital efficiency by reducing safety stock requirements 30-40% while maintaining sub-60-minute service levels.
MOHAP's pharmaceutical distribution licensing framework is tightening cold-chain verification requirements for health-related q-commerce. Temperature logging and prescription authentication protocols now mandate blockchain-traceable documentation. Specialist platforms serving chronic medication segments face the steepest compliance investment curves.
Young professionals in Dubai and Abu Dhabi are consolidating convenience spending into bundled subscription tiers. Monthly memberships covering grocery, restaurant, and retail delivery displace pay-per-order behavior. This shift concentrates most visibly in Marina and Downtown Dubai, where density supports frequent utilization economics.
UAE Q-Commerce Industry Market Segmentation
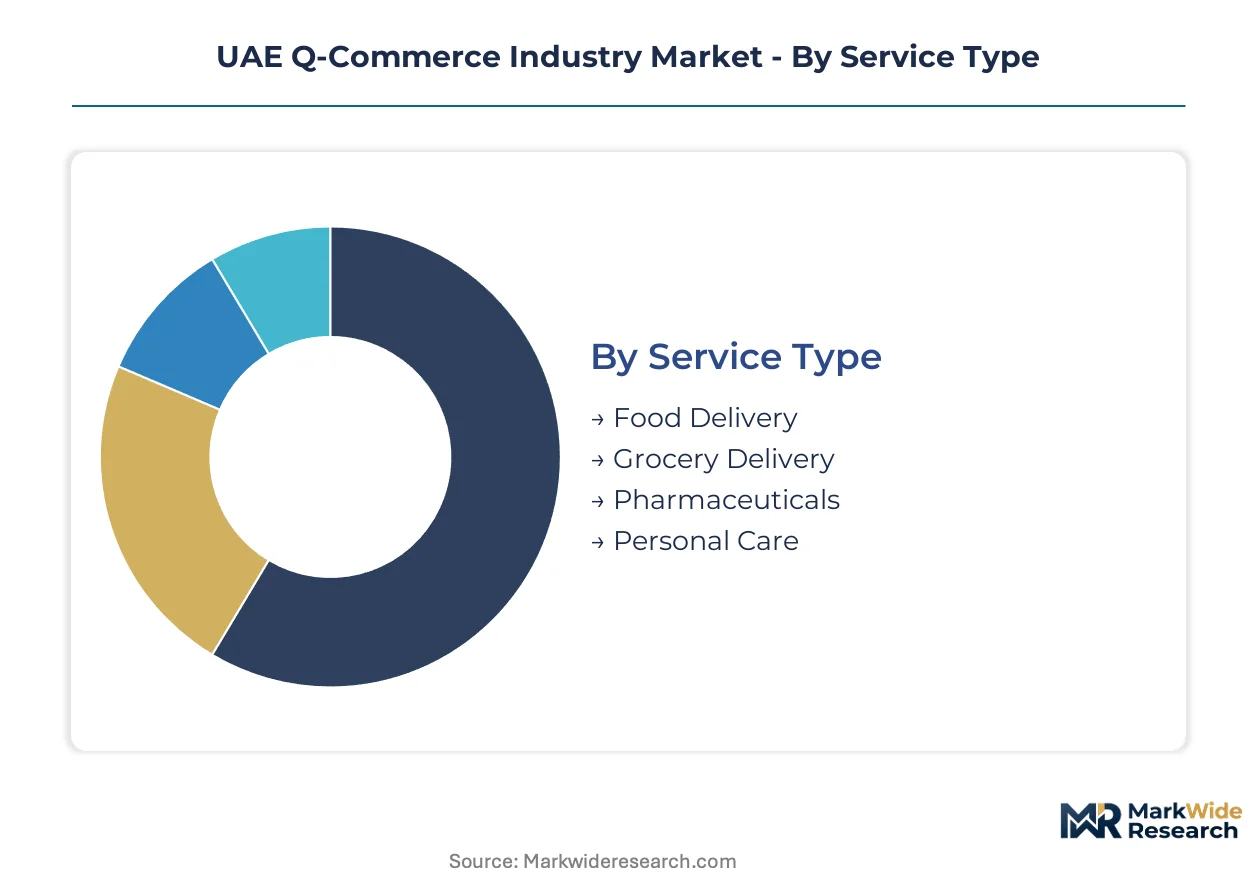
Segmentation in UAE q-commerce reveals how fulfillment economics diverge across service intensity, customer relationship depth, and infrastructure ownership. Each dimension exposes distinct margin structures and capital requirements that shape platform strategy in Dubai and Abu Dhabi's concentrated corridors.
Service Type:
Buyer decisions here pivot on urgency frequency and basket composition, with convenience thresholds varying sharply across consumption occasions.
- Food Delivery:Restaurant-prepared meals dispatched through algorithmic rider allocation dominate transaction volume. Demand clusters around Business Bay and Marina office districts during lunch windows, where young professionals prioritize speed over price elasticity.
- Grocery Delivery:Dark store networks stock ambient and fresh categories for sub-60-minute fulfillment. Jumeirah residential density supports the unit economics, though cold-chain SKUs compress margins relative to ambient staples.
- Pharmaceuticals:MOHAP-licensed distribution with prescription verification and temperature logging. Chronic medication schedules create recurring demand, but CDSCO-aligned compliance costs favor specialized platforms over generalist expansion.
- Personal Care:Beauty and hygiene SKUs with lower velocity than grocery. Impulse-driven purchases concentrate in evening delivery windows, bundling with food orders to amortize last-mile costs.
Food delivery leads on scale; pharmaceuticals leads on momentum.
Customer Type:
Account concentration and order predictability separate segments, with contractual relationships commanding superior lifetime value economics.
- Individual Consumers:Mobile-first users purchasing through subscription tiers or pay-per-order models. Marina and Downtown Dubai households show highest membership penetration, consolidating convenience spending across verticals.
- Businesses:Corporate catering and office supply procurement with scheduled delivery windows. Al Reem Island commercial clusters generate predictable midday volume that stabilizes fleet utilization.
- Restaurants:Kitchen operators dependent on platform demand aggregation. Commission structures and promotional spend determine profitability, with independent outlets more price-sensitive than chain affiliates.
- Retail Chains:Established grocers and pharmacies leveraging platform infrastructure for digital reach. Inventory ownership and brand recognition reduce customer acquisition costs versus pure-play dark stores.
Individual consumers anchor volume concentration; businesses offer the steepest expansion trajectory.
Technology:
Interface choice and operational automation determine fulfillment latency and labor substitution potential across the Emirates.
- Mobile Apps:Native iOS and Android interfaces capturing 90%+ of order origination. Push notification timing and personalization engines drive conversion rates in dense urban corridors.
- Web Platforms:Browser-based ordering for corporate procurement and older demographics. Lower development overhead but declining share as smartphone penetration saturates.
- Automated Dispatching:Real-time rider allocation algorithms minimizing delivery windows. Machine learning models trained on Dubai traffic patterns reduce estimated arrival variance.
- GPS Tracking:Location visibility for customers and fleet managers. Integration with UAE road network data enables dynamic route adjustment during congestion events.
Mobile apps dominate current transaction flow; automated dispatching is climbing the fastest as competitive differentiation.
Delivery Model:
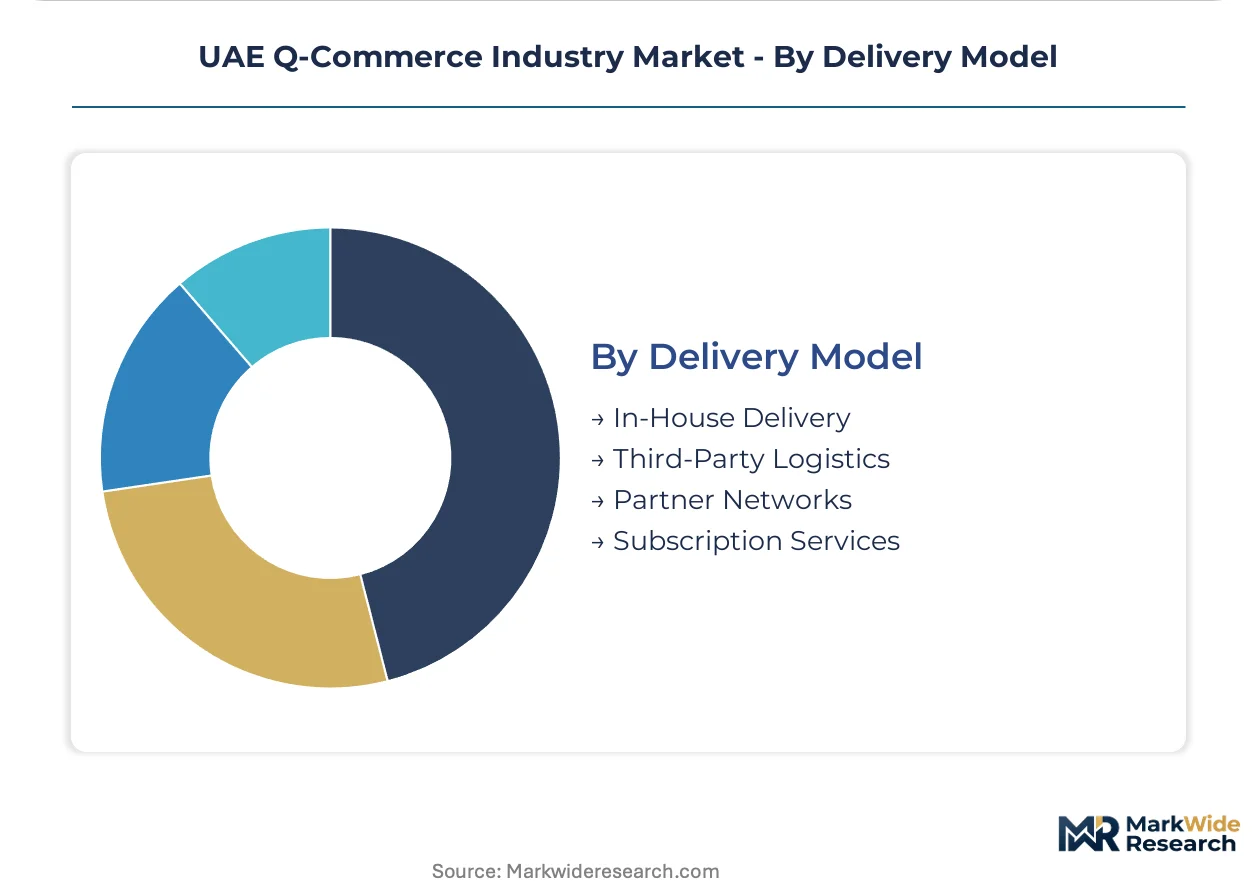
Asset ownership versus partnership structures define capital efficiency and service level control in geographically concentrated markets.
- In-House Delivery:Captive rider fleets with branded uniforms and equipment. Noon deploys this model for inventory-owning operations, securing capacity during peak windows.
- Third-Party Logistics:External fleet contracts enabling rapid geographic expansion. Careem leverages partner networks to extend coverage without fixed cost commitment.
- Partner Networks:Hybrid arrangements with independent contractors and small fleet operators. Nafis program subsidies improve Emirati participation rates relative to pure gig models.
- Subscription Services:Monthly delivery memberships locking in recurring revenue. Young professional segments in Abu Dhabi and Dubai show willingness to prepay for unlimited delivery bundling.
In-house delivery commands service quality leadership; subscription services are gaining share fastest as customer acquisition costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai and Abu Dhabi concentrate the Emirates' q-commerce infrastructure, while Sharjah and the Northern Emirates present divergent density and regulatory conditions for platform expansion.
Dubai
Business Bay and Marina office clusters generate concentrated midday food delivery demand from young professionals. The central bank's instant payment rails reduce transaction friction for sub-60-minute orders. Dark store networks cluster around Jumeirah residential corridors, compressing delivery radii through algorithmic inventory positioning.
Abu Dhabi
Al Reem Island and Saadiyat residential clusters remain underpenetrated relative to Dubai's density. Nafis citizen employment program subsidies reshape gig workforce economics with lower churn than traditional contractor models. Corporate catering demand from commercial districts stabilizes fleet utilization during predictable midday windows.
Sharjah
Lower commercial rents attract third-party logistics providers seeking cost-efficient fulfillment nodes. MOHAP pharmaceutical distribution licensing governs cold-chain compliance for health-related categories. Industrial zones near the Dubai border enable cross-emirate coverage without captive asset deployment.
Northern Emirates
Ajman and Ras Al Khaimah present sparse dark store coverage and extended delivery windows. SAMR-aligned commercial regulations enforce fair competition standards preventing predatory platform pricing. Emerging residential developments along E311 corridor create greenfield network buildout opportunities for first movers.
UAE Q-Commerce Industry Market Competitive Landscape
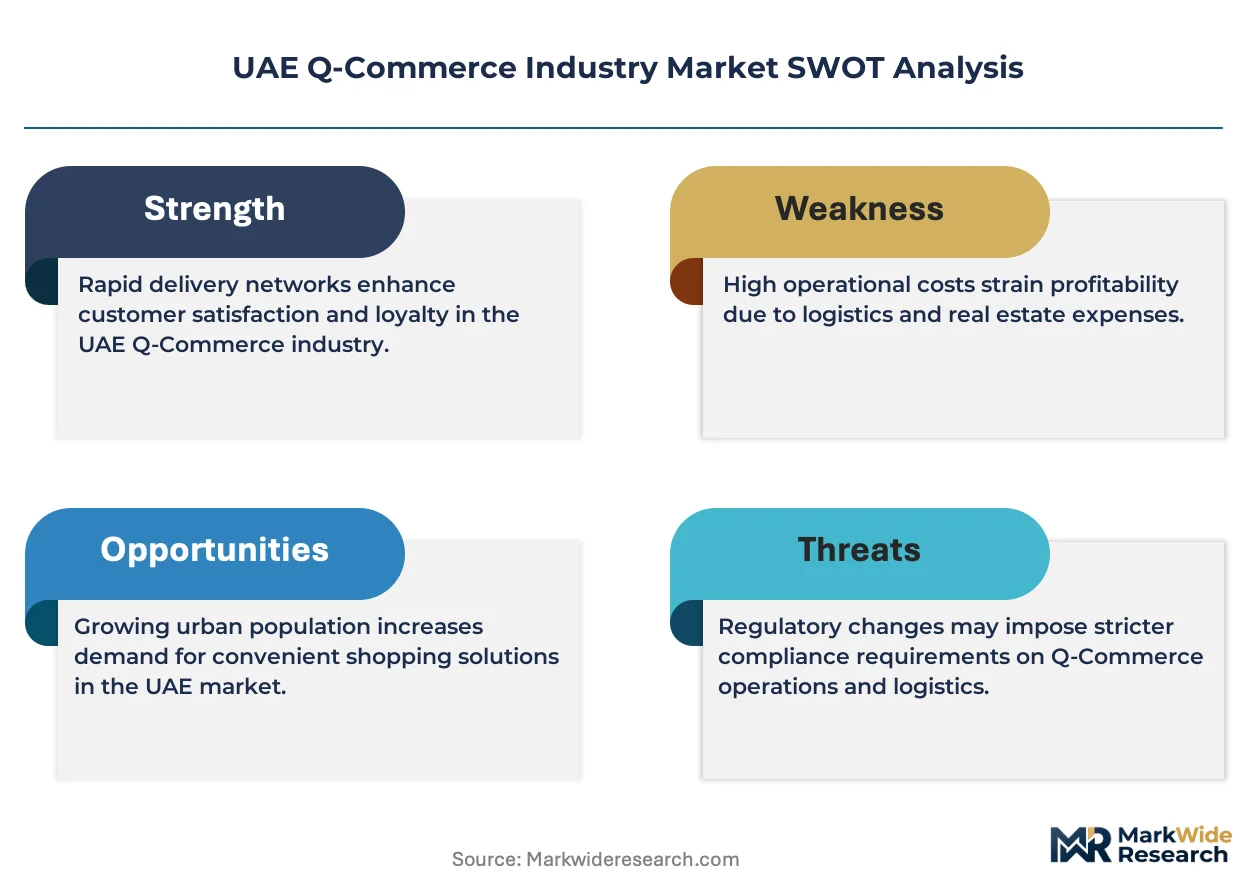
Top-tier vendors anchor integrated super-app ecosystems, while mid-tier specialists concentrate on single-vertical dominance or geographic niche capture. The competitive structure stratifies across inventory-owning operators, platform aggregators, and logistics-native entrants. Three archetypes define positioning: captive infrastructure builders, asset-light marketplace orchestrators, and mobility-rooted service bundlers. Consolidation pressure favors M&A activity targeting dark store networks and algorithmic dispatch capabilities.
Within the integrated ecosystem tier, Talabat and Noon exemplify divergent capital deployment strategies—one leveraging restaurant-grocery cross-selling, the other anchoring through direct inventory ownership. Careem occupies a position as the mobility-rooted bundler, embedding q-commerce within super-app architecture. These three entities represent the dominant competitive anchors shaping platform economics across Dubai and Abu Dhabi corridors.
| Leading Market Players |
|---|
| Talabat |
| Noon |
| Careem |
| InstaShop |
| Deliveroo |
| Amazon |
| Kibsons |
| El Grocer |
| Nana |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed logistics infrastructure and venture-capital-funded platform consolidation are reshaping pricing discipline across Dubai and Abu Dhabi corridors. Dark store ownership concentration in Jumeirah and Business Bay enables captive operators to resist margin erosion while asset-light competitors face third-party logistics markups.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive pricing architecture. Subscription memberships covering unlimited grocery, restaurant, and retail delivery command premium positioning versus pay-per-order commodity fulfillment. Price differentiation rests on delivery speed guarantees and cold-chain certification tiers for pharmaceutical categories. Cost compression in third-party logistics tiers is intensifying because rider availability bottlenecks during peak windows force surge pricing mechanisms. Individual consumers in Marina and Downtown Dubai show lowest price sensitivity, while price-conscious segments in Sharjah and Northern Emirates gravitate toward unbundled pay-per-order models.
Supply Chain Analysis
Workforce availability constraints in UAE logistics hubs are reshaping fulfillment network deployment. Supply concentration centers on domestic dark store infrastructure in Dubai, cross-border inventory staging from Saudi Arabia, and third-party fleet partnerships originating in Oman. Raw material dependencies include temperature-controlled packaging materials, last-mile delivery vehicles, and cloud computing infrastructure for dispatch algorithms. Single-source vulnerability in algorithmic dispatch talent pools creates operational risk. Distribution runs through hub-and-spoke micro-fulfillment networks radiating from high-density residential corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAE q-commerce represents a late-cycle quality story as young professionals shift convenience spending toward bundled subscription tiers with guaranteed sub-60-minute service levels. Premium specifications now center on pharmaceutical cold-chain compliance and super-app service convergence.
For Market Incumbents: Acquire dark store real estate in Al Reem Island and Saadiyat corridors before rental escalation. Consolidate algorithmic dispatch capabilities through targeted hiring of machine learning engineers with real-time logistics optimization experience. Nafis program labor reclassification threats demand proactive workforce structuring to preserve contractor model economics. For New Entrants and Emerging Players: Capture pharmaceutical delivery white space in chronic medication segments where MOHAP licensing creates barrier-to-entry protection. Abu Dhabi residential clusters around Al Reem Island remain underpenetrated relative to Dubai density. Partner with existing third-party logistics networks to avoid fixed asset commitment during geographic expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light marketplace orchestrators facing third-party logistics dependency risks. Long-term viability favors inventory-owning operators with captive fulfillment infrastructure and super-app cross-selling capabilities. Watch Nafis program labor classification rulings as the critical inflection signal for platform cost structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Dark Store Network Expansion | Captive fulfillment infrastructure in Al Reem Island reduces third-party logistics markups and secures capacity. |
| Subscription Model Penetration | Monthly memberships in Marina and Downtown Dubai lock recurring revenue and reduce customer acquisition costs. |
| Pharmaceutical Cold-Chain Compliance | MOHAP-aligned temperature logging and prescription verification opens margin-accretive health categories. |
| Super-App Service Convergence | Cross-selling mobility, delivery, and financial services within unified interfaces improves multi-vertical retention. |
| Algorithmic Dispatch Talent Acquisition | Machine learning engineers with real-time logistics optimization experience reduce delivery latency variance. |
Research Methodology
Multiple input streams — platform operations executives, dark store network managers, MOHAP regulatory affairs specialists, and gig workforce coordinators — were reconciled against customs records, central bank payment flow data, and real estate leasing databases. Primary interviews with logistics technology vendors and grocery retail procurement heads informed operational cost structures. Secondary validation drew from UAE commercial regulations, SAMR-aligned competition filings, and Nafis program documentation. Bottom-up dark store unit economics were triangulated against top-down market sizing from transaction volume estimates.
Historical growth trajectories were cross-referenced against panel input from platform strategy executives to anchor projection assumptions. The analytical framework modeled service type, customer relationship depth, technology interface, and delivery model ownership across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation. Forecast inputs incorporated dark store network expansion timelines and central bank instant payment adoption curves.
Regulatory reclassification of gig workers, escalation of commercial rents in prime corridors, and data localization mandate implementation are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding Nafis program stability and cloud infrastructure sovereignty rules. Material deviation in labor classification rulings or dark store rental trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
Asia Pacific Same Day Delivery Market
E-Commerce Solutions
M-Commerce Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
South America E-Commerce Apparel Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
Asia-Pacific Dropshipping Market
E-Commerce Solutions
Portugal E-Commerce Market
E-Commerce Solutions
Moldova E-Commerce Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
Europe E-Commerce Apparel Market