
 Asia-Pacific E-Commerce Logistics Market | 2026-2036
Asia-Pacific E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific E-Commerce Logistics Market Insights
Subscription-based warehousing is rebalancing what e-commerce logistics providers sell, shifting from per-shipment fees to recurring capacity contracts. JD Logistics leverages its captive fulfillment network to anchor same-day delivery promises across tier-one Chinese cities. Delhivery competes through dense last-mile node coverage that sustains cost leadership in India's fragmented address landscape. SF Express dominates premium cross-border lanes with integrated air freight control.
Asia-Pacific e-commerce logistics encompasses the movement, storage, and fulfillment of goods ordered through digital channels, requiring real-time inventory synchronization across multi-node distribution networks with throughput velocities exceeding traditional retail by an order of magnitude. The primary commercial purpose is collapsing order-to-delivery time windows while absorbing demand volatility from promotional surges. Last-mile delivery commands the largest service-type revenue pool but faces margin compression from urban congestion fees and rider wage floors. Fulfillment centers represent the fastest-expanding segment as brands abandon owned warehouses for third-party operator capacity. Drone delivery remains nascent across the region but attracts disproportionate pilot investment from regulators seeking to decongest ground infrastructure.
China's SAMR enforces platform antitrust provisions that restrict exclusive logistics arrangements, while India's DGFT mandates e-commerce export documentation digitization that reshapes cross-border customs clearance timelines. Japan's METI logistics efficiency standards drive warehouse automation investment to offset labor force contraction. Stakeholders must monitor how Indonesia's national freight data exchange and Vietnam's customs modernization programs alter competitive access to Southeast Asia's most populous consumer corridors.
Market Dynamics
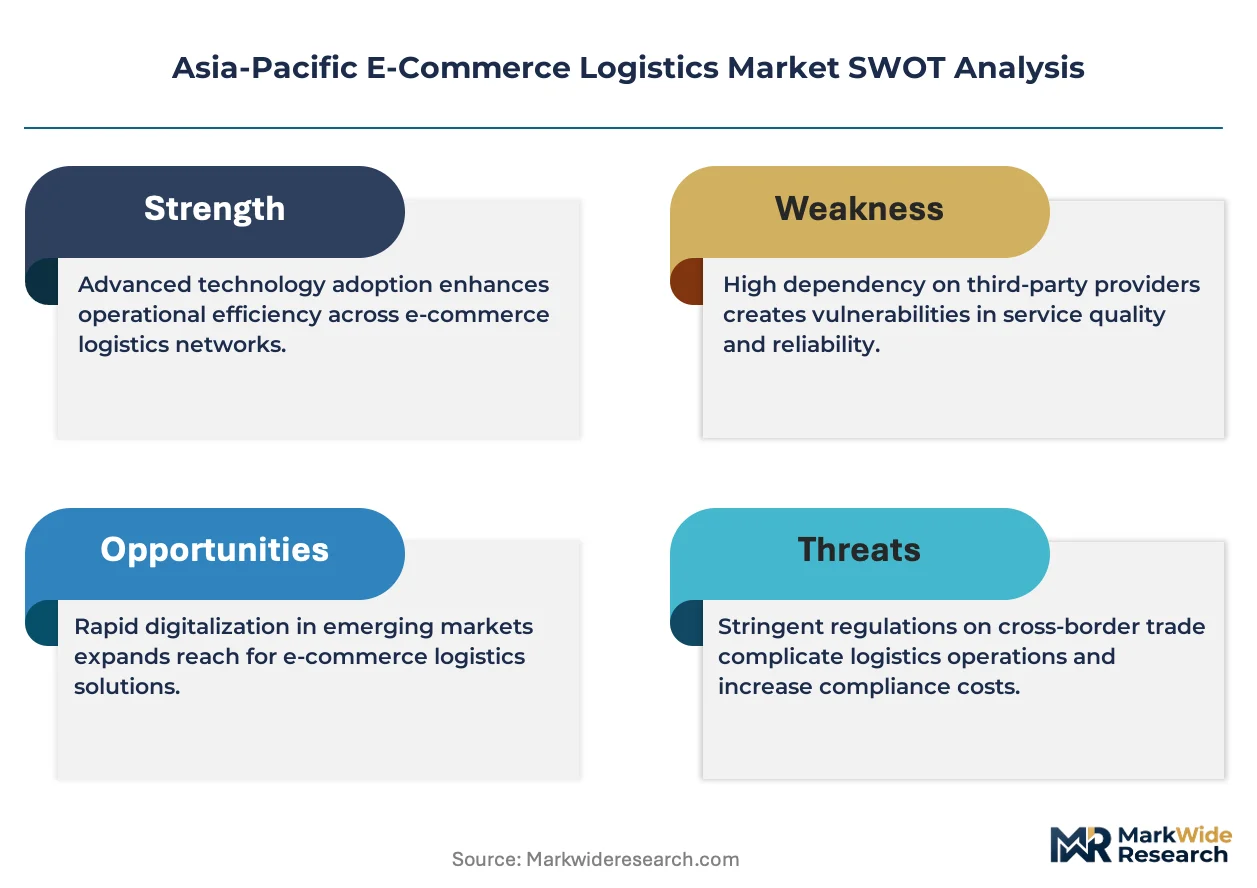
Subscription-based warehousing contracts are displacing transactional fulfillment pricing across Asia-Pacific e-commerce corridors, locking brands into multi-year capacity commitments that reshape operator revenue stability and capital deployment cycles.
Growth Catalysts
- India's PLI scheme for logistics infrastructure:Capital subsidies accelerate automated sortation hub deployment across tier-two and tier-three consumption clusters.
- Fashion and apparel cross-border fulfillment:Southeast Asian retailers expand bonded warehouse networks to collapse delivery windows into Indonesia, Vietnam, and Philippines consumer bases.
- China's MIIT digital freight platform mandates:Real-time load-matching requirements force fleet operators onto centralized exchanges that improve asset utilization.
Market Restraints
- Urban congestion fees and rider wage floors:Last-mile delivery margins compress as municipal authorities in Chinese and Indian megacities impose per-delivery levies and minimum earnings guarantees.
- Warehouse labor force contraction:Japan's METI logistics efficiency standards expose acute shortages of forklift-certified operators and systems technicians.
- Exclusive logistics arrangement prohibitions:China's SAMR antitrust enforcement prevents platforms from locking merchants into captive fulfillment networks.
Strategic Opportunities
- Indonesia's Greater Jakarta corridor warehouse absorption surge:Third-party operators secure long-term leases in Bekasi and Bogor industrial zones ahead of demand maturation.
- Drone delivery pilot programs:Regulators in Singapore and Thailand authorize beyond-visual-line-of-sight trials to decongest ground infrastructure in dense urban cores.
- Vietnam customs modernization:Digitized export documentation accelerates cross-border clearance timelines for e-commerce parcels entering ASEAN markets.
Industry Challenges
- Real-time inventory synchronization complexity:Multi-node distribution networks require API integration across incompatible legacy warehouse management systems.
- Promotional surge absorption capacity:Singles' Day and year-end festival spikes strain automated sortation throughput, forcing temporary labor hiring that erodes unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific E-Commerce Logistics Market |
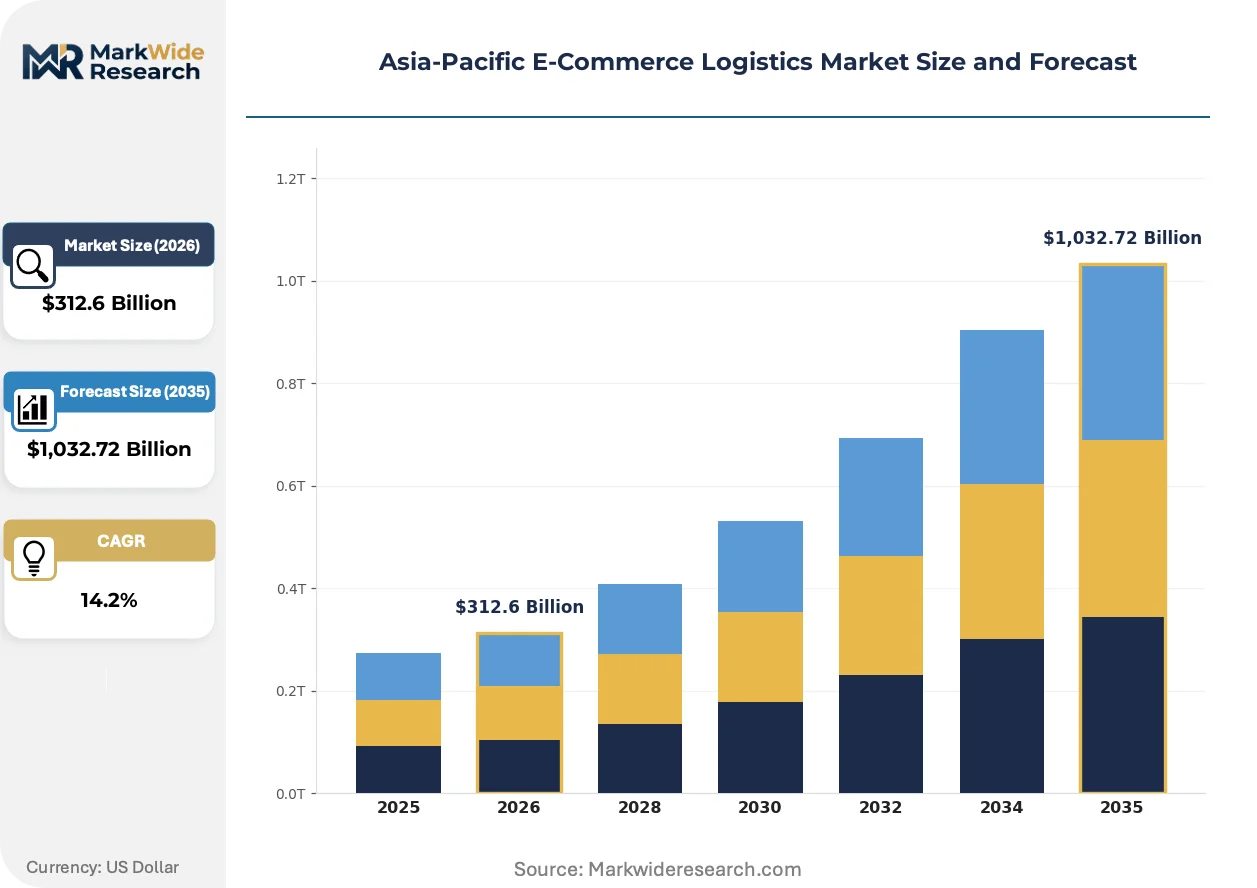
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,032.72 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last-Mile Delivery, Fulfillment Centers, Warehousing, Return Management Customer Type: B2C, B2B, C2C, Online Marketplaces Delivery Mode: Ground Shipping, Air Freight, Sea Freight, Drone Delivery Packaging Type: Cartons, Pallets, Bags, Custom Packaging |
| Companies Covered | Ninja Van, Cainiao, SF Express, Sinotrans Limited, Nippon Express, JD Logistics, Delhivery, YCH Logistics, CJ Logistics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific E-Commerce Logistics Market Trends and Innovations
Automation technologies and regulatory digitization mandates are compressing fulfillment cycle times while reshaping competitive positioning across Asia-Pacific logistics corridors.
Autonomous mobile robots (AMRs) with computer vision navigation are electrifying warehouse picking workflows in Chinese and South Korean fulfillment centers. Electronics and fast-fashion merchants deploy these systems to triple pick rates during promotional surges. The technology is electrifying labor cost structures and enabling same-day delivery promises in tier-one cities previously constrained by human throughput ceilings.
Indonesia's national freight data exchange mandates real-time visibility into truck location and load status for all licensed operators. The policy forces consolidation among fragmented owner-driver fleets that previously operated offline. Cross-border e-commerce exporters face the steepest compliance burden as they integrate with customs pre-clearance systems.
Merchant procurement of fulfillment capacity is fragmenting across multiple third-party operators rather than consolidating with single providers. Direct-to-consumer brands in India and Southeast Asia distribute inventory across four to six regional warehouses to optimize delivery speed against cost. This pattern concentrates in apparel and consumer electronics verticals where return rates drive proximity requirements.
Asia-Pacific E-Commerce Logistics Market Segmentation
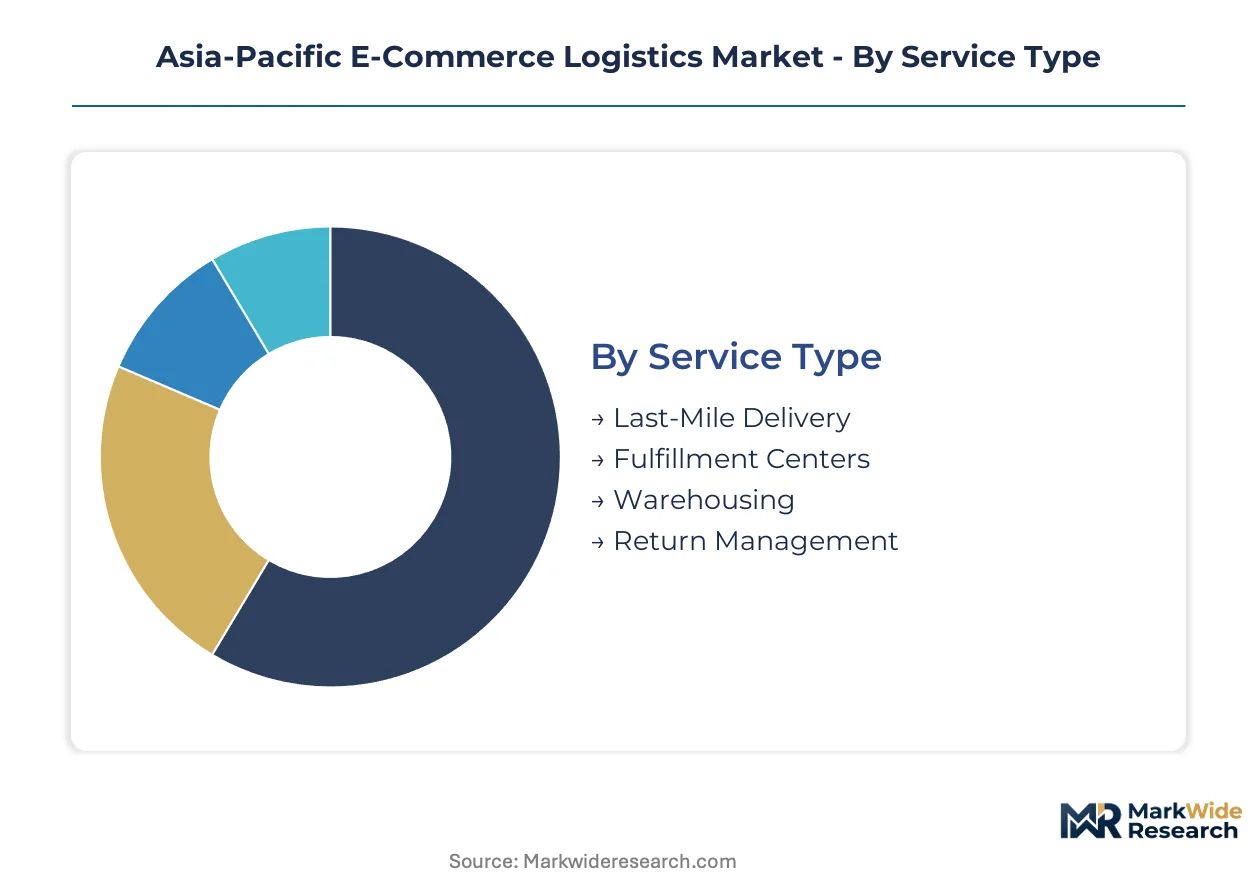
E-commerce logistics operators in Asia-Pacific structure service portfolios around velocity tiers and inventory custody models. Segment boundaries determine capital deployment intensity and margin durability across the region's fragmented consumption corridors.
Service Type:
Fulfillment centers and last-mile networks demand the heaviest upfront infrastructure investment, with automated sortation hubs requiring capital commitments that dwarf asset-light service lines.
- Last-Mile Delivery:Final-leg courier networks aggregate parcels from urban micro-fulfillment nodes for direct-to-consumer handoff. Demand concentrates in Indonesia's Greater Jakarta corridor where warehouse absorption surges strain rider capacity. Municipal congestion fees in Chinese and Indian megacities compress per-delivery margins.
- Fulfillment Centers:Multi-story automated facilities with AMR-enabled picking workflows process inventory for same-day delivery promises. China's tier-one cities anchor the densest concentration as JD Logistics and third-party operators scale captive networks. India's PLI scheme for logistics infrastructure accelerates automated sortation hub deployment in tier-two clusters.
- Warehousing:Long-term storage infrastructure supports inventory buffering against promotional surges. Subscription-based contracts are displacing transactional pricing across Southeast Asian corridors.
- Return Management:Reverse logistics networks handle apparel and electronics return volumes that exceed traditional retail rates. Proximity requirements drive fragmentation across multiple regional nodes.
Most installed capacity flows through Fulfillment Centers. Expansion is steepest in Last-Mile Delivery.
Customer Type:
Contract scale and payment reliability separate enterprise-grade accounts from fragmented merchant bases, reshaping operator working capital requirements and API integration priorities.
- B2C:Direct-to-consumer brands procure multi-node distribution capacity to collapse delivery windows. India's fragmented address landscape rewards dense last-mile node coverage.
- B2B:Wholesale replenishment and retail distribution contracts emphasize palletized freight and scheduled lane density. China's MIIT digital freight platform mandates force fleet operators onto centralized exchanges.
- C2C:Peer-to-peer parcel flows concentrate in cross-border corridors where SF Express dominates premium lanes with integrated air freight control.
- Online Marketplaces:Platform-anchored merchants drive the steepest volume spikes during Singles' Day and year-end festivals, straining automated sortation throughput.
B2C commands the deepest revenue pool. B2B posts the most stable contract tenures.
Delivery Mode:
Speed-cost tradeoffs and regulatory authorization boundaries determine competitive positioning across ground, air, and emerging autonomous channels.
- Ground Shipping:Truck-based parcel networks absorb the majority of intra-city and inter-city volume across Asia-Pacific. Indonesia's national freight data exchange mandates real-time visibility that forces consolidation among fragmented owner-driver fleets.
- Air Freight:Premium cross-border lanes require integrated carrier relationships and customs pre-clearance systems. Vietnam's customs modernization accelerates clearance timelines for e-commerce parcels entering ASEAN markets.
- Sea Freight:Containerized consolidation serves bulk inventory repositioning and bonded warehouse replenishment. Fashion and apparel retailers scale cross-border fulfillment networks to collapse delivery windows into Southeast Asian consumer bases.
- Drone Delivery:Beyond-visual-line-of-sight trials in Singapore and Thailand aim to decongest ground infrastructure in dense urban cores. Regulatory authorization remains limited to pilot programs.
Ground Shipping carries the highest volume throughput. Drone Delivery is climbing the fastest on pilot investment.
Packaging Type:
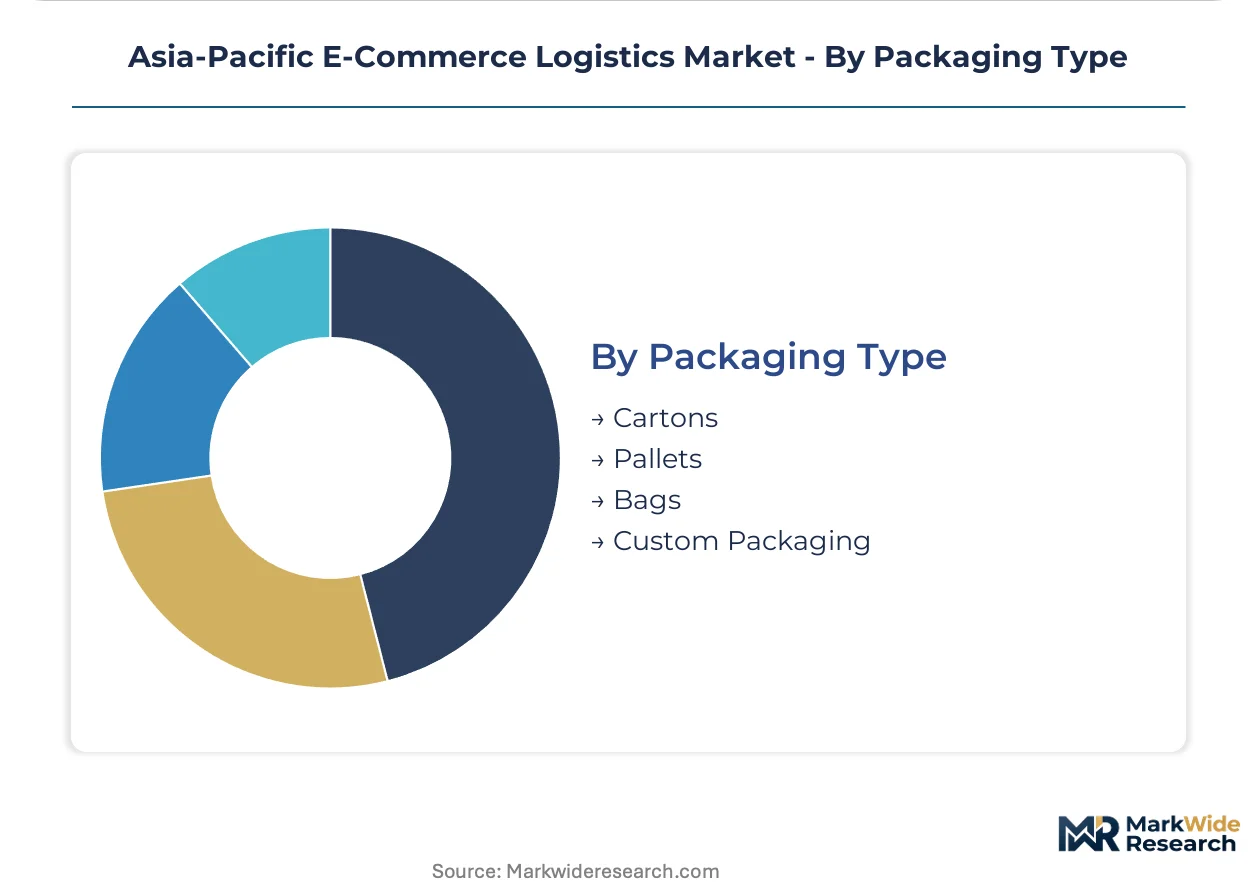
Dimensional weight pricing and automation compatibility drive standardization pressures against customization demands for brand differentiation.
- Cartons:Corrugated fiberboard containers dominate automated sortation workflows with standardized dimensions. Electronics and fast-fashion merchants deploy AMR-enabled systems to triple pick rates during promotional surges.
- Pallets:Unitized loads support B2B replenishment and fulfillment center inbound flows. Japan's METI logistics efficiency standards drive warehouse automation investment to offset labor force contraction.
- Bags:Poly mailers reduce dimensional weight charges for apparel and soft goods. Return rates in apparel verticals drive proximity requirements for packaging reuse.
- Custom Packaging:Branded unboxing experiences and protective inserts serve premium direct-to-consumer positioning. China's SAMR antitrust enforcement prevents platforms from locking merchants into captive fulfillment networks that might restrict packaging choice.
Cartons move through the most automated handling infrastructure. Custom Packaging is gaining share fastest among premium-positioned brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one fulfillment density contrasts sharply with Indonesia's fragmented archipelago logistics, while India's address infrastructure gaps create divergent competitive requirements across the region's three largest consumer economies.
China
JD Logistics and Cainiao anchor same-day delivery promises through captive fulfillment networks in Shanghai, Beijing, and Shenzhen. MIIT digital freight platform mandates force fleet operators onto centralized exchanges that improve asset utilization. SAMR antitrust enforcement prevents platforms from locking merchants into exclusive logistics arrangements, opening third-party operator access.
India
Delhivery competes through dense last-mile node coverage that sustains cost leadership in fragmented address landscapes across tier-two and tier-three clusters. PLI scheme capital subsidies accelerate automated sortation hub deployment in consumption corridors outside Mumbai and Delhi-NCR. DGFT mandates for e-commerce export documentation digitization reshape cross-border customs clearance timelines.
Indonesia
Ninja Van and local operators absorb warehouse absorption surges in Bekasi and Bogor industrial zones within the Greater Jakarta corridor. National freight data exchange mandates force consolidation among fragmented owner-driver fleets that previously operated offline. Cross-border e-commerce exporters face steep compliance burdens integrating with customs pre-clearance systems.
Japan
Nippon Express leverages METI logistics efficiency standards to justify warehouse automation investment that offsets acute forklift-certified operator shortages. Labor force contraction in Kanto and Kansai regions drives multi-story automated facility deployment. Electronics and automotive parts e-commerce channels concentrate fulfillment capacity in Chubu and Osaka industrial belts.
Vietnam
Customs modernization programs accelerate digitized export documentation for e-commerce parcels entering ASEAN markets through Ho Chi Minh City and Hanoi corridors. Bonded warehouse networks expand to collapse delivery windows into Southeast Asian consumer bases. Ground shipping consolidation intensifies as regional operators secure long-term industrial zone leases ahead of demand maturation.
Asia-Pacific E-Commerce Logistics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform-captive networks commanding tier-one city density while independent operators capture cross-border premium lanes. Market structure tilts toward consolidation in China and fragmentation in Southeast Asian archipelago markets. Three archetypes dominate: vertically integrated platform logistics arms, asset-light cross-border specialists, and regional last-mile aggregators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators secure industrial zone leases ahead of demand maturation.
Among platform-anchored operators, JD Logistics exemplifies the vertically integrated archetype through captive fulfillment network control, while SF Express occupies the premium cross-border specialist position with integrated air freight relationships. Delhivery represents the regional last-mile aggregator model competing through dense node coverage in fragmented address landscapes. These three companies anchor the competitive topology without exhausting the segment's structural diversity.
| Leading Market Players |
|---|
| Ninja Van |
| Cainiao |
| SF Express |
| Sinotrans Limited |
| Nippon Express |
| JD Logistics |
| Delhivery |
| YCH Logistics |
| CJ Logistics |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals for logistics fleet electrification gate both qualified supply and premium-tier pricing access, as operators with compliant green fleets command rate premiums while carbon-intensive competitors face margin compression from municipal congestion fees and emissions levies across tier-one cities.
Pricing Analysis
Capacity additions in Indonesia's Greater Jakarta corridor are reshaping price floors for third-party warehousing as Bekasi and Bogor industrial zone leases absorb demand surges ahead of maturation. Subscription-based contracts displace transactional fulfillment pricing, with three-tier pricing structure across premium, standard, and economy levels differentiating by automation grade and same-day delivery guarantees. Cost compression in last-mile delivery intensifies because rider wage floors and urban congestion levies erode per-delivery margins. Direct-to-consumer brands exhibit highest price sensitivity, while enterprise marketplace merchants prioritize speed reliability over unit cost.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale merchant demand through multi-node inventory distribution across four to six regional warehouses. Supply concentration rests on China, India, and Vietnam as primary fulfillment infrastructure hubs, with automated sortation equipment and AMR systems drawing from South Korean and Japanese technology suppliers. Single-source vulnerability concentrates in semiconductor-dependent warehouse automation controllers. Distribution runs through platform-anchored captive networks and independent third-party operators competing for merchant procurement fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as e-commerce penetration deepens across Southeast Asia's archipelago geographies, with subscription-based warehousing contracts locking in recurring revenue visibility regardless of promotional volatility.
For Market Incumbents: Anchor tier-one city density through automated fulfillment center expansion before emerging entrants secure industrial zone leases in Bekasi and Bogor. Lock merchant brands into multi-year capacity commitments to defend against platform-captive network poaching. Invest in AMR-enabled picking workflows to offset labor force contraction risks flagged by Japan's METI standards. For New Entrants and Emerging Players: Tier-two Indian consumption clusters present the most penetrable white-space as PLI scheme subsidies accelerate infrastructure deployment outside Mumbai and Delhi-NCR. Vietnam's customs modernization corridors offer cross-border specialization angles with lower incumbent saturation than Greater Jakarta. Pursue drone delivery pilot authorization in Singapore and Thailand to establish regulatory relationship advantages before beyond-visual-line-of-sight permits broaden. For Investors and Strategic Acquirers: Valuations sit cheapest among regional last-mile aggregators with dense node coverage but limited captive fulfillment assets. Long-term viability favors operators with integrated air freight control for premium cross-border lanes. Monitor Indonesia's national freight data exchange compliance integration rates as inflection indicator for consolidation timing among fragmented owner-driver fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fulfillment Center Deployment | AMR-enabled picking triples throughput velocity during Singles' Day promotional surges. |
| Multi-Node Inventory Distribution | Four-to-six warehouse fragmentation optimizes delivery speed against cost in apparel verticals. |
| Drone Delivery Pilot Authorization | Beyond-visual-line-of-sight trials in Singapore decongest ground infrastructure in dense urban cores. |
| Subscription-Based Warehousing Contracts | Recurring capacity commitments reshape operator revenue stability and capital deployment cycles. |
| Cross-Border Bonded Warehouse Expansion | Customs pre-clearance integration collapses delivery windows into Indonesia and Philippines consumer bases. |
Research Methodology
Coverage spans China, India, Indonesia, Japan, and Vietnam, with primary inputs from each market's logistics corridor stakeholders. Primary interviews with fulfillment center operators, last-mile network managers, e-commerce platform procurement leads, and warehouse automation systems integrators combined with secondary validation from MIIT digital freight platform disclosures, DGFT export documentation mandates, and METI logistics efficiency standards. Bottom-up merchant demand sizing and top-down infrastructure capacity assessment provided triangulation across the analysis window.
Rate-of-change decomposition across service type, customer type, delivery mode, and packaging type dimensions informed projection modeling. CAGRs derived from segment-level demand elasticity analysis against infrastructure deployment timelines, with cross-border volume growth and automation adoption curves as industry-specific forecast inputs throughout the forecast period.
Underlying measurement precision varies by segment; fulfillment center capacity data carries tighter precision than drone delivery pilot investment flows. Forecasts reflect assumptions regarding regulatory digitization pace and promotional surge frequency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
Express and Parcel Market
E-Commerce Solutions
Metaverse in E-Commerce Market
E-Commerce Solutions
Singapore E-Commerce Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
Saudi Arabia Delivery Apps Market
E-Commerce Solutions
E-Commerce Apparel Market
E-Commerce Solutions
Online on-Demand Laundry Service Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
India Digital Gift Card Market
E-Commerce Solutions
Croatia E-Commerce Market
E-Commerce Solutions
E-Commerce Ecosystem Market
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market
E-Commerce Solutions
South Africa E-Commerce Market