
 Artificial Intelligence (AI) in Radiology Market | 2026-2036
Artificial Intelligence (AI) in Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in Radiology Market Outlook
The United States is tilting toward cloud-native AI deployment as health systems modernize imaging infrastructure. Siemens Healthineers AG leverages its installed base of CT and MRI modalities to embed algorithmic workflows directly at the scanner level. GE HealthCare anchors its position through Edison platform integration, which sustains recurring revenue from algorithm marketplace subscriptions. Philips differentiates via diagnostic pathway orchestration that connects radiology operations with enterprise-wide patient flow management.
Artificial intelligence in radiology encompasses machine learning algorithms trained on annotated medical images to detect, classify, or quantify pathological findings with defined sensitivity and specificity thresholds. These systems process DICOM-standard imaging data to augment radiologist interpretation, reduce turnaround times, and standardize reporting quality across high-volume screening programs. Image analysis applications command the deepest clinical validation, while workflow optimization tools are capturing margin pools by addressing labor shortages and throughput constraints. Cloud-based deployment is outpacing on-premises installation as cybersecurity frameworks mature and health systems prioritize capital expenditure flexibility.
FDA software-as-a-medical-device regulations shape product development timelines and predicate device requirements for algorithm clearance. HIPAA interoperability provisions and the ONC information blocking rules are accelerating data liquidity essential for training and validating radiology AI models. Stakeholders must monitor evolving reimbursement determinations from CMS and private payers, as coverage decisions for AI-augmented reads will determine whether adoption scales beyond academic medical centers into community hospital settings.
Market Dynamics
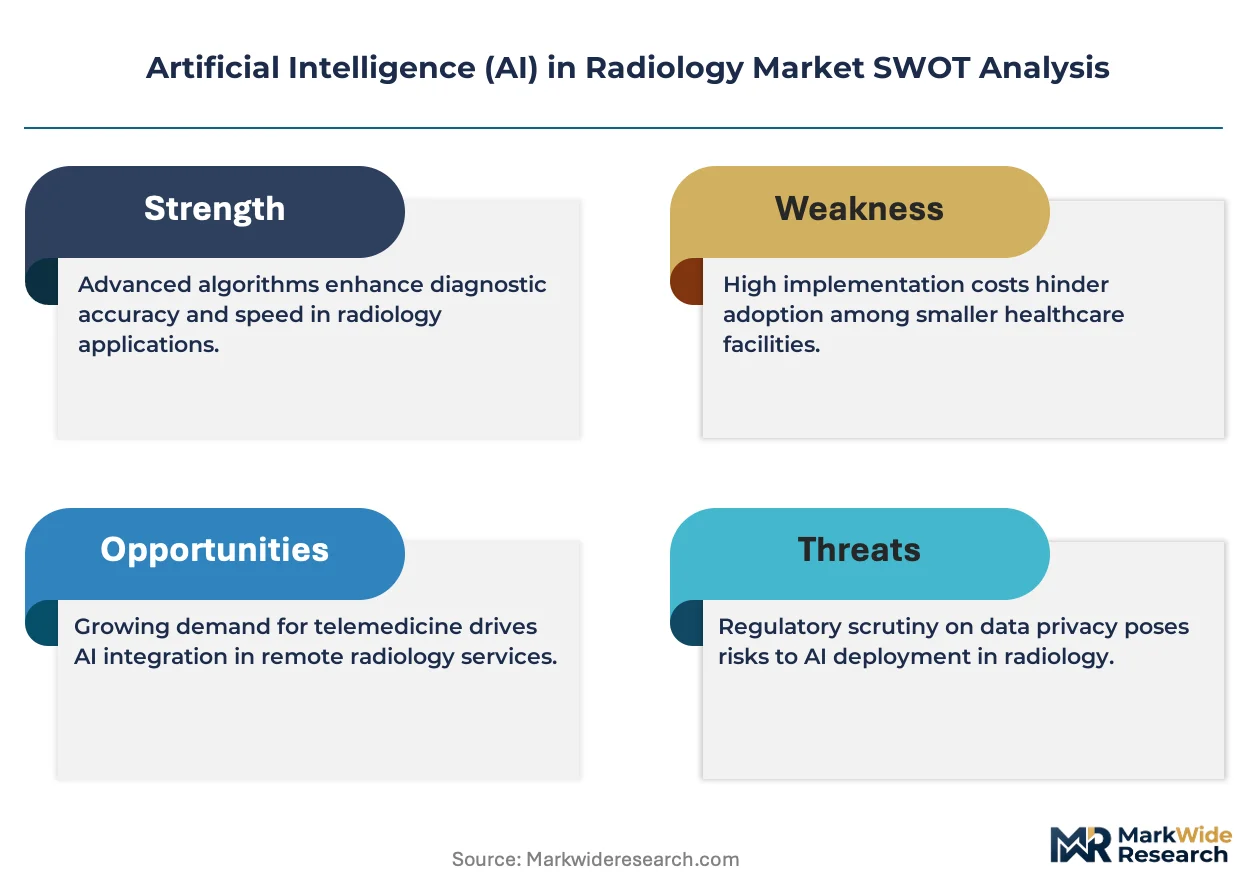
Cloud-native deployment architectures are compressing capital barriers for mid-sized health systems, while FDA software-as-a-medical-device pathways accelerate commercial entry for algorithm developers seeking recurring revenue from integrated diagnostic workflows.
Growth Catalysts
- CMS reimbursement determinations:Coverage decisions for AI-augmented reads in lung cancer screening programs are expanding procurement budgets beyond academic medical centers into community hospital networks.
- Workflow optimization tools:Labor shortages in diagnostic radiology are pushing integrated delivery networks toward algorithmic triage systems that reduce turnaround times for emergency department imaging.
- ONC information blocking rules:HIPAA interoperability provisions are accelerating data liquidity essential for training and validating machine learning models on diverse patient populations.
Market Restraints
- Validation burden:FDA predicate device requirements for algorithm clearance impose lengthy clinical trials that delay revenue recognition for developers without existing 510(k) pathways.
- Cybersecurity infrastructure:Health systems with legacy PACS architectures face capital intensity in hardening network perimeters for cloud-based AI deployment.
- Radiologist workflow integration:DICOM-standard compatibility gaps between proprietary scanner protocols and third-party algorithms create technical friction in multi-vendor environments.
Strategic Opportunities
- Point-of-care ultrasound:Emergency medicine and critical care units present underpenetrated demand for real-time AI guidance in resource-constrained settings.
- EU AI Act compliance services:Conformity assessment requirements for high-risk medical devices create advisory revenue streams for algorithm developers with established quality management systems.
- Federated learning architectures:Multi-institutional model training without centralized data sharing is collapsing barriers for community hospitals to participate in algorithm development.
Industry Challenges
- Annotation labor scarcity:Specialist radiologists capable of ground-truth labeling for training datasets command premium compensation that strains startup burn rates.
- Multi-site validation complexity:Algorithm performance degradation across scanner manufacturers and acquisition protocols requires continuous monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in Radiology Market |
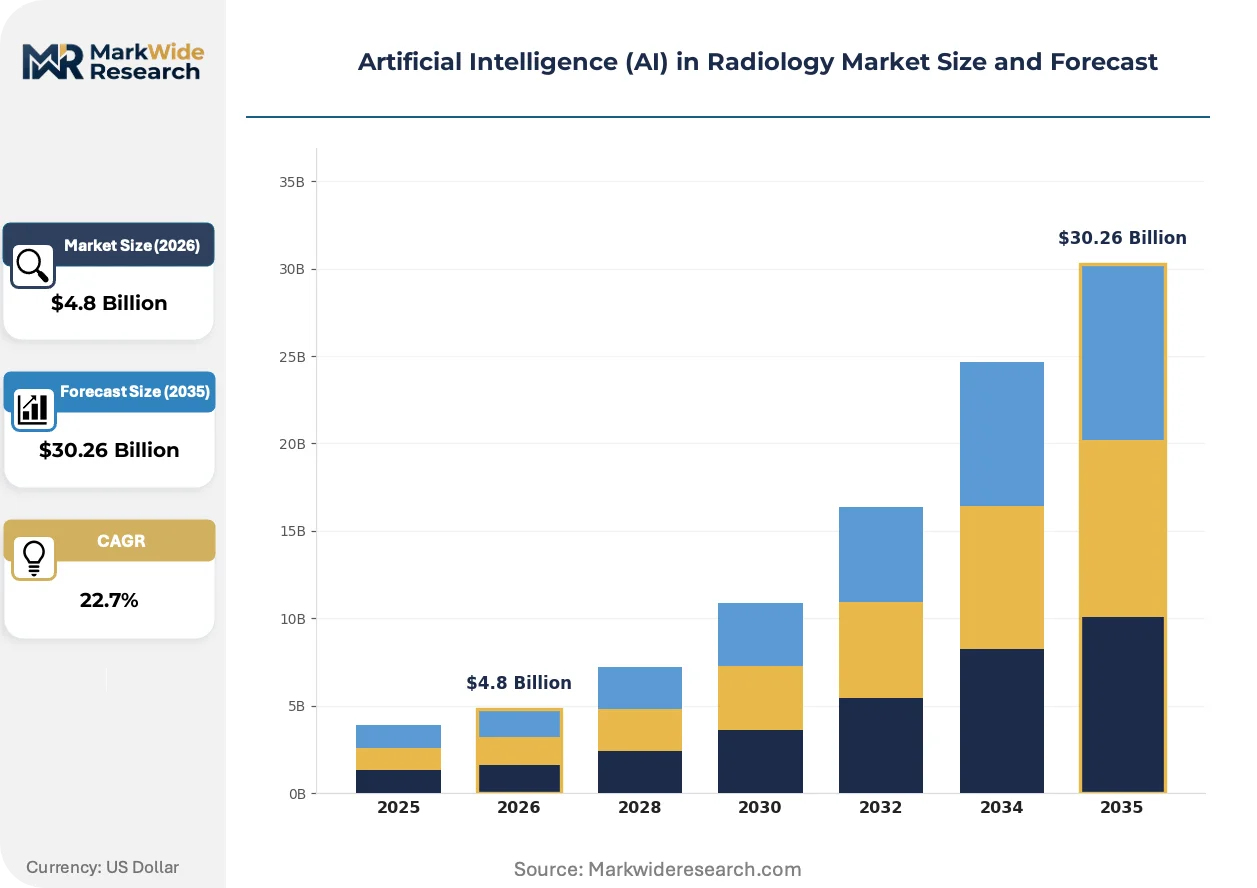
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Image Analysis, Workflow Optimization, Clinical Decision Support, Predictive Analytics End User: Hospitals, Diagnostic Centers, Research Facilities, Academic Institutions Application: X-Ray, MRI, CT Scan, Ultrasound Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Siemens Healthineers AG, GE HealthCare, Koninklijke Philips N.V., Aidoc, Rad AI, Canon Medical Systems, Fujifilm Holdings Corporation, Lunit, Viz.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in Radiology Market Strategic Shifts
Foundation models trained on heterogeneous imaging modalities are compressing development timelines for diagnostic algorithms, while regulatory frameworks mature to accommodate continuous learning systems that improve with deployment scale.
Edge computing architectures embedded directly into CT and MRI scanners are collapsing latency between image acquisition and algorithmic inference. Community health systems lacking dedicated IT infrastructure are adopting these scanner-integrated deployments fastest. The structural consequence is collapsing reliance on centralized cloud processing for time-critical diagnostic workflows.
The EU AI Act's risk classification framework for medical devices is mandating conformity assessments that favor developers with established quality management systems. Algorithm vendors are restructuring product portfolios to secure CE marking before MDR transition deadlines. High-risk diagnostic applications in oncology screening face the steepest compliance burden and are consolidating around vendors with regulatory affairs capabilities.
Subscription-based licensing for algorithm marketplaces is displacing perpetual software licenses in procurement negotiations. Integrated delivery networks are consolidating vendor relationships to secure enterprise-wide pricing for multi-modality AI portfolios. This shift is most visible in United States health systems modernizing imaging infrastructure under capital expenditure constraints.
Artificial Intelligence (AI) in Radiology Market Segmentation
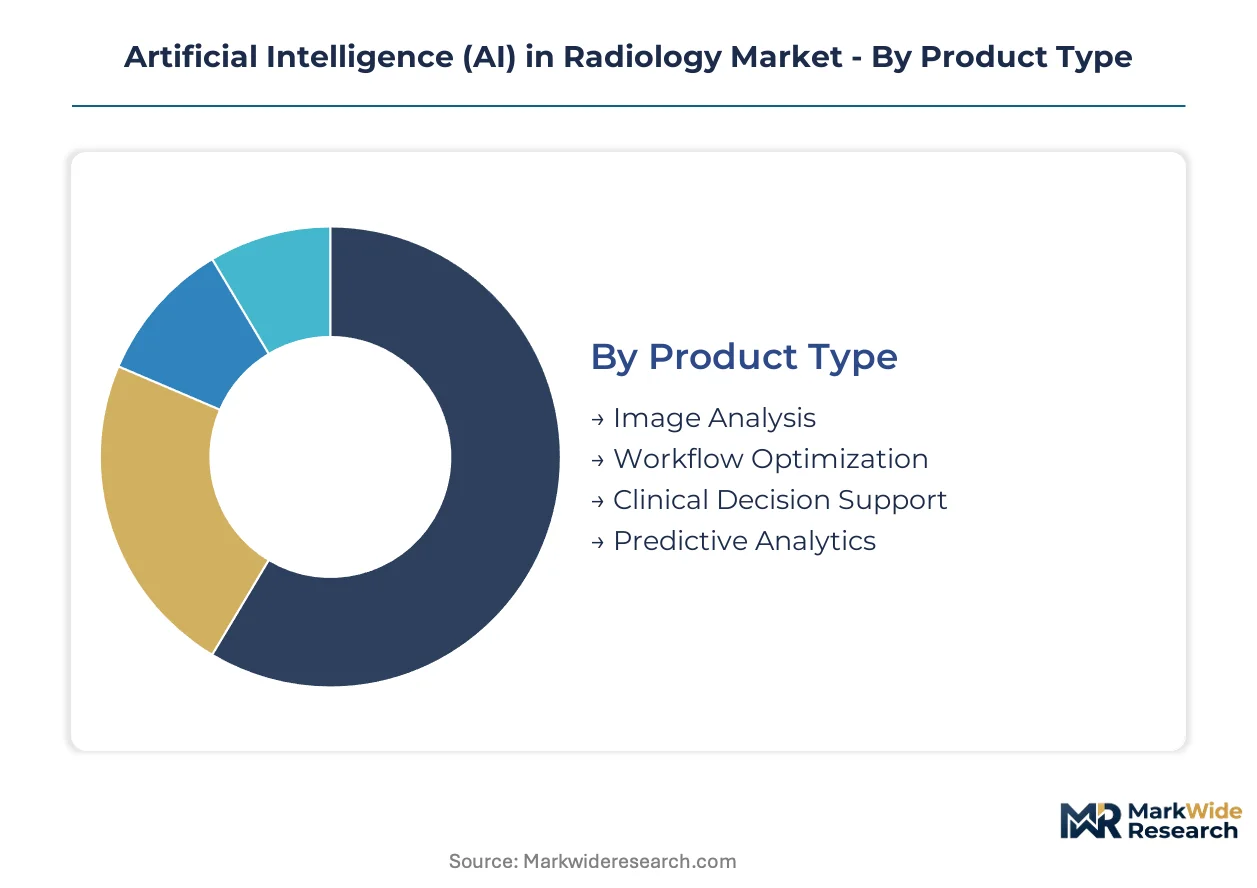
Radiology AI vendors structure product portfolios across four intersecting dimensions. Procurement patterns diverge sharply between capital-constrained community hospitals and academic medical centers with dedicated research infrastructure.
Product Type:
Mature image analysis platforms anchor revenue while emerging workflow optimization tools capture margin from labor shortages.
- Image Analysis:Machine learning algorithms trained on annotated DICOM datasets detect and classify pathological findings with defined sensitivity thresholds. United States integrated delivery networks concentrate procurement in oncology screening and emergency trauma protocols.
- Workflow Optimization:Algorithmic triage systems prioritize study queues and automate preliminary reporting to compress turnaround times. Community hospital networks facing radiologist staffing gaps are deploying these tools fastest.
- Clinical Decision Support:Quantitative biomarker extraction tools integrate structured findings into electronic health record workflows.
- Predictive Analytics:Population-level risk stratification models trained on longitudinal imaging histories.
Image Analysis retains volume leadership; Workflow Optimization holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-scale deployments from point solutions.
- Hospitals:Multi-modality AI portfolios deployed across emergency, inpatient, and ambulatory settings with enterprise-wide licensing. United States health systems under capital expenditure constraints favor subscription-based algorithm marketplaces over perpetual licenses.
- Diagnostic Centers:High-volume imaging facilities prioritize throughput algorithms for screening programs with thin reimbursement margins.
- Research Facilities:Federated learning participation and ground-truth annotation services.
- Academic Institutions:Training data generation and regulatory validation partnerships with algorithm developers.
Hospitals command procurement volume; Diagnostic Centers are climbing the fastest.
Application:
Modality-specific algorithms reflect varying data complexity and regulatory validation burdens.
- CT Scan:Cross-sectional imaging algorithms with established FDA 510(k) pathways for pulmonary embolism and stroke triage. United States emergency departments deploy these for time-critical diagnostic workflows.
- MRI:Soft tissue characterization tools for neurological and musculoskeletal applications with longer validation timelines.
- X-Ray:Chest radiography screening algorithms with the deepest clinical validation and lowest deployment cost.
- Ultrasound:Real-time guidance systems for point-of-care applications in resource-constrained settings.
CT Scan anchors installed base; Ultrasound is gaining share fastest.
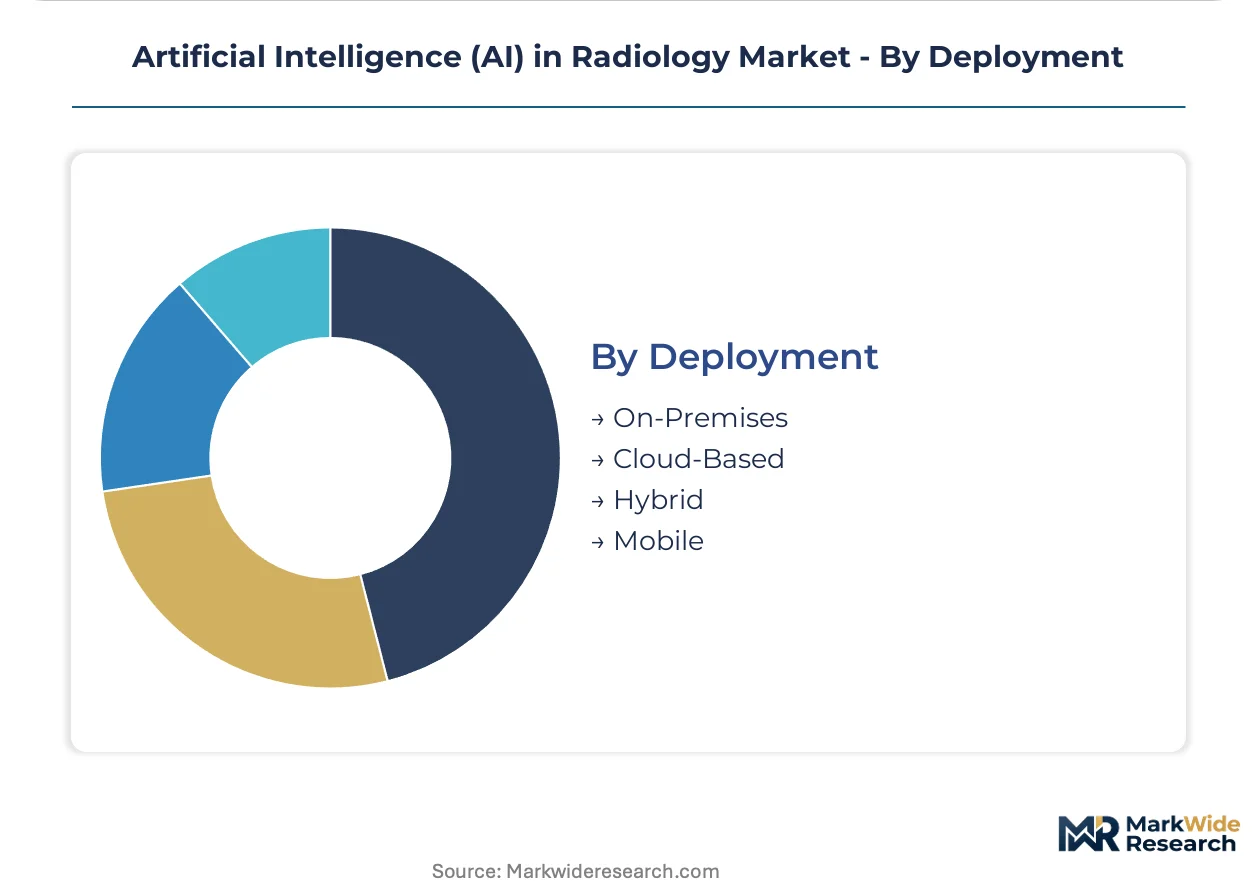
Deployment:
Customer type determines infrastructure requirements and cybersecurity posture.
- Cloud-Based:Scalable compute architectures with API integration into existing PACS and vendor-neutral archives. United States health systems prioritize this model for capital flexibility.
- On-Premises:Air-gapped installations for institutions with legacy infrastructure or stringent data residency requirements.
- Hybrid:Split architectures routing non-sensitive preprocessing to cloud while retaining protected health information locally.
- Mobile:Edge-optimized models for point-of-care ultrasound and teleradiology applications.
Cloud-Based dominates new procurement; Mobile shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA software-as-a-medical-device pathways anchor procurement momentum in the United States, while the EU AI Act and Japan's PMDA frameworks reshape competitive entry across developed markets. Cloud-native deployment architectures and integrated delivery network consolidation determine regional adoption velocity.
United States
CMS reimbursement determinations for AI-augmented lung cancer screening and stroke triage are expanding procurement budgets beyond academic medical centers into community hospital networks. HIPAA interoperability provisions and ONC information blocking rules accelerate data liquidity essential for training machine learning models. The Greater Boston and San Francisco Bay Area clusters concentrate algorithm developers and FDA regulatory expertise.
Germany
University hospital networks in Baden-Württemberg and Bavaria drive validation partnerships for multi-site algorithm performance monitoring. The EU AI Act's high-risk medical device classification mandates conformity assessments favoring developers with established quality management systems. Siemens Healthineers anchors industrial concentration in Erlangen and Forchheim.
Japan
PMDA regulatory frameworks accommodate continuous learning systems that improve with deployment scale, compressing validation timelines for domestic algorithm developers. METI funding programs support federated learning architectures enabling multi-institutional model training. The Kanto region around Tokyo concentrates diagnostic imaging manufacturers and hospital system procurement.
United Kingdom
NHS England's AI Award program de-risks procurement for mid-sized trusts lacking dedicated evaluation infrastructure. MHRA recognition of FDA-cleared algorithms accelerates commercial entry for United States-based developers. London and the Southeast cluster health technology assessment expertise and integrated care system pilot programs.
China
NMPA innovation pathways for AI-assisted diagnostic software attract venture funding toward chest radiography and retinal screening applications. National hospital grading standards mandate imaging quality metrics that algorithm vendors address. The Yangtze River Delta around Shanghai concentrates medical AI startups and cloud infrastructure deployment.
Artificial Intelligence (AI) in Radiology Market Competitive Environment
Installed-base incumbents and venture-backed specialists split the market into distinct competitive spheres. Tier-one imaging equipment manufacturers leverage scanner-level integration to capture recurring algorithm marketplace revenue. Pure-play algorithm developers compete on workflow optimization and point-of-care applications. Dominant competitive moves include strategic partnerships with integrated delivery networks and portfolio diversification across imaging modalities.
Within the installed-base tier, Siemens Healthineers AG and GE HealthCare exemplify archetypes embedding algorithmic workflows directly at the scanner level. Koninklijke Philips N.V. occupies a position emphasizing diagnostic pathway orchestration connecting radiology operations with enterprise patient flow management. Among venture-backed specialists, Aidoc and Rad AI represent algorithm developers securing FDA clearance through software-as-a-medical-device pathways and targeting workflow optimization in emergency department settings.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Aidoc |
| Rad AI |
| Canon Medical Systems |
| Fujifilm Holdings Corporation |
| Lunit |
| Viz.ai |
| Others |
Value Chain & Pricing Dynamics
GPU cluster provisioning in the United States and Taiwan concentrates upstream compute capacity for model training, directing margin capture toward cloud hyperscalers and scanner-integrated deployment tiers where algorithm vendors bundle inference costs into recurring subscriptions.
Pricing Analysis
United States health systems pay 40-60% premiums over European counterparts for FDA-cleared algorithms with established 510(k) predicates. Subscription-based SaaS tiers dominate procurement, with pricing stratifying across enterprise-wide deployments, departmental licenses, and per-study transactional models. Cost compression in the community hospital segment is intensifying because integrated delivery networks leverage consolidated purchasing power. Diagnostic centers with thin screening margins exhibit highest price sensitivity; academic medical centers prioritize regulatory validation depth over unit cost.
Supply Chain Analysis
United States export controls on advanced GPU architectures and semiconductor manufacturing equipment constrain flows to Chinese algorithm developers, fragmenting training infrastructure access across geopolitical blocs. Supply concentrates in Taiwan for advanced node fabrication, the United States for chip design and cloud infrastructure, and China for rare earth processing in MRI magnet components. Algorithm development draws from annotated imaging datasets, specialized radiologist labor, and regulatory consulting services. Single-source vulnerability persists in photolithography equipment. Distribution runs through direct enterprise sales teams and OEM co-marketing agreements with scanner manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is cycling through a post-pandemic capital expenditure recovery as hospital systems modernize imaging infrastructure deferred during liquidity constraints.
For Market Incumbents: Insulate installed-base revenue by embedding algorithm marketplaces directly into CT and MRI scanner operating systems, creating technical switching costs against pure-play competitors. Prioritize FDA 510(k) pathway expansion for continuous learning algorithms to defend against emerging entrants with faster regulatory navigation. Vertical integration into cloud infrastructure provisioning captures margin pools currently flowing to hyperscalers. For New Entrants and Emerging Players: Build out point-of-care ultrasound AI capabilities where emergency medicine departments lack dedicated radiologist coverage and incumbent scanner integration is weakest. Target community hospital networks in the United States with workflow optimization tools addressing staffing gaps rather than competing on diagnostic accuracy in saturated oncology screening. Pursue strategic partnerships with teleradiology service providers as channel partners. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed algorithm developers holding FDA clearances but lacking scanner-level integration partnerships. Five-to-ten-year viability hinges on recurring revenue conversion rates and enterprise contract renewals. Monitor CMS reimbursement determinations for AI-augmented reads as the inflection signal separating scalable platforms from pilot-stage technologies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Expansion | Accelerates commercial entry for algorithm developers seeking predicate device pathways. |
| Scanner-Level Integration Partnership | Siemens Healthineers and GE HealthCare embed workflows directly at modality acquisition points. |
| Cloud-Native Deployment Architecture | Reduces capital barriers for mid-sized health systems prioritizing operational expenditure flexibility. |
| Federated Learning Infrastructure | Enables multi-institutional model training without centralized data sharing across hospital networks. |
| CMS Reimbursement Strategy | Determines whether AI-augmented diagnostic reads scale beyond academic medical centers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiology department chairs, hospital procurement committee members, biomedical informatics officers, and algorithm vendor product managers. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement determinations, hospital GPO contract filings, and ONC interoperability rulemaking dockets. Bottom-up triangulation across installed base estimates and top-down reconciliation against health system capital expenditure surveys anchored market sizing.
Calibration against historical FDA clearance timelines and cloud infrastructure deployment patterns informed projection assumptions across the modeling period. Segmentation dimensions modeled include product type, end-user archetype, imaging modality, and deployment architecture. CAGRs were derived from regression analysis of procurement velocity correlated with reimbursement policy shifts and radiologist workforce shortage metrics. Federated learning adoption curves and EU AI Act compliance timelines served as industry-specific forecast modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by venture-backed specialists with superior continuous learning architectures would shift outcomes. Material shifts in FDA software-as-a-medical-device guidance or CMS coverage determinations for AI-augmented screening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Enterprise Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Content Automation AI Tools Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
AI Recruitment Market