
 Cognitive Systems Market | 2026-2036
Cognitive Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Systems Market Intelligence
Modular AI service bundling is restructuring procurement patterns across enterprise buyers. NVIDIA leverages its full-stack hardware-software integration to anchor high-performance cognitive workloads in data centers. IBM differentiates through Watson's vertical specialization in regulated industries. Google competes by extending cloud-native cognitive APIs that reduce deployment friction for developers.
Cognitive systems integrate artificial intelligence, machine learning, and natural language processing to simulate human reasoning, process unstructured data, and automate complex decision workflows at scale. These platforms operate through neural network architectures trained on large datasets, with inference latency and model accuracy serving as critical performance parameters for real-time applications. Machine learning dominates technology investment due to its foundational role in predictive model development across fraud detection and image analysis applications. Cloud-based deployment captures expanding margin pools as hyperscalers integrate cognitive APIs into subscription tiers, while edge computing grows fastest in manufacturing and autonomous systems where millisecond response requirements exclude centralized processing.
The FDA regulates machine learning-based medical devices through its predetermined change control plan framework, requiring manufacturers to document algorithm modification protocols before market authorization. The EU AI Act imposes risk-tiered compliance obligations on high-stakes cognitive applications in healthcare and finance, with conformity assessments administered by notified bodies under CE marking procedures. ISO/IEC 23053 provides technical standards for AI system transparency and robustness, shaping procurement criteria for enterprise buyers in telecommunications and retail. Stakeholders must monitor evolving liability frameworks that assign accountability between cognitive system developers, deployers, and end-users as regulatory divergence between jurisdictions intensifies compliance complexity.
Market Dynamics
Enterprise procurement of cognitive systems is absorbing pressure from the EU AI Act's risk-tiered compliance framework, which forces healthcare and financial institutions to document algorithmic transparency before deployment authorization.
Growth Catalysts
- FDA Predetermined Change Control Plans:Medical device manufacturers gain regulatory clarity for iterative algorithm updates, accelerating diagnostic imaging platform commercialization.
- Federal AI R&D spending:United States defense and pharmaceutical sectors channel procurement toward high-performance cognitive infrastructure with documented inference latency benchmarks.
- Cloud-native API integration:Hyperscalers embed cognitive services into subscription tiers, reducing deployment friction for developer teams in retail and telecommunications.
Market Restraints
- GPU supply concentration:Taiwan and South Korea foundries constrain availability of high-throughput processors essential for neural network training.
- Conformity assessment bottlenecks:EU notified body capacity limits CE marking throughput for high-risk healthcare applications under the AI Act.
- On-premise infrastructure capex:Financial services firms face stranded asset risk from data center investments competing against elastic cloud alternatives.
Strategic Opportunities
- Edge manufacturing applications:Millisecond response requirements in autonomous systems and predictive maintenance create deployment openings outside centralized cloud architectures.
- ISO/IEC 23053 procurement criteria:Telecommunications and retail buyers now mandate transparency standards, favoring vendors with documented robustness testing.
- India's PLI scheme:Domestic electronics manufacturing incentives attract cognitive hardware assembly investments serving South Asian enterprise demand.
Industry Challenges
- MLEngineer scarcity:Production-grade model deployment and fine-tuning expertise concentrates in coastal technology hubs, inflating compensation benchmarks.
- Legacy system integration:Healthcare providers confront middleware complexity when connecting cognitive platforms to electronic health record architectures.
- Liability framework ambiguity:Courts have not resolved accountability allocation between algorithm developers, system deployers, and clinical end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Systems Market |
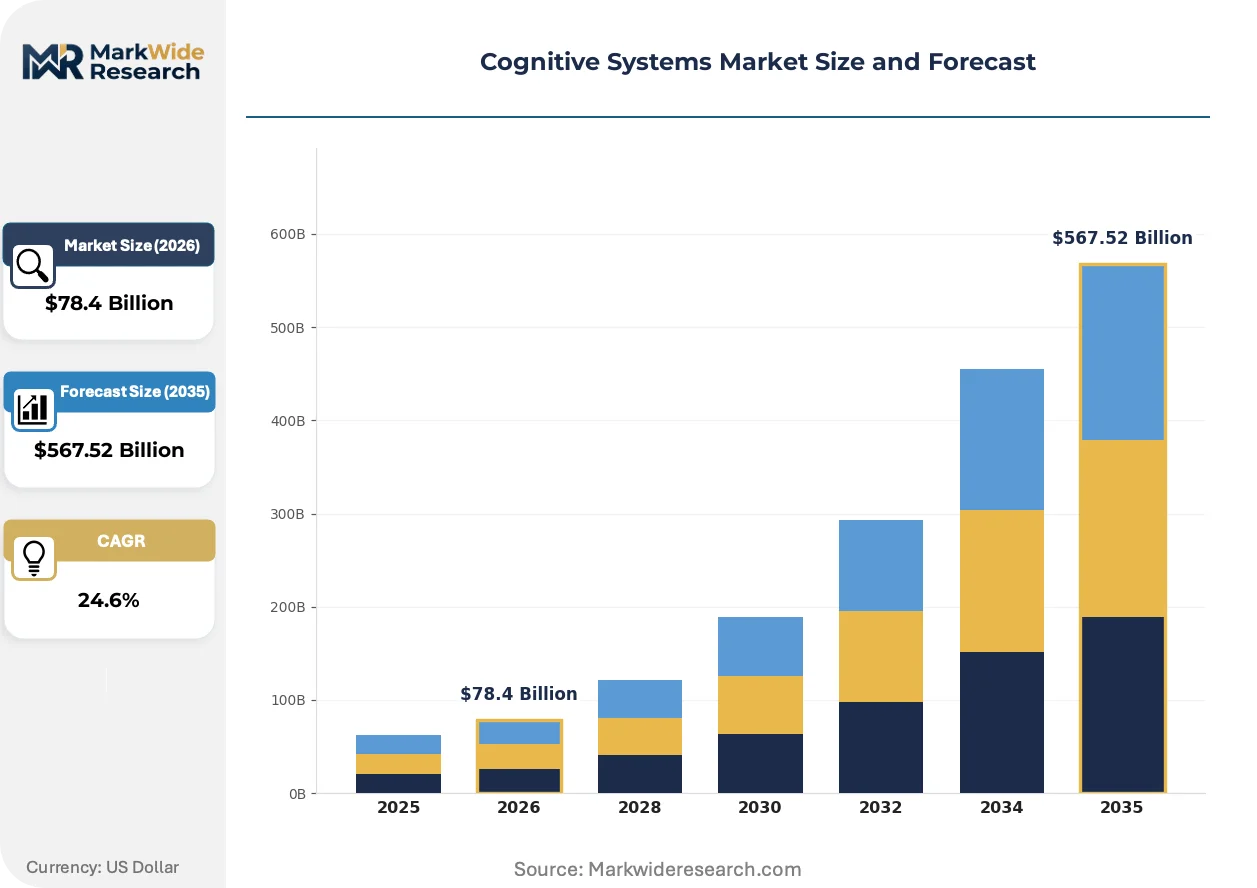
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $567.52 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Machine Learning, Computer Vision, Speech Recognition Application: Virtual Assistants, Fraud Detection, Predictive Analytics, Image Analysis End User: Healthcare, Retail, Finance, Telecommunications Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | NVIDIA, Siemens, IBM, Suffescom Solutions, Nestle, Accenture, Cognizant, Azumo, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Systems Market Strategic Shifts & Innovations
Neural architecture search and automated machine learning are compressing model development timelines, while regulatory jurisdictions race to establish precedents for algorithmic accountability in high-stakes applications.
Foundation model fine-tuning is absorbing enterprise attention as organizations seek domain-specific performance without training costs. Pharmaceutical companies and diagnostic imaging departments adopt parameter-efficient adaptation methods to embed proprietary clinical knowledge. This capability compression is absorbing mid-market vendor margins by reducing dependency on custom model development services.
The EU AI Act's risk classification system imposes documentation burdens on high-stakes healthcare and finance applications. Manufacturers must submit conformity assessments to notified bodies before CE marking authorization. German medical device firms and French diagnostic platforms are restructuring product roadmaps to segregate prohibited AI practices from deployable feature sets.
Enterprise buyers now unbundle cognitive procurement from comprehensive service contracts, preferring modular API consumption with usage-based metering. Systems integrators lose attach-rate leverage as direct cloud marketplace purchasing grows. This pattern is most visible in United States financial services, where risk management teams source fraud detection capabilities through native cloud vendor consoles rather than traditional VAR channels.
Cognitive Systems Market Segmentation
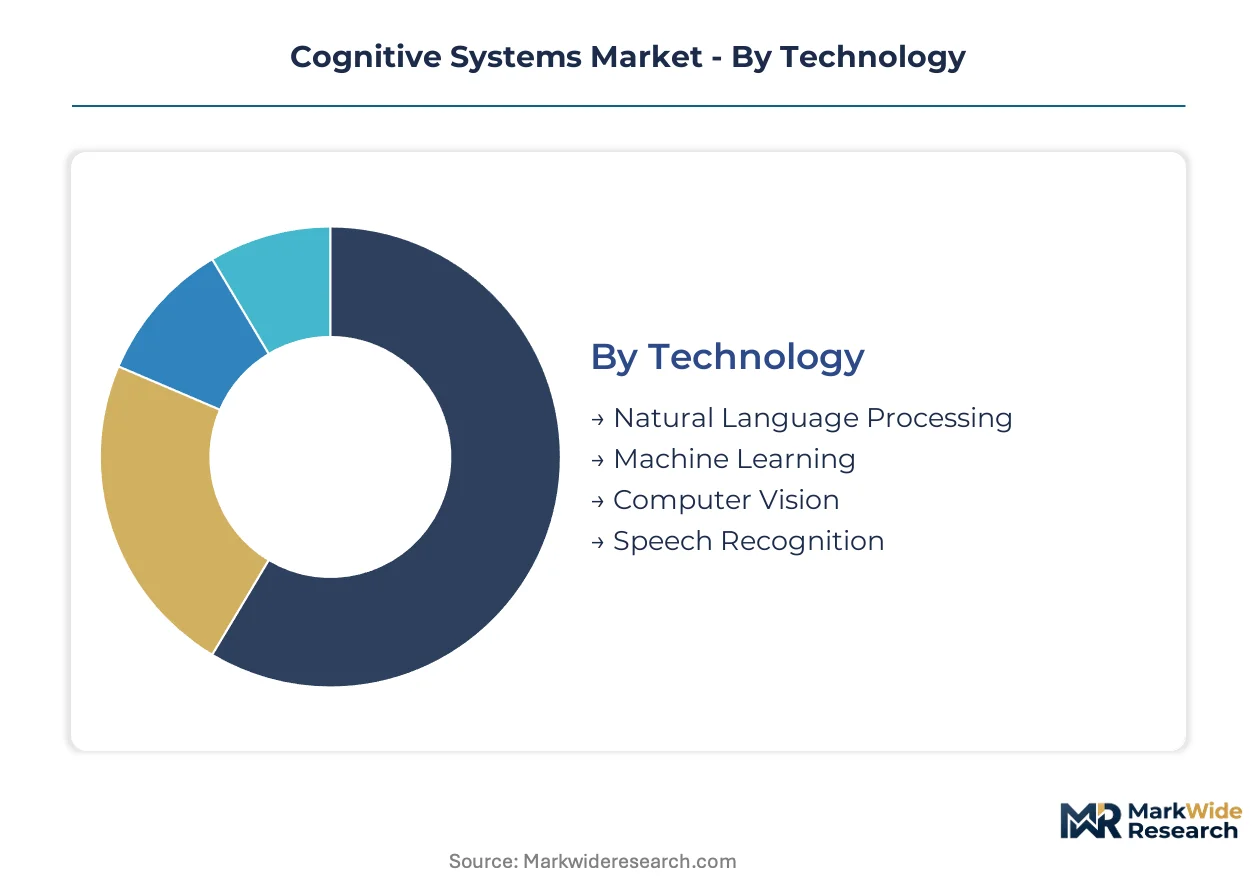
Cognitive systems vendors structure offerings across four intersecting dimensions that determine procurement economics and integration complexity. Technology selection dictates infrastructure requirements, while deployment mode shapes total cost of ownership and latency performance.
Technology:
Upgrade cycles in enterprise cognitive infrastructure favor platforms with backward-compatible model architectures and API stability guarantees.
- Natural Language Processing:Text analysis engines parse unstructured documents, chat transcripts, and clinical notes through transformer architectures. Healthcare providers in the United States deploy NLP for electronic health record summarization, though HIPAA compliance adds middleware complexity. Volume placements concentrate in healthcare documentation; the faster expansion belongs to real-time conversational interfaces.
- Machine Learning:Predictive model development frameworks support supervised and unsupervised learning across tabular and sequential data. Financial institutions in New York and London prioritize ML pipelines for credit risk scoring, with explainability requirements tightening under the EU AI Act. Volume placements concentrate in fraud detection; the faster expansion belongs to automated feature engineering tools.
- Computer Vision:Image classification and object detection systems process visual inputs through convolutional and vision transformer networks. Manufacturing quality control in Germany absorbs high-resolution inspection systems, while autonomous vehicle development in California demands sub-50-millisecond inference latency. Volume placements concentrate in industrial inspection; the faster expansion belongs to medical imaging diagnostics.
- Speech Recognition:Audio-to-text conversion engines handle multilingual transcription with speaker diarization and emotion detection. Call center operators in India and the Philippines integrate speech APIs for real-time agent coaching, though accent diversity strains model accuracy. Volume placements concentrate in customer service automation; the faster expansion belongs to voice biometric authentication.
Procurement patterns favor ML and NLP for their maturity in enterprise toolchains; computer vision and speech recognition gain share fastest in latency-sensitive edge deployments.
Application:
Cost-tier differentiation separates turnkey SaaS implementations from custom model development engagements with professional services attach rates.
- Virtual Assistants:Conversational AI agents handle customer inquiries, appointment scheduling, and technical troubleshooting through multi-turn dialogue management. Retail banks in Singapore and Sydney deploy virtual assistants for 24/7 account services, reducing call center headcount. Volume concentrates in banking customer service; predictive analytics is climbing the fastest.
- Fraud Detection:Real-time transaction scoring identifies anomalous patterns in payment flows and insurance claims. Card networks and neobanks in Brazil and Nigeria prioritize sub-100-millisecond authorization decisions with false positive rates below 2%. Volume concentrates in payment processing; image analysis is gaining share fastest in document forgery detection.
- Predictive Analytics:Forecasting models project demand, equipment failure, and patient deterioration from historical time-series data. Pharmaceutical supply chain teams in Switzerland and Denmark optimize inventory positioning against demand volatility. Volume concentrates in supply chain planning; virtual assistants are expanding most quickly in internal IT helpdesk automation.
- Image Analysis:Diagnostic algorithms flag pathologies in radiology, dermatology, and ophthalmology imaging studies. FDA-cleared devices for diabetic retinopathy screening see concentrated demand from health systems in Texas and Florida seeking CMS reimbursement pathways. Volume concentrates in radiology triage; fraud detection is climbing the fastest in insurance claim documentation verification.
Virtual assistants and fraud detection dominate current procurement volumes; image analysis shows the steepest expansion trajectory as regulatory clearance pathways mature.
End User:
Customer-type segmentation reveals divergent procurement authority structures and compliance sophistication across verticals.
- Healthcare:Hospital systems and diagnostic laboratories deploy cognitive platforms for clinical decision support, medical imaging, and operational optimization. German university hospitals and NHS trusts in England navigate CE marking under the EU AI Act's high-risk system classification. Volume concentrates in diagnostic imaging; retail is expanding most quickly in pharmacy inventory optimization.
- Retail:Merchandising teams and e-commerce operators apply demand forecasting, visual search, and personalized recommendation engines. Fashion retailers in Milan and Stockholm leverage computer vision for virtual try-on and inventoryless showroom concepts. Volume concentrates in recommendation systems; finance is gaining share fastest in buy-now-pay-later credit scoring.
- Finance:Banks, insurers, and asset managers deploy cognitive systems for algorithmic trading, regulatory reporting, and customer onboarding. Swiss private banks and Japanese megabanks invest heavily in natural language processing for KYC document analysis and ESG sentiment monitoring. Volume concentrates in compliance automation; telecommunications is climbing the fastest in network fraud prevention.
- Telecommunications:Network operators apply predictive maintenance, customer churn modeling, and dynamic spectrum allocation. South Korean and Finnish carriers lead in deploying edge cognitive nodes for 5G network slicing optimization. Volume concentrates in network operations; healthcare is expanding most quickly in remote patient monitoring integration.
Healthcare and finance absorb the largest procurement budgets; telecommunications shows the fastest volume growth as 5G infrastructure investment accelerates.
Deployment:
Margin structures vary sharply across deployment modes, with cloud-native consumption capturing recurring revenue while edge hardware sales yield lower attach rates.
- On-Premises:Dedicated infrastructure installations within enterprise data centers satisfy data residency and air-gapped security requirements. Defense contractors and intelligence agencies in the United States mandate on-premise cognitive systems for classified workloads under FISMA and NIST frameworks. Volume concentrates in government and defense; hybrid architectures are expanding most quickly in regulated commercial verticals.
- Cloud-Based:Hyperscaler-hosted cognitive APIs deliver elastic compute with usage-based metering and automatic model updates. Mid-market retailers and professional services firms in Canada and Australia prefer cloud deployment for its elimination of data center capital expenditure. Volume concentrates in commercial SaaS consumption; edge computing is gaining share fastest in manufacturing quality control.
- Hybrid:Split architectures process sensitive data on-premise while leveraging cloud resources for model training and non-critical inference. European multinationals with cross-border data flows deploy hybrid cognitive systems to satisfy GDPR localization requirements while accessing centralized GPU clusters. Volume concentrates in multinational enterprise; on-premises is expanding most quickly in sovereign cloud mandates.
- Edge Computing:Distributed inference nodes embedded in manufacturing equipment, vehicles, and medical devices enable sub-millisecond response without network dependency. Autonomous vehicle developers in California and Bavaria and robotic surgery system manufacturers in Massachusetts prioritize edge cognitive deployment for safety-critical decision loops. Volume concentrates in automotive and robotics; cloud-based is expanding most quickly in generative AI application prototyping.
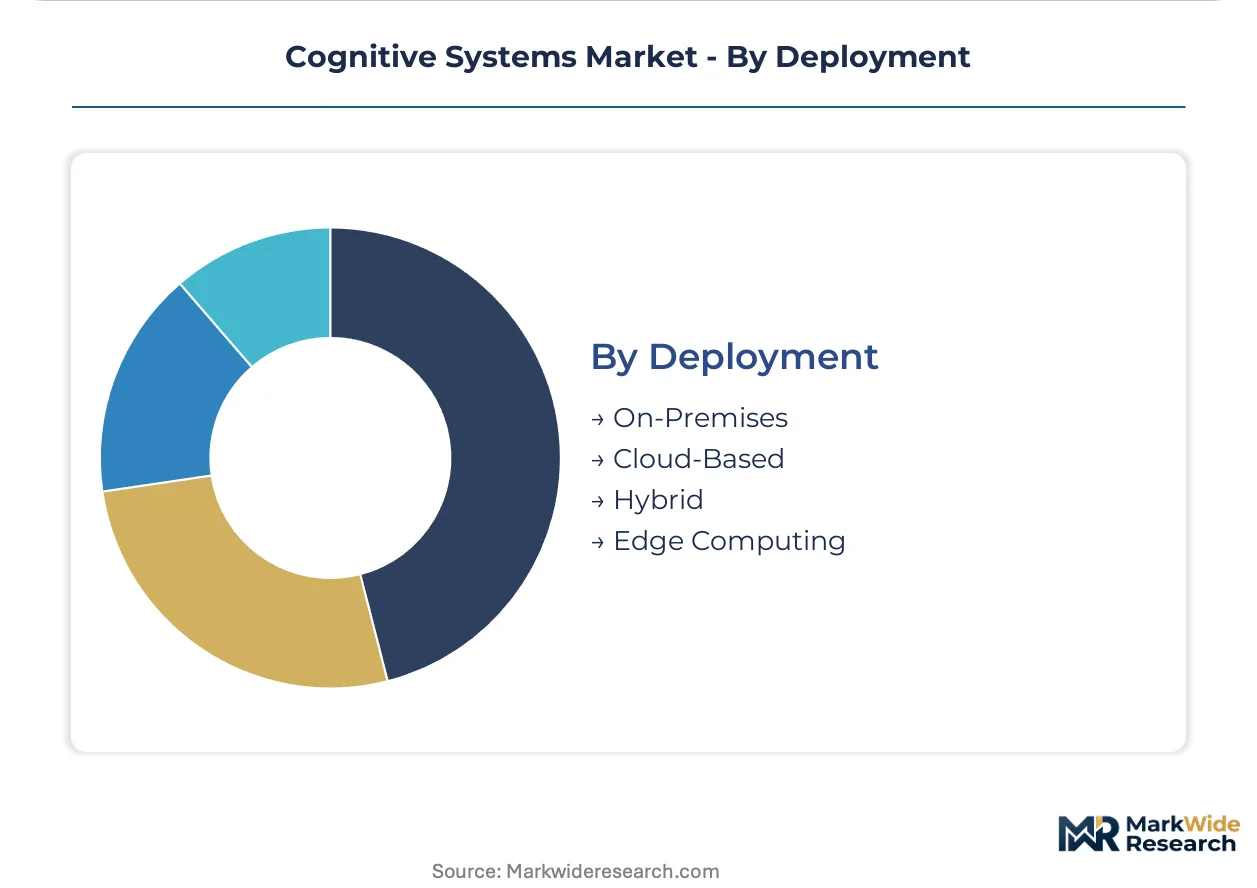
Cloud-based deployment captures the largest revenue pool; edge computing shows the fastest expansion as manufacturing and mobility applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India, Taiwan, and Bavaria concentrate cognitive systems manufacturing and R&D through tax incentives and infrastructure subsidies. These zones anchor regional supply chains while regulatory divergence across FDA, EU AI Act, and BIS frameworks shapes local deployment pathways.
United States
Federal AI R&D spending and defense procurement drive demand for high-performance cognitive infrastructure. FDA predetermined change control plans provide regulatory clarity for iterative medical device algorithms. Boston and Austin clusters concentrate diagnostic imaging platform development.
Germany
Automotive OEMs and industrial machinery manufacturers deploy edge cognitive systems for predictive maintenance. EU AI Act high-risk system classifications force documentation of algorithmic transparency for CE marking. Stuttgart and Munich engineering hubs specialize in manufacturing quality control applications.
India
PLI scheme incentives attract cognitive hardware assembly investments serving South Asian enterprise demand. BIS standards and RBI guidelines shape fintech and telecommunications deployment requirements. Bangalore and Hyderabad IT corridors concentrate NLP and virtual assistant development.
China
MIIT industrial internet initiatives accelerate cognitive system integration in smart manufacturing. GB standards and SAMR algorithmic governance frameworks impose domestic compliance obligations. Shenzhen and Hangzhou technology clusters lead in computer vision and speech recognition commercialization.
United Kingdom
NHS trusts navigate EU AI Act conformity assessments for high-risk diagnostic applications post-Brexit. MHRA guidance on machine learning-based medical devices creates parallel authorization pathways. London financial services firms prioritize fraud detection and compliance automation cognitive platforms.
Cognitive Systems Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across technology stack layers. Market structure shows moderate consolidation at the infrastructure tier with fragmentation in application-layer services. Three archetypes dominate: full-stack hardware-software integrators, cloud-native API providers, and vertical-specialized platform vendors. Competitive moves concentrate on strategic partnerships for model training capacity and portfolio diversification into edge computing hardware.
Within the full-stack integrator tier, NVIDIA anchors high-performance cognitive workload deployment through data center infrastructure dominance. IBM exemplifies vertical specialization archetype with Watson platforms targeting regulated healthcare and financial services sectors. Google occupies the cloud-native API position, embedding cognitive services into subscription tiers to reduce developer deployment friction.
| Leading Market Players |
|---|
| NVIDIA |
| Siemens |
| IBM |
| Suffescom Solutions |
| Nestle |
| Accenture |
| Cognizant |
| Azumo |
| Others |
Cost & Logistics Intelligence
Machine learning engineer concentration in Bangalore and Hyderabad feeds labor-cost differentials that widen pricing-tier spreads between premium custom model development and standardized API consumption tiers.
Pricing Analysis
Short lead-time premiums for GPU cluster allocation separate expedited training contracts from standard queue pricing. Three-tier pricing structure across premium, standard, and economy levels aligns with ISO/IEC 23053 certification status and vertical integration depth. Price differentiation stems from inference latency guarantees and after-sales model fine-tuning support. Enterprise healthcare buyers show lowest price sensitivity due to FDA compliance requirements, while mid-market retailers face acute margin pressure from cloud-native alternatives.
Supply Chain Analysis
Regional distribution centers in Singapore and Frankfurt anchor hub-and-spoke patterns for cognitive hardware delivery. Taiwan and South Korea foundries supply high-throughput processors, while Chinese manufacturers dominate edge inference module assembly. Taiwan Strait geopolitical exposure concentrates single-source vulnerability for neural network training infrastructure. Distribution runs through hyperscaler marketplaces and systems integrator channels serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification erects a cost-of-compliance moat that favors incumbent vendors with documented conformity assessment capacity and notified body relationships.
For Market Incumbents: Deploy predetermined change control plan documentation as a competitive barrier against unvalidated entrants. IBM and NVIDIA anchor positions through Watson vertical specialization and full-stack hardware-software integration. GPU supply concentration in Taiwan-South Korea creates procurement leverage for incumbents with long-term foundry agreements. Channel control through cloud marketplace listings reduces systems integrator attach-rate erosion. For New Entrants and Emerging Players: Direct cloud marketplace routes bypass traditional VAR channels and reduce customer acquisition friction. Edge manufacturing applications in Germany and India present white-space openings outside hyperscaler-dominated cloud tiers. Parameter-efficient fine-tuning tools for pharmaceutical clinical knowledge embedding offer the most penetrable application layer. Target mid-market healthcare providers in Texas and Florida seeking CMS reimbursement pathway support. For Investors and Strategic Acquirers: Re-rating potential sits with vertical-specialized platform vendors given FDA predetermined change control plan adoption acceleration. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than raw model performance. Acquisition targets should show documented EU AI Act conformity assessment progress and established notified body relationships. Watch FDA 510(k) clearance velocity for diagnostic imaging platforms as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Predetermined Change Control Plan Submission | FDA documentation accelerates iterative algorithm updates for diagnostic imaging platforms. |
| Cloud-Native API Marketplace Listing | Hyperscaler integration reduces deployment friction for developer teams in retail. |
| Edge Computing Hardware Partnership | Autonomous vehicle developers in California demand sub-50-millisecond inference nodes. |
| Vertical Specialization Acquisition | Watson healthcare focus demonstrates regulated sector premium pricing power. |
| EU Notified Body Relationship Investment | CE marking throughput limits create bottleneck for high-risk healthcare applications. |
Research Approach
Independent corroboration across chief technology officers, healthcare procurement committees, and platform engineering leads underwrites the qualitative findings. Primary interviews with biomedical engineers, GPO contracts managers, and integration specialists combined with secondary validation from FDA 510(k) filings, EMA submission databases, and hyperscaler capex disclosures. Bottom-up segmentation modeling and top-down macroeconomic anchoring ensure cross-verified outputs.
Comparable-period anchoring to historical regulatory authorization timelines calibrated the forecast window across the analysis window. Segmentation dimensions modeled include deployment architecture, organization scale, vertical regulatory cluster, and integration complexity tier. CAGRs derive from neural network training cost curves, cloud API consumption trajectories, and edge hardware shipment patterns. Inference latency benchmarks and model accuracy thresholds inform technology adoption assumptions.
The model holds under stable regulatory authorization pathways; deviation in FDA guidance interpretation or EU notified body capacity would shift commercialization timelines. Forecasts reflect documented assumptions about algorithmic transparency standards and liability framework evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Text-To-Speech (TTS) Market
Artificial Intelligence (AI)
AI Voice Cloning Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
AI Dubbing Software Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Embedded Intelligence Market