
 Global Artificial Grass Market | 2026-2036
Global Artificial Grass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Grass Market Foresight
Polyethylene monofilament cross-section engineering is fragmenting the traditional tufting technology stack, splitting manufacturing between flat yarn specialists and textured yarn producers. TenCate Grass leverages its Dutch R&D campus to dominate FIFA-certified pitch systems across European stadiums. CCGrass sustains cost leadership through integrated extrusion-tufting-coating capacity at its Jiangsu manufacturing complex. Shaw Industries Group anchors North American distribution through its specialty retail and contractor channel networks.
Artificial grass consists of synthetic fiber tufts stitched into perforated polyurethane or latex backing layers, typically installed over compacted aggregate bases with optional infill materials such as silica sand or thermoplastic elastomers to stabilize blade structure and simulate soil resilience. The product serves commercial landscaping, sports facilities, municipal recreation areas, and residential yards where natural grass maintenance proves impractical due to climate, usage intensity, or water constraints. Polyethylene fibers lead volume shipments for landscaping applications due to softer hand feel and UV stability, while nylon retains premium positioning in high-traffic sports fields where resilience under cleat abrasion determines replacement cycles. Infill installation types command higher upfront project values but deliver longer performance warranties, shifting margin pools toward system integrators capable of substrate preparation and drainage engineering.
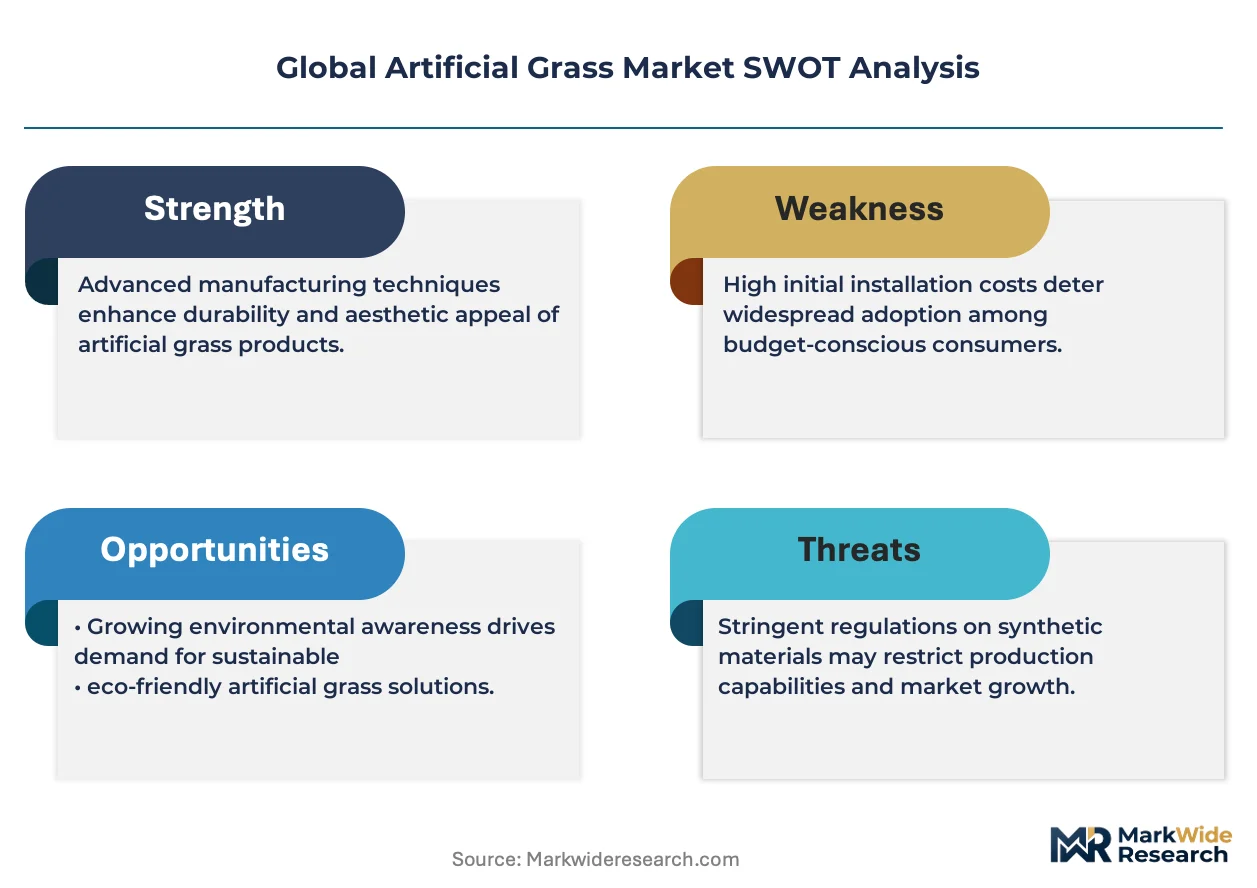
REACH regulates chemical content in European turf backing adhesives and infill granules, forcing reformulation away from legacy styrene-butadiene rubber toward EPDM and thermoplastic alternatives. FIFA Quality Programme and EPA stormwater runoff guidelines in the United States shape product certification and site eligibility for public funding. ISO 9001 quality management and ISO 14001 environmental management frameworks govern supplier qualification for municipal tenders across Australia and the Middle East. Stakeholders must monitor evolving microplastic discharge regulations and infill migration standards, as these will determine which product architectures retain market access and which face retrofit obligations or procurement exclusion.
Market Dynamics
Polyethylene monofilament engineering is fragmenting traditional tufting technology, splitting manufacturing between flat yarn specialists and textured yarn producers while REACH compliance and FIFA Quality Programme certification tighten material standards across European and Middle Eastern procurement.
Growth Catalysts
- REACH chemical reformulation mandates:European ECHA requirements for crumb rubber infill alternatives are accelerating EPDM and thermoplastic elastomer adoption, opening procurement pathways for compliant system integrators.
- Sun Belt drought restrictions:Municipal water curtailments across California, Arizona, and Texas are forcing residential lawn replacement, concentrating demand in states with the most severe conservation mandates.
- FIFA Quality Programme certification:Stadium pitch standards in Germany, the United Kingdom, and Australia are mandating certified synthetic turf systems, locking in premium specification tiers for qualified suppliers.
Market Restraints
- Petroleum-based input volatility:Polyethylene and polyurethane backing adhesive costs fluctuate with crude oil derivatives, compressing margin predictability for extrusion-tufting-coating integrated manufacturers.
- EPDM infill supply concentration:Thermoplastic elastomer granule production clusters in select Asian petrochemical corridors, creating single-source vulnerability for European system integrators seeking REACH-compliant alternatives.
- Microplastic discharge uncertainty:Pending EU regulatory frameworks on synthetic fiber runoff threaten retrofit obligations for installed base maintenance, chilling long-dated municipal procurement cycles.
Strategic Opportunities
- Substrate preparation capability gap:Drainage engineering and aggregate base construction expertise is scarce outside established sports facility contractors, creating white space for landscape contractors to upskill into system integration.
- EPA stormwater guideline alignment:United States federal eligibility criteria for public recreation funding are tightening permeability standards, advantaging suppliers with pre-certified drainage-optimized architectures.
- Residential landscaping penetration:Professional installer networks remain underdeveloped in Texas and Florida compared to California, offering channel expansion runway for contractors with irrigation-to-turf conversion expertise.
Industry Challenges
- Multi-certification timeline compression:Simultaneous ISO 9001, ISO 14001, and FIFA Quality Programme audits strain quality management staffing at mid-cap manufacturers bidding Australian and Middle Eastern municipal tenders.
- Legacy latex-to-polyurethane adhesive transition:Backing reformulation for enhanced UV stability requires coating line reconfiguration, demanding capital deployment while maintaining throughput on existing tufting assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Grass Market |
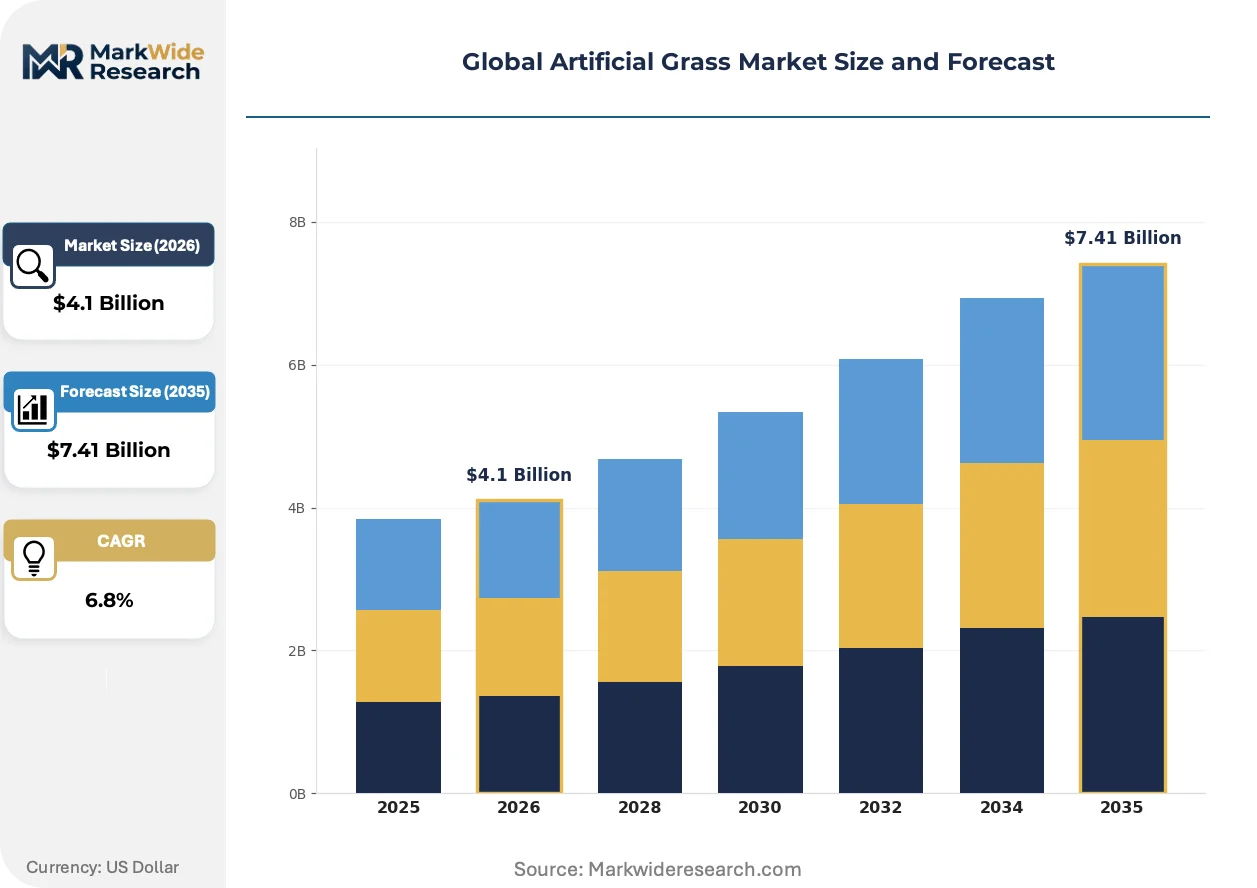
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon, Polypropylene, Polyethylene, Others Application: Sport Fields, Residential Landscaping, Commercial Landscaping, Playgrounds Installation Type: Glue Down, Infill, Loose Lay, Hybrid End User: Residential, Commercial, Sports Facilities, Municipal |
| Companies Covered | Shaw Industries Group, Tarkett, TenCate Grass, CCGrass, SportGroup, Act Global, SIS Pitches, TigerTurf, ForeverLawn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Grass Market Shifts & Advancements
Digital substrate modeling and virtual performance simulation are compressing specification-to-installation cycles, while regulatory chemistry mandates and buyer procurement centralization are restructuring competitive position around compliance documentation rather than unit economics alone.
Cross-section engineered monofilament yarn is virtualizing traditional flat-turf specification. Textured polyethylene fibers with engineered curvature profiles now dominate FIFA-certified pitch tenders across German and Australian stadium procurement. These architectures reduce infill migration and stabilize cleat interaction, compressing replacement cycles for high-traffic fields while extending performance warranty terms that system integrators can monetize.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber infill are forcing granular reformulation across European municipal recreation tenders. ECHA enforcement timelines are compressing supplier qualification windows, advantaging manufacturers with pre-validated EPDM and thermoplastic elastomer supply chains. German sports facility procurement offices are now excluding styrene-butadiene rubber submissions from technical evaluation, locking in chemistry-compliant architectures for the 2026-2035 replacement cycle.
Specification authority is consolidating from landscape architects toward municipal procurement offices with embedded technical compliance teams. Australian council tender evaluation now weights ISO 14001 environmental management certification above historical supplier relationships, displacing incumbent contractors lacking documented chain-of-custody. Texas and Arizona water district rebate programs are accelerating this pattern, requiring pre-approved product lists that filter residential installer participation.
Global Artificial Grass Market Segmentation
Segmentation in artificial grass markets separates specification tiers that carry radically different margin profiles and compliance burdens. Installation complexity and infill chemistry requirements create distinct service revenue streams that reshape competitive position across product categories.
Product Type:
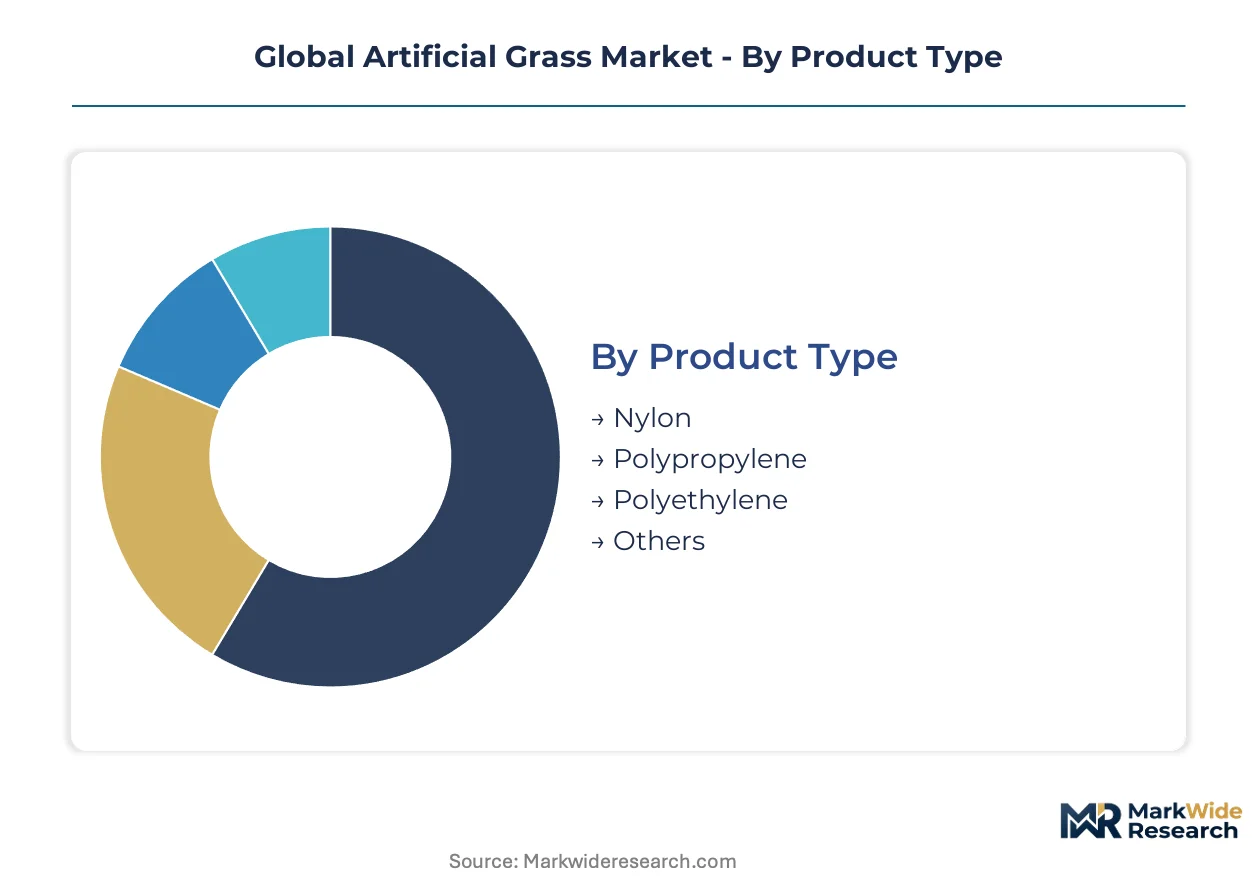
After-sales-service intensity varies sharply by fiber chemistry, with nylon demanding specialized repair protocols and polyethylene requiring UV-monitoring maintenance contracts.
- Polyethylene:Soft-hand monofilament fibers dominate landscaping applications across California and Arizona residential markets. Drought-driven water restrictions in the Sun Belt accelerate replacement of natural lawns, concentrating procurement with contractors offering irrigation-to-turf conversion packages.
- Nylon:High-tenacity fibers withstand cleat abrasion in German and Australian stadium pitches certified under FIFA Quality Programme standards. Premium positioning reflects extended replacement cycles, though petroleum-based input volatility compresses margin predictability for extrusion-integrated manufacturers.
- Polypropylene:Stiffer polymer suited to low-traffic commercial installations and cost-sensitive municipal tenders.
- Others:Specialty blends including hybrid fiber constructions and experimental bio-based polymers.
By volume, polyethylene leads. By growth pace, nylon is ahead.
Application:
Cost tier separation defines this category, with sports facilities commanding system-level pricing and residential landscaping competing on installed-square-meter economics.
- Residential Landscaping:Sun Belt water curtailments in California, Arizona, and Texas force lawn replacement, concentrating demand in states with severe conservation mandates. Professional installer networks remain underdeveloped in Texas and Florida compared to California, creating channel expansion runway for irrigation specialists.
- Sport Fields:FIFA-certified pitch systems across German, United Kingdom, and Australian stadiums mandate textured yarn architectures with engineered curvature profiles. These specifications reduce infill migration and stabilize cleat interaction, extending performance warranties that system integrators monetize.
- Commercial Landscaping:Corporate campus and retail exterior applications prioritizing visual uniformity over performance metrics.
- Playgrounds:Safety-focused installations requiring critical fall height certification and cushioned underlay systems.
Commercial landscaping generates the highest transaction volumes. Sport fields capture the steepest expansion trajectory.
Installation Type:
Customer type stratification structures this dimension, with municipal sports facilities demanding certified system integration and residential buyers accepting simpler loose-lay alternatives.
- Infill:Silica sand or thermoplastic elastomer stabilization delivers longer performance warranties, shifting margin pools toward system integrators with substrate preparation and drainage engineering capabilities. REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber infill are forcing EPDM and thermoplastic elastomer adoption across European municipal recreation tenders.
- Glue Down:Polyurethane adhesive bonding suits permanent commercial installations requiring maximum dimensional stability.
- Loose Lay:Temporary or seasonal deployment with minimal site preparation, common in event and exhibition contexts.
- Hybrid:Combined mechanical fastening and adhesive systems for high-wind or high-traffic environments.
Infill dominates project values. Hybrid configurations are climbing the fastest.
End User:
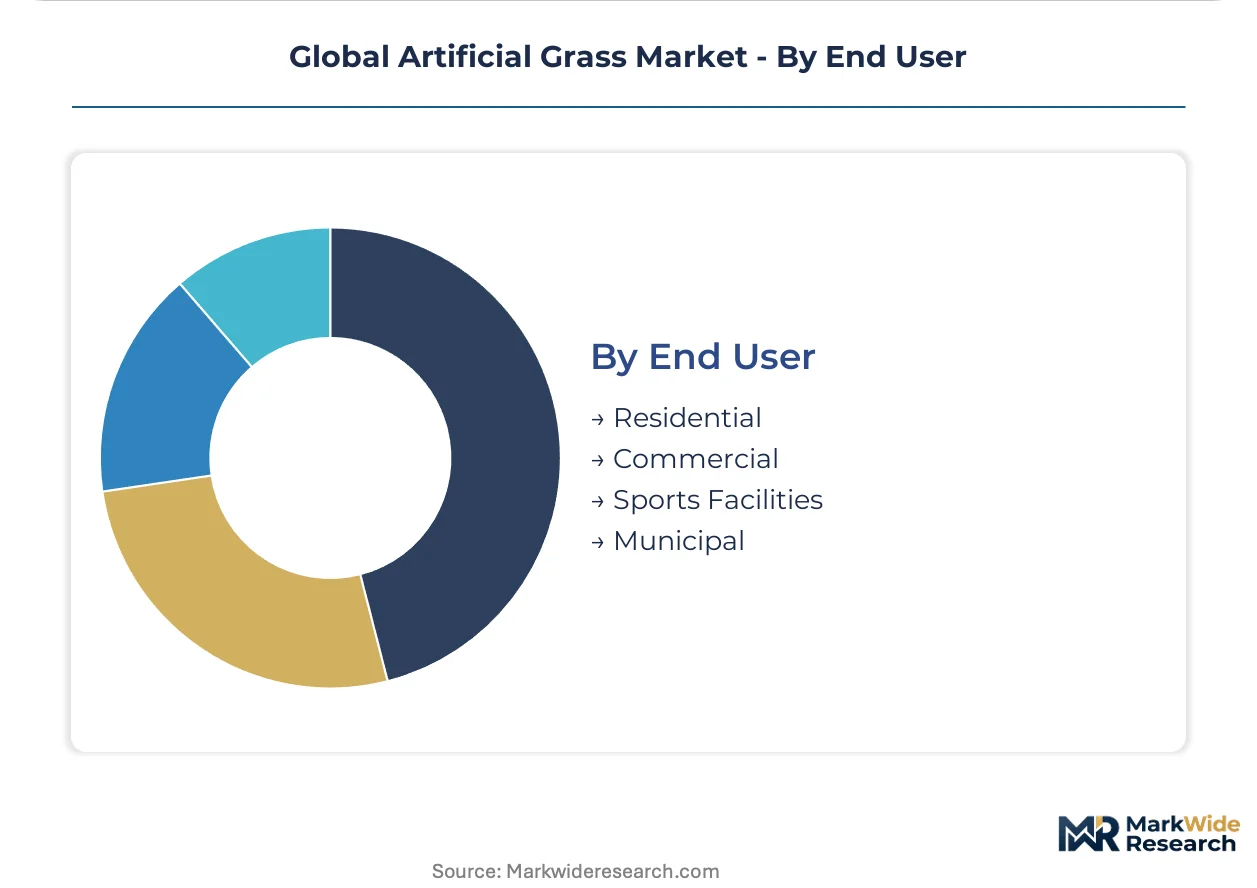
Supply concentration patterns differentiate this category, with municipal procurement offices consolidating specification authority away from landscape architects.
- Municipal:Australian council tender evaluation now weights ISO 14001 environmental management certification above historical supplier relationships, displacing incumbent contractors lacking documented chain-of-custody. Texas and Arizona water district rebate programs require pre-approved product lists that filter residential installer participation.
- Sports Facilities:German sports facility procurement offices exclude styrene-butadiene rubber submissions from technical evaluation, locking in chemistry-compliant architectures for the replacement cycle.
- Residential:Individual homeowners responding to rebate programs and aesthetic preferences.
- Commercial:Property developers and facility managers optimizing maintenance cost reduction.
Municipal tenders lead in contract scale. Sports facilities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese extrusion-integrated manufacturers supply the bulk of polyethylene monofilament yarn to European system integrators and North American distributors, with Jiangsu province anchoring export capacity for REACH-compliant thermoplastic elastomer infill formulations.
United States
Sun Belt drought restrictions in California, Arizona, and Texas accelerate residential lawn replacement as municipal water curtailments tighten. EPA stormwater runoff guidelines shape eligibility for federal recreation funding. Texas and Florida installer networks remain underdeveloped relative to California, creating channel expansion runway for irrigation-to-turf conversion specialists.
Germany
Municipal sports facilities across Bavaria and North Rhine-Westphalia expand synthetic turf procurement for football and rugby pitches. ECHA REACH Annex XVII enforcement excludes styrene-butadiene rubber infill from technical evaluation, locking in EPDM and thermoplastic elastomer architectures. The Rhine-Ruhr industrial corridor concentrates backing adhesive reformulation capacity for UV-stabilized polyurethane systems.
Australia
Council tender evaluation in New South Wales and Victoria weights ISO 14001 environmental management certification above historical supplier relationships. TGA-aligned state procurement frameworks govern playground safety installations requiring critical fall height certification. Melbourne and Sydney anchor demand for FIFA Quality Programme-certified stadium pitch systems.
United Kingdom
Sports facility procurement offices in Greater London and the Midlands mandate certified synthetic turf for municipal recreation tenders. UK-specific adaptations of REACH compliance frameworks regulate crumb rubber infill migration standards. The Manchester-Liverpool corridor concentrates drainage engineering expertise for substrate preparation contracts.
China
Jiangsu province maintains integrated extrusion-tufting-coating capacity serving export markets with cost-optimized polyethylene yarn production. MIIT industrial standards and dual carbon goals shape domestic manufacturing efficiency mandates. The Yangtze River Delta cluster dominates thermoplastic elastomer granule supply for European REACH-compliant system integrators.
Global Artificial Grass Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Distribution-anchored conglomerates leverage retail and contractor networks to capture residential landscaping volume, while extrusion-integrated manufacturers compete on yarn cost and compliance documentation. Three archetypes dominate: vertically integrated petrochemical-to-turf producers, specification-driven system integrators with substrate preparation capabilities, and pure-play yarn specialists supplying certified tufting operations. Capacity expansion and strategic partnerships represent the dominant competitive moves, with M&A activity concentrating in European REACH-compliant infill formulation assets.
Among Dutch R&D-anchored specialists, TenCate Grass occupies a position exemplifying FIFA-certified pitch system dominance across European stadium procurement. Jiangsu-based CCGrass represents the extrusion-integrated cost leadership archetype through captive yarn-to-coating manufacturing. Shaw Industries Group anchors the North American distribution-control tier, leveraging specialty retail and contractor channel networks to capture Sun Belt residential replacement demand. These three entities collectively illustrate the geographic and capability segmentation structuring competitive position in polyethylene monofilament supply.
| Leading Market Players |
|---|
| Shaw Industries Group |
| Tarkett |
| TenCate Grass |
| CCGrass |
| SportGroup |
| Act Global |
| SIS Pitches |
| TigerTurf |
| ForeverLawn |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese extrusion-tufting facilities is compressing polyethylene yarn pricing while simultaneously pressuring European system integrators to absorb REACH-compliant reformulation costs. This utilization asymmetry between Jiangsu manufacturing clusters and German coating operations fragments margin capture across the value chain.
Pricing Analysis
Flat-yarn legacy systems trade at substantial discounts to textured monofilament architectures engineered for FIFA-certified pitches. Pricing stratifies across premium, standard, and economy tiers with certification grade and substrate preparation bundling as primary differentiation drivers. Cost compression in polyethylene fiber tiers is intensifying because petroleum derivative volatility feeds directly into extrusion-integrated manufacturer margins. Residential landscaping buyers in Texas and Florida exhibit highest price sensitivity, while German municipal sports facilities prioritize warranty terms over unit economics.
Supply Chain Analysis
Extended payment terms from European system integrators to Jiangsu yarn suppliers have become standard practice, stretching working capital requirements across the procurement cycle. Manufacturing gravity centers on China, the Netherlands, and the United States, with raw material dependencies spanning Saudi polyethylene resin, German polyurethane adhesive precursors, and Malaysian EPDM granule feedstock. Single-source vulnerability in thermoplastic elastomer infill production creates procurement risk for REACH-compliant European tenders. Distribution runs through specialty contractor networks in North America and direct stadium procurement offices across Germany and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from xeriscaping and drought-tolerant natural turf varieties as water restrictions ease in select Sun Belt municipalities. Defense requires locking in specification authority before alternative landscaping solutions capture municipal procurement mindshare.
For Market Incumbents: Harden specification control by embedding FIFA Quality Programme and ISO 14001 certification into municipal tender pre-qualification criteria. Deepen backward integration into EPDM infill formulation to offset REACH-driven supply concentration risk. Prioritize drainage engineering capability acquisition to capture substrate preparation margins that pure-play yarn manufacturers cannot access.
For New Entrants and Emerging Players: Texas residential installer networks remain thin relative to California penetration, offering channel buildout runway for irrigation-to-turf conversion specialists. Target professional landscaping contractor certification programs as the most penetrable entry vector, pairing product supply with installation training to differentiate from commodity yarn distributors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among system integrators with multi-year maintenance contracts on municipal sports facilities, suggesting superior cash-flow quality versus project-dependent yarn manufacturers. Acquisition focus should center on REACH-compliant infill formulation assets with validated ECHA documentation. Monitor ECHA enforcement timelines on microplastic discharge as the critical inflection signal for retrofit obligation exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPDM Infill Production | REACH Annex XVII compliance locks in chemistry-compliant architectures for European municipal tenders. |
| Drainage Engineering Capability Acquisition | Substrate preparation expertise captures margin pools shifting toward system-level project delivery. |
| FIFA Quality Programme Certification Investment | Stadium pitch standards in Germany and Australia mandate certified suppliers for public funding eligibility. |
| Professional Installer Network Expansion | Underdeveloped contractor channels in Texas and Florida offer residential penetration runway. |
| ISO 14001 Environmental Management Certification | Australian council tender evaluation weights documented chain-of-custody above historical supplier relationships. |
Research Methodology
Desk research of customs trade databases, ECHA regulatory filings, and FIFA certification registries preceded structured interviews with municipal procurement officers, sports facility maintenance directors, artificial grass manufacturing plant managers, and landscape contractor business owners. Primary fieldwork across Jiangsu manufacturing clusters, German industrial corridors, and Sun Belt distribution networks validated secondary data on capacity utilization and pricing dynamics. Bottom-up shipment analysis triangulated against top-down market sizing from petrochemical derivative consumption patterns.
Forecast assumptions held fixed the current REACH Annex XVII enforcement trajectory and EPA stormwater guideline implementation pace while varying drought restriction severity and petroleum price volatility scenarios. Segmentation modeling spanned fiber chemistry, installation complexity, application end-use, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections tied to municipal water curtailment mandates and stadium replacement cycle timing.
Practitioners should monitor ECHA microplastic discharge proposal advancement and Sun Belt drought restriction relaxation for early signals of demand trajectory revision. Macroeconomic, regulatory, or technological deviation would prompt forecast reassessment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Inflatable Pool Market
Outdoor & Sports
Fire Pits Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Camping Utensils Market
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
Mexico Fishing Reels Market
Outdoor & Sports
Golf Stand Bag Market
Outdoor & Sports
Sleeper Pads Market
Outdoor & Sports
Fishing Reels Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Garden Solar Lights Market
Outdoor & Sports
Walkbehind Lawnmower Market