
 Snow Chain Market | 2026-2036
Snow Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Snow Chain Market Analytics
Subscription-based seasonal fitting and storage services is recalibrating how consumers acquire snow chains, shifting transactions from one-time hardware purchases to recurring service relationships. Thule Group leverages its retail network and brand recognition to anchor premium positioning in European markets. RUD Ketten sustains engineering leadership through intensive R&D in alloy formulations for extreme-load applications. Peerless Industrial Group dominates North American private-label and fleet supply channels through manufacturing scale.
Snow chains are traction devices constructed from hardened steel, textile composites, or hybrid materials, designed to wrap around vehicle tires to enhance grip on ice and packed snow through mechanical engagement with the road surface. Metal chains remain the dominant product type due to regulatory acceptance and proven performance in severe conditions, though composite chains are gaining share where weight reduction and corrosion resistance matter. Passenger vehicles constitute the largest vehicle type segment by volume, while commercial vehicles generate higher per-unit margins due to specialized fitment requirements and fleet compliance mandates.
EU member states enforce winter equipment regulations through national transport authorities under the EU Roadworthiness Directive, while the United States lacks federal mandate but sees state-level chain requirements in California, Colorado, and Oregon enforced by DOT and state patrol agencies. ISO 9001 and TÜV certification frameworks govern product testing and market access, creating compliance barriers for uncertified suppliers. Stakeholders must monitor evolving material standards and regional enforcement intensity to align production portfolios with where legal obligation, not preference, drives purchase behavior.
Market Dynamics
The Snow Chain Market faces structural recalibration as EU F-Gas Regulation and tightening CO2 standards force manufacturers toward lighter composite materials, while Alpine municipalities expand municipal fleet procurement under stricter mountain pass mandates.
Growth Catalysts
- Alpine Municipal Procurement:Fleet operators across Germany, Austria, and Switzerland are expanding winter readiness budgets to comply with mountain pass mandates. This institutional demand creates predictable volume commitments.
- EU F-Gas Regulation:Transport equipment CO2 standards pressure manufacturers to reduce vehicle weight. Composite snow chains gain regulatory preference where metal chains add unacceptable payload.
- Composite Material R&D:Hardened textile formulations now achieve TÜV certification thresholds previously reserved for steel. This technical validation opens passenger vehicle segments to corrosion-resistant alternatives.
Market Restraints
- Steel Input Volatility:Hardened alloy prices fluctuate with European energy costs. Manufacturers lack long-term hedging instruments for specialized metallurgical inputs.
- Certification Concentration:TÜV and ISO 9001 testing capacity concentrates in Germany and Austria. Uncertified suppliers face 12-18 month queue times for market access documentation.
- All-Season Tire Substitution:Three-peak mountain snowflake rated tires satisfy regulatory requirements in milder winter zones. This technical substitute erodes discretionary chain purchases in urban corridors.
Strategic Opportunities
- Nordic Fleet Electrification:Battery electric commercial vehicles in Norway and Sweden require weight-minimized traction solutions. Composite chains align with range-preservation priorities.
- Subscription Fitting Services:Seasonal storage and installation subscriptions convert one-time hardware transactions into recurring revenue. Thule Group's retail network demonstrates channel viability.
- REACH-Compliant Coatings:EU chemical registration requirements favor domestic coating suppliers. Corrosion-resistant surface treatments create differentiation against Asian imports.
Industry Challenges
- Composite Welding Expertise:Textile-to-metal hybrid construction requires polymer engineers with automotive safety system experience. This talent pool concentrates in Stuttgart and Munich industrial clusters.
- Multi-Jurisdiction Certification:Swiss OEKO-TEX requirements diverge from German TÜV protocols. Product portfolios require parallel testing streams for cross-border market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snow Chain Market |
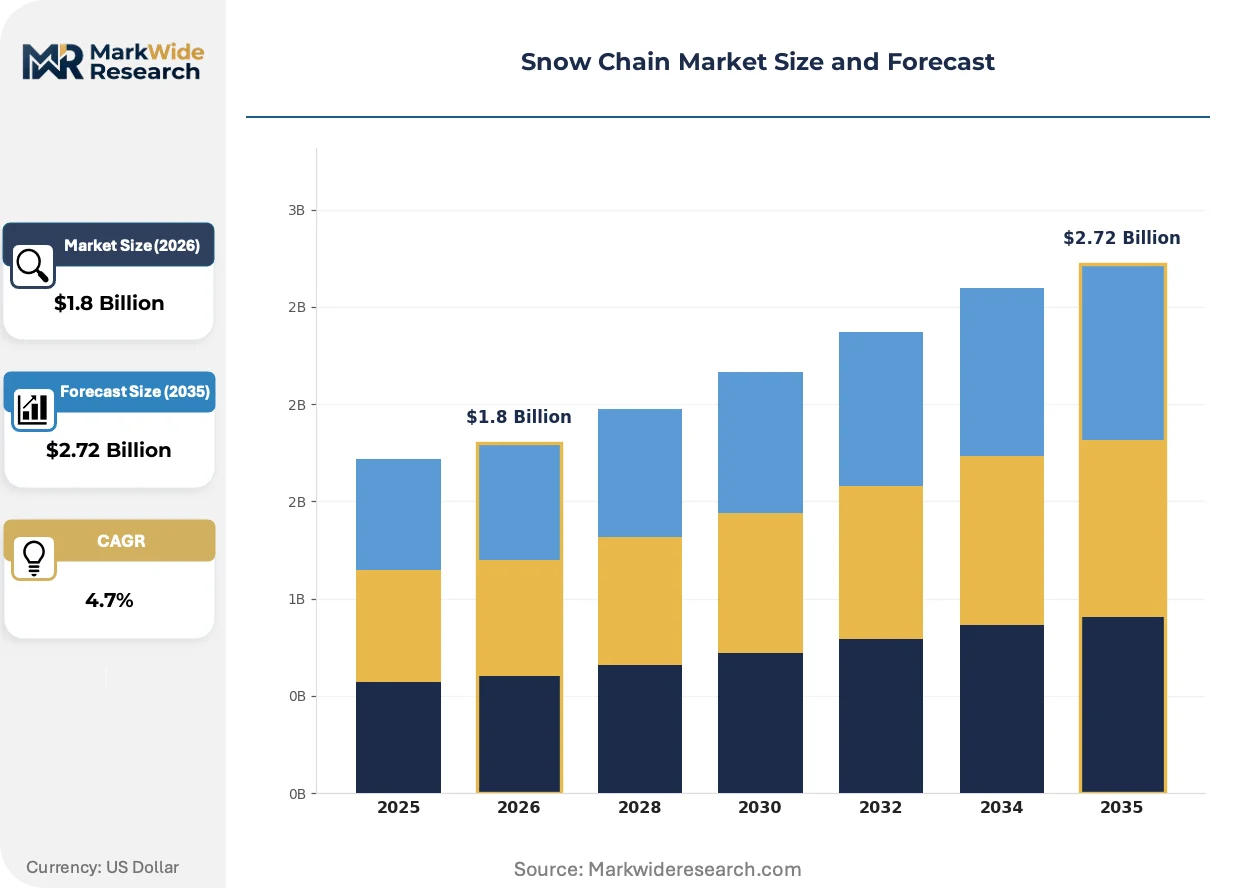
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Chains, Fabric Chains, Composite Chains, Automatic Chains Vehicle Type: Passenger Vehicles, Trucks, SUVs, Commercial Vehicles Installation Type: Manual, Automatic, Semi-Automatic, Quick-Install Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Distributors |
| Companies Covered | Thule Group, RUD Ketten, Peerless Industrial Group, Pewag Group, Maggi Group, Weissenfels, Security Chain Company, Laclede Chain Manufacturing, Konig, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snow Chain Market Evolving Landscape
Material science advances and regulatory stringency are compressing traditional metal-dominant supply structures while opening service-based revenue models. Three developments warrant particular attention.
Self-tensioning textile composite chains is decentralizing fitment authority away from specialized installers. Alpine rental fleets in Austria and Switzerland now deploy tool-free installation systems that reduce roadside fitting time from fifteen minutes to under three. This capability compression enables direct-to-consumer distribution through automotive retailers rather than winter equipment specialists.
The EU F-Gas Regulation's transport equipment amendments are accelerating composite adoption timelines. Manufacturers must demonstrate CO2-equivalent weight reductions across vehicle accessory portfolios to maintain type approval. Passenger vehicle OEMs in Germany now specify certified composite chains as factory-approved equipment, shifting procurement influence upstream to vehicle assemblers.
Fleet procurement departments are unbundling hardware ownership from seasonal service obligations. Municipal operators in Bavaria and Tyrol now contract fitting, storage, and liability coverage through three-year service agreements. This consumption-pattern shift compresses distributor margins while extending manufacturer cash conversion cycles through recurring revenue recognition.
Snow Chain Market Segmentation
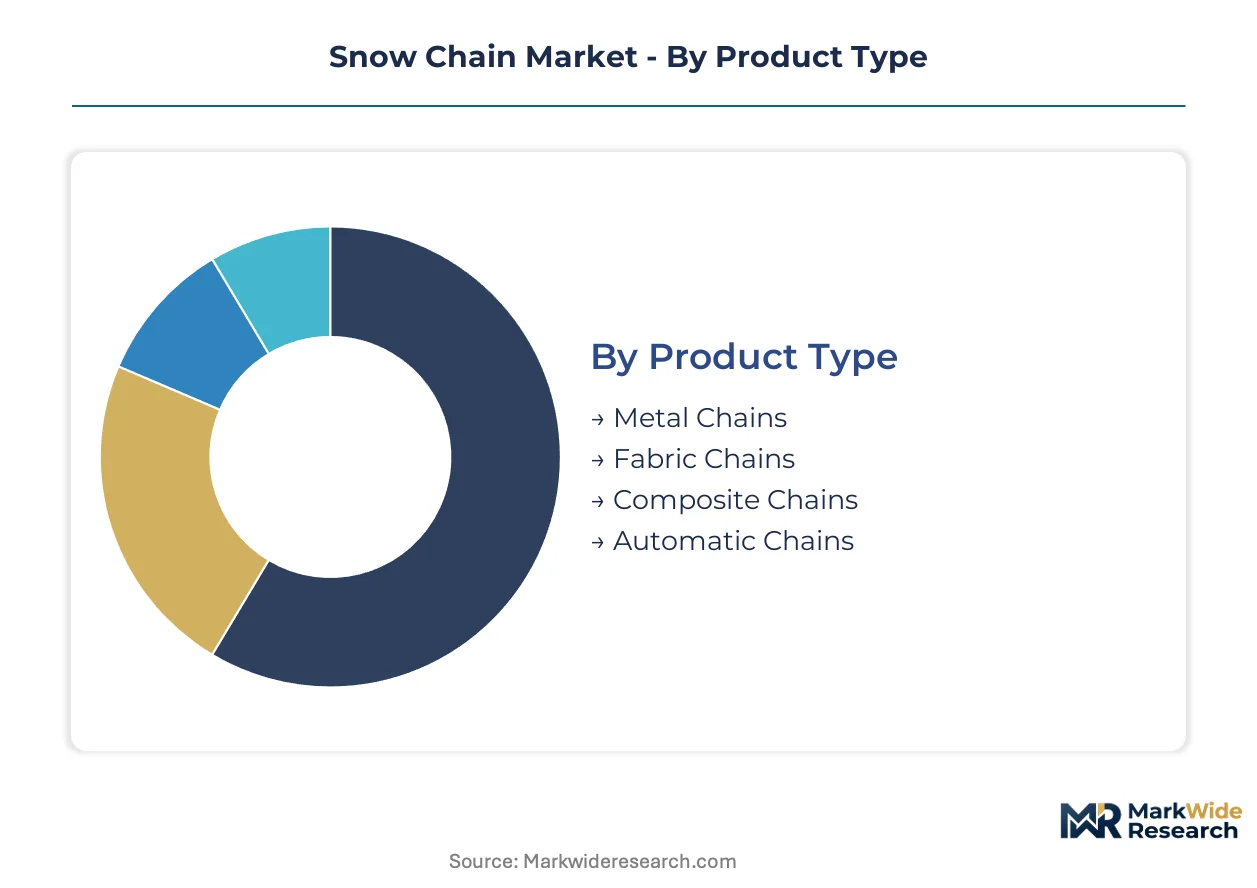
Snow chain procurement divides sharply between regulatory-mandated fleet purchases and discretionary consumer acquisitions. Certification requirements vary dramatically across product categories, with TÜV and ISO 9001 thresholds determining market access for institutional buyers.
Product Type:
TÜV certification protocols differentiate acceptance standards across material compositions, with steel derivatives facing distinct testing regimens from textile and hybrid formulations.
- Metal Chains:Hardened steel link constructions with case-hardened alloy components dominate Alpine enforcement zones. German KBA type-approval remains mandatory for OE supply contracts with Stuttgart and Munich-based vehicle assemblers.
- Composite Chains:Reinforced polymer-fiber matrices achieve corrosion resistance without payload penalty. Norwegian and Swedish electric fleet operators specify these for battery range preservation under Nordic winter conditions.
- Fabric Chains:High-tensile textile weaves with metal stud reinforcements occupy the rental fleet segment in Austrian mountain resorts.
- Automatic Chains:Centrifugal deployment mechanisms integrated with vehicle hub assemblies command premium positioning through OEM fitment channels.
Metal chains sit at the top of the volume ranking, with composite chains climbing the fastest.
Vehicle Type:
Per-unit economics separate passenger applications from commercial mandates, with margin structures inversely related to procurement volume.
- Passenger Vehicles:Individual consumers in Germany, Austria, and Switzerland drive replacement cycles tied to winter severity. Three-peak mountain snowflake tire substitution erodes discretionary purchases in urban corridors.
- Commercial Vehicles:Fleet compliance mandates across Bavarian municipal operators generate contracted volume with specialized fitment requirements. Higher per-unit margins reflect liability coverage and installation service bundling.
- SUVs:All-terrain specification chains accommodate larger tire profiles and higher axle loads for recreational Alpine access.
- Trucks:Heavy-duty chain configurations face Swiss OEKO-TEX material standards divergent from German protocols.
Passenger vehicles generate the highest absolute shipment volumes, while commercial vehicles deliver the steepest margin expansion trajectory.
Installation Type:
Fitment complexity determines distribution channel viability and end-user purchase authority.
- Manual:Traditional tensioning systems requiring roadside tool deployment retain cost advantage for price-sensitive consumers.
- Quick-Install:Pre-tensioned loop designs reduce fitting time to under three minutes, enabling direct-to-consumer retail through automotive parts chains.
- Automatic:Hub-mounted centrifugal systems activate without driver intervention, specified by German OEMs for factory-approved equipment lists.
- Semi-Automatic:Partial self-tensioning mechanisms balance cost and convenience for rental fleet operators in Tyrol.
Manual installation retains volume leadership, with quick-install systems expanding most quickly through mass retail penetration.
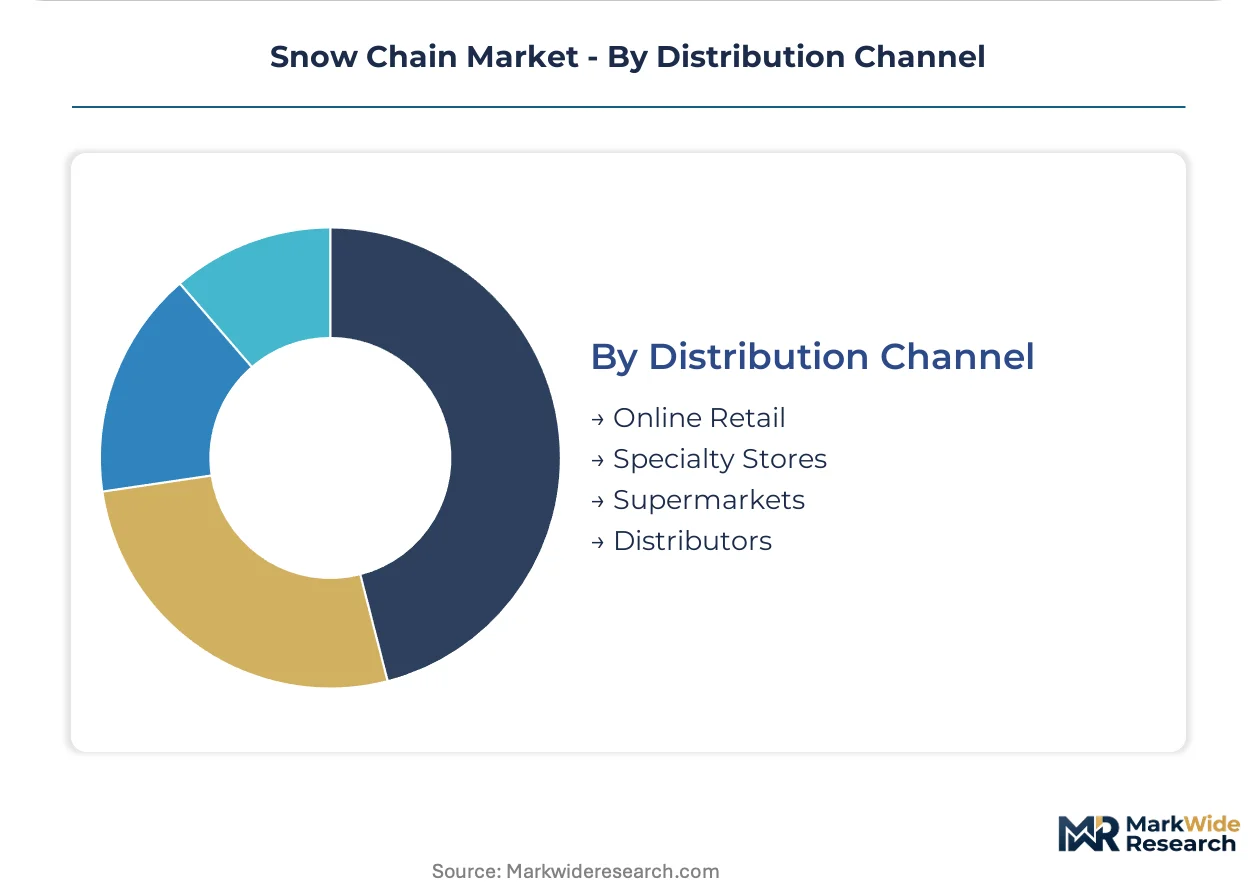
Distribution Channel:
Channel selection reflects purchase urgency and technical assistance requirements.
- Specialty Stores:Winter equipment specialists in Alpine regions provide fitment verification and regulatory compliance guidance for cross-border travelers.
- Distributors:Fleet procurement departments in Swiss and Austrian municipalities contract through authorized supply networks with service bundling obligations.
- Online Retail:Direct-to-consumer platforms concentrate in replacement purchases where sizing verification precedes seasonal demand spikes.
- Supermarkets:Mass-market seasonal displays capture impulse purchases in German urban centers with intermittent winter enforcement.
Specialty stores anchor premium transaction value, with distributor channels gaining share fastest through municipal fleet consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating composite chain production toward jurisdictions with streamlined REACH compliance and shorter TÜV certification queues, exploiting cost-of-compliance gaps between German testing hubs and emerging European facilities.
Germany
Alpine fleet procurement from Bavarian municipal operators drives institutional volume commitments. The KBA enforces type-approval standards for OE supply contracts with Stuttgart and Munich-based vehicle assemblers. The Stuttgart industrial cluster concentrates polymer engineering talent for textile-to-metal hybrid construction.
Switzerland
Mountain pass mandates across cantonal transport authorities sustain replacement demand for hardened steel configurations. Swissmedic-aligned OEKO-TEX material standards diverge from German protocols, requiring parallel testing streams. Zurich-based distributors now bundle three-year service agreements with hardware procurement.
Austria
Rental fleet operators in Tyrol deploy tool-free installation systems to compress roadside fitting times. The national transport ministry enforces winter equipment regulations under EU Roadworthiness Directive transpositions. Salzburg specialty retailers provide fitment verification for cross-border travelers.
Sweden
Battery electric commercial vehicle fleets in Nordic municipalities require weight-minimized traction solutions for range preservation. The Swedish Transport Agency mandates winter readiness documentation for commercial operators. Gothenburg automotive suppliers specify certified composite chains as factory-approved equipment.
United States
State-level chain requirements in California, Colorado, and Oregon create enforcement pockets without federal mandate. The NHTSA lacks winter equipment standards, leaving DOT and state patrol agencies to administer roadside compliance. Denver distributors supply private-label channels for Rocky Mountain fleet operators.
Snow Chain Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among European heritage brands and volume production anchored in North American private-label channels. The vendor base organizes into three tiers: integrated alloy formulators, composite material innovators, and scale-driven fabricators. Two competitive moves dominate current positioning: strategic partnerships between textile suppliers and automotive OEMs for factory-approved equipment lists, and geographic expansion of fitting-service networks to capture recurring revenue conversion.
Within the heritage-branded tier, Thule Group and RUD Ketten exemplify divergent specialization vectors—Thule leveraging retail network density for seasonal service bundling, RUD Ketten occupying the extreme-load engineering position through alloy formulation depth. Peerless Industrial Group anchors the North American scale-driven segment, its manufacturing footprint supplying fleet procurement channels with standardized specifications. These three represent the structural poles around which mid-cap competitors organize their positioning.
| Leading Market Players |
|---|
| Thule Group |
| RUD Ketten |
| Peerless Industrial Group |
| Pewag Group |
| Maggi Group |
| Weissenfels |
| Security Chain Company |
| Laclede Chain Manufacturing |
| Konig |
| Others |
Value Network & Pricing Analysis
European steel alloy price indices cascade through three distinct pricing tiers, with hardened case-hardened alloy fluctuations compressing distributor margins while elevating composite chain premiums in German and Austrian procurement channels.
Pricing Analysis
Distributor margin layers separate factory gate pricing from end-user transactions across Alpine supply networks. Three-tier pricing structure across premium, standard, and economy levels reflects TÜV certification grade and volume scale, with municipal fleet contracts commanding direct-to-manufacturer discounts unavailable to seasonal consumers. Pricing pressure stems from steel input volatility tied to European energy costs, eroding margin buffers for alloy-dependent fabricators. Individual consumers in urban German corridors exhibit highest price sensitivity, while Bavarian municipal operators prioritize liability coverage and installation service bundling over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Austrian TÜV certification hubs, where testing queue times concentrate market access control. Manufacturing draws from hardened steel alloy suppliers in Germany, textile composite formulators in Sweden, and polymer engineering clusters in Stuttgart. Raw material dependencies center on metallurgical-grade steel alloys, high-tensile aramid fibers, and REACH-compliant corrosion coatings. Tariff exposure on Asian textile imports threatens cost structures for hybrid chain fabricators. Distribution runs through authorized supply networks with service bundling obligations for fleet procurement, alongside direct-to-consumer platforms for replacement purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
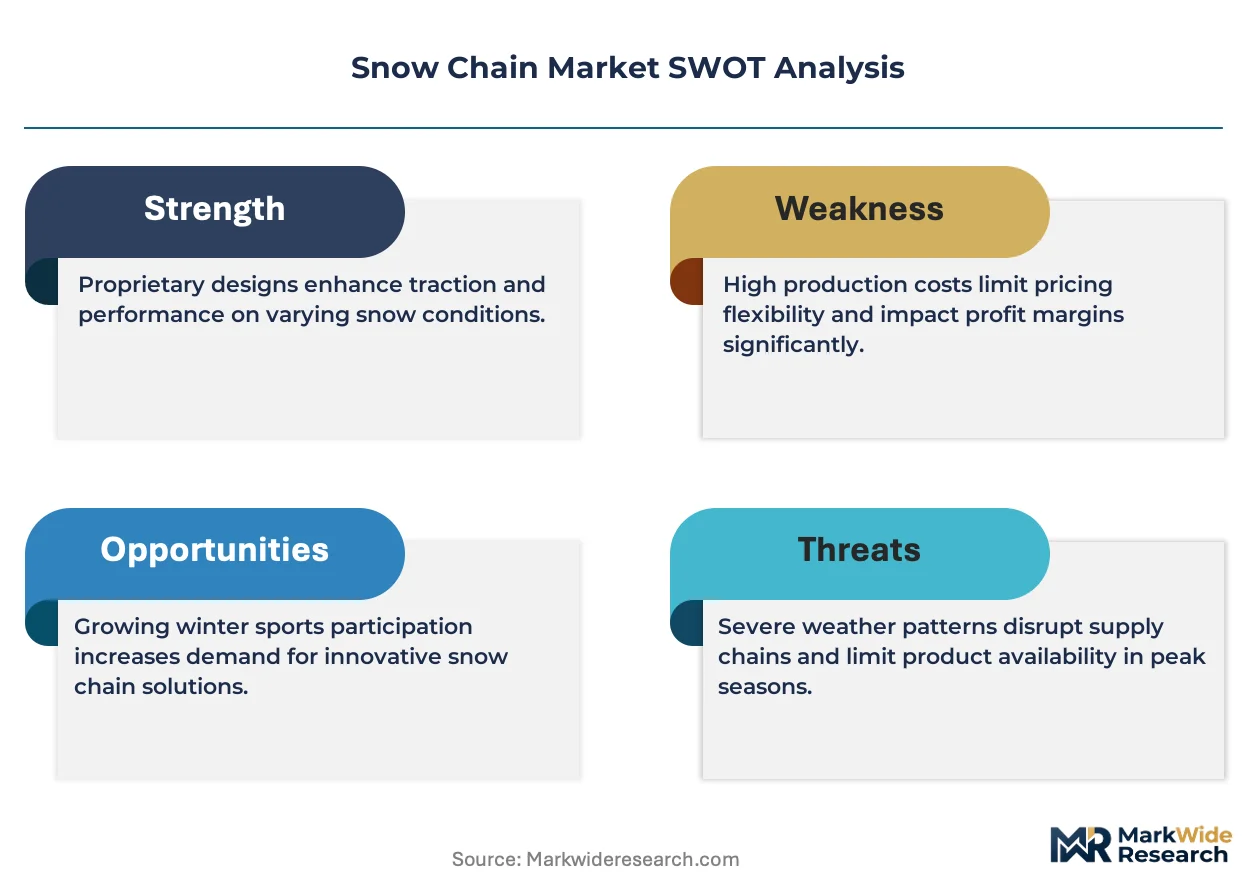
This market reads as a late-cycle quality story, with battery electric commercial vehicle fleet specifications in Norway and Sweden shifting procurement toward premium composite formulations.
For Market Incumbents: Deepen backward integration into hardened alloy supply through captive metallurgical partnerships, insulating margin structures from European energy cost volatility. Fortify TÜV certification pipeline investments to maintain 12-18 month queue advantages against uncertified Asian competitors. Composite welding expertise scarcity in Stuttgart and Munich clusters represents a defendable capability moat. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for REACH-compliant coating suppliers to capture share from corrosion-vulnerable Asian imports. Target Norwegian and Swedish electric fleet operators with weight-minimized traction solutions, leveraging battery range preservation as the primary value proposition. Pursue strategic partnerships with Gothenburg automotive suppliers for factory-approved equipment list placement. For Investors and Strategic Acquirers: Asymmetric upside sits with composite material innovators possessing TÜV-validated textile formulations and established OEM relationships. Long-term viability hinges on regulatory preference for CO2-equivalent weight reductions across vehicle accessory portfolios. Monitor German OEM factory-approved equipment specifications as the inflection signal for procurement influence migration upstream.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material R&D Investment | TÜV certification for textile formulations opens passenger vehicle segments to corrosion-resistant alternatives. |
| Subscription Fitting Service Expansion | Thule Group's retail network demonstrates viability of recurring revenue conversion from hardware transactions. |
| REACH-Compliant Coating Development | EU chemical registration requirements favor domestic suppliers against Asian import competition. |
| Backward Integration into Alloy Supply | Captive metallurgical partnerships insulate margin structures from European energy cost volatility. |
| OEM Factory-Approved Equipment Placement | German vehicle assemblers in Stuttgart and Munich shift procurement influence upstream to certified suppliers. |
Research Methodology
Bottom-up municipal fleet and passenger vehicle modeling reconciled against top-down alloy and composite production tracking forms the analytical core of this study. Primary interviews with procurement directors at Bavarian municipal operators, technical R&D leads at Stuttgart polymer engineering clusters, and aftermarket service heads at Alpine specialty retailers combined with secondary validation from KBA type-approval databases, EU Roadworthiness Directive transpositions, and customs trade data for hardened steel and textile composite inputs.
Historical trendline analysis across metal chain, composite chain, and automatic chain deployment patterns informed projection frameworks. Segmentation dimensions modeled include material composition, vehicle type classification, installation complexity tier, and distribution channel structure. CAGRs derive from regression analysis against Alpine winter severity indices, fleet electrification penetration curves, and regulatory enforcement intensity metrics. Composite adoption timelines incorporate EU F-Gas Regulation transport equipment amendment compliance requirements.
Revisions become necessary when steel alloy price volatility exceeds historical bands, TÜV certification queue times extend beyond 18 months, or three-peak mountain snowflake tire substitution accelerates in German urban corridors. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and material science advancement trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Outdoor Hot Tub Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
Rain Boots Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Fairway Mowers Market
Outdoor Gear
New Zealand Camping Equipment Market
Outdoor Gear
Japan Camping Equipment Market
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
Professional Gear Bags Market