
 Photography Services Market | 2026-2036
Photography Services Market Size, Share, and Industry Trends Forecast 2026-2036
Photography Services Market Outlook
Asset-light subscription licensing for camera bodies and lighting kits is rewriting competitive entry barriers across the photography services landscape. Snappr leverages a distributed freelancer model to sustain national coverage without studio overhead. Lifetouch anchors its position through institutional contracts with schools and families across North America. PlanOmatic specializes in real estate visualization, dominating property marketing channels for residential brokerages.
Photography services encompass the professional capture, processing, and delivery of still or moving images using digital sensors or film, typically outputting raw files at 14-bit color depth or higher for commercial grading. These services serve commercial promotion, personal commemoration, editorial documentation, and legal evidence purposes across consumer and enterprise contexts. Event photography leads service type revenue due to recurring wedding and corporate booking cycles, while commercial photography commands premium pricing through usage rights and brand campaign integration. Portrait photography competes on volume efficiency, with subscription pricing models now capturing recurring family and individual sessions.
The Federal Aviation Administration governs commercial drone photography through Part 107 certification, restricting airspace access and shaping aerial service provider qualifications. The Federal Trade Commission enforces advertising disclosure rules on influencer and product photography, affecting how commercial creators contract deliverables and represent sponsored content. Copyright registration through the U.S. Copyright Office establishes enforcement foundations for image licensing disputes. Stakeholders must monitor evolving state-level privacy statutes governing biometric capture and facial recognition in portrait workflows.
Market Dynamics
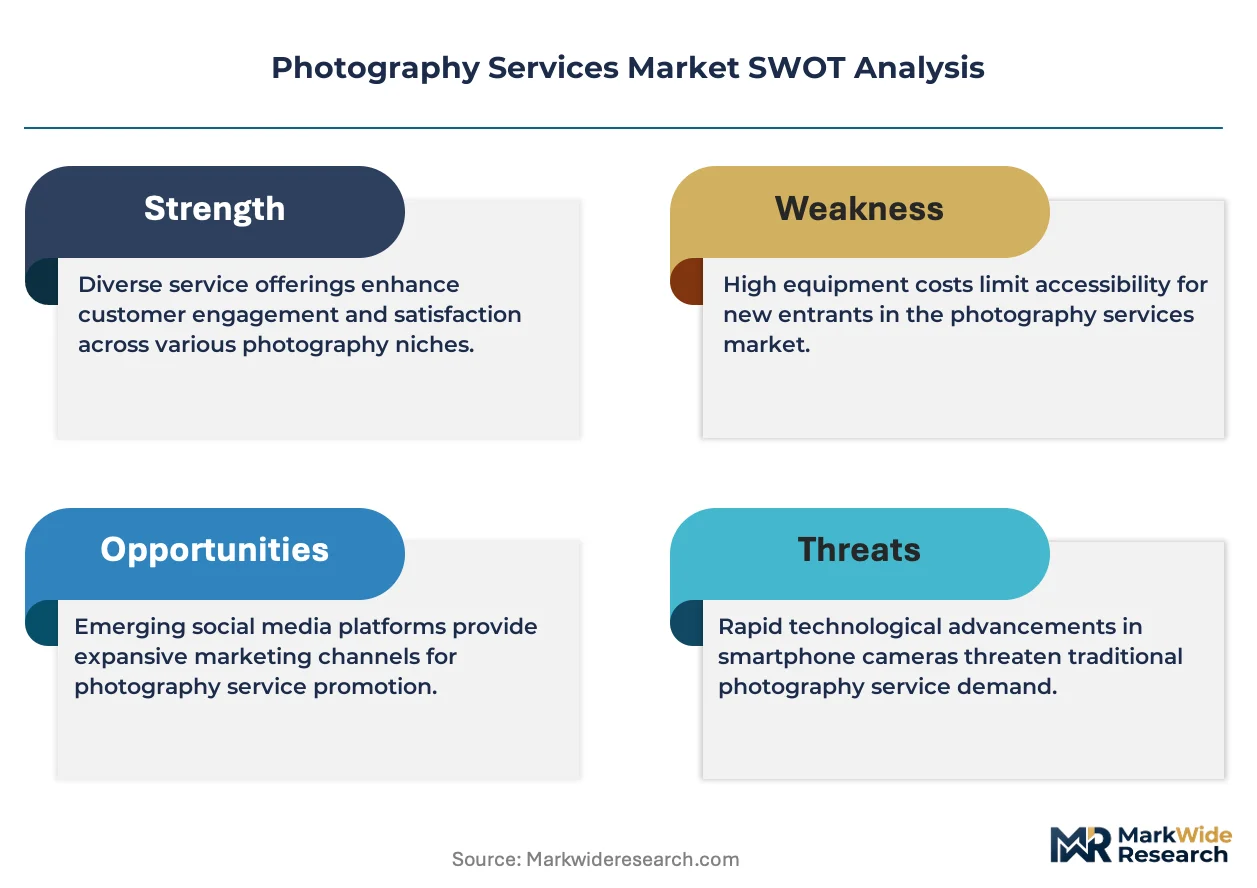
Asset-light subscription licensing for camera bodies and lighting kits is collapsing traditional capital barriers, enabling distributed freelancer networks to challenge established studio operations without fixed overhead.
Growth Catalysts
- Part 107 Certification:The FAA's commercial drone framework creates qualified aerial photography specialists who access restricted airspace for real estate and event documentation.
- Wedding Planner Procurement:Event coordinators in the United States now bundle professional photography into comprehensive service packages, consolidating buyer power.
- Metropolitan Studio Scaling:Mumbai and Delhi operations expand portrait and commercial capacity to serve domestic Indian demand plus export clients.
Market Restraints
- Equipment Depreciation Cycles:Camera body and sensor technology refresh rates compress investment recovery periods for independent operators.
- Biometric Privacy Statutes:State-level facial recognition regulations in multiple U.S. jurisdictions restrict portrait workflow automation and client database practices.
- Platform Commission Structures:Gig-economy intermediaries extract 20-40% of transaction value from freelance photographers, compressing net margins.
Strategic Opportunities
- Institutional Contract Anchoring:School district and family portrait agreements provide predictable recurring revenue with lower customer acquisition costs.
- Real Estate Visualization Integration:Property marketing channels for residential brokerages demand immersive 3D tours and aerial footage bundles.
- Export Service Capacity:Indian studios leverage lower operational costs to serve international commercial clients seeking high-volume post-production.
Industry Challenges
- Part 107 Recertification Burden:Aerial photography specialists face recurring testing requirements and operational limitation updates that disrupt service continuity.
- Copyright Registration Complexity:Image licensing disputes require formal U.S. Copyright Office filings that many independent creators neglect, weakening enforcement position.
- FTC Disclosure Compliance:Influencer and product photography contracts must embed advertising transparency that alters creative workflow and client communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photography Services Market |
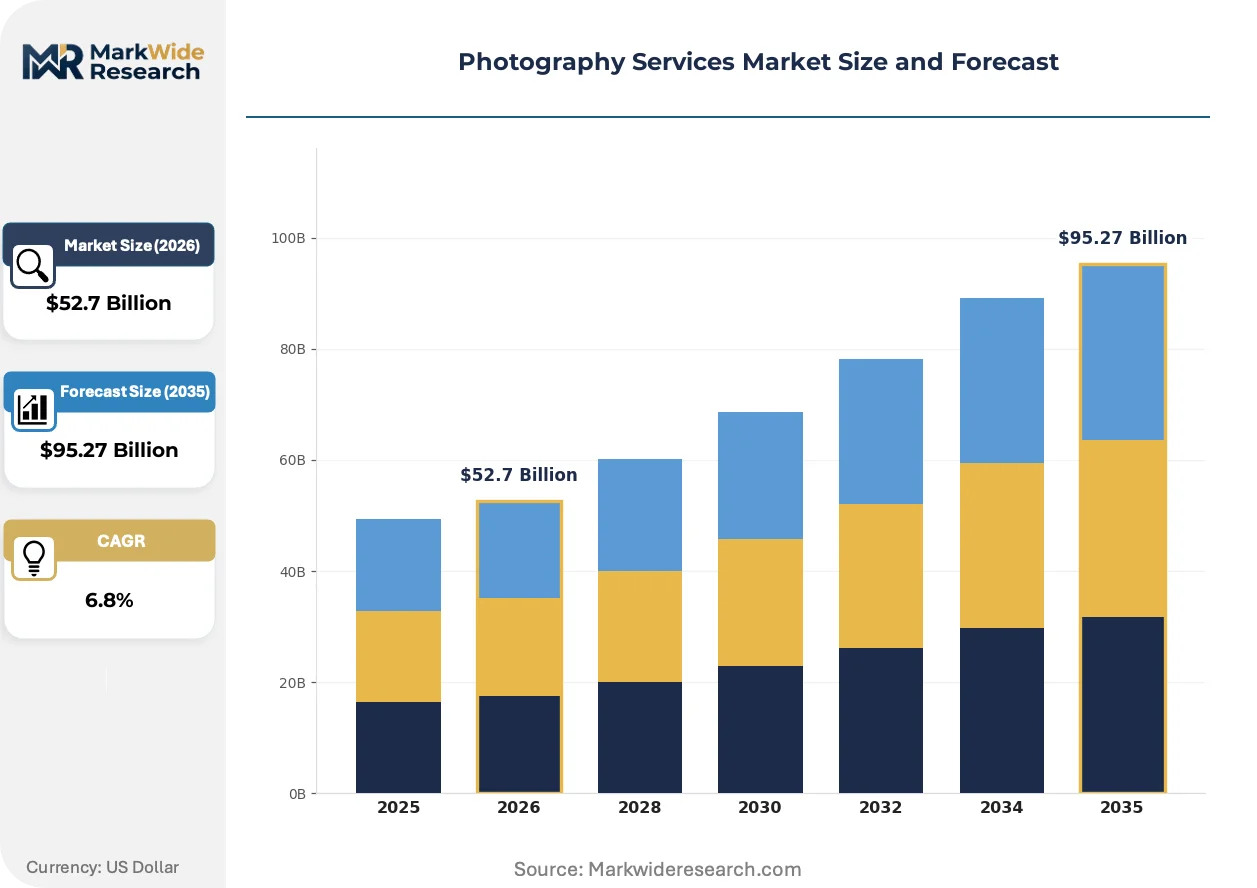
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Event Photography, Portrait Photography, Commercial Photography, Fashion Photography End User: Individuals, Corporations, Nonprofits, Government Agencies Delivery Mode: On-site Services, Studio Sessions, Virtual Consultations, Remote Editing Pricing Model: Hourly Rates, Package Deals, Subscription Services, Pay-Per-Project |
| Companies Covered | PlanOmatic, Skalawag Productions, Lifetouch, EM Productions, One Percenter, Snappr, Mott Visuals, Courage Production, ORBIS Production, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photography Services Market Strategic Shifts
Computational photography and AI-assisted editing tools are compressing production timelines while regulatory frameworks reshape operator qualifications across multiple jurisdictions.
Computational multi-frame stacking and AI denoising algorithms are collapsing the technical gap between professional full-frame systems and advanced smartphone sensors. Wedding photographers and content creators adopt these tools to deliver client-ready images within 24-hour turnaround windows. The distinction between professional and prosumer output quality is compressing pricing power at the mid-market tier.
REACH chemical restrictions and emerging EU AI Act provisions on synthetic media disclosure are reshaping equipment manufacturing and post-production transparency requirements. European commercial studios must now document editing pipeline provenance for advertising clients. German and French regulatory bodies lead enforcement, forcing workflow documentation investments that smaller operators struggle to absorb.
Subscription-based family portrait packages are displacing single-session bookings as the dominant consumer procurement model. Parents in U.S. suburban markets prefer quarterly milestone documentation with predictable annual costs over episodic studio visits. This shift concentrates lifetime customer value with operators who master retention logistics and automated scheduling systems.
Photography Services Market Segmentation
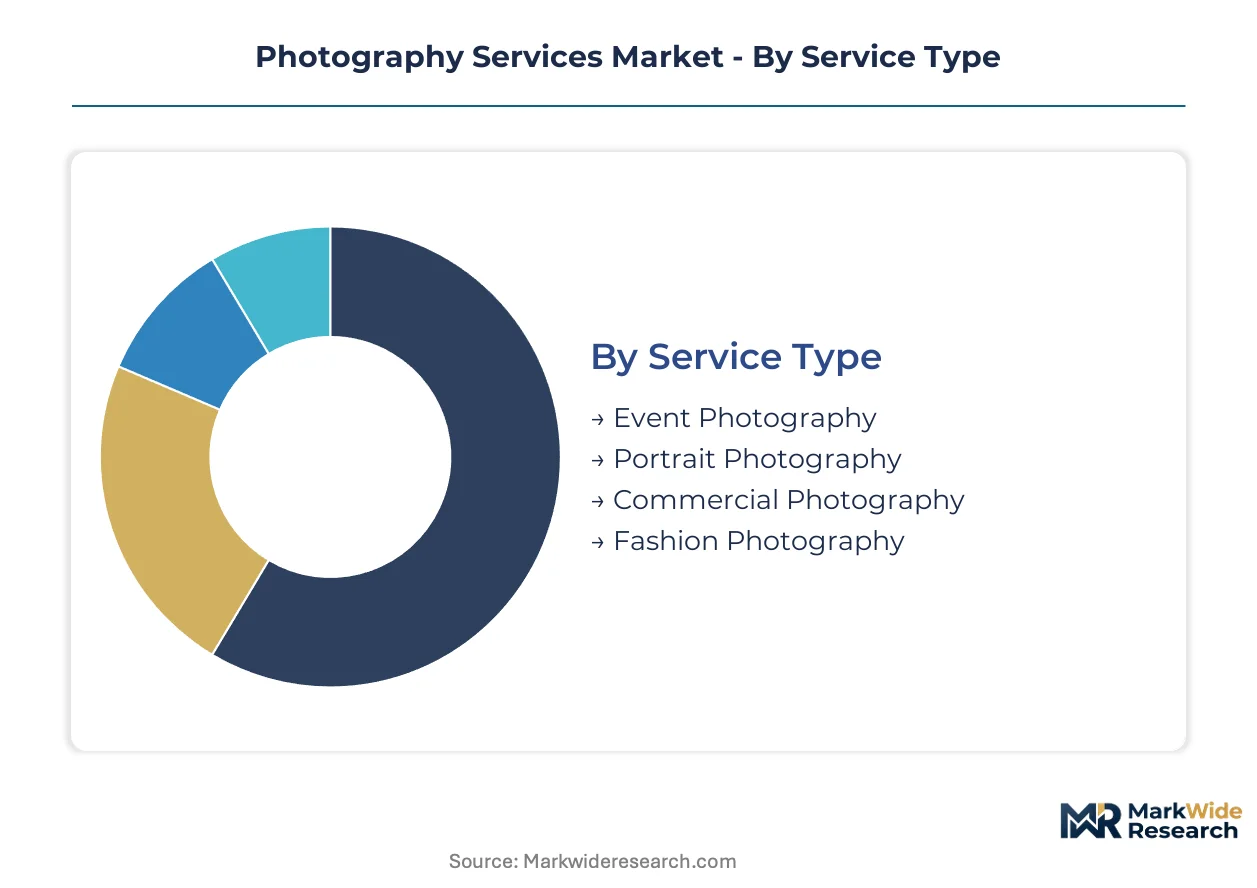
Photography services fragment across four operational dimensions that determine capital intensity, customer acquisition economics, and margin structure. Service type and delivery mode together dictate equipment requirements and geographic reach, while pricing model selection shapes lifetime customer value and cash flow predictability.
Service Type:
Mature segments dominate revenue concentration while emerging niches reshape competitive positioning through technology differentiation.
- Event Photography:Captures weddings, corporate gatherings, and milestone celebrations with high equipment redundancy requirements for zero-failure tolerance. Wedding planners in the United States now bundle this service into comprehensive packages, consolidating procurement decisions and compressing margins for standalone operators.
- Commercial Photography:Produces advertising assets, product imagery, and brand campaign content with 14-bit raw output standards for commercial grading flexibility. Metropolitan studios in Mumbai and Delhi scale this segment for export clients seeking high-volume post-production at lower operational cost bases.
- Portrait Photography:Family, individual, and professional headshot sessions compete on volume efficiency and subscription retention mechanics.
- Fashion Photography:Editorial and runway documentation requiring specialized lighting expertise and rapid turnaround protocols for publication deadlines.
Event Photography handles the majority of throughput; Commercial Photography is expanding most quickly on share as Indian studios capture international client volume.
End User:
Customer type determines contract structure, with institutional buyers favoring multi-year agreements and individuals driving subscription adoption.
- Individuals:Family portrait subscribers and wedding clients who procure through bundled event coordinator packages, shifting toward quarterly milestone documentation with predictable annual costs.
- Corporations:Brand marketing departments and HR functions requiring consistent visual asset libraries with usage rights documentation for campaign integration.
- Nonprofits:Mission-driven organizations prioritizing cost efficiency over production values for donor communications and annual reports.
- Government Agencies:Public sector procurement with formal bidding requirements and compliance with FAA Part 107 for aerial documentation projects.
Individuals generate the highest transaction frequency; Corporations deliver the steepest expansion trajectory as brand content demands intensify.
Delivery Mode:
Physical presence requirements segment operators by overhead structure, with asset-light models challenging traditional studio economics.
- On-site Services:Location-based capture at events, properties, or client premises requiring portable equipment kits and travel logistics management.
- Studio Sessions:Controlled environment photography with fixed lighting arrays and climate control, carrying rent burden but enabling higher hourly output rates.
- Virtual Consultations:Remote client intake and pre-production planning that reduces geographic constraints on photographer-client matching.
- Remote Editing:Post-production workflows executed by distributed teams, with Indian studios leveraging this mode for international commercial client service.
On-site Services commands the largest labor allocation; Remote Editing is climbing the fastest as computational photography tools compress technical quality gaps.
Pricing Model:
Revenue predictability separates models, with subscription mechanics capturing lifetime value and project pricing preserving flexibility.
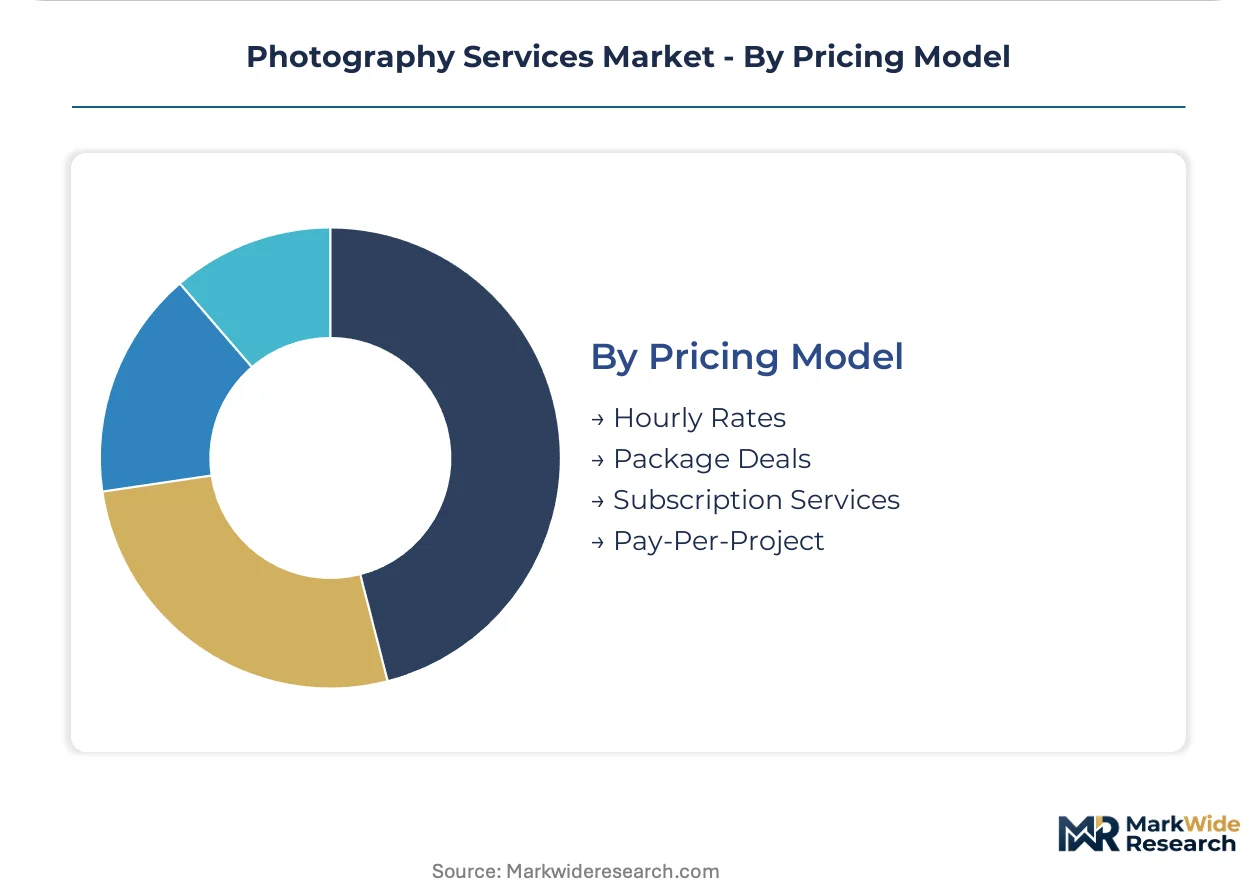
- Hourly Rates:Time-based billing for event coverage and corporate assignments with transparent cost structures but capped upside per engagement.
- Package Deals:Bundled deliverable sets for weddings and portraits that improve close rates through simplified decision architecture.
- Subscription Services:Quarterly family milestone programs with automated scheduling and retention logistics, displacing single-session bookings in U.S. suburban markets.
- Pay-Per-Project:Scope-defined commercial contracts with usage rights negotiations and brand campaign integration requirements.
Package Deals anchor current volume; Subscription Services is gaining share fastest as retention economics reshape consumer procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Aviation Administration's Part 107 certification framework has reshaped commercial aerial photography qualifications across multiple jurisdictions. National regulators now enforce divergent standards for drone operation, biometric capture, and synthetic media disclosure that fragment operational compliance costs.
United States
Wedding planners and event coordinators now bundle professional photography into comprehensive service packages, consolidating procurement decisions. The FAA governs commercial drone photography through Part 107 certification, restricting airspace access and mandating recurrent testing for aerial specialists. Metropolitan clusters in Los Angeles and New York anchor high-volume commercial and portrait studio operations serving domestic and export clients.
India
Metropolitan studios in Mumbai and Delhi scale portrait and commercial operations for domestic demand plus international post-production outsourcing. The country's national aviation regulator mandates unmanned aircraft system certifications for commercial aerial work, creating qualified specialist pools. Bangalore and Hyderabad emerging as secondary hubs for remote editing workflows serving European and North American commercial clients.
Germany
REACH chemical restrictions and emerging EU AI Act provisions on synthetic media disclosure reshape equipment manufacturing and post-production transparency requirements. German regulatory bodies lead enforcement on editing pipeline provenance documentation for advertising clients. Berlin and Munich studio concentrations absorb compliance workflow investments that smaller operators struggle to match.
France
French regulatory authorities enforce EU AI Act synthetic media disclosure rules alongside national privacy statutes governing biometric capture in portrait workflows. Paris anchors fashion and editorial photography clusters with rapid-turnaround publication deadline expertise. Lyon and Marseille emerging as secondary commercial production centers with lower operational cost bases.
United Kingdom
London's creative sector drives commercial photography demand for brand campaign integration and advertising asset production. The national data protection authority enforces biometric privacy restrictions affecting portrait workflow automation and client database practices. Manchester and Birmingham studio networks expand to capture corporate and institutional contract volume outside the capital's premium cost structure.
Photography Services Market Competitive Environment
On the supply side, the industry is fragmented across distributed freelancer networks, institutional contract holders, and specialized visualization studios. Three strategic archetypes dominate: asset-light platform intermediaries matching clients with gig photographers, institutional anchoring specialists securing multi-year school and family portrait agreements, and property marketing visualization experts bundling aerial footage with immersive 3D tours. Competitive moves concentrate on geographic expansion through distributed freelancer models and vertical integration into automated scheduling and retention logistics systems.
Within the institutional contract tier, Lifetouch secures predictable recurring revenue through school district and family portrait agreements across North America. Snappr exemplifies the asset-light platform archetype, sustaining national coverage without studio overhead through distributed freelancer matching. PlanOmatic anchors the property marketing specialization, dominating residential brokerage visualization channels with bundled aerial and immersive tour deliverables.
| Leading Market Players |
|---|
| PlanOmatic |
| Skalawag Productions |
| Lifetouch |
| EM Productions |
| One Percenter |
| Snappr |
| Mott Visuals |
| Courage Production |
| ORBIS Production |
| Others |
Value Chain & Pricing Dynamics
Part 107 recertification burdens and FAA airspace restrictions create operational chokepoints that compress margins for aerial specialists while widening spreads between certified and uncertified service tiers. Equipment depreciation cycles and platform commission structures force independent operators toward subscription models or institutional contracts, reshaping how capital flows through production and post-production nodes.
Pricing Analysis
Certification level creates the primary spread between Part 107 aerial specialists and ground-based generalists, with drone operators commanding premium rates for restricted airspace access. Three-tier pricing structure across premium event packages, standard portrait subscriptions, and economy gig-platform bookings reflects divergent customer lifetime value mechanics. Pricing pressure stems from AI-assisted editing tools collapsing quality gaps between professional and prosumer output. Wedding planners bundling services exhibit lowest price sensitivity; independent freelancers on platform marketplaces face highest margin compression.
Supply Chain Analysis
Extended payment terms from real estate brokerages and school districts dominate supplier financing, with institutional clients stretching receivables to 60-90 days. Equipment manufacturing concentrates in Japan, Germany, and China for camera bodies, lighting systems, and sensor components. Raw material dependencies include rare earth elements for sensor fabrication, lithium for battery systems, and optical glass for lens production. Tariff exposure on Chinese-manufactured drones and accessories threatens margin stability for aerial operators. Distribution runs through direct-to-consumer platform channels, institutional procurement offices, and event coordinator intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photography services sit in early-cycle expansion as subscription-based family documentation displaces episodic bookings across U.S. suburban markets, with retention automation driving predictable revenue streams.
For Market Incumbents: Build switching-cost moats through proprietary scheduling and automated milestone reminder systems that embed deeper into family lifecycle events. Deepen backward integration into editing software and cloud delivery platforms to reduce platform dependency. Acquire remote editing capacity in Indian metropolitan studios to capture international post-production arbitrage. Defend against AI-native entrants by emphasizing human curation and relationship-based service continuity. For New Entrants and Emerging Players: Pursue white-space opportunity in biometric-compliant portrait workflows for states with emerging facial recognition statutes, where incumbents face compliance retrofit costs. Target underpenetrated secondary Indian cities for export-oriented commercial production, leveraging lower operational bases than Mumbai-Delhi clusters. Enter through vertical specialization—pet photography, elder milestone documentation, or creator economy content retainers—rather than competing on generalist event coverage. For Investors and Strategic Acquirers: EU AI Act synthetic media disclosure requirements reshape the acquisition landscape toward studios with documented editing provenance and compliance infrastructure. Long-term viability favors operators with institutional contract anchoring and subscription retention mechanics over project-dependent freelancers. Target acquisition archetype: regional portrait chains with automated scheduling systems and school district relationships. Monitor FAA Part 107 regulatory expansion as signal for aerial service consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Snappr's freelancer matching model demonstrates national coverage without studio overhead burden. |
| Institutional Contract Anchoring | Lifetouch's school district agreements provide predictable recurring revenue with lower acquisition costs. |
| Geographic Expansion | Indian studios in Bangalore and Hyderabad capture European commercial post-production outsourcing volume. |
| Backward Integration | In-house AI editing tools reduce platform commission exposure and accelerate client delivery timelines. |
| Certification Investment | Part 107 compliance creates defendable aerial service positioning as FAA restricts commercial airspace access. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wedding planners, event coordinators, school district procurement officers, real estate brokerage marketing directors, and freelance photographers across platform networks. Secondary validation drew from FAA regulatory filings, U.S. Copyright Office registration data, FTC advertising disclosure enforcement actions, and state-level biometric privacy statute tracking. Bottom-up triangulation across service type, delivery mode, and pricing model segmentation informed volume estimates, while top-down calibration against equipment shipment data and platform transaction disclosures anchored value projections.
Calibration against historical booking cycle patterns and equipment refresh rates stabilized growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include service type, end user category, delivery mode, and pricing model structure. CAGRs derived from fitted trend analysis incorporating platform penetration rates, subscription adoption curves, and regulatory implementation timelines. Industry-specific forecast inputs include Part 107 certification growth, AI editing tool adoption slopes, and institutional contract renewal rates.
Sensitivities concentrate around FAA regulatory expansion pace, EU AI Act enforcement intensity, and platform commission structure evolution. Forecasts reflect documented assumptions on technology diffusion and buyer behavior migration. Macroeconomic contraction affecting discretionary event spending, regulatory deviation on biometric capture restrictions, or breakthroughs in synthetic media generation would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
South Korea Webtoons Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
Music Rights Management Market
Digital Media
Europe Location-Based Entertainment Market
Digital Media
Online Gambling Market
Digital Media
Middle East Media and Entertainment Market
Digital Media
Mobile Entertainment Market
Digital Media
Germany Animation, VFX and Post Production Market
Digital Media
Photographic Services Market
Digital Media
Anime Merchandising Market
Digital Media
United States Sports Betting Market
Digital Media
Global Digital Painting Market
Digital Media
India Webtoons Market
Digital Media
Webcomics Market