
 Media Coding Service Market | 2026-2036
Media Coding Service Market Size, Share, and Industry Trends Forecast 2026-2036
Media Coding Service Market Intelligence
ISO/IEC 23008 compliance for high-efficiency video coding is rotating vendor eligibility across the Media Coding Service landscape. Microsoft sustains cloud-native encoding infrastructure through Azure Media Services. Google dominates consumer-facing streaming codec deployment via YouTube's VP9 and AV1 pipelines. Amazon Web Services controls enterprise-grade transcoding throughput through AWS Elemental offerings.
Media coding services encompass the computational transformation of raw audiovisual signals into compressed, distribution-ready formats using standards such as H.265/HEVC at bitrates as low as 2 Mbps for 1080p delivery, serving broadcasters and streaming platforms with interoperability-critical output. Transcoding commands the largest revenue pool among service types, as legacy content libraries require continuous format migration to reach fragmented device ecosystems. Live Streaming within the delivery model segment captures the fastest expansion trajectory, driven by sports rights holders and event producers demanding sub-three-second latency.
FCC regulations govern broadcast signal standards in the United States, while ETSI and the EU AI Act shape automated content tagging and metadata requirements across European deployments. The CE marking framework mandates electromagnetic compatibility for on-premise encoding hardware sold into EU member states. Stakeholders must monitor codec patent pool dynamics and sovereign data-localization mandates as these forces determine which vendors retain market access.
Market Dynamics
Codec patent pool fragmentation is reshaping vendor economics across the Media Coding Service landscape, as MPEG-LA, Access Advance, and Velos Media compete for H.266/VVC royalty claims while cloud providers absorb licensing costs into bundled infrastructure pricing.
Growth Catalysts
- EU AI Act metadata mandates:Automated content tagging requirements in Europe are forcing broadcasters to upgrade encoding pipelines with embedded machine-learning descriptors.
- Live sports latency compression:Rights holders now demand sub-three-second end-to-end latency, driving edge-node encoding deployments adjacent to 5G infrastructure.
- South Korean 8K broadcast trials:Terrestrial trials by KBS and MBC are accelerating HEVC and VVC encoder qualification for next-generation distribution.
Market Restraints
- Silicon supply concentration:GPU and ASIC encoder chip fabrication concentrates in Taiwan and South Korea, exposing transcoding capacity to geopolitical disruption.
- Patent royalty stacking:Accumulating claims from multiple pools inflate per-stream costs for independent streaming platforms without vertical cloud infrastructure.
- Legacy format persistence:Broadcasters in Germany and Japan maintain MPEG-2 transmission chains, delaying full HEVC migration and bifurcating encoder procurement.
Strategic Opportunities
- India's OTT infrastructure buildout:Reliance Jio and Disney+ Hotstar expansion is creating demand for regional-language transcoding at massive scale.
- AI-generated content pipelines:Synthetic media production tools require real-time encoding integration for synthetic face and voice consistency verification.
- FCC captioning modernization:Updated closed-captioning standards are opening retrofit contracts for broadcast archive reprocessing.
Industry Challenges
- Real-time encoding specialist scarcity:Engineers with kernel-level GPU optimization skills for FFmpeg and NVENC pipelines command premium compensation, constraining vendor scaling.
- Multi-codec certification timelines:Qualifying hardware encoders for simultaneous H.264, HEVC, and AV1 output extends product development cycles by twelve to eighteen months.
- Hybrid cloud orchestration complexity:Broadcasters struggle to synchronize on-premise encoding clusters with burst transcoding to AWS, Azure, and Google Cloud without frame-level drift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Media Coding Service Market |
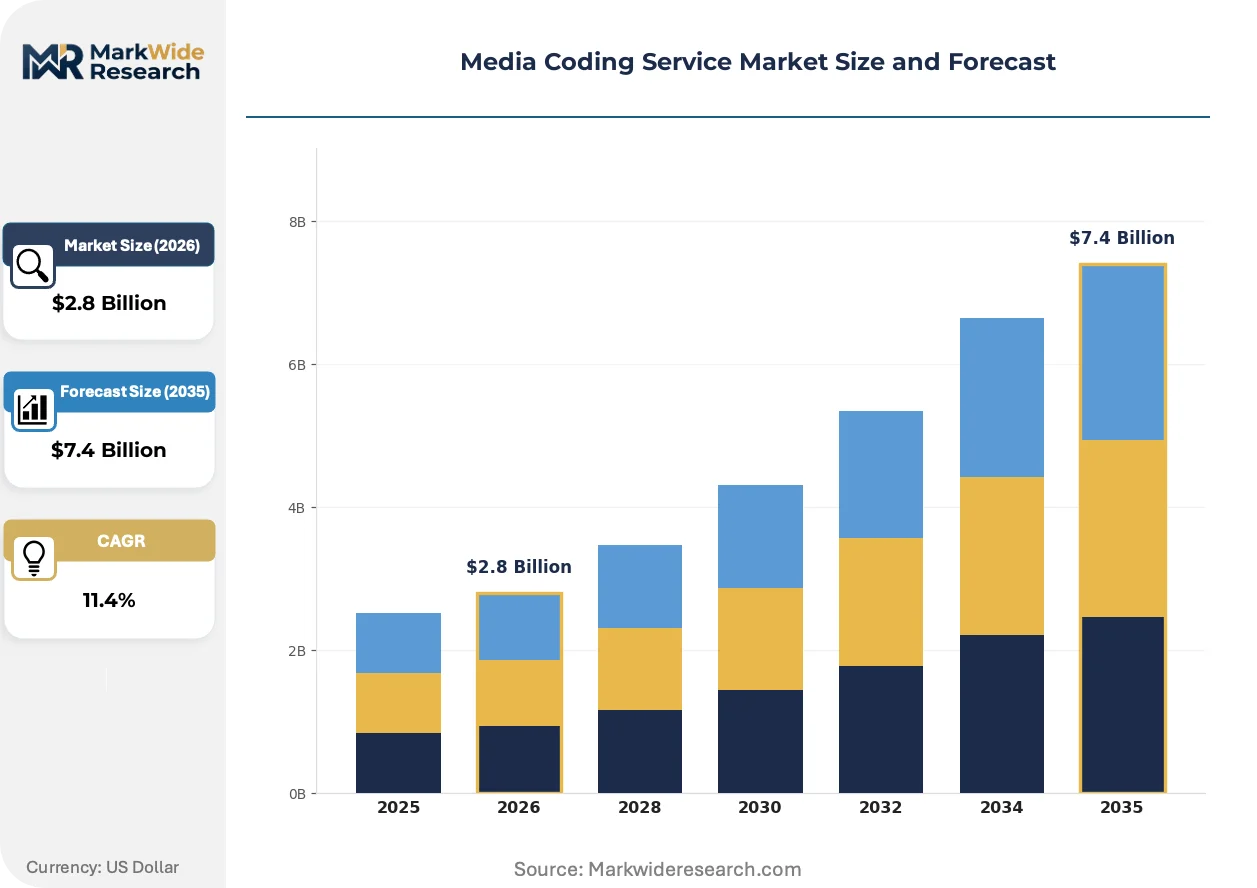
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transcoding, Encoding, Subtitling, Dubbing Content Type: Video, Audio, Streaming, Interactive Media Delivery Model: On-Demand, Subscription, Pay-Per-View, Live Streaming End User: Broadcasters, Content Creators, Enterprises, Educational Institutions |
| Companies Covered | Google, Microsoft, Amazon Web Services, Harmonic Inc., ATEME SA, Kaltura, Telefonaktiebolaget LM Ericsson, Akamai Technologies, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Media Coding Service Market Strategic Shifts & Innovations
Perceptual optimization algorithms and neural network-based compression are compressing bitrate requirements while preserving subjective quality, enabling streaming platforms to reduce distribution costs without subscriber-visible degradation.
AV1 open-source codec deployment is supplanting HEVC in browser-based streaming environments. YouTube and Netflix have completed library-wide AV1 re-encodes for mobile and desktop tiers. This shift is eroding patent-encumbered codec leverage and redistributing value toward CDN and edge-compute infrastructure providers.
ETSI standards for synthetic media watermarking are mandating forensic traceability in encoded output across European deployments. Content distributors must now embed provenance metadata at the encoding stage. French broadcasters and German public-service media are piloting compliant pipelines ahead of 2026 enforcement deadlines.
Subscription fatigue among streaming households is fragmenting library access across ad-supported tiers. Platforms now procure tiered encoding profiles—premium bitrate for paid subscribers, aggressive compression for ad-supported viewers. This bifurcation is most visible in the United States and United Kingdom, where hybrid revenue models now dominate new service launches.
Media Coding Service Market Segmentation
Media coding service procurement varies sharply by workflow complexity and latency requirements. Buyers select service tiers based on content velocity, regulatory obligations, and target device fragmentation.
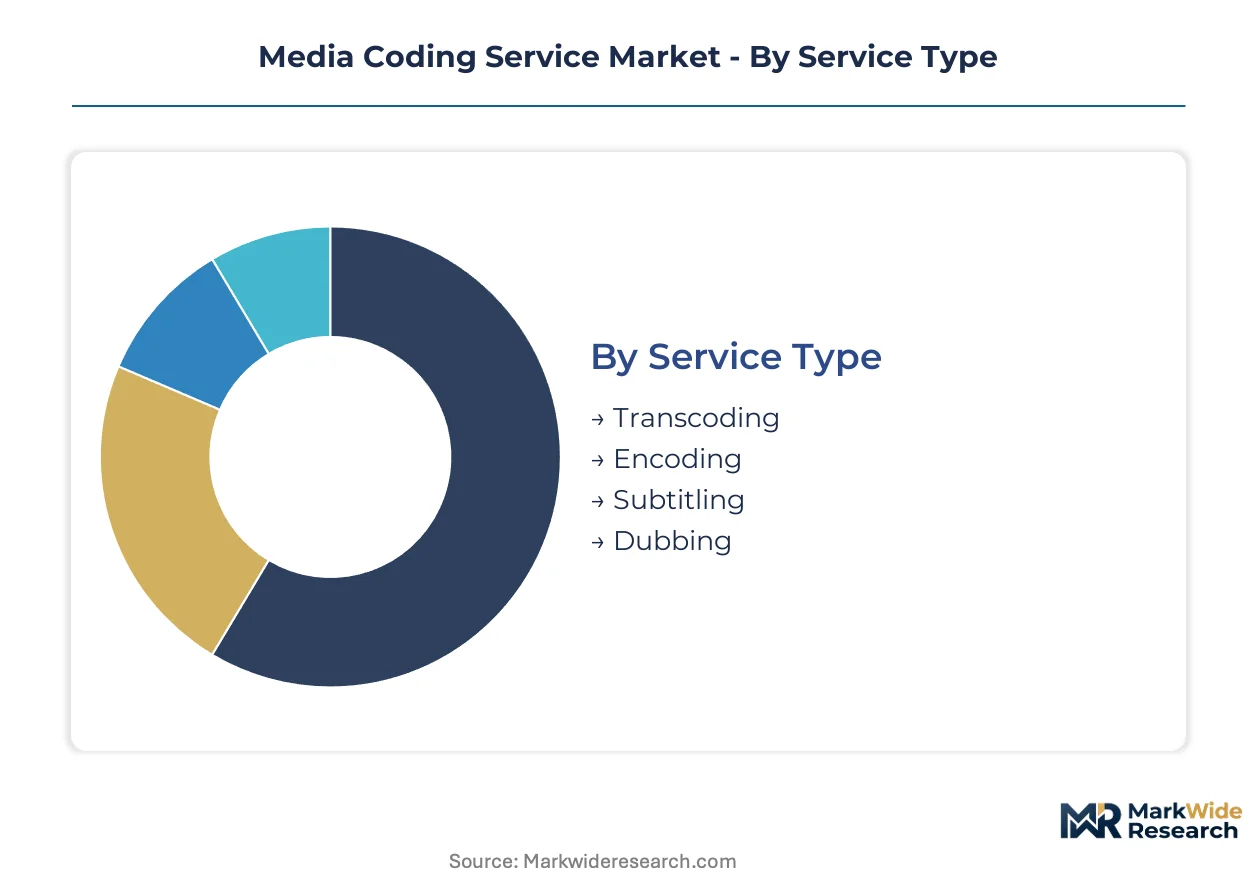
Service Type:
Margin pools concentrate in high-throughput transcoding contracts serving streaming platform back catalogs.
- Transcoding:Format migration of existing libraries to HEVC, AV1, and VVC standards for multi-device compatibility. Demand clusters with Netflix, Disney+, and Amazon Prime Video as they refresh compression tiers for bandwidth-constrained markets.
- Encoding:Raw signal compression from camera-to-delivery using hardware-accelerated ASIC and GPU pipelines. Live sports broadcasters in the United States and South Korea drive premium pricing for sub-three-second latency configurations.
- Subtitling:Timed-text insertion meeting FCC and EBU accessibility mandates.
- Dubbing:Audio track replacement with automated lip-sync alignment for regional distribution.
The dominant share belongs to Transcoding, while Encoding is closing the gap fastest.
Content Type:
Application intensity tracks directly with bitrate sensitivity and audience scale.
- Video:Motion-compensated compression dominating infrastructure spend across 4K and 8K pipelines. Studios in Germany and South Korea are qualifying VVC encoders for theatrical streaming windows.
- Streaming:Adaptive bitrate packaging for fragmented CDN delivery. YouTube and Twitch consumption patterns in the United States shape codec roadmap priorities for browser-based playback.
- Audio:Spatial and object-based coding for immersive formats.
- Interactive Media:Real-time compression for cloud gaming and virtual production environments.
Video commands the largest revenue pool, with Streaming expanding most quickly as live viewing displaces scheduled broadcast.
Delivery Model:
Customer type determines contract structure and margin durability.
- Live Streaming:Edge-node encoding for sports, esports, and concert distribution with sub-three-second latency requirements. Rights holders in the United States and United Kingdom are deploying 5G-adjacent encoding clusters for mobile-first audiences.
- Subscription:Recurring transcoding volume from SVOD platforms maintaining multi-format libraries.
- On-Demand:Transactional encoding for rental and purchase windows.
- Pay-Per-View:Burst capacity provisioning for one-time events with unpredictable viewership spikes.
Subscription delivers the steadiest margins, though Live Streaming is gaining share fastest as sports rights renegotiations emphasize direct-to-consumer distribution.
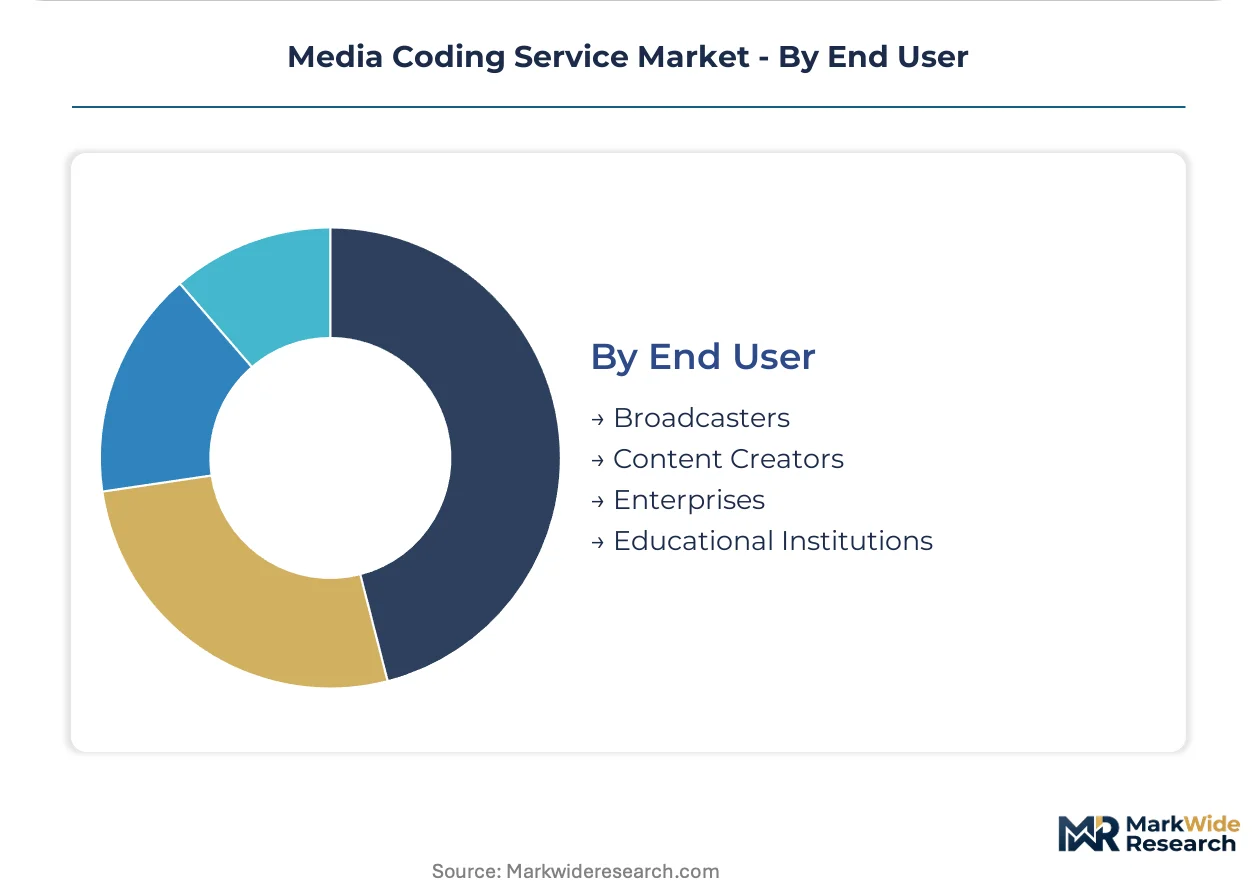
End User:
Procurement sophistication varies with technical staffing depth and compliance exposure.
- Broadcasters:National networks and public-service media requiring FCC, EBU, and EU AI Act compliance. ARD and ZDF in Germany are piloting synthetic media watermarking pipelines ahead of enforcement deadlines.
- Content Creators:Independent studios and influencer networks purchasing cloud-burst encoding without capital infrastructure.
- Enterprises:Corporate communications and training video distribution with internal SLA requirements.
- Educational Institutions:Lecture capture and MOOC platforms with accessibility captioning obligations.
Broadcasters retain the largest contract values, while Content Creators are scaling fastest as creator economy monetization drives professional-grade post-production demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadcasters and streaming platforms in the United States, Germany, and South Korea command the largest procurement volumes for media coding services. Rights holders in these markets prioritize sub-three-second latency configurations and compliance-grade metadata pipelines. Cloud infrastructure providers align encoder qualification programs with national regulatory frameworks.
United States
Major sports leagues and OTT platforms drive demand for edge-node encoding clusters. The FCC mandates closed-captioning standards and broadcast signal specifications that shape vendor eligibility. Los Angeles and New York media corridors host the densest concentrations of live production facilities deploying real-time transcoding.
Germany
Public-service broadcasters ARD and ZDF pilot synthetic media watermarking pipelines ahead of EU AI Act enforcement. ETSI standards and CE marking requirements govern encoder hardware sold into EU member states. Berlin and Munich production hubs qualify multi-codec encoders for simultaneous H.264, HEVC, and AV1 output.
South Korea
KBS and MBC terrestrial trials accelerate HEVC and VVC encoder qualification for 8K broadcast distribution. The country's national broadcast regulator shapes transmission standards for next-generation formats. Seoul's Gangnam district clusters encoding infrastructure providers serving regional streaming platforms.
United Kingdom
Hybrid ad-supported streaming models fragment library access across tiered encoding profiles. Ofcom accessibility mandates and EBU technical standards influence procurement specifications. London's Soho post-production district concentrates facilities processing sports rights for direct-to-consumer distribution.
India
Reliance Jio and Disney+ Hotstar expansion creates demand for regional-language transcoding at massive scale. TRAI regulations govern OTT platform interoperability and quality-of-service metrics. Mumbai and Bengaluru technology corridors host cloud encoding nodes serving South Asian language markets.
Media Coding Service Market Key Industry Players
Player mix skews toward hyperscale cloud providers with integrated media services divisions. The market structure concentrates around three infrastructure archetypes: vertically integrated technology conglomerates, broadcast-specialist equipment vendors, and CDN-anchored encoding services. Strategic moves emphasize codec licensing absorption into bundled infrastructure pricing and edge-node deployment partnerships with telecommunications carriers.
Within the cloud-native tier, Google, Microsoft, and Amazon Web Services exemplify the infrastructure-integrated archetype. These entities absorb patent pool royalties into opaque pricing structures while controlling transcoding throughput through proprietary silicon and global fiber networks. ATEME SA and Harmonic Inc. occupy positions within the broadcast-specialist segment, serving terrestrial and satellite operators with compliance-certified encoder hardware. Akamai Technologies represents the CDN-anchored model, embedding encoding functions within distributed edge infrastructure to compress latency for live sports and esports distribution.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| Harmonic Inc. |
| ATEME SA |
| Kaltura |
| Telefonaktiebolaget LM Ericsson |
| Akamai Technologies |
| Apple |
| Others |
Cost & Logistics Intelligence
Fourteen-to-eighteen-month encoder hardware qualification cycles concentrate procurement leverage with cloud hyperscalers, compressing margins for independent transcoding vendors while patent royalty stacking inflates per-stream costs for platforms without bundled infrastructure pricing.
Pricing Analysis
Cost-plus contracts indexed to GPU and ASIC chip pricing dominate enterprise transcoding agreements, with Azure Media Services and AWS Elemental absorbing patent pool royalties into opaque bundled rates. Price differentiation rests on latency tier certification and multi-codec output capability, with broadcasters in Germany and South Korea paying premiums for sub-three-second configurations. Cost compression in ad-supported streaming tiers intensifies as Netflix and Disney+ bifurcate encoding profiles by subscriber tier. Independent content creators exhibit highest price sensitivity, while sports rights holders in the United States demonstrate lowest sensitivity for live-edge deployments.
Supply Chain Analysis
Strategic stockpiling of encoder ASICs by cloud providers contrasts with just-in-time component procurement among broadcast-specialist vendors, exposing the latter to Taiwan and South Korea fabrication bottlenecks. GPU and ASIC encoder chip supply concentrates in Taiwan, South Korea, and select United States foundries, drawing from silicon wafer, memory module, and thermal management component streams. Single-source vulnerability around TSMC advanced node allocation threatens transcoding capacity expansion timelines. Distribution runs through direct hyperscaler procurement for cloud-native tiers and systems integrator channels for on-premise broadcast deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has consolidated around three hyperscale cloud providers, fragmenting negotiating leverage for independent streaming platforms and forcing vendor qualification decisions toward bundled infrastructure pricing.
For Market Incumbents: Secure exclusive edge-node partnerships with telecommunications carriers in the United States and South Korea to defend against CDN-anchored encoding entrants. Patent royalty absorption into bundled pricing structures serves as the primary margin defense lever against independent transcoding vendors. For New Entrants and Emerging Players: Differentiate on regional-language transcoding specialization for India's OTT infrastructure buildout, where Reliance Jio and Disney+ Hotstar expansion creates white-space demand. Target synthetic media watermarking compliance pipelines ahead of EU AI Act enforcement deadlines. A channel partnership route through Berlin and Munich production hubs offers viable go-to-market positioning. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-commoditization play because encoding throughput increasingly embeds within cloud compute bundles rather than standing as discrete procurement categories. Acquisition targets should display kernel-level GPU optimization capabilities for FFmpeg and NVENC pipelines. The signal to watch is AV1 adoption velocity across browser-based streaming environments, which erodes patent-encumbered codec leverage and redistributes value toward edge-compute infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Node Partnership with 5G Carriers | Compresses latency for live sports rights holders deploying mobile-first distribution in the United States. |
| Multi-Codec Hardware Certification | Extends product development timelines but qualifies encoders for simultaneous H.264, HEVC, and AV1 output. |
| Patent Royalty Absorption into Bundled Pricing | Cloud hyperscalers obscure licensing costs while independent platforms face per-stream cost inflation. |
| Synthetic Media Watermarking Pipeline Development | Positions vendors ahead of ETSI enforcement deadlines for French and German public-service broadcasters. |
| Regional-Language Transcoding Scale-Up | Captures demand from Reliance Jio and Disney+ Hotstar expansion across South Asian language markets. |
Research Approach
A standing panel of cloud platform engineers, broadcast technology procurement leads, and streaming operations directors provided ongoing calibration across primary interviews, validated against hyperscaler capex disclosures, FCC filing databases, ETSI standards documentation, and patent pool royalty schedules. Bottom-up transcoding volume estimates triangulated with top-down infrastructure spending analysis.
Consistency checks against external benchmarks validated projection outputs across the analysis window, with segmentation modeling across service type, content velocity tier, delivery latency requirement, and end-user compliance exposure. CAGRs derived from encoder shipment trajectories and streaming platform library refresh cycles, incorporating 8K broadcast trial timelines from KBS and MBC as format migration inputs.
Material uncertainties — codec patent pool litigation outcomes, sovereign data-localization mandate expansion, and Taiwan fabrication capacity disruption — sit outside the modeled envelope. Forecasts reflect assumptions around continued HEVC-to-AV1 transition velocity and sustained hyperscaler infrastructure investment levels. Revision becomes warranted when AV1 browser penetration crosses thresholds that fundamentally restructure royalty-bearing codec economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Streaming Media Device Market
Digital Media
Video Wall Market
Digital Media
LED Stadium Screens Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Sound Effects Services Market
Digital Media
North America Online Gambling Market
Digital Media
Digital Video Advertising Market
Digital Media
Visual Effects (VFX) Market
Digital Media
Webcomics Market
Digital Media
Digital Content Market
Digital Media
Japan Webtoons Market
Digital Media
Europe Location-Based Entertainment Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Anime Market
Digital Media
Video Content Management Market
Digital Media
Adult Entertainment Market