
 Arnica Montana Market | 2026-2036
Arnica Montana Market Size, Share, and Industry Trends Forecast 2026-2036
Arnica Montana Market Analytics
European cultivator networks in France and Romania is expanding raw botanical output for Arnica montana extraction. Boiron leverages integrated cultivation sites across the French Alps to secure standardized sesquiterpene lactone concentrations. Herb Pharm sustains wildcrafting partnerships in the Pacific Northwest to differentiate its tincture portfolio. Hänseler AG anchors European pharmacy distribution through its Swiss manufacturing base.
Arnica montana denotes a perennial Asteraceae species whose flowering heads yield helenalin and related sesquiterpene lactones through ethanol or supercritical CO2 extraction; these bioactive compounds serve primarily as anti-inflammatory and analgesic agents in topical and oral homeopathic preparations. Topical cream and gel formats dominate current volume as consumers prioritize direct-application pain relief, while tincture formulations represent the fastest-expanding category among healthcare professionals seeking dose-flexible protocols. Wellness clinics and pharmacies concentrate margin pools through professional-grade dispensing relationships that command premium positioning over supermarket channels.
The European Medicines Agency governs THMPD compliance for oral Arnica products, while the FDA regulates topical preparations under OTC monograph standards that restrict concentration claims and therapeutic indications. Germany's national pharmacy regulator enforces BfArM documentation requirements that elevate entry barriers for non-EU suppliers. Stakeholders must monitor evolving pharmacovigilance reporting obligations that could reshape labeling requirements and distribution eligibility across key European markets.
Market Dynamics
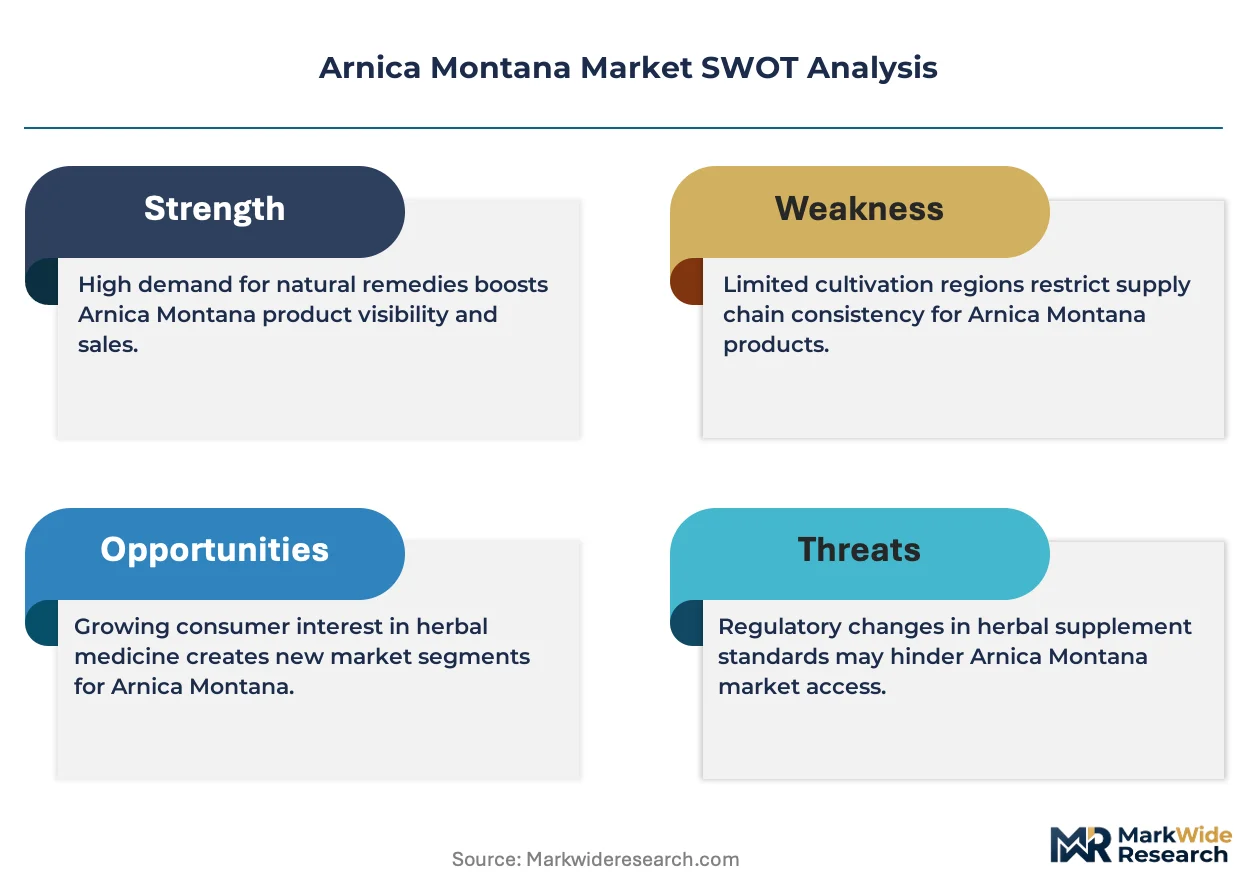
The Arnica Montana market is being reshaped by the EU Traditional Herbal Medicinal Products Directive, which forces manufacturers to choose between costly full marketing authorization and restricted commercial claims. This regulatory bifurcation concentrates investment among established European pharmacy suppliers while marginalizing smaller wildcrafting operations.
Growth Catalysts
- THMPD Registration Pathways:Germany's BfArM documentation requirements create defensible market positions for compliant suppliers, locking in pharmacy shelf access.
- Sports Therapy Integration:Professional athletic training facilities are incorporating topical Arnica protocols into post-injury recovery regimens, expanding institutional purchasing.
- Sesquiterpene Standardization:Supercritical CO2 extraction technology enables precise helenalin concentration control, satisfying pharmacopeial consistency demands.
Market Restraints
- Wild Population Depletion:Alpine habitat loss and overharvesting pressure in Romanian Carpathian zones constrain raw material availability for non-cultivated supply chains.
- FDA OTC Monograph Restrictions:The agency's limitation on concentration claims and pain-relief indications caps US market positioning for oral preparations.
- Synthetic Anti-Inflammatory Substitution:Diclofenac and ibuprofen gel formulations compete directly on price and immediate efficacy in mass retail channels.
Strategic Opportunities
- Wellness Clinic Penetration:France's expanding network of integrated medicine centers offers professional-grade dispensing relationships outside pharmacy gatekeeping.
- Supercritical CO2 Tincture Innovation:Converging extraction precision with homeopathic dilution protocols creates dose-flexible products for integrative healthcare practitioners.
- Swissmedic Fast-Track Procedures:Switzerland's streamlined herbal product registration attracts manufacturers seeking European market entry with reduced documentation burdens.
Industry Challenges
- Pharmacognosy Expertise Scarcity:Botanical identification and sesquiterpene assay skills are thinning across European analytical laboratories, extending quality control timelines.
- Legacy ERP Integration:Batch-specific traceability requirements for THMPD compliance force expensive software reconfigurations at mid-sized manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arnica Montana Market |
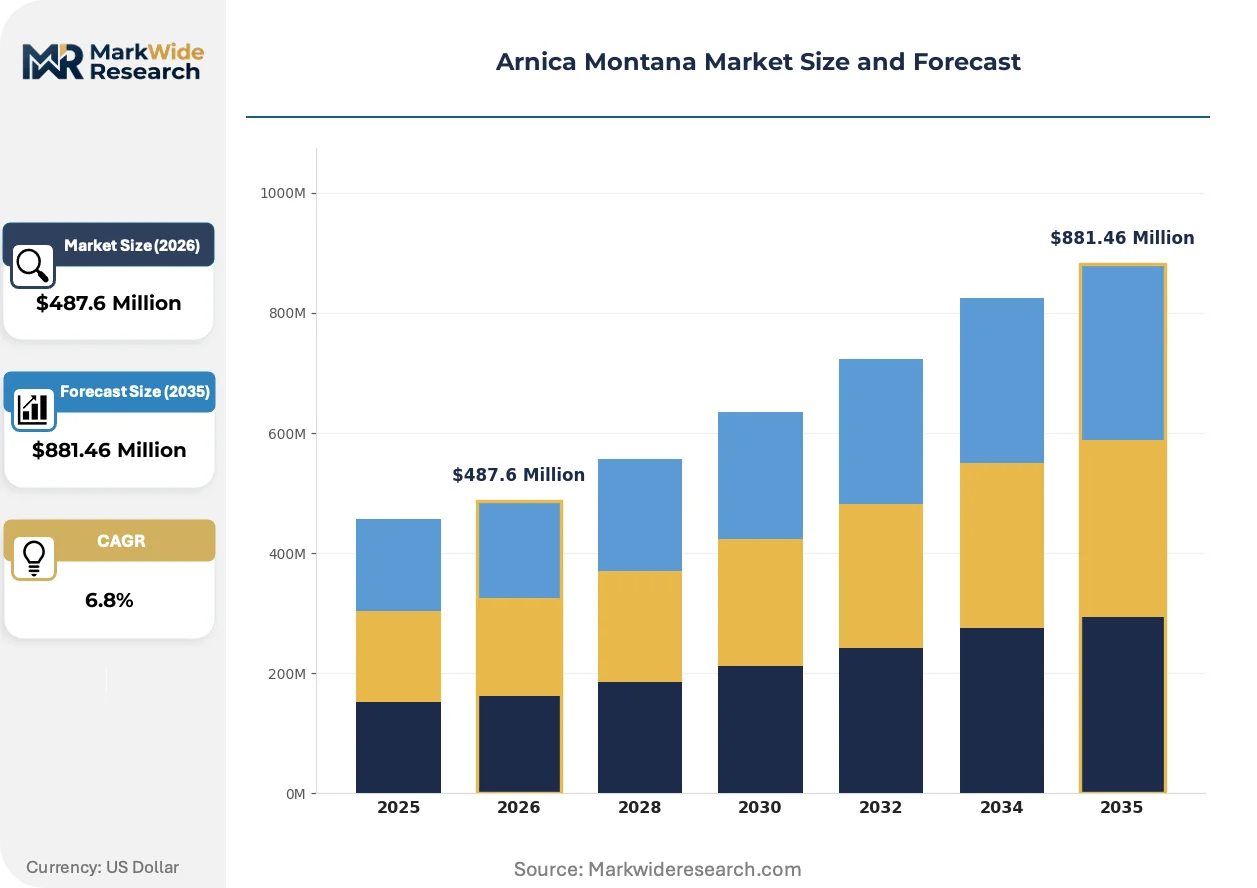
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Cream, Gel, Ointment, Tincture Form: Liquid, Powder, Capsule, Tablet End User: Consumers, Healthcare Professionals, Wellness Clinics, Pharmacies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Stores |
| Companies Covered | Hyland's, BO International, Boiron, From Nature With Love, Badger Company, Weleda, De La Cruz, Hänseler AG, Herb Pharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arnica Montana Market Evolving Landscape
Supercritical extraction technologies and evolving professional dispensing channels are compressing traditional supply hierarchies. Manufacturers are repositioning around standardization capabilities and direct practitioner relationships.
Supercritical CO2 extraction systems are absorbing capital investment from ethanol-based infrastructure across French and Swiss processing facilities. Wellness clinics and compounding pharmacies are adopting these standardized inputs to reduce batch-to-batch variability in custom formulations. The technology is absorbing market share from conventional tincture suppliers unable to document precise sesquiterpene profiles.
REACH registration requirements for novel extraction solvents are extending compliance timelines for European manufacturers reformulating product lines. The European Chemicals Agency's substance evaluation protocols now capture residual solvent specifications previously governed only by pharmacopeial monographs. German and Austrian suppliers are absorbing these costs through dedicated regulatory affairs teams, while smaller operators exit oral product categories.
Direct-to-practitioner distribution is displacing wholesale pharmacy intermediaries for professional-grade Arnica lines. Integrative medicine clinics in Bavaria and Baden-Württemberg are establishing captive purchasing agreements with certified cultivators, bypassing traditional pharmaceutical distribution markups. This channel compression is most visible in southern Germany's dense network of Heilpraktiker practices.
Arnica Montana Market Segmentation
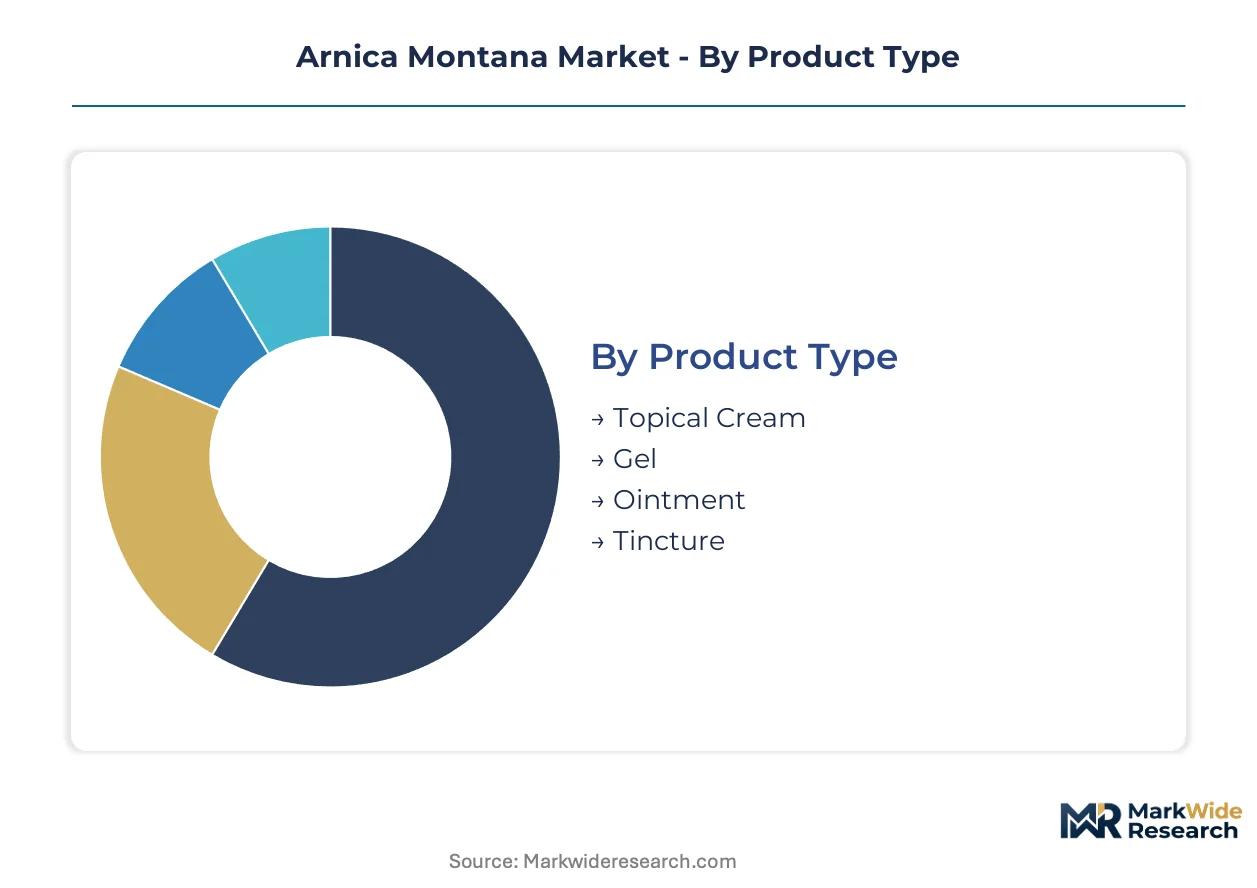
Arnica Montana product positioning hinges on formulation chemistry, professional versus self-directed use, and regulatory pathway complexity. Segmentation reveals how extraction technology and distribution access create divergent margin structures across the value chain.
Product Type:
Buyers differentiate by application mechanics and absorption kinetics rather than active ingredient concentration alone.
- Topical Cream:Oil-in-water emulsions with 20-30% lipid content enable rapid skin penetration for acute bruising applications. German pharmacy chains prioritize cream formats for homeopathic prescribing protocols due to patient familiarity and dosing consistency.
- Gel:Hydroalcoholic matrices with carbomer thickeners deliver faster drying and non-greasy residue for athletic training environments. Sports therapy centers in France and Switzerland specify gel formats for locker-room dispensing where clothing contact matters.
- Ointment:Occlusive petrolatum-based vehicles with enhanced epidermal retention suit chronic joint applications. Traditional pharmacy customers in Alpine regions maintain preference for ointment textures despite slower absorption profiles.
- Tincture:Ethanol-based extracts with standardized sesquiterpene lactone content enable dose-flexible protocols for integrative practitioners. Supercritical CO2 extraction advances are compressing batch variability for professional-grade tincture suppliers.
Volume sits with Topical Cream; growth tilts toward Tincture.
Form:
Manufacturing infrastructure and stability requirements separate liquid investments from solid-dose capital allocation.
- Liquid:Aqueous and hydroalcoholic solutions with documented helenalin stability across 24-month shelf lives. Boiron's French Alpine processing facilities concentrate liquid output for pharmacy distribution networks.
- Powder:Spray-dried extracts with defined particle size distributions for compounding pharmacy integration. Swiss manufacturers supply powder inputs to Bavarian Heilpraktiker practices seeking custom formulation flexibility.
- Capsule:Hard gelatin shells containing dried Arnica extract for oral homeopathic preparations. THMPD registration requirements constrain capsule launches to established European suppliers with pharmacovigilance infrastructure.
- Tablet:Compressed dosage forms with excipient matrices protecting sesquiterpene lactones from gastric degradation. German BfArM documentation demands elevate tablet development costs beyond mid-sized manufacturer thresholds.
Manufacturing concentration favors Liquid; tablet development accelerates among THMPD-compliant suppliers.
End User:
Purchasing authority and reimbursement access determine pricing power and formulation sophistication requirements.
- Consumers:Self-directed purchasers responding to bruising and muscle soreness indications through retail channels. French and Romanian consumers demonstrate highest per-capita Arnica familiarity due to traditional medicine continuity.
- Healthcare Professionals:Physicians and homeopathic practitioners prescribing standardized preparations with documented sesquiterpene profiles. German Kassenärztliche Vereinigung recognition expands professional prescribing volumes in statutory health insurance segments.
- Wellness Clinics:Integrated medicine centers combining Arnica protocols with physical therapy and acupuncture services. Baden-Württemberg and Bavaria clinic networks are establishing direct cultivator relationships to bypass pharmaceutical distribution.
- Pharmacies:Licensed dispensaries with mandatory THMPD compliance for oral products and OTC monograph adherence for topicals. German pharmacy regulator enforcement maintains highest entry barriers among European markets.
Pharmacies anchor current volume; wellness clinics are expanding most quickly through direct procurement channels.
Distribution Channel:
Regulatory gatekeeping and customer education requirements stratify channel economics.
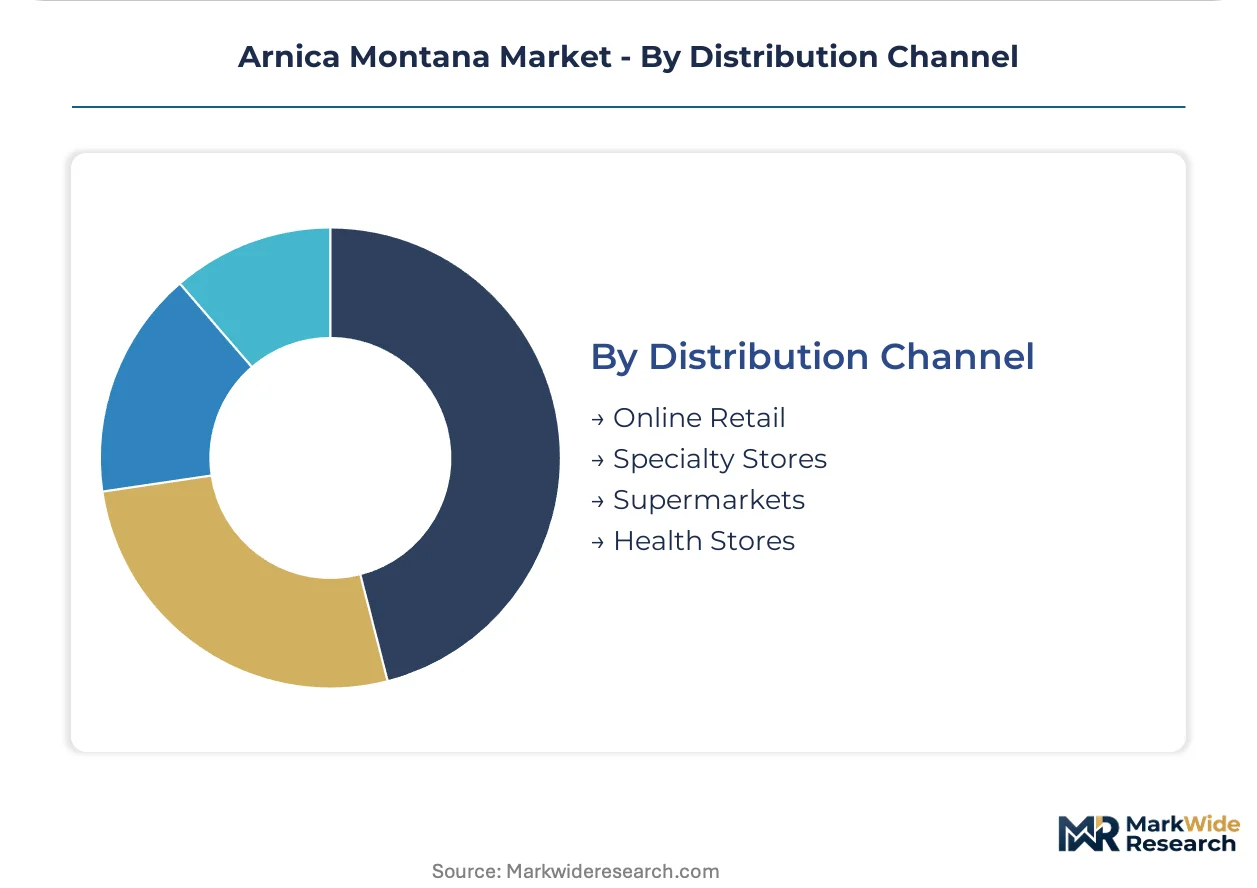
- Online Retail:Direct-to-consumer platforms with variable THMPD compliance enforcement across member states. German and Austrian regulators pursue stricter platform accountability for oral product listings than southern European markets.
- Specialty Stores:Dedicated homeopathic and natural medicine retailers with trained staff capable of explaining potency designations. French réseau de pharmacie partnerships concentrate specialty store presence in urban centers.
- Supermarkets:Mass retail channels limited to topical preparations under simplified regulatory classifications. Price competition with synthetic anti-inflammatory gels constrains Arnica margin recovery in supermarket placements.
- Health Stores:Independent retailers emphasizing organic and wildcrafted sourcing narratives for differentiation. Pacific Northwest wildcrafting partnerships supply distinctive positioning for Herb Pharm and comparable suppliers in North American health store channels.
Pharmacy and specialty store concentration holds volume; online retail climbs fastest where enforcement remains fragmented.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alpine cultivation zones in France and Romania anchor raw material flows for European extraction facilities. German pharmacy networks and Swiss manufacturing bases concentrate finished-product value addition.
Germany
Homeopathic prescribing traditions sustain pharmacy-level demand for standardized Arnica preparations. BfArM documentation requirements enforce strict THMPD compliance for oral products, elevating entry barriers for non-EU suppliers. Bavaria's dense network of Heilpraktiker practices drives direct-procurement relationships with certified cultivators.
France
Integrated medicine centers and wellness clinics expand professional-grade dispensing outside traditional pharmacy channels. ANSM oversight governs herbal product registration and pharmacovigilance reporting obligations. The French Alps host Boiron's cultivation and processing facilities for sesquiterpene-standardized extracts.
Switzerland
Swissmedic's streamlined herbal registration procedures attract manufacturers seeking European market entry with reduced documentation burdens. The country's pharmaceutical manufacturing heritage supports precision extraction capabilities. Basel-Zurich corridor facilities serve as distribution hubs for pharmacy networks across German-speaking markets.
Romania
Carpathian wild populations and expanding cultivator networks supply raw botanical material to European processors. EU habitat regulations constrain overharvesting pressure in alpine zones. Transylvanian collection cooperatives feed extraction facilities in Western Europe.
United States
Pacific Northwest wildcrafting partnerships differentiate premium tincture positioning for natural medicine channels. FDA OTC monograph restrictions limit concentration claims and pain-relief indications for topical preparations. Oregon and Washington State operations supply health store distribution networks.
Arnica Montana Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-practitioner dispensing relationships outside pharmacy intermediaries. The market structures around three maturity tiers: integrated cultivator-extractors with Alpine sourcing control, formulation specialists with THMPD-compliant manufacturing infrastructure, and wildcrafting-dependent suppliers serving premium natural channels. Dominant competitive moves include backward integration into certified cultivation and strategic partnerships with wellness clinic networks.
Among European-integrated suppliers, Boiron and Hänseler AG exemplify the cultivator-manufacturer archetype with Alpine supply chain control. Herb Pharm occupies a distinct position as a North American wildcrafting specialist. These three entities represent divergent sourcing strategies: captive cultivation, pharmacy distribution anchoring, and premium natural-channel differentiation.
| Leading Market Players |
|---|
| Hyland's |
| BO International |
| Boiron |
| From Nature With Love |
| Badger Company |
| Weleda |
| De La Cruz |
| Hänseler AG |
| Herb Pharm |
| Others |
Value Network & Pricing Analysis
EU habitat conservation mandates under the Alpine Convention gate both certified wildcrafting permits and premium-tier Arnica extract pricing. Compliance with Carpathian biodiversity protocols separates pharmacy-grade suppliers from mass-market competitors, concentrating margin capture among documented sustainable harvesters.
Pricing Analysis
Batch-specific sesquiterpene assay warranties differentiate professional-grade tincture pricing from unbundled supermarket offerings. Three-tier pricing structure across premium, standard, and economy levels reflects THMPD registration status, extraction technology, and cultivator certification depth. Cost compression in economy-tier topical gels is intensifying because synthetic diclofenac alternatives undercut herbal positioning in mass retail. Wellness clinics demonstrate lowest price sensitivity due to protocol-driven procurement, while supermarket consumers exhibit highest elasticity.
Supply Chain Analysis
Pharmacognosy workforce scarcity in French and Swiss extraction facilities constrains processing capacity expansion for standardized Arnica outputs. Raw material flows draw from Romanian Carpathian wild populations, French Alpine cultivator cooperatives, and Pacific Northwest wildcrafting partnerships. Helenalin-rich flower heads, supercritical CO2 extraction equipment, and certified organic solvents anchor upstream dependencies. Single-source vulnerability concentrates in Transylvanian collection cooperatives feeding Western European processors. Distribution runs through pharmacy wholesale networks in German-speaking markets, direct-to-practitioner channels in French wellness clinics, and health store independents in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Arnica Montana market operates as a cost-of-compliance story where Germany's BfArM documentation requirements erect barrier-to-entry moats favoring established THMPD-registered suppliers.
For Market Incumbents: Acquire certified Alpine cultivation acreage to secure captive helenalin supply against Romanian wild population depletion. Consolidate backward integration into French and Swiss processing infrastructure to defend margin position against supercritical CO2 technology entrants. Lock in multi-year dispensing agreements with Bavarian Heilpraktiker networks before wellness clinic procurement shifts fully to direct cultivator relationships. For New Entrants and Emerging Players: Supercritical CO2 extraction precision offers a technology-first wedge into professional-grade tincture segments where batch variability tolerance is collapsing. Target Baden-Württemberg wellness clinics as the most penetrable end-user channel outside pharmacy gatekeeping. Pursue Swissmedic fast-track registration to bypass EMA documentation burdens while accessing German-speaking pharmacy networks. For Investors and Strategic Acquirers: BfArM oral product registration approvals for new capsule formulations is the leading indicator that compliance infrastructure investments are yielding defensible market positions. Five-to-ten year viability favors integrated cultivator-extractors with Alpine supply chain control over formulation-dependent toll manufacturers. Watch for pharmacovigilance reporting obligation expansions that would force additional labeling investments and reshape acquisition target valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Cultivation | Captive Alpine supply secures helenalin consistency against Romanian habitat constraints. |
| Supercritical CO2 Extraction Scale-Up | Precise sesquiterpene control satisfies pharmacopeial demands from German pharmacy networks. |
| THMPD Registration Pathway Completion | BfArM compliance unlocks statutory health insurance reimbursement for oral preparations. |
| Direct-to-Practitioner Distribution Buildout | Bypassing pharmaceutical intermediaries captures margin pools in French wellness clinic expansion. |
| Swissmedic Fast-Track Registration | Streamlined herbal approval reduces documentation burdens for European market entry. |
Research Methodology
EMA regulatory filings, BfArM registration databases, and ANSM pharmacovigilance reports formed the secondary backbone of this study. Primary interviews with homeopathic pharmacy procurement managers, Alpine cultivator cooperative directors, supercritical extraction equipment suppliers, wellness clinic protocol designers, and THMPD regulatory consultants validated demand assumptions and pricing structures. Bottom-up cultivation volume estimates and top-down pharmacy dispensing data were triangulated to anchor market sizing.
Bottom-up modeling tracked Arnica flower harvest volumes, extraction yields, and formulation throughput across French, Swiss, and Romanian processing facilities. Top-down validation cross-referenced pharmacy distribution data, health store retail audits, and online platform transaction patterns. Segmentation dimensions included product type, form, end-user category, and distribution channel complexity. CAGRs were derived from regression analysis of historical dispensing growth and projected wellness clinic penetration rates across the analysis window. Helenalin standardization adoption curves and THMPD registration completion timelines served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential EMA reclassification of oral Arnica preparations, abrupt Romanian habitat protection enforcement, and FDA OTC monograph revisions for topical concentration claims. Forecasts reflect documented assumptions regarding regulatory stability and cultivator network expansion trajectories. Material deviation in Alpine climate patterns, wild population census results, or pharmacovigilance reporting thresholds warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Okra Seed Market
Seeds
Flax Crop Market
Seeds
Pumpkin Seeds Market
Seeds
United States Garden Seeds Market
Seeds
North America Alfalfa Seed Market
Seeds
Cucumber Seeds Market
Seeds
Africa Peas Market
Seeds
Global Sorghum Seed Market
Seeds
North America Tomato Seed Market
Seeds
North America Maize Seed Treatment Market
Seeds
Buckwheat Market
Seeds
Dodder Seed Market
Seeds
Spain Forage Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Sesame Seeds Market
Seeds
North America Vegetable Seed Market