
 Seaweed Cultivation Market | 2026-2036
Seaweed Cultivation Market Size, Share, and Industry Trends Forecast 2026-2036
Seaweed Cultivation Market Insights
Multi-source contracting for seed stock and processed biomass is decoupling from the traditional single-farm dependency that once locked buyers into narrow geographic supply zones. Cargill, Incorporated leverages its global commodity infrastructure to aggregate seaweed-derived hydrocolloids across multiple origin points. Qingdao Bright Moon Seaweed Group Co., Ltd. anchors China's domestic carrageenan and alginate output through backward integration into hatchery operations.
Seaweed cultivation denotes the controlled growth of marine macroalgae in open-water, nearshore, or land-based systems, typically requiring salinity between 30-35 ppt and photon flux densities of 100-400 μmol m⁻² s⁻¹ for optimal photosynthetic efficiency; the primary purpose spans food-grade hydrocolloid extraction, bioactive compound recovery, and regenerative ocean farming. Nori dominates volume flows into food ingredients, while nutraceutical applications command premium positioning due to fucoidan and phlorotannin concentration thresholds. Wild harvesting retains cost advantages in artisanal supply tiers, though aquaculture methods are displacing uncontrolled collection as regulatory frameworks mandate traceable biomass chains.
China's SAMR enforces GB standards on heavy-metal limits in edible seaweed, while the EU EFSA reviews novel food dossiers for invasive species like Asparagopsis taxiformis in feed applications. Japan's METI promotes blue carbon credits through certified seaweed farm registration, directly incentivizing capital deployment into offshore longline infrastructure. Stakeholders must monitor how carbon accounting methodologies and marine spatial planning permits reshape site eligibility before committing to multi-year lease structures.
Market Dynamics
Integrated multi-trophic aquaculture systems are consolidating production scale in East Asian coastal zones, compressing the traditional fragmented farm structure into vertically coordinated supply networks that centralize seed stock quality control and biomass traceability.
Growth Catalysts
- EU EFSA novel food pathways:Asparagopsis taxiformis feed approvals are opening methane-reduction markets for livestock integrators seeking verified carbon intensity reductions in ruminant protein supply chains.
- Japan METI blue carbon credits:Certified seaweed farm registration creates direct revenue stacking for offshore longline operators beyond commodity biomass sales alone.
- Hydrocolloid substitution in plant-based formulations:Food manufacturers are reformulating with carrageenan and alginate to replace synthetic stabilizers in clean-label product lines.
Market Restraints
- Seed stock genetic bottleneck:Narrow cultivar diversity in Porphyra and Saccharina germplasm banks concentrates yield vulnerability to warming sea surface temperatures.
- China SAMR heavy-metal enforcement:Stricter GB standard testing cadences for arsenic and cadmium in edible seaweed are disqualifying legacy drying and processing infrastructure.
- Wild harvest cost undercutting:Uncontrolled collection in artisanal fisheries in Indonesia and the Philippines maintains price floors below aquaculture breakeven for lower-grade hydrocolloid feedstock.
Strategic Opportunities
- Offshore deep-water longline expansion:Norway and Scotland are licensing marine spatial zones beyond territorial limits for kelp cultivation at industrial scale.
- Fucoidan nutraceutical extraction:Pharmaceutical-grade bioactive compound recovery commands 15-40x commodity biomass pricing for certified organic Undaria pinnatifida.
- Biorefinery co-location with aquaculture waste streams:Nutrient recycling from salmon and shellfish operations reduces synthetic fertilizer dependency in IMTA configurations.
Industry Challenges
- Marine spatial planning permit timelines:Multi-year lease structures in crowded nearshore zones delay capital deployment and create site access uncertainty.
- Carbon accounting methodology standardization:Divergent protocols for blue carbon quantification complicate credit monetization and investor due diligence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seaweed Cultivation Market |
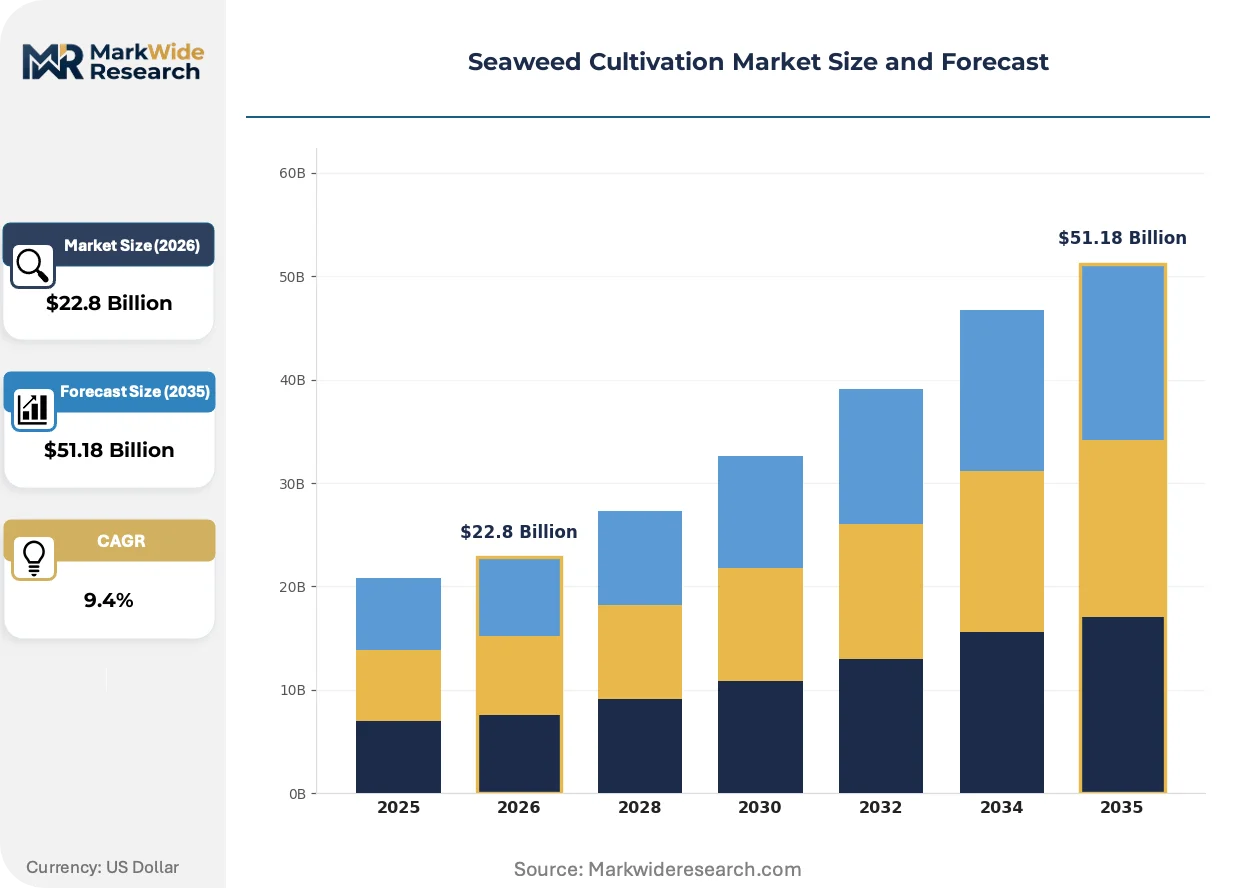
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $51.18 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nori, Dulse, Wakame, Kombu End User: Food Industry, Pharmaceuticals, Cosmetics, Biofuels Method: Wild Harvesting, Aquaculture, Hatchery, Integrated Multi-Trophic Aquaculture Application: Food Ingredients, Nutraceuticals, Animal Feed, Bioplastics |
| Companies Covered | Cargill, Incorporated, DuPont, Groupe Roullier, CP Kelco U.S., Inc., Qingdao Bright Moon Seaweed Group Co., Ltd., Qingdao Seawin Biotech Group Co., Ltd., Acadian Seaplants, The Seaweed Company, Gelymar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seaweed Cultivation Market Trends and Innovations
Automation in seeding and harvesting operations is compressing labor intensity while sensor-based water quality monitoring is enabling predictive cultivation management across dispersed farm networks.
Integrated sensor-robotics platforms are integrating photon flux and nutrient dosing algorithms to optimize Saccharina latissima growth rates in land-based tank systems. Nordic kelp cooperatives are deploying these systems to shorten production cycles from 18 to 12 months. The technology is integrating hatchery-to-harvest data layers that compress quality assurance costs for hydrocolloid processors.
China's GB standards for aquaculture traceability are mandating blockchain-linked biomass documentation from seed stock origin through processing. SAMR enforcement actions against non-compliant dried nori shipments are accelerating farm-level digitization investments. Smaller Fujian and Shandong operators face disproportionate compliance burdens relative to backward-integrated processors with captive hatcheries.
Ingredient procurement from seaweed-derived hydrocolloids is consolidating toward multi-year offtake contracts with specified carbon intensity thresholds. Plant-based meat and dairy formulators in North America and Western Europe are requiring third-party verified origin documentation that excludes wild-harvested material. This specification shift favors aquaculture-sourced alginate and carrageenan with chain-of-custody certification.
Seaweed Cultivation Market Segmentation
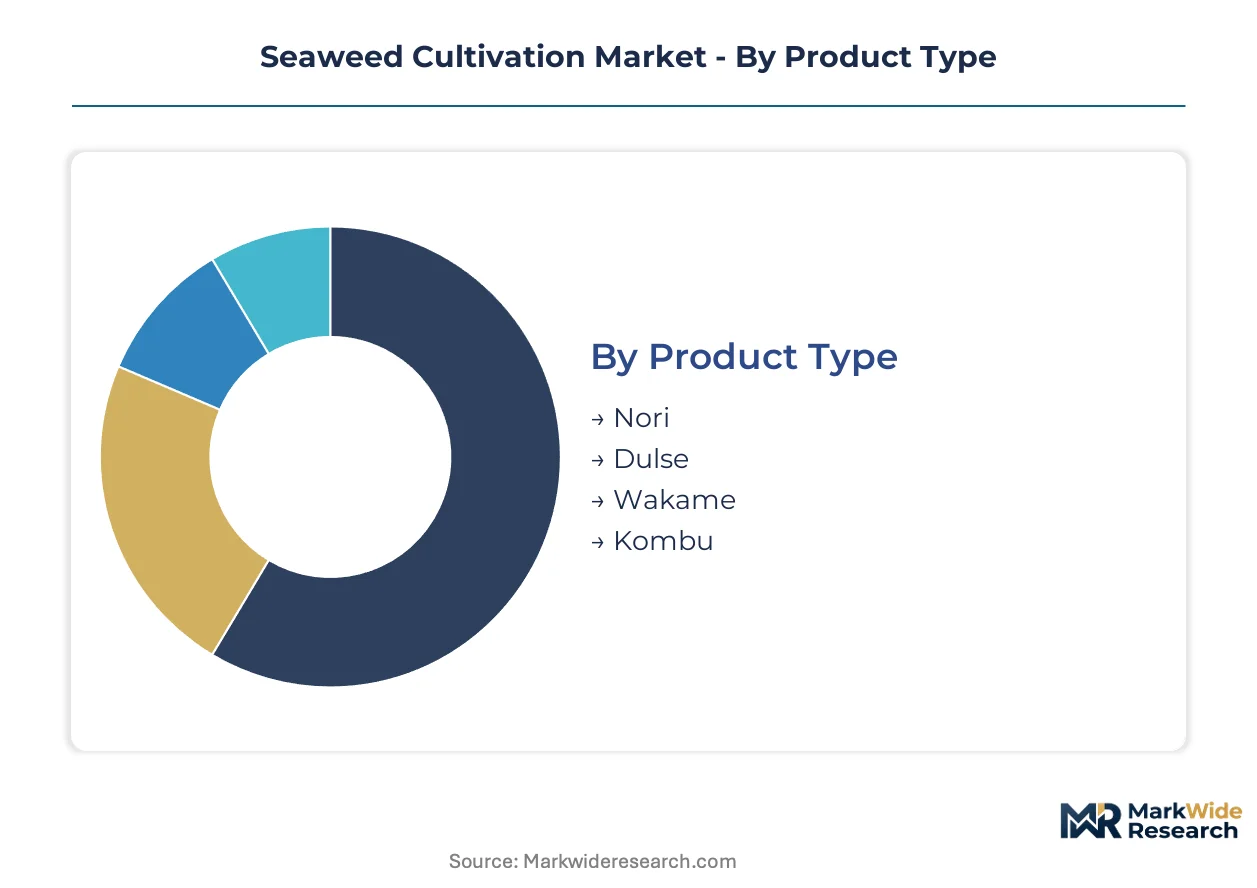
Seaweed cultivation segments diverge sharply by processing intensity and regulatory burden. Food-grade hydrocolloids demand traceable aquaculture chains, while nutraceutical extraction requires pharmaceutical-grade bioactive concentration thresholds.
Product Type:
Standardization dominates commodity grades, whereas premium tiers demand cultivar-specific cultivation protocols and harvest timing precision.
- Nori:Thin-sheet red algae of the genus Porphyra, cultivated on intertidal nets or floating rafts with 45-60 day grow-out cycles. Demand concentrates in Japan's sushi supply chains and China's processed snack sector, where SAMR's GB standards for arsenic limits are disqualifying non-compliant drying operations.
- Wakame:Brown kelp Undaria pinnatifida requiring cold nutrient-rich waters and 6-8 month cultivation periods for optimal fucoidan content. South Korea's Jeolla province and China's Dalian coastal zones anchor production, with pharmaceutical-grade extraction commanding premium positioning over commodity food uses.
- Dulse:Red algae Palmaria palmata harvested from rocky North Atlantic substrates.
- Kombu:Laminaria species dried for dashi stock and hydrocolloid extraction in Hokkaido processing facilities.
Leading the category by volume: Nori. Growing fastest: Wakame.
End User:
Cost tiers separate artisanal procurement from industrial-scale offtake with certified chain-of-custody documentation.
- Food Industry:Hydrocolloid processors, plant-based meat formulators, and clean-label stabilizer manufacturers requiring carrageenan and alginate with verified aquaculture origin. EFSA novel food pathways for invasive species feedstocks are opening methane-reduction applications in European livestock operations.
- Pharmaceuticals:Fucoidan, phlorotannin, and laminarin extraction for oncology and immunomodulatory drug candidates. Japan's PMDA and South Korea's MFDS enforce GMP compliance for marine-derived active pharmaceutical ingredients, concentrating contract manufacturing in certified biorefinery clusters.
- Cosmetics:Marine bioactive incorporation into anti-aging and hydration formulations.
- Biofuels:Third-generation ethanol and biogas feedstock from high-yield kelp biomass.
Dominant by revenue concentration: Food Industry. Steepest expansion trajectory: Pharmaceuticals.
Method:
Volume scalability inversely correlates with operational control and genetic traceability.
- Aquaculture:Controlled nearshore longline or raft systems with hatchery-propagated seed stock, enabling year-round biomass predictability. China's Shandong and Fujian provinces concentrate industrial scale, where backward integration into captive hatchery operations compresses quality assurance costs for hydrocolloid processors.
- Integrated Multi-Trophic Aquaculture:Co-cultivation with finfish or shellfish species recycling nutrient waste streams. Norway and Scotland are licensing offshore zones beyond territorial limits for kelp-salmon IMTA configurations, reducing synthetic fertilizer dependency while stacking carbon credit revenues.
- Wild Harvesting:Uncontrolled collection from natural beds, retaining cost advantages in Indonesian and Philippine artisanal supply tiers.
- Hatchery:Land-based seed stock propagation and genetic improvement facilities.
Fastest scaling: Integrated Multi-Trophic Aquaculture. Largest current footprint: Aquaculture.
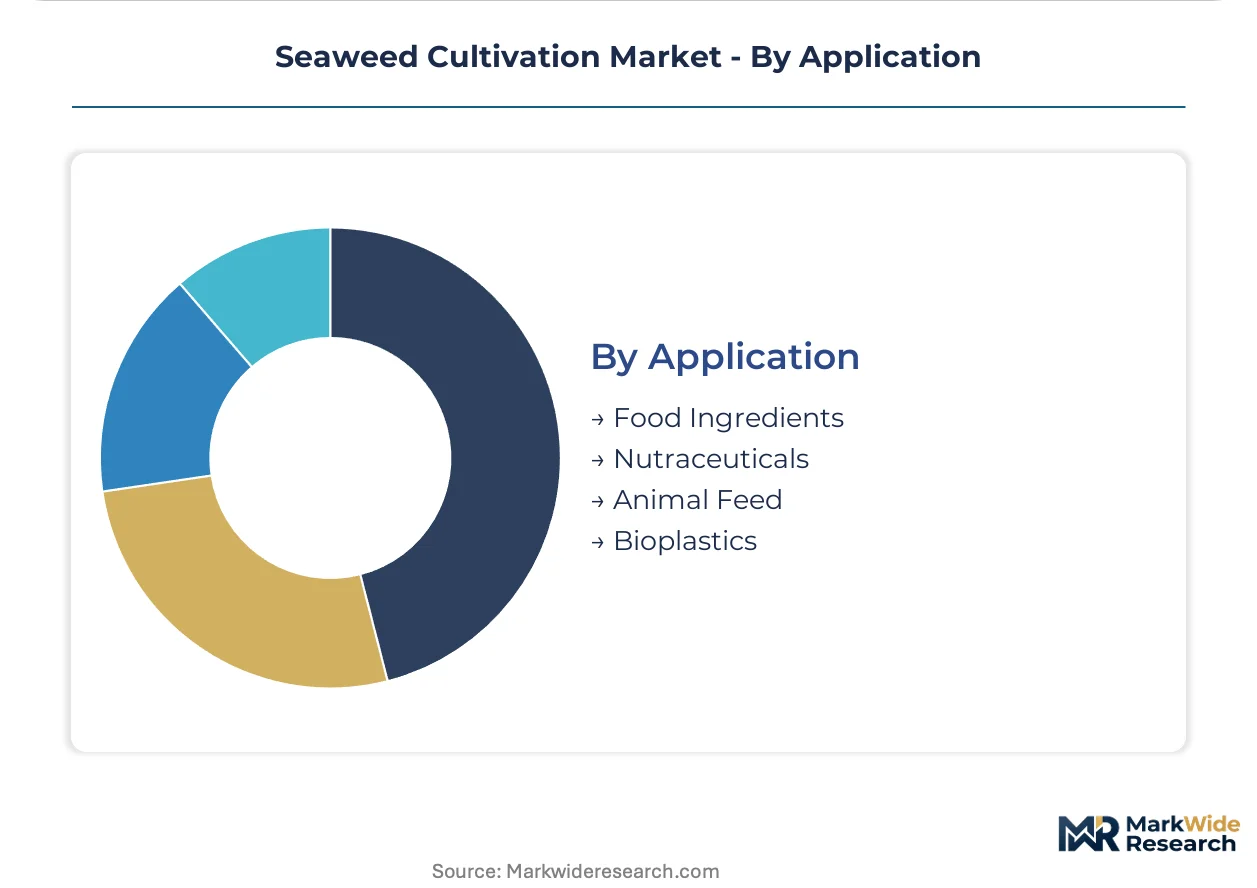
Application:
Margin structures diverge by certification grade and bioactive concentration thresholds.
- Nutraceuticals:Standardized fucoidan, astaxanthin, and omega-3 fatty acid extraction for dietary supplements and functional foods. Third-party organic certification and heavy-metal testing protocols command 15-40x commodity biomass pricing, with Japan's METI blue carbon credits providing additional revenue stacking for certified farm registration.
- Food Ingredients:Hydrocolloid recovery for texture modification and clean-label stabilization. North American and Western European plant-based meat formulators are mandating aquaculture-sourced alginate and carrageenan with verified origin documentation, excluding wild-harvested material from approved supplier lists.
- Animal Feed:Asparagopsis taxiformis supplementation for ruminant methane reduction.
- Bioplastics:Alginate and carrageenan film formulations for biodegradable packaging.
Highest margin capture: Nutraceuticals. Broadest volume base: Food Ingredients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's kelp longlines anchor Asia-Pacific biomass flows, while Norway's offshore licensing and Scotland's IMTA zones reshape Atlantic cultivation economics. Regulatory divergence across SAMR, EFSA, and METI frameworks is redrawing site eligibility and carbon credit stacking.
China
Shandong and Fujian provinces concentrate industrial-scale raft and longline systems for hydrocolloid-grade kelp and nori. SAMR's tightened GB standards on arsenic and cadmium are disqualifying legacy drying infrastructure. Qingdao processing clusters are absorbing smaller operators through backward integration into captive hatcheries.
Japan
Hokkaido's kombu drying facilities and Kyushu's wakame rafts serve food and nutraceutical offtake channels. METI's certified seaweed farm registration enables blue carbon credit revenue stacking beyond commodity sales. Tokyo-based processors are mandating blockchain-linked traceability for export-grade biomass.
South Korea
Jeolla province's Undaria pinnatifida farms supply pharmaceutical-grade fucoidan extraction for MFDS-regulated active pharmaceutical ingredients. Coastal zone permits are tightening under revised fisheries management frameworks. Busan biorefinery clusters are consolidating contract manufacturing for oncology drug candidates.
Norway
Offshore longline licensing beyond territorial limits is enabling industrial kelp scale without nearshore spatial conflicts. Salmon-IMTA configurations recycle aquaculture waste streams into Saccharina latissima nutrient inputs. Bergen and Trondheim research cooperatives are deploying sensor-robotics platforms to compress grow-out cycles.
Scotland
Marine spatial planning in the Highlands and Islands is allocating zones for kelp-salmon IMTA systems with carbon credit eligibility. Edinburgh-based processors are securing multi-year offtake contracts specifying aquaculture-only origin documentation. Wild harvest price undercutting from Icelandic artisanal fisheries pressures lower-grade hydrocolloid margins.
Seaweed Cultivation Market Competitive Landscape
Global majors compete with regional champions across hydrocolloid aggregation and captive hatchery control. The vendor base stratifies between commodity-grade biomass traders and vertically integrated processors with in-house seed stock propagation. Three archetypes dominate: multinational food ingredient aggregators, backward-integrated Chinese processors, and Nordic offshore cultivation specialists. Competitive moves center on multi-origin supply contracting and marine spatial zone pre-emption through early licensing.
Within the multinational aggregator tier, Cargill, Incorporated leverages global commodity infrastructure to aggregate seaweed-derived hydrocolloids across multiple origin points. Qingdao Bright Moon Seaweed Group Co., Ltd. and Qingdao Seawin Biotech Group Co., Ltd. exemplify Chinese processors with upstream hatchery control over Shandong and Fujian production bases. Acadian Seaplants occupies a position bridging North American wild harvest sourcing and aquaculture diversification.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DuPont |
| Groupe Roullier |
| CP Kelco U.S., Inc. |
| Qingdao Bright Moon Seaweed Group Co., Ltd. |
| Qingdao Seawin Biotech Group Co., Ltd. |
| Acadian Seaplants |
| The Seaweed Company |
| Gelymar |
| Others |
Pricing and Supply Chain Analysis
Seed stock propagation costs cascade through three distinct pricing tiers for hydrocolloid-grade biomass, with hatchery-controlled supply commanding premium positioning over wild-harvested alternatives in buyer qualification protocols. China's SAMR enforcement of GB arsenic limits has compressed margins for legacy drying operations while concentrating pricing power among backward-integrated processors with captive germplasm banks.
Pricing Analysis
Certification bundling separates aquaculture-origin alginate and carrageenan from unverified wild-harvested material, with third-party chain-of-custody documentation now standard in North American and Western European plant-based meat formulator contracts. Three-tier pricing structure across premium, standard, and economy levels reflects heavy-metal testing cadences, organic certification status, and carbon intensity thresholds. Pricing pressure stems from Indonesian and Philippine artisanal wild harvest undercutting aquaculture breakeven for lower-grade hydrocolloid feedstock. Food-grade hydrocolloid processors exhibit highest price sensitivity due to commodity substitution options, while pharmaceutical-grade fucoidan extraction tolerates significant premium capture.
Supply Chain Analysis
Dual-sourcing mandates from Cargill and CP Kelco require qualified suppliers across China's Shandong and Fujian provinces plus Norway's emerging offshore zones to mitigate single-origin vulnerability. Raw material dependencies center on Porphyra and Saccharina germplasm, synthetic fertilizer inputs for non-IMTA configurations, and energy-intensive drying infrastructure. Supply chain risk concentrates in marine spatial planning permit delays that freeze site access for multi-year lease structures. Distribution runs through Qingdao and Dalian processing clusters for Asian hydrocolloid aggregation, with Bergen and Trondheim cooperatives emerging as Atlantic consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine spatial planning permit scarcity constrains site expansion velocity, propping pricing power for incumbent operators with pre-leased offshore zones and backward-integrated hatchery capacity.
For Market Incumbents: Lock in multi-year offtake contracts with specified carbon intensity thresholds before Norway and Scotland license additional offshore zones to new entrants. Prioritize sensor-robotics platform deployment across Saccharina latissima operations to compress grow-out cycles from 18 to 12 months, defending margin position against Nordic cooperative cost structures. Certify additional farm sites under Japan's METI blue carbon credit framework to stack revenue beyond commodity biomass sales. For New Entrants and Emerging Players: Capture pharmaceutical-grade fucoidan extraction contracts from South Korea's MFDS-regulated biorefinery clusters, where oncology drug candidate demand outstrips certified organic Undaria pinnatifida supply. Target Scotland's Highlands and Islands marine spatial zones for kelp-salmon IMTA configurations with carbon credit eligibility, leveraging Edinburgh processor mandates for aquaculture-only origin documentation. Lead with blockchain-linked traceability systems that satisfy China's SAMR GB standards compliance requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor hatchery-controlled processors in China's Fujian province facing disproportionate SAMR compliance burdens relative to backward-integrated competitors. Long-term viability hinges on captive germplasm banks and marine spatial zone pre-emption through early licensing. Watch for carbon accounting methodology standardization breakthroughs as the inflection signal triggering institutional capital deployment into blue credit revenue stacking.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Spatial Zone Pre-emption | Early licensing in Norway and Scotland secures offshore longline capacity before regulatory saturation. |
| Hatchery Backward Integration | Captive Porphyra germplasm banks compress quality assurance costs for hydrocolloid processors under SAMR scrutiny. |
| Blue Carbon Credit Certification | METI-registered farm status enables revenue stacking beyond commodity biomass in Japanese markets. |
| Sensor-Robotics Platform Deployment | Photon flux optimization algorithms shorten kelp production cycles and reduce labor intensity. |
| Blockchain Traceability Implementation | SAMR-mandated biomass documentation from seed stock origin accelerates farm-level digitization investments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving hatchery operators, hydrocolloid procurement managers, marine spatial planning officers, and biorefinery technical directors. SAMR enforcement actions, EFSA novel food dossiers, and METI certification registries provided regulatory trajectory validation. Bottom-up farm-level capacity estimates reconciled against top-down hydrocolloid trade flow analysis.
Data-stream reconciliation across cultivation method, product type, and end-use segmentation dimensions enabled volume and value modeling throughout the forecast period. CAGRs derived from historical production trajectory analysis adjusted for marine spatial permitting velocity and carbon credit monetization feasibility. Industry-specific inputs incorporated kelp grow-out cycle compression rates from Nordic sensor-robotics deployments and germplasm bank concentration indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon accounting methodology standardization and marine spatial zone allocation policy shifts. Deviation in EFSA Asparagopsis taxiformis feed approval timelines or China SAMR heavy-metal enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
APAC Aquafeed Market
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
Marine Life Raft Market
Aquaculture Innovations
South America Aqua Feed Market
Aquaculture Innovations
Vietnam Aquafeed Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
Microalgae-Based Aquafeed Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Aquaculture Healthcare Market