
 Shrimp Feed Market | 2026-2036
Shrimp Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Shrimp Feed Market Intelligence
Aquaculture nutrition expertise is bifurcating the competitive landscape, as specialized formulators pull ahead of generalist feed compounders. BioMar Group leverages its marine research stations in Denmark and Norway to sustain premium product pipelines for intensive vannamei systems. Charoen Pokphand Foods anchors its feed dominance across Thailand through captive supply of key ingredients and direct mill-to-farm distribution networks. Cargill, Incorporated competes via its integrated aquaculture platforms that extend from soy protein processing to finished shrimp feed delivery.
Shrimp feed denotes formulated diets engineered to deliver precise protein levels, lipid profiles, and micronutrient balances required by penaeid species across larval, post-larval, and grow-out stages; extrusion and pelleting processes gelatinize starches and improve water stability, reducing nutrient leaching in pond environments. Pelleted feed occupies the largest volume share due to its mechanical durability and controlled sinking rates suited to automated feeding systems. Extruded feed is expanding fastest among high-density commercial farms where floating properties enable consumption monitoring and waste reduction. Plant-based ingredients now dominate formulation cost structures as fish meal inclusion rates face downward pressure from sustainability certifications and price volatility.
The EU Green Deal and REACH frameworks constrain marine ingredient sourcing for feeds entering European supply chains, while India's BIS and MPEDA guidelines enforce quality standards for export-oriented aquaculture inputs. ESG disclosure rules under CSRD will require European feed buyers to document ingredient provenance and carbon intensity. Stakeholders must monitor regulatory divergence between sustainability-driven import markets and production-focused export nations when allocating R&D and certification budgets.
Market Dynamics
Intensive vannamei farming systems are compressing feed conversion ratios and demanding precision-formulated diets with enhanced water stability, forcing compounders to retool extrusion lines and reformulate protein matrices around plant-based alternatives.
Growth Catalysts
- EU Green Deal sustainability mandates:Certification requirements for marine ingredient traceability are pulling premium feeds into European supply chains and rewarding early adopters with preferential procurement contracts.
- India's coastal aquaculture zones:MPEDA-backed integrated farming clusters in Andhra Pradesh and Gujarat are consolidating demand for high-performance grow-out feeds with guaranteed pathogen-free delivery.
- Extrusion technology maturation:Floating feed production lines now achieve 95% water stability at 4-hour immersion, enabling waste reduction and real-time consumption monitoring in high-density ponds.
Market Restraints
- Soy protein concentrate volatility:Brazilian drought cycles and US biofuel policy shifts transmit price shocks directly into feed formulation cost structures.
- Marine ingredient supply concentration:Peruvian anchovy harvest quotas and Chilean fish meal export licensing create single-point vulnerabilities for premium larval feeds.
- REACH chemical registration burdens:Novel feed additives face 18-24 month approval timelines and six-figure dossier costs, freezing innovation pipelines for smaller formulators.
Strategic Opportunities
- Indonesia's unpenetrated eastern archipelago:Sulawesi and Papua farming concessions lack local milling capacity, creating white space for mobile extrusion units and satellite distribution hubs.
- CSRD-driven ESG disclosure:European feed buyers must document carbon intensity and ingredient provenance by 2026, opening premium positioning for certified low-carbon formulations.
- Recirculating aquaculture system convergence:RAS engineering firms and precision nutrition platforms are co-developing closed-loop feed protocols that eliminate pond-side variables.
Industry Challenges
- Aquaculture nutritionist scarcity:Penaeid species specialists command salary premiums exceeding 40% above generalist feed formulators, constraining R&D team expansion.
- ASC certification timeline compression:Farm-level audits now require 90-day feed ingredient traceability documentation, forcing mill-to-farm data system overhauls.
- Multi-species formulation complexity:Monodon revival in Vietnam and Bangladesh demands parallel larval feed lines with incompatible lipid profiles and processing parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrimp Feed Market |
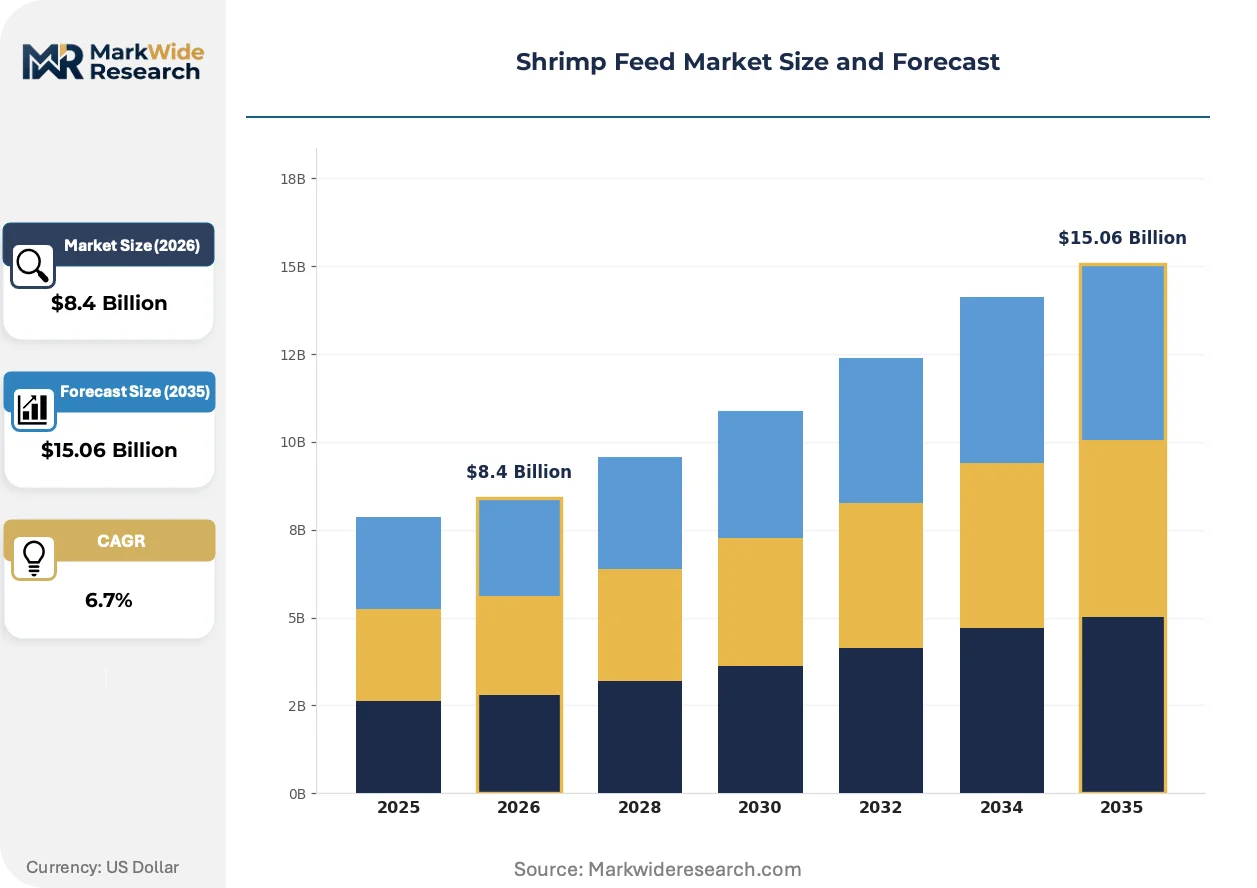
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Feed, Flake Feed, Pelleted Feed, Powder Feed Ingredient Type: Plant-Based Ingredients, Fish Meal, Animal-Based Protein, Additives Distribution Channel: Online Retail, Specialty Stores, Distributors, Feed Mills End User: Commercial Farms, Aquaculture Enterprises, Research Institutes, Small Scale Farmers |
| Companies Covered | BioMar Group, Avanti Feeds, Charoen Pokphand Foods, Skretting, Guangdong HAID Group, Cargill, Incorporated, Thai Union Group, Alltech Inc., Nutreco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrimp Feed Market Strategic Shifts & Innovations
Formulation science and production technology are converging to restructure competitive advantage around water stability, sustainability verification, and species-specific life stage optimization.
Single-cell protein from methanotrophic bacteria is displacing fish meal in post-larval diets. Thai and Vietnamese commercial farms are adopting these ingredients at 15-20% inclusion rates within 18 months of regulatory clearance. This displacement is compressing marine ingredient dependency and insulating margins from Peruvian catch volatility.
REACH and EU Green Deal frameworks now mandate full marine ingredient chain-of-custody documentation for feeds entering European retail channels. Feed compounders must install blockchain-enabled traceability systems or forfeit access to premium export-oriented farm clusters. Vietnamese and Indian mills are responding by segregating production lines and pursuing Friend of the Sea certification.
Direct mill-to-farm procurement contracts are supplanting distributor networks in Thailand's Eastern Seaboard and India's Krishna-Godavari delta. Large integrated farms now negotiate annual volume commitments with formulation guarantees and embedded technical service. This channel compression is visible most acutely in Vietnam, where Charoen Pokphand and Cargill field teams maintain permanent on-site presence at top twenty producers.
Shrimp Feed Market Segmentation
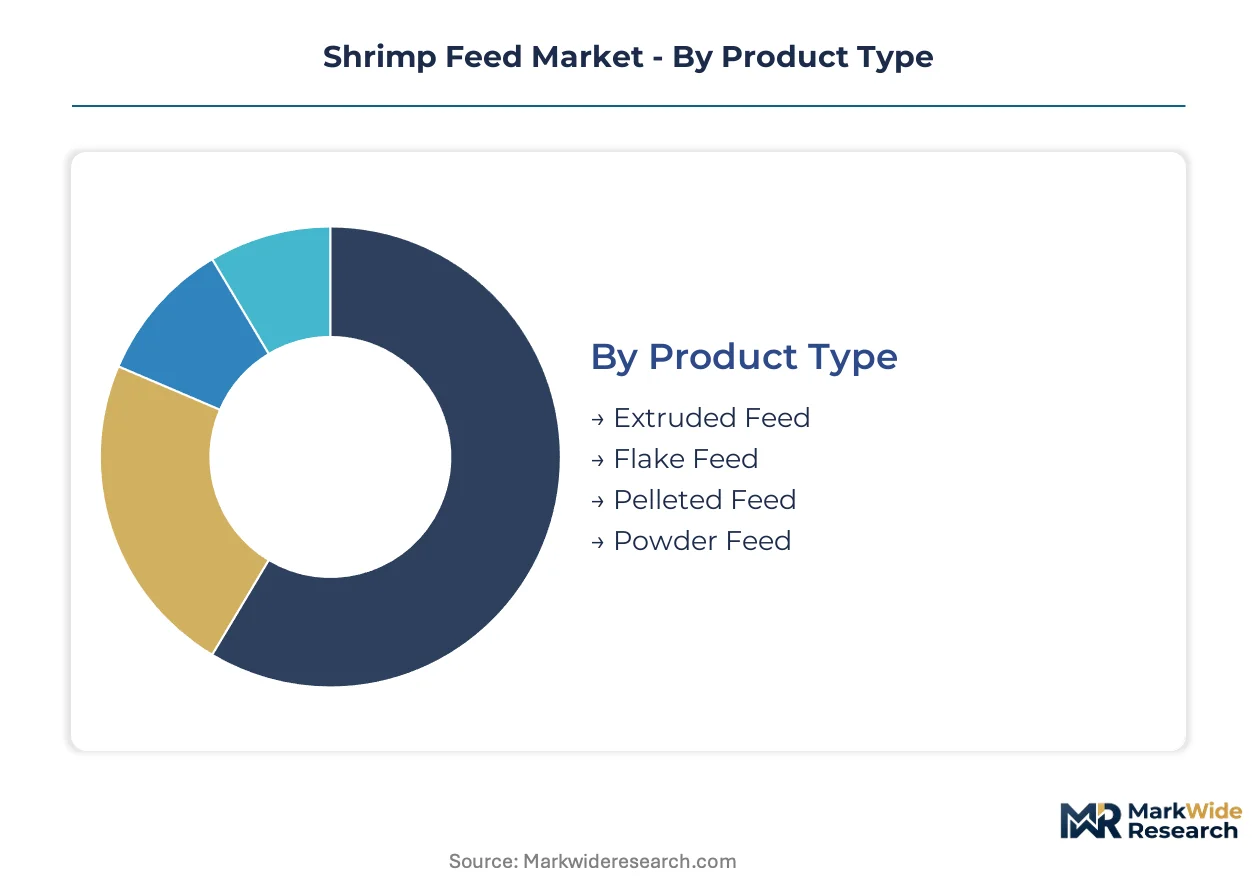
Shrimp feed segmentation reflects divergent regulatory pressures across export corridors. Feed compounders must align product architectures with certification requirements in destination markets while managing cost structures for price-sensitive domestic aquaculture.
Product Type:
REACH and EU Green Deal frameworks differentiate water stability requirements for feeds entering European supply chains versus domestic Asian markets.
- Extruded Feed:Thermal processing gelatinizes starches to achieve floating properties and 95% water stability at extended immersion. Vietnamese and Thai intensive vannamei operations prioritize this format for real-time consumption monitoring and waste reduction in high-density ponds.
- Pelleted Feed:Mechanical compression produces sinking pellets with controlled degradation rates suited to automated feeding systems. India's Andhra Pradesh commercial clusters specify this format for its durability in extended pond cycles and compatibility with existing infrastructure.
- Flake Feed:Thin-layer drying creates high surface-area nutrition for larval and post-larval stages in hatchery applications.
- Powder Feed:Micronized particle size supports early-stage penaeid nutrition in nursery systems and research protocols.
Established volume favors pelleted feed; emerging adoption favors extruded feed.
Ingredient Type:
Cost tier stratification separates premium formulations from commodity blends based on marine ingredient inclusion rates and certification status.
- Plant-Based Ingredients:Soy protein concentrates, pea meals, and processed grain byproducts now constitute the dominant cost share in grow-out formulations. Brazilian drought exposure and US biofuel policy shifts transmit direct price volatility into formulation budgets.
- Fish Meal:Peruvian anchovy and Chilean jack mackerel reductions provide essential amino acid profiles for larval stages. Friend of the Sea and MSC chain-of-custody documentation is becoming mandatory for European-bound feed streams.
- Animal-Based Protein:Poultry byproduct meals and rendered proteins offer intermediate protein density for transitional growth stages.
- Additives:Enzyme complexes, probiotic cultures, and pigment carriers command premium positioning in performance-guaranteed contracts.
Ingredient sourcing concentrates in plant-based alternatives; premium differentiation depends on marine ingredient traceability.
Distribution Channel:
Customer type determines channel selection, with integrated commercial farms bypassing traditional intermediaries.
- Feed Mills:Direct mill-to-farm procurement now dominates Thailand's Eastern Seaboard and India's Krishna-Godavari delta, with annual volume commitments and embedded technical service.
- Distributors:Regional stocking points maintain inventory for fragmented small-scale farmer networks in Indonesia's eastern archipelago.
- Specialty Stores:Urban retail access serves hobbyist and research segments with packaged quantities and technical literature.
- Online Retail:E-commerce penetration remains limited to specialty additives and diagnostic tools rather than bulk feed volumes.
Channel compression favors feed mills; geographic expansion favors distributor networks.
End User:
Application maturity separates intensive commercial systems from extensive traditional methods.
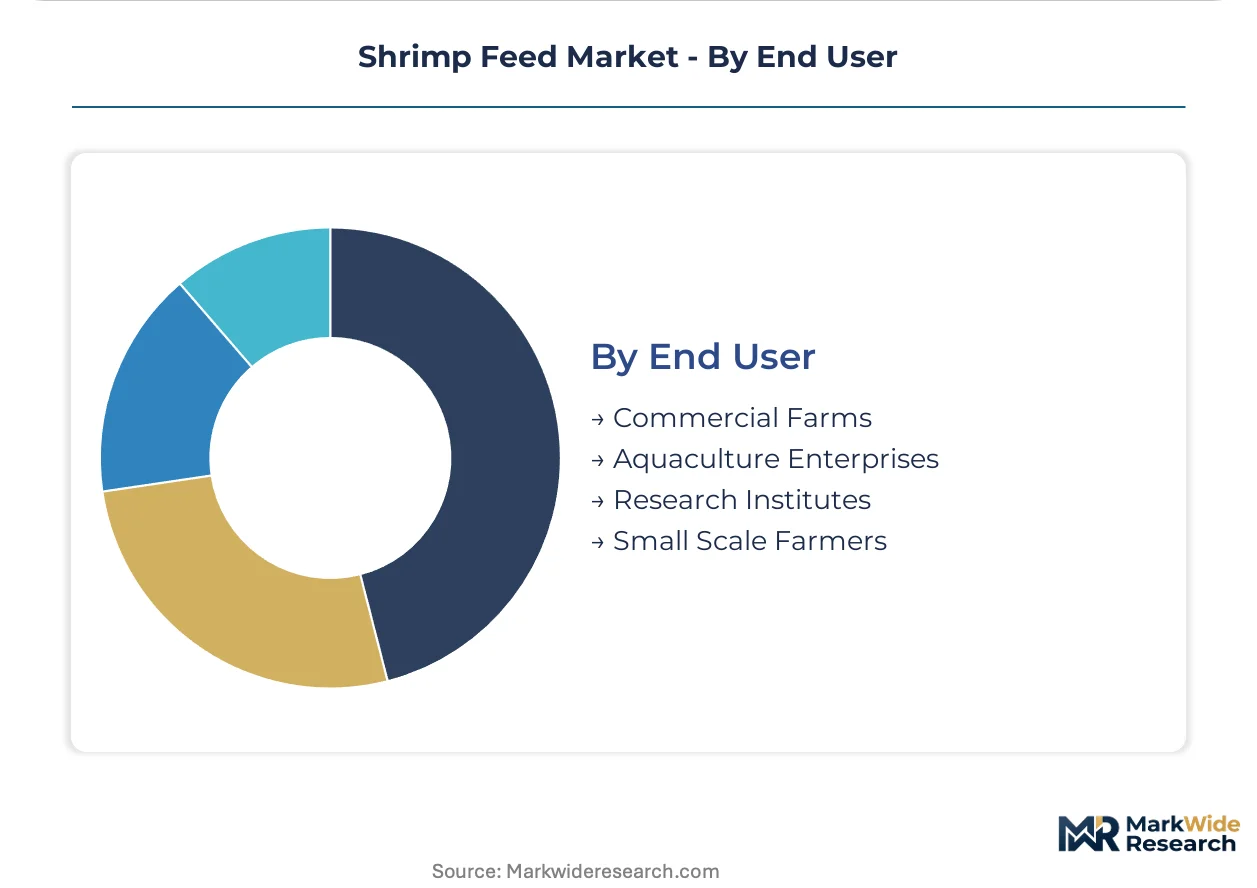
- Commercial Farms:Integrated vannamei operations in Vietnam's Mekong Delta and India's Gujarat specify precision-formulated diets with guaranteed feed conversion ratios and pathogen-free delivery protocols.
- Aquaculture Enterprises:Corporate farming groups negotiate formulation guarantees and embedded nutritionist support through multi-year supply agreements.
- Small Scale Farmers:Extensive pond operators in Bangladesh and Myanmar rely on commodity-grade feeds with limited technical service attachment.
- Research Institutes:Experimental protocols demand custom lipid profiles and controlled micronutrient matrices for breeding program support.
Procurement scale favors commercial farms; formulation innovation originates with research institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS and MPEDA guidelines enforce quality standards across India's coastal aquaculture zones. Vietnam's Mekong Delta concentrates intensive vannamei operations under evolving sustainability protocols. Thailand maintains feed formulation dominance through integrated supply chains.
India
Andhra Pradesh and Gujarat host MPEDA-backed integrated farming clusters consolidating demand for high-performance grow-out feeds. BIS certification mandates pathogen-free delivery protocols for export-oriented aquaculture inputs. The Krishna-Godavari delta anchors direct mill-to-farm procurement networks with annual volume commitments.
Vietnam
Intensive vannamei operations in the Mekong Delta specify precision-formulated diets with guaranteed feed conversion ratios. ASC certification timelines now require 90-day feed ingredient traceability documentation from compounders. Commercial farms in Cà Mau and Bạc Liêu provinces negotiate embedded technical service through multi-year supply agreements.
Thailand
The Eastern Seaboard sustains captive supply networks for key ingredients with mill-to-farm distribution eliminating intermediaries. Domestic regulations emphasize sustainable marine ingredient sourcing aligned with EU export requirements. Rayong and Chonburi provinces concentrate extrusion capacity serving high-density pond systems.
Indonesia
Sulawesi and Papua farming concessions lack local milling capacity, creating white space for satellite distribution expansion. The country's national aquaculture regulator enforces quality standards for imported feed additives. Eastern archipelago clusters rely on regional stocking points serving fragmented small-scale farmer networks.
Ecuador
Commercial vannamei producers in Guayas and El Oro provinces drive demand for extruded feeds with enhanced water stability. National aquaculture authorities monitor marine ingredient inclusion rates for sustainability compliance. The Santa Elena Peninsula anchors integrated farming operations with direct procurement relationships to international compounders.
Shrimp Feed Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the shrimp feed sector. The market structure consolidates around vertically integrated agribusiness conglomerates and specialized marine nutrition formulators. Three archetypes dominate: captive supply integrators, research-driven specialists, and diversified protein processors. Competitive moves concentrate on backward integration into soy protein processing and geographic expansion through satellite milling capacity.
Among European-based research specialists, BioMar Group exemplifies technology leadership through marine research station networks. Charoen Pokphand Foods anchors the captive supply archetype with integrated ingredient sourcing and direct distribution control. Cargill, Incorporated occupies a position bridging diversified protein processing with aquaculture platform integration, representing the scale-driven multinational tier.
| Leading Market Players |
|---|
| BioMar Group |
| Avanti Feeds |
| Charoen Pokphand Foods |
| Skretting |
| Guangdong HAID Group |
| Cargill, Incorporated |
| Thai Union Group |
| Alltech Inc. |
| Nutreco |
| Others |
Cost & Logistics Intelligence
Thailand's captive supply networks and India's mill-to-farm procurement clusters concentrate formulation capacity at scales that compress unit economics for regional competitors. This concentration anchors price floors while enabling premium-tier producers to extract margin through certification-linked guarantees.
Pricing Analysis
Vietnamese extruded feed commands 15-25% premia over Indian pelleted equivalents due to EU Green Deal compliance costs and embedded technical service. Three-tier pricing structure across premium, standard, and economy levels separates Friend-of-the-Sea-certified formulations from commodity blends and small-scale farmer grades. Cost compression in standard-tier grow-out feeds is intensifying because Brazilian soy protein concentrate volatility transmits directly into formulation budgets. Small-scale farmers in Bangladesh and Myanmar exhibit highest price sensitivity, while integrated Vietnamese commercial farms prioritize feed conversion ratio guarantees over unit cost.
Supply Chain Analysis
Inventory cycles for Peruvian fish meal extend 90-120 days through anchovy harvest seasons, forcing compounders to pre-position marine ingredient stocks ahead of quota announcements. Supply concentrates in Thailand, Vietnam, and India for finished feed production, with raw material sourcing drawing from Brazil for soy protein, Peru for fish meal, and China for vitamin premixes. Single-source vulnerability in Peruvian anchovy quotas creates formulation disruption risk for larval-stage diets. Distribution runs through direct mill-to-farm contracts in Thailand's Eastern Seaboard and India's Krishna-Godavari delta, with distributor networks serving Indonesia's fragmented eastern archipelago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shrimp feed market is recovering from Peruvian anchovy quota compression and Brazilian drought-driven soy volatility, with restocking cycles in Vietnam and India driving volume normalization.
For Market Incumbents: Shield margin structures by securing multi-year soy protein concentrate offtakes with Brazilian processors before biofuel policy shifts tighten export availability. Deepen backward integration into captive vitamin premix production to reduce Chinese supply chain exposure. Charoen Pokphand Foods and Cargill have demonstrated that direct mill-to-farm technical service teams lock in annual volume commitments against price undercutting. For New Entrants and Emerging Players: Anchor in Indonesia's Sulawesi and Papua farming concessions where local milling capacity gaps exceed 60% of regional demand. Mobile extrusion units with satellite distribution hubs offer the most penetrable entry vector against established Thai and Vietnamese compounders. Pursue Friend of the Sea certification immediately to access EU-bound supply chains before CSRD disclosure mandates harden procurement requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with embedded technical service contracts and multi-year formulation guarantees. Five-to-ten-year viability favors specialists with marine research station networks over commodity blenders exposed to raw material volatility. Acquisition targets should display proven extrusion technology platforms and established ASC certification documentation systems. Monitor Peruvian anchovy quota announcements as the critical inflection signal for marine ingredient cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soy Protein Processing | Cargill's captive crushing capacity insulates margins from Brazilian drought-driven price spikes. |
| Mobile Extrusion Unit Deployment | Satellite milling capacity captures unmet demand in Indonesia's eastern archipelago farming zones. |
| Friend of the Sea Certification Pursuit | Chain-of-custody documentation unlocks EU Green Deal-compliant procurement contracts. |
| Embedded Technical Service Teams | On-site nutritionist presence at Vietnamese commercial farms secures multi-year volume commitments. |
| Single-Cell Protein Formulation Development | Methanotrophic bacterial protein displaces fish meal dependency and insulates against Peruvian catch volatility. |
Research Approach
Cross-validation between regulatory filing analysis and supply chain participant interviews anchors the qualitative findings. Primary fieldwork engaged feed mill operations directors, aquaculture nutritionists at commercial farms, MPEDA compliance officers, and procurement leads at integrated shrimp producers. Secondary sources included BIS certification registries, EU REACH substance databases, MPEDA export documentation, and customs trade records for soy protein concentrate and fish meal flows. Bottom-up demand modeling triangulated against top-down aquaculture production forecasts.
Sensitivity analysis tested forecast outputs against alternative scenarios for Peruvian anchovy harvest variability and Brazilian drought frequency. Segmentation dimensions spanned product type, ingredient composition, distribution channel, and end-user scale across the analysis window. CAGRs derived from regression-weighted historical growth patterns adjusted for regulatory inflection points. Industry-specific inputs incorporated feed conversion ratio improvement trajectories and extrusion technology adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable Indian coastal aquaculture zone expansion; material deviation in marine ingredient availability or Brazilian soy export policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Europe Organic Aquaculture Market
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
Perch Market
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
Ecuador Shrimp Feed Market
Aquaculture Innovations
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
United States Ornamental Fish Market