
 Kids GPS Trackers and Wearables Market | 2026-2036
Kids GPS Trackers and Wearables Market Size, Share, and Industry Trends Forecast 2026-2036
Kids GPS Trackers and Wearables Market Insights
Platform licensing revenue is fragmenting as hardware vendors seek recurring income streams beyond device sales. Garmin leverages its aviation-grade GPS heritage to anchor premium positioning in the segment. Xiaomi competes through manufacturing scale that compresses bill-of-material costs for entry-level smartwatches. AngelSense differentiates via specialized software for children with special needs, occupying a defensible niche with higher retention rates.
Kids GPS trackers and wearables are electronic devices incorporating satellite positioning modules, cellular modems, and accelerometers to transmit location and activity data to caregiver smartphones. These products typically operate on 4G LTE or 5G networks with battery capacities ranging from 400 to 800 mAh, enabling 24 to 72 hours of continuous tracking between charges. Smartwatches represent the dominant product type, capturing the largest revenue share as parents prefer consolidated communication and safety functions in wrist-worn form factors. Cellular-enabled devices are expanding fastest among technology segments, as Bluetooth-reliant products fail to deliver independent location reporting beyond proximity range.
The Federal Communications Commission mandates E911 location accuracy standards that directly influence GPS chipset selection and antenna design in devices sold domestically. The European Union's GDPR and the Children's Online Privacy Protection Act impose strict data handling requirements, forcing manufacturers to implement encrypted transmission protocols and localized data storage architectures. Stakeholders must monitor evolving battery safety certifications and emerging right-to-repair mandates that could alter product lifecycle economics and aftermarket service opportunities.
Market Dynamics
The Federal Communications Commission's E911 location accuracy mandates are compressing GPS chipset selection cycles and forcing antenna design investments that reshape hardware economics for domestic manufacturers.
Growth Catalysts
- Cellular network densification:4G LTE and 5G infrastructure expansion in urban United States corridors enables real-time location transmission without Bluetooth tethering, removing proximity constraints that limited earlier device generations.
- COPPA enforcement intensification:The Children's Online Privacy Protection Act's data handling requirements are accelerating encrypted transmission protocol adoption, creating competitive moats for compliant vendors in North American distribution channels.
- Special needs care integration:School districts and therapy centers in Germany are procuring GPS wearables as assistive technology, opening institutional procurement pathways beyond traditional retail.
Market Restraints
- Lithium-polymer battery supply concentration:Cell production concentrates in East Asian contract manufacturers, exposing hardware vendors to input cost volatility and extended lead times during demand surges.
- GDPR compliance architecture costs:The European Union's data localization requirements force redundant server infrastructure investments that inflate operational expenditures for market entrants.
- Smartphone substitution pressure:Declining age thresholds for first mobile device ownership in Chinese households compresses the addressable window for standalone GPS tracker purchases.
Strategic Opportunities
- Rural United States connectivity gaps:Satellite messaging integration targets agricultural and remote residential zones where cellular coverage remains inconsistent, opening underserved geographic segments.
- Health-monitoring convergence:Accelerometer and heart rate sensor fusion creates pediatric wellness platforms that extend product lifecycles beyond pure safety positioning.
- India's PLI scheme for electronics:Production-linked incentives for wearable manufacturing attract contract assembly relocation, reducing landed costs for price-sensitive South Asian distribution.
Industry Challenges
- RF engineering talent scarcity:Compact antenna design for wrist-worn form factors requires specialized electromagnetic simulation expertise that concentrates in aerospace and telecommunications sectors.
- Multi-certification timeline compression:FCC, CE marking, and battery safety approvals must sequence across jurisdictions, delaying product launches and consuming working capital.
- Firmware update infrastructure:Post-sale security patch delivery demands cloud architecture investments that smaller hardware vendors struggle to operationalize at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids GPS Trackers and Wearables Market |
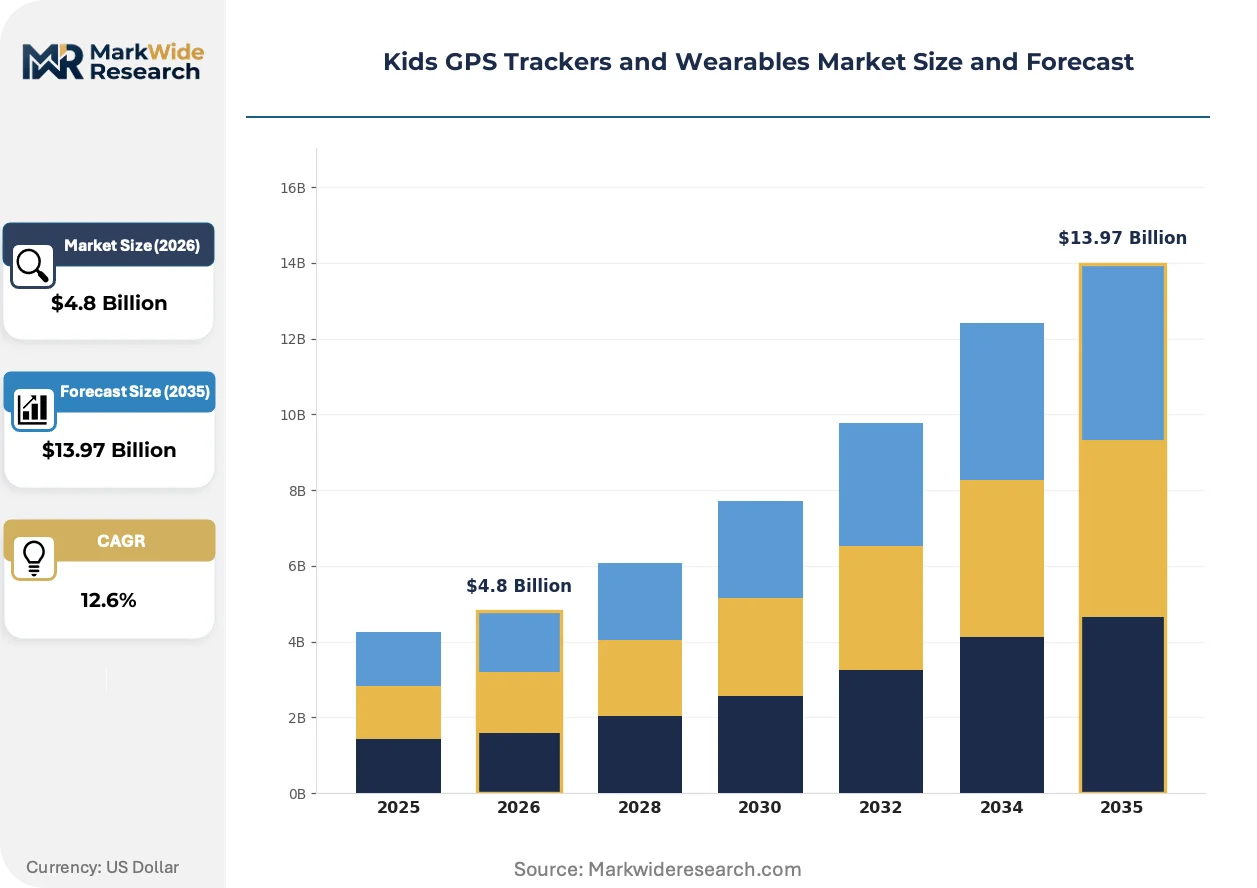
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, GPS Trackers, Wearable Bands, Clip-ons Technology: Bluetooth, Cellular, Wi-Fi, NFC End User: Parents, Schools, Caregivers, Sports Organizations Distribution Channel: Online Retail, Physical Stores, Direct Sales, Third-party Distributors |
| Companies Covered | AngelSense, Jiobit, Garmin, Xiaomi, Xplora, VTech Holdings, TickTalk, Tracki, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids GPS Trackers and Wearables Market Trends and Innovations
Edge computing migration is redistributing processing loads from caregiver smartphones toward device-local inference, reducing latency and cellular data consumption while enabling offline safety alerts.
Ultra-wideband positioning chips are digitizing indoor location granularity to room-level accuracy, displacing Wi-Fi fingerprinting in school and shopping mall environments where GPS satellite signals attenuate. Parents of children with autism spectrum conditions in the United States are adopting these devices fastest, compressing replacement cycles as accuracy specifications tighten annually.
Germany's implementation of the EU AI Act's risk classification framework is forcing algorithmic transparency disclosures for predictive geofencing features that anticipate boundary crossings. Manufacturers must document machine learning training data provenance and decision logic, increasing compliance documentation burdens. Premium smartwatch segments targeting German retail channels are responding with open-source firmware commitments and third-party audit certifications.
Subscription service unbundling is fragmenting the traditional hardware-plus-software bundle into tiered connectivity plans with variable location update frequencies. Direct-to-consumer channels in China are displacing electronics retail intermediaries, with manufacturers operating flagship stores on domestic e-commerce platforms that capture recurring revenue streams through automated renewal billing.
Kids GPS Trackers and Wearables Market Segmentation
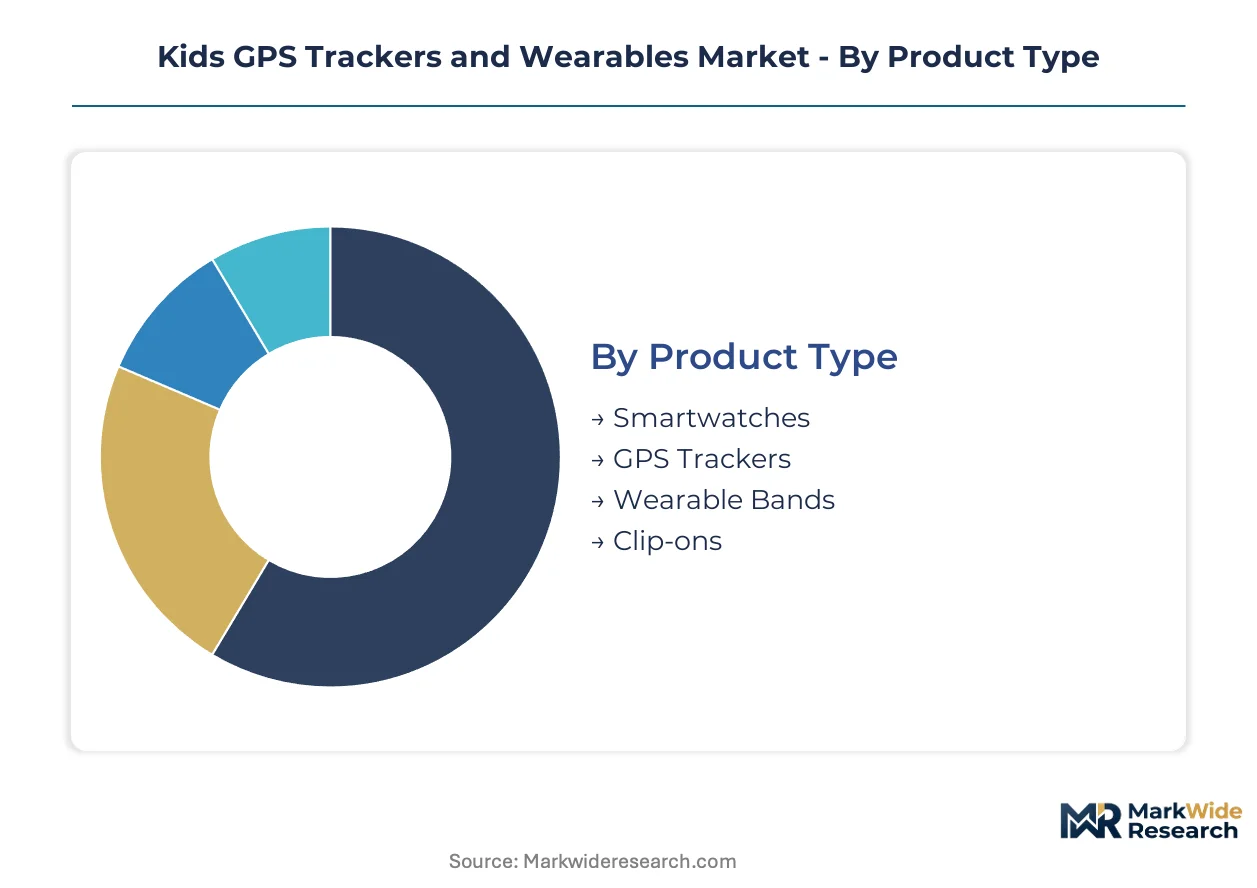
Segmentation in kids GPS trackers and wearables reveals how hardware specifications, connectivity protocols, and procurement channels reshape vendor economics. Parents, schools, and institutional buyers each impose distinct performance thresholds and compliance burdens that fragment product development roadmaps.
Product Type:
Mature wrist-worn form factors dominate revenue concentration while emerging clip-on designs target specialized use cases.
- Smartwatches:These devices integrate GPS modules, cellular modems, and touchscreens into wrist-worn enclosures with 400-800 mAh batteries enabling 24-72 hour operation. Demand concentrates among urban households in the United States and Germany where parents prefer consolidated communication and safety functions in a single device.
- GPS Trackers:Dedicated location-only devices omit displays to extend battery life beyond 72 hours through reduced power draw. Schools and therapy centers in Germany procure these units as assistive technology for children with special needs, creating institutional procurement pathways with higher retention rates than retail channels.
- Wearable Bands:Slim form factors prioritize comfort for all-day wear by younger children with smaller wrist circumferences.
- Clip-ons:Attachable designs target clothing or backpack placement for children who resist wrist-worn devices.
Smartwatches handle the majority of throughput; clip-ons are expanding most quickly among parents seeking non-intrusive monitoring options.
Technology:
Cost tier stratification separates premium independent-connectivity solutions from economy-tier proximity-dependent alternatives.
- Cellular:4G LTE and 5G-enabled devices transmit location data independently without smartphone tethering, enabling true remote monitoring. FCC E911 mandates in the United States compress GPS chipset selection cycles and force antenna design investments that reshape hardware economics for domestic manufacturers.
- Bluetooth:Low-energy protocols limit range to approximately 100 meters, constraining utility to proximity alerts in shopping malls or schoolyards. Chinese households show declining tolerance for these limitations as smartphone ownership ages downward, compressing the addressable window for standalone tracker purchases.
- Wi-Fi:Fingerprinting techniques supplement GPS for indoor positioning where satellite signals attenuate.
- NFC:Near-field protocols enable tap-to-check-in functionality for controlled environments like school pickup zones.
Cellular handles the majority of throughput; NFC is climbing the fastest as ultra-wideband integration enables room-level accuracy.
End User:
Application context fragments procurement authority across consumer, educational, and therapeutic settings with divergent compliance requirements.
- Parents:Individual purchasers prioritize real-time location dashboards and geofencing alerts accessible through smartphone applications. COPPA enforcement in the United States accelerates encrypted transmission protocol adoption, creating competitive moats for compliant vendors in North American distribution channels.
- Schools:Institutional buyers in Germany procure GPS wearables as assistive technology under disability accommodation frameworks, opening procurement pathways beyond traditional retail with multi-year contract structures.
- Caregivers:Professional childcare providers demand simplified interfaces and consolidated multi-child monitoring dashboards.
- Sports Organizations:Youth leagues utilize location tracking for team travel safety and practice field coordination.
Parents handle the majority of throughput; schools are gaining share fastest as institutional procurement scales.
Distribution Channel:
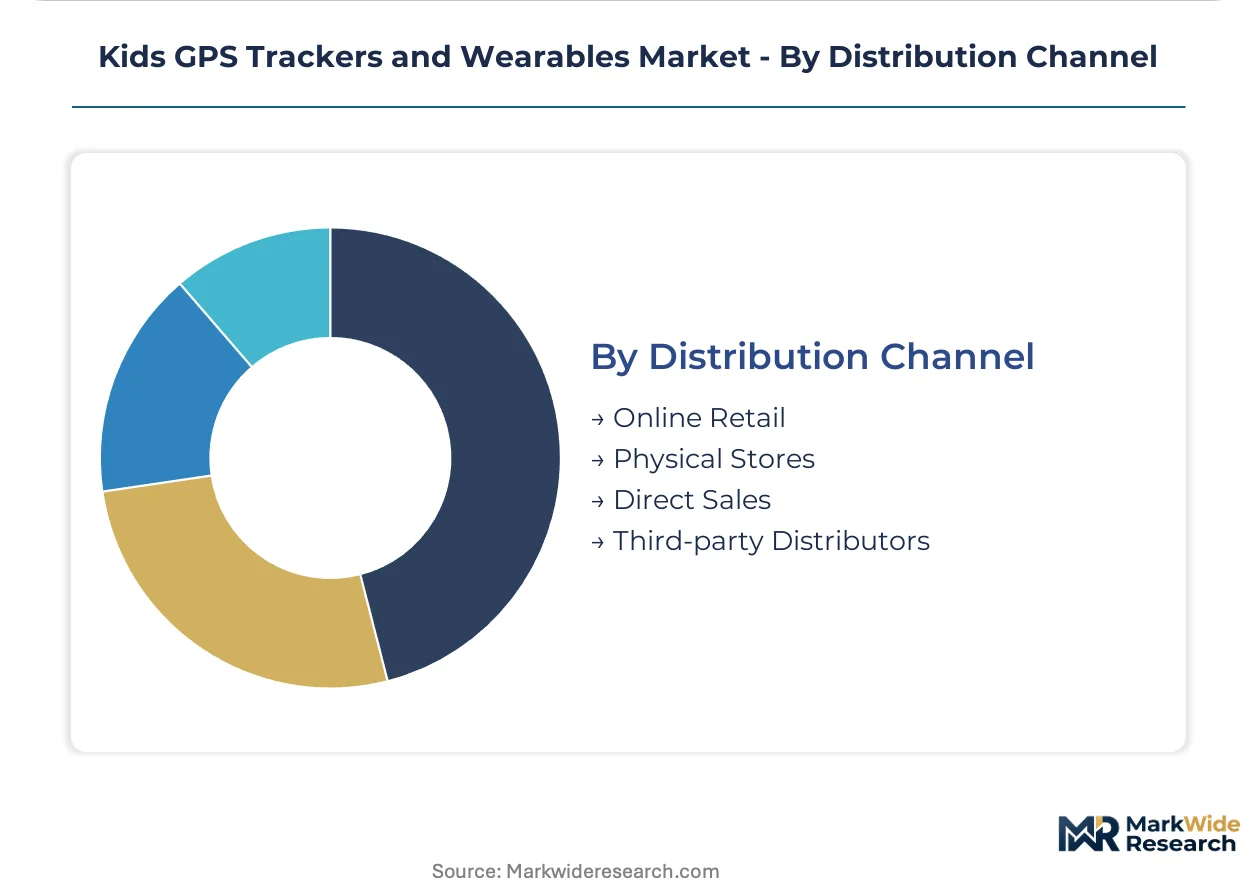
Geography of sale determines margin capture and recurring revenue attachment rates through divergent channel economics.
- Online Retail:Domestic e-commerce platforms in China displace electronics retail intermediaries, with manufacturers operating flagship stores that capture recurring revenue through automated renewal billing of tiered connectivity plans.
- Physical Stores:Electronics retailers and mobile carrier outlets provide hands-on evaluation opportunities that reduce return rates for first-time purchasers.
- Direct Sales:Manufacturer-controlled channels enable subscription service unbundling into tiered connectivity plans with variable location update frequencies.
- Third-party Distributors:Regional logistics specialists penetrate rural United States markets where direct fulfillment economics prove prohibitive.
Online retail handles the majority of throughput; direct sales are expanding most quickly as vendors seek recurring income streams beyond device margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parental purchasing patterns diverge sharply across geographies: United States households prioritize cellular-enabled smartwatches with communication features, while German procurement concentrates on specialized assistive devices for institutional special-needs programs, and Chinese consumers increasingly substitute standalone trackers with early smartphone adoption.
United States
FCC E911 mandates compress GPS chipset selection cycles and force antenna design investments that reshape hardware economics for domestic manufacturers. COPPA enforcement accelerates encrypted transmission protocol adoption, creating competitive moats for compliant vendors in North American distribution channels. California and Texas metropolitan corridors drive volume concentration as urban households prioritize real-time location dashboards.
Germany
School districts and therapy centers procure GPS wearables as assistive technology under disability accommodation frameworks, opening institutional procurement pathways with multi-year contract structures. GDPR data localization requirements force redundant server infrastructure investments that inflate operational expenditures for market entrants. Bavaria's industrial clusters anchor manufacturing partnerships for premium-tier device assembly.
China
Declining age thresholds for first mobile device ownership compress the addressable window for standalone GPS tracker purchases among urban households. MIIT certification requirements and GB standards govern cellular module approval timelines for domestic market entry. Shenzhen's electronics manufacturing ecosystem enables rapid prototyping cycles that accelerate product iteration for export markets.
India
Production-linked incentives for wearable manufacturing attract contract assembly relocation, reducing landed costs for price-sensitive South Asian distribution. BIS certification mandates and TRAI spectrum regulations govern device import and cellular connectivity provisioning. Maharashtra and Karnataka industrial corridors concentrate final assembly operations for regional distribution.
Japan
METI safety standards and PMDA consultation frameworks influence pediatric wearable design specifications for domestic market entry. Kanto and Kansai metropolitan regions concentrate retail distribution networks for premium consumer electronics. Aging demographics and dual-income household structures sustain demand for child monitoring solutions despite declining birth rates.
Kids GPS Trackers and Wearables Market Competitive Landscape
Capability concentration sits with specialized software vendors; scale advantage sits with diversified electronics conglomerates. The market structures around three tiers: aviation-grade positioning heritage anchors premium positioning, manufacturing scale compresses entry-level economics, and specialized assistive technology occupies defensible retention-rich niches. Dominant competitive moves include platform licensing revenue unbundling and direct-to-consumer channel migration that captures recurring connectivity subscriptions.
Within the specialized assistive tier, AngelSense occupies a position exemplifying software-differentiated retention economics. Garmin and Xiaomi anchor opposing ends of the price-performance spectrum: the former represents premium heritage positioning, the latter exemplifies manufacturing-scale cost compression. These three entities collectively illustrate how capability specialization and production scale fragment competitive advantage across distinct customer acquisition strategies.
| Leading Market Players |
|---|
| AngelSense |
| Jiobit |
| Garmin |
| Xiaomi |
| Xplora |
| VTech Holdings |
| TickTalk |
| Tracki |
| Fitbit |
| Others |
Pricing and Supply Chain Analysis
Lithium-polymer cell production concentrates in East Asian contract manufacturers, tethering margin pools to battery chemistry sourcing and compressing pricing power for hardware vendors without captive supply arrangements. This upstream concentration forces downstream players to absorb input volatility or pass through cost swings via subscription repricing.
Pricing Analysis
Long-term connectivity contracts anchor revenue stability for cellular-enabled devices, while spot-market component purchasing exposes entry-tier vendors to lithium-polymer price swings. Three-tier pricing structure across premium, standard, and economy levels separates aviation-grade GPS heritage from manufacturing-scale cost compression. Pricing pressure stems from Xiaomi's bill-of-material compression in entry-level smartwatches. Schools and therapy centers show least price sensitivity due to institutional procurement frameworks.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for GPS chipset and cellular module sourcing. Manufacturing concentrates in China, South Korea, and Vietnam for final assembly and component fabrication. The supply chain draws from lithium-polymer cells, GPS chipsets, and ultra-wideband positioning modules. Single-source vulnerability concentrates in East Asian battery cell production. Distribution runs through direct-to-consumer channels and third-party logistics specialists penetrating rural United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in institutional procurement pathways as school districts and therapy centers adopt assistive technology frameworks, creating retention-rich niches beyond consumer retail saturation.
For Market Incumbents: Harden subscription revenue attachment through automated renewal billing infrastructure that captures recurring connectivity income beyond device margins. Deepen in-house production of encrypted transmission protocols to maintain COPPA compliance moats against emerging entrants lacking cloud architecture scale. Vertical integration into localized server infrastructure defends GDPR positioning in European distribution channels. For New Entrants and Emerging Players: Rural United States connectivity gaps represent the most penetrable entry point for satellite messaging integration targeting agricultural zones where cellular coverage attenuates. India's production-linked incentive corridors offer contract assembly relocation for price-sensitive South Asian distribution. Direct sales channels enable tiered connectivity plan unbundling with variable location update frequencies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized software vendors serving special-needs populations through institutional procurement pathways. Long-term viability centers on retention economics rather than customer acquisition scale. The signal to watch is school district procurement velocity as assistive technology adoption accelerates under disability accommodation frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Licensing Revenue Unbundling | Hardware vendors capture recurring income streams beyond device sales through tiered connectivity subscriptions. |
| Direct-to-Consumer Channel Migration | Manufacturers operating flagship stores on domestic e-commerce platforms displace retail intermediaries. |
| Ultra-Wideband Integration | Room-level indoor positioning accuracy displaces Wi-Fi fingerprinting in school and shopping mall environments. |
| GDPR-Compliant Server Localization | Redundant data infrastructure investments create competitive moats for European market entry. |
| Special Needs Software Specialization | Institutional procurement pathways under disability accommodation frameworks deliver higher retention rates than retail. |
Research Methodology
Operator-level perspectives from hardware engineering directors, cellular module procurement leads, school district assistive technology coordinators, and FCC compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from MIIT certification databases, FCC equipment authorization filings, GDPR enforcement bulletins, and customs trade records. Bottom-up device shipment modeling and top-down parental expenditure surveys triangulated market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, with CAGRs derived from segment-level penetration curves and replacement cycle compression patterns. Segmentation dimensions modeled include product type, connectivity protocol, end-user context, and regional regulatory cluster. Forecast inputs incorporated cellular network densification trajectories and COPPA enforcement intensity indices.
Macroeconomic conditions sit as an overlay; deviation in household discretionary expenditure patterns or lithium commodity price volatility would shift the trajectory. Forecasts reflect assumptions about institutional procurement scaling and battery chemistry cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Global Smart Ring Market
Wearable Technology
Global Smartwatch Battery Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Smart Band Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Wearable Gaming Technology Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
Kids Smart Watch Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Smart Bra Market
Wearable Technology
Europe Wearable Technology Market