
 Wearable Technology Market | 2026-2036
Wearable Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Technology Market Analysis
A shortage of embedded firmware engineers with biomedical signal-processing expertise is unwinding the pace at which new health-monitoring features reach certification. Apple Inc. leverages its vertical control over silicon and sensor fusion to sustain rapid iteration cycles in heart-rate variability tracking. Samsung Electronics Co., Ltd. competes by anchoring its Galaxy Watch line across multiple Android OEM ecosystems. Garmin Ltd. specializes in GPS-dominant outdoor and aviation wearables that occupy premium endurance-sports niches.
Wearable technology encompasses body-worn electronic devices integrating microelectromechanical sensors, low-power Bluetooth chipsets, and photoplethysmography optics to capture physiological or environmental data for real-time feedback or cloud-synced analytics. The primary commercial purpose spans preventive health surveillance, athletic performance optimization, and hands-free industrial task support. Smartwatches lead product-type revenue pools due to their multipurpose health-communication-entertainment convergence, while hearables represent the fastest-growing category as active noise cancellation and real-time language translation expand use cases. Fitness trackers retain volume dominance in entry-tier consumer segments where battery longevity and step-count accuracy anchor purchasing decisions.
FDA premarket notification requirements for Class II medical-wearable claims are elevating clinical-validation costs and compressing margins for entrants lacking regulatory affairs infrastructure. The EU MDR and GDPR jointly shape European market access by mandating clinical-evidence dossiers for health-claim devices while restricting biometric data flows to approved third-party processors. Stakeholders must monitor how FDA digital-health pilot programs and EU AI Act risk-classification rules for biometric inference will reshape compliance budgets and partnership strategies.
Market Dynamics
FDA tightening of 510(k) clearance thresholds for pulse oximetry and ECG claims is compressing product development timelines while elevating clinical-validation burdens for wearable health devices.
Growth Catalysts
- Hospital-at-home reimbursement expansion:United States CMS coding changes for remote patient monitoring are pulling continuous glucose monitors and cardiac event recorders into acute-care substitution workflows.
- EU AI Act biometric risk classification:The regulation's tiered oversight framework is accelerating investment in explainable algorithms for heart-rate variability inference to preempt compliance costs.
- Photoplethysmography optics miniaturization:Advances in LED-PD packaging from semiconductor foundries are enabling SpO2 monitoring in form factors below 30 grams.
Market Restraints
- Biomedical firmware talent scarcity:Embedded signal-processing engineers with ISO 13462 familiarity command 40-60% salary premiums, inflating R&D fixed costs for mid-tier entrants.
- MEMS foundry concentration in Taiwan:Single-source dependency for accelerometer and gyroscope wafers exposes shipment schedules to geopolitical contingency.
- Battery energy-density plateau:Lithium-polymer chemistry improvements have stalled below 300 Wh/kg, capping always-on sampling rates for multi-sensor arrays.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:The incentive structure is attracting final assembly of fitness trackers for price-sensitive South Asian and African export markets.
- Non-invasive glucose monitoring:Spectroscopic sensing platforms using near-infrared interferometry are approaching clinical-grade correlation thresholds for prediabetes management applications.
- Specialty pharmacy distribution channels:CVS Health and Walgreens Boots Alliance are building RPM device fulfillment infrastructure that bypasses traditional consumer electronics retail.
Industry Challenges
- Multimodal sensor fusion complexity:Integrating PPG, bioimpedance, and temperature data streams into validated digital biomarkers requires 18-24 month algorithm training cycles against reference-standard cohorts.
- Cross-border data residency fragmentation:GDPR Article 44 transfer mechanisms, China's PIPL localization mandates, and state-level US privacy laws are forcing redundant cloud infrastructure deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Technology Market |
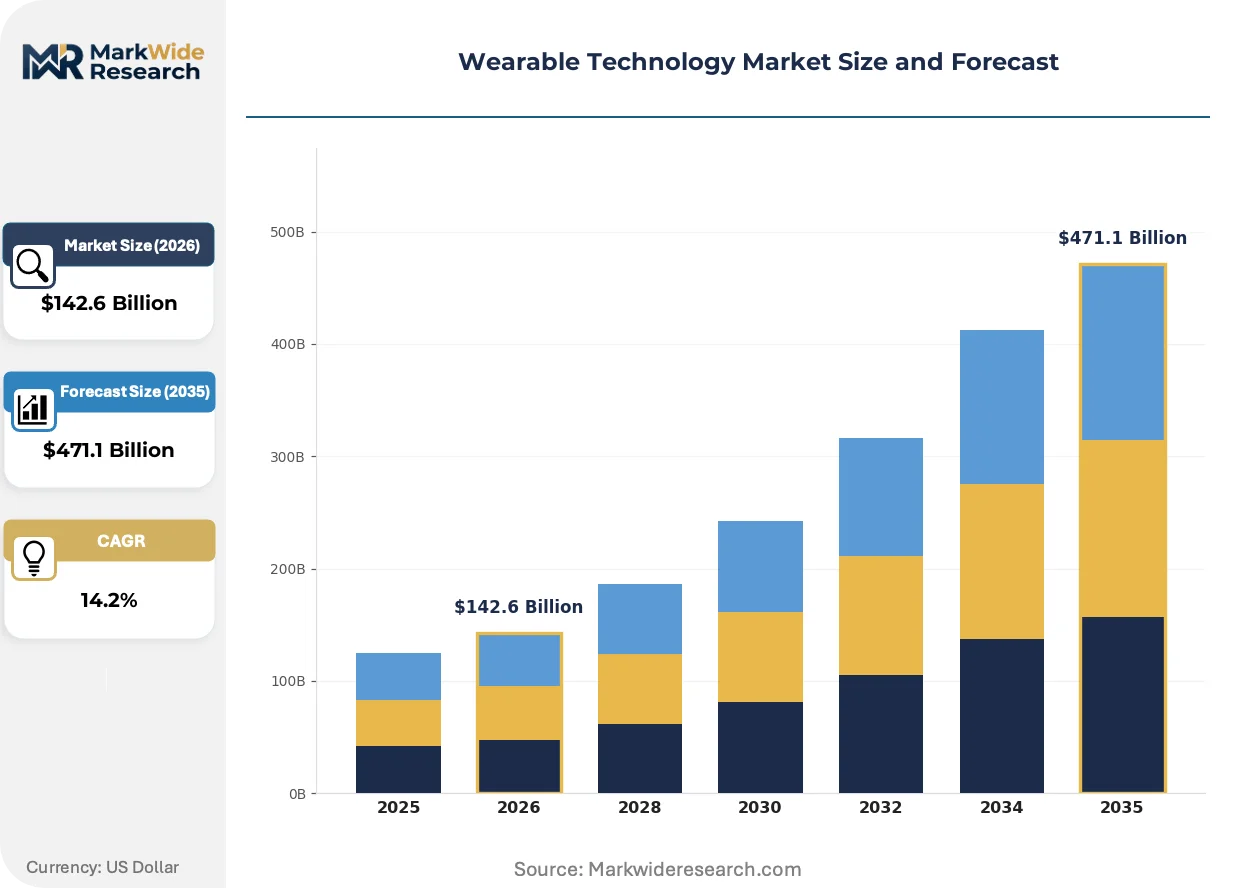
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $471.1 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Hearables Technology: Bluetooth, NFC, Wi-Fi, GPS End User: Consumers, Healthcare Professionals, Sports Enthusiasts, Military Application: Health Monitoring, Fitness Tracking, Communication, Entertainment |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Garmin Ltd., Fitbit LLC, Huawei Technologies Co., Ltd., Xiaomi Corporation, Alphabet Inc., Sony Group Corporation, Adidas AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Technology Market Emerging Trajectories
Silicon-level integration of neural processing units is collapsing the power-performance tradeoff that previously forced wearable designers to choose between battery life and on-device inference capability.
Ring-form-factor wearables with multi-wavelength PPG arrays are supplanting wrist-worn devices in sleep-stage classification applications. Wellness platforms from Oura and Ultrahuman are capturing subscription revenue from users prioritizing circadian rhythm optimization over step counting. The shift is compressing addressable market share for legacy fitness bands while elevating industrial design and materials-science capabilities as competitive differentiators.
EU MDR Annex XVI expansion to cover devices without intended medical purpose but with physiological measurement capability is forcing consumer electronics brands to maintain parallel technical documentation for CE-marked and non-CE product variants. The regulatory friction is most acute for hearable manufacturers adding core-temperature estimation features. Several firms are responding by bifurcating SKU strategies between health-claim and wellness-only positioning.
Enterprise procurement of industrial safety wearables is consolidating around integrated platform contracts rather than point-solution purchases. Oilfield operators and logistics warehouse networks are demanding unified dashboards combining location tracking, biometric fatigue alerts, and environmental hazard detection. The bundling imperative is most visible in Germany's chemical processing corridor and the US Gulf Coast petrochemical cluster, where multi-site standardization reduces training and integration overhead.
Wearable Technology Market Segmentation
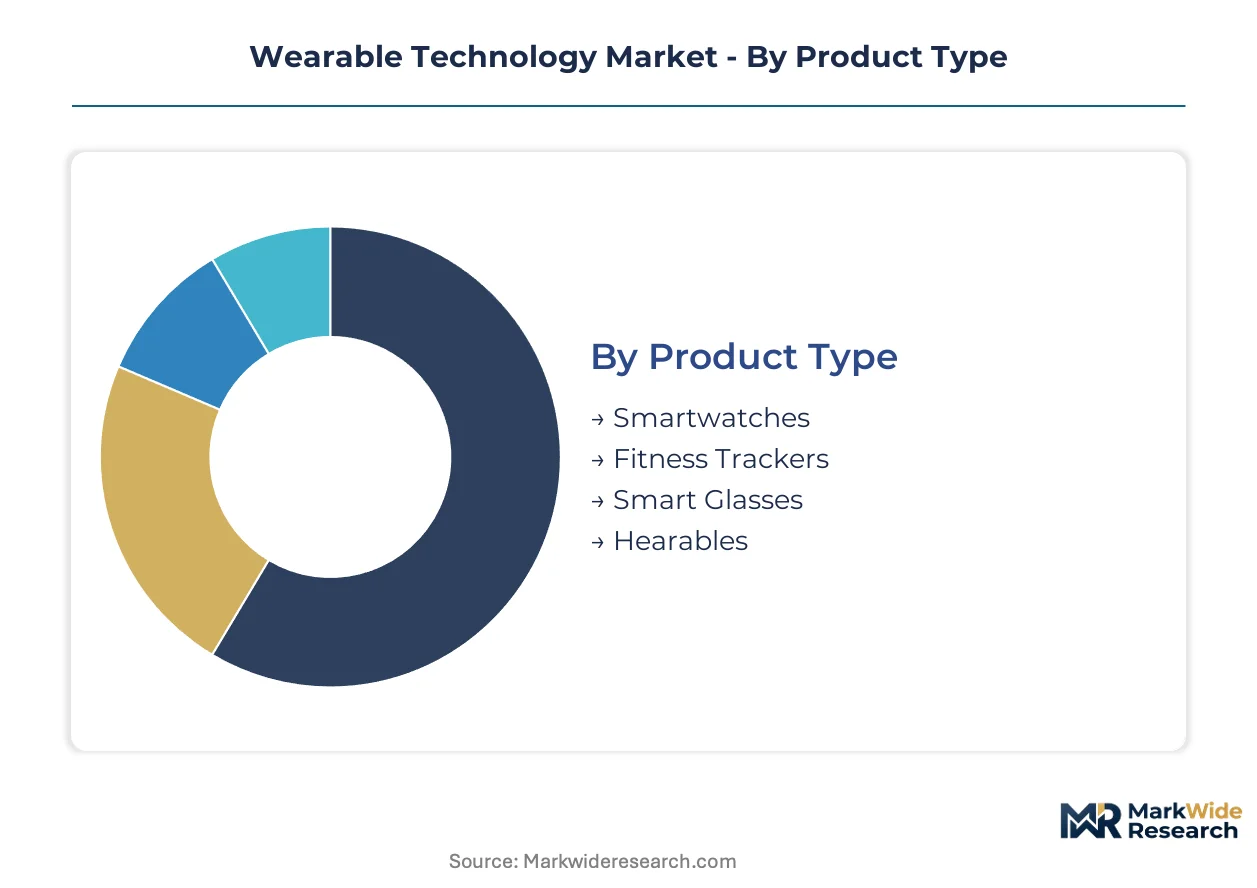
Wearable technology segmentation reveals how hardware form factors, connectivity protocols, and user workflows fragment purchasing criteria across consumer wellness, clinical diagnostics, and enterprise safety domains. Manufacturers must align R&D roadmaps with the divergent validation standards and battery-performance tradeoffs that each segment demands.
Product Type:
Margin pools concentrate in devices that combine medical-grade sensing with consumer-grade scale, where subscription attach rates and replacement cycles compound lifetime value.
- Smartwatches:Multi-sensor arrays integrating PPG, accelerometry, and bioimpedance support FDA-cleared ECG and SpO2 functions. Hospital-at-home reimbursement expansion in the United States is pulling Apple Watch and Galaxy Watch variants into remote patient monitoring workflows for cardiac event surveillance.
- Hearables:Active noise cancellation and real-time language translation are expanding use cases beyond audio into biometric monitoring via in-ear PPG and core-temperature estimation. EU MDR Annex XVI expansion is forcing bifurcated SKU strategies between health-claim and wellness-only positioning for manufacturers adding physiological measurement features.
- Fitness Trackers:Entry-tier devices prioritize battery longevity and step-count accuracy for price-sensitive South Asian and African export markets.
- Smart Glasses:Enterprise safety applications in Germany's chemical processing corridor and US Gulf Coast petrochemical clusters are driving unified platform contracts combining location tracking with environmental hazard detection.
Smartwatches hold installed capacity. Hearables are rotating up the share rankings.
Technology:
Connectivity choice determines power budget allocation and cloud-sync architecture, with low-energy protocols dominating wrist-worn form factors below 30 grams.
- Bluetooth:Low-power chipsets from Nordic Semiconductor and Qualcomm enable continuous physiological streaming to paired smartphones while preserving multi-day battery endurance. Fitness tracker volume in India PLI-subsidized assembly lines depends on Bluetooth 5.3's extended range for rural connectivity gaps.
- GPS:Multi-band GNSS reception supports premium outdoor navigation in aviation and endurance sports niches where Garmin Ltd. maintains positioning dominance. Dual-frequency L1/L5 signal processing is elevating accuracy standards for trail-running and backcountry applications.
- Wi-Fi:Direct cloud upload capability bypasses smartphone tethering for standalone health-monitoring devices in senior living facilities.
- NFC:Contactless payment and access control integration is standardizing across mid-tier smartwatches for transit and retail authentication workflows.
Bluetooth holds installed capacity. GPS is rotating up the share rankings.
End User:
Customer type dictates regulatory pathway complexity and average selling price tolerance, with clinical channels commanding 3-5x consumer hardware premiums.
- Consumers:Wellness-oriented purchasers prioritize circadian rhythm optimization and subscription-tier analytics over step counting, driving ring-form-factor adoption from Oura and Ultrahuman. Battery energy-density plateaus below 300 Wh/kg cap always-on sampling rates for multi-sensor arrays in this price-sensitive segment.
- Healthcare Professionals:Continuous glucose monitor and cardiac event recorder deployment in acute-care substitution workflows requires FDA 510(k) clearance and CMS reimbursement coding alignment. Embedded firmware engineers with ISO 13462 familiarity command 40-60% salary premiums, inflating R&D fixed costs for mid-tier entrants targeting this channel.
- Sports Enthusiasts:GPS-dominant outdoor and aviation wearables occupy premium endurance-sports niches where materials-science capabilities differentiate competitive positioning.
- Military:Ruggedized biometric fatigue alert systems are consolidating around integrated platform contracts for multi-site standardization in logistics warehouse networks.
Consumers hold installed capacity. Healthcare Professionals are rotating up the share rankings.
Application:
Use case maturity varies sharply, with preventive health surveillance requiring 18-24 month algorithm training cycles against reference-standard cohorts while entertainment functions iterate quarterly.
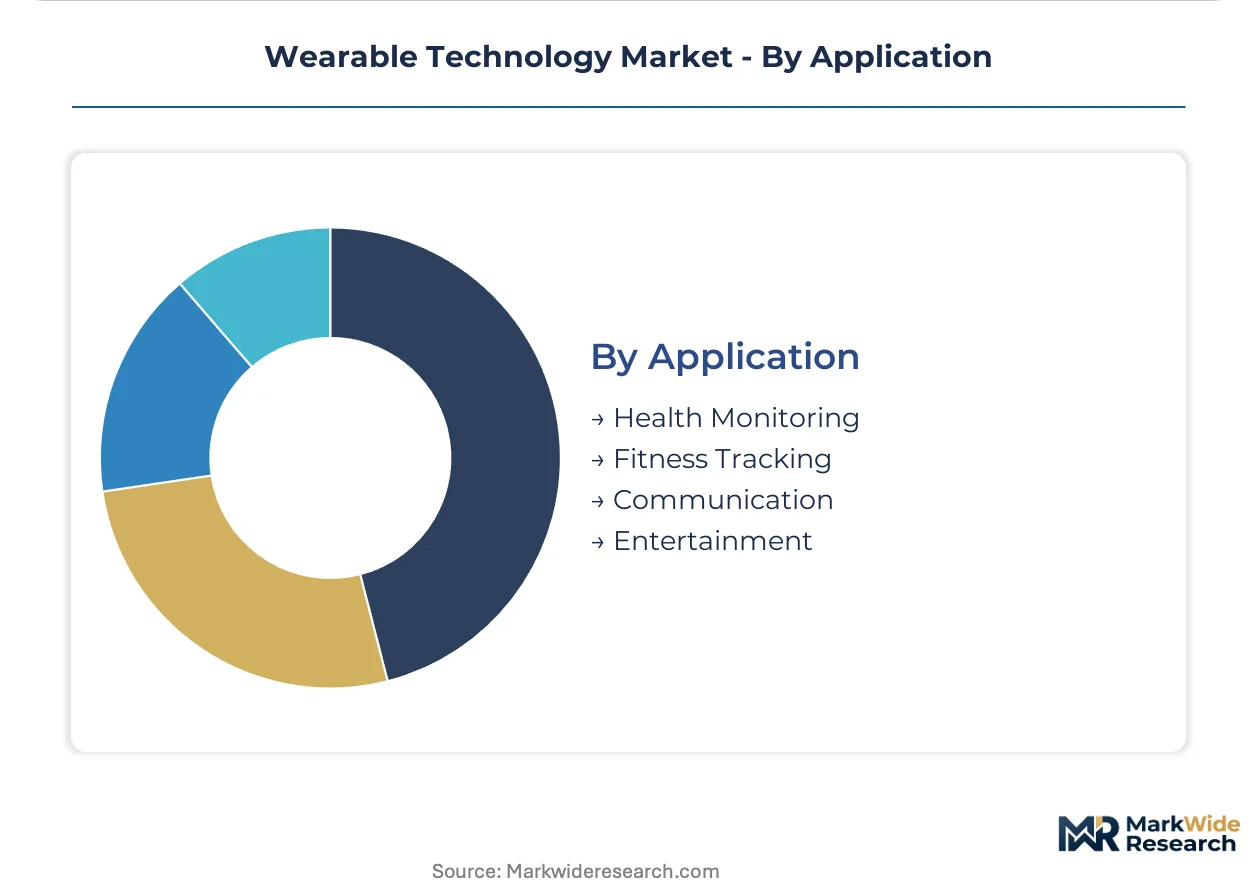
- Health Monitoring:Multimodal sensor fusion integrating PPG, bioimpedance, and temperature data streams into validated digital biomarkers supports prediabetes management via spectroscopic near-infrared interferometry platforms approaching clinical-grade correlation thresholds. FDA tightening of 510(k) clearance thresholds for pulse oximetry and ECG claims is compressing product development timelines.
- Fitness Tracking:Step-count accuracy and sleep-stage classification anchor purchasing decisions in entry-tier consumer segments where Oura ring-form-factor devices are supplanting legacy fitness bands. Photoplethysmography optics miniaturization advances are enabling SpO2 monitoring in sub-30-gram form factors.
- Communication:Hands-free industrial task support in oilfield operations demands unified dashboards combining location tracking with biometric fatigue alerts.
- Entertainment:Real-time language translation and active noise cancellation are expanding hearable use cases beyond audio into productivity and travel workflows.
Health Monitoring holds installed capacity. Fitness Tracking is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes clinical-grade remote patient monitoring reimbursement, while Asian markets emphasize battery longevity and cost-optimized fitness tracking for price-sensitive consumer segments.
United States
Hospital-at-home program expansion drives demand for FDA-cleared cardiac event recorders and continuous glucose monitors. CMS coding changes for remote patient monitoring reimburse acute-care substitution workflows. Greater Boston anchors medical-device R&D clusters where embedded firmware engineers command salary premiums for ISO 13462 expertise.
Germany
Industrial safety wearable procurement consolidates around unified platform contracts combining location tracking with biometric fatigue alerts. EU MDR Annex XVI expansion forces parallel technical documentation for CE-marked and non-CE product variants. The chemical processing corridor in North Rhine-Westphalia standardizes multi-site deployments to reduce training overhead.
China
Domestic brands capture volume in entry-tier fitness trackers for South Asian and African export markets. PIPL data localization mandates force redundant cloud infrastructure deployments alongside GDPR Article 44 transfer mechanisms. Shenzhen's electronics manufacturing ecosystem enables rapid LED-PD packaging advances for sub-30-gram SpO2 monitoring devices.
India
PLI scheme incentives attract final assembly operations targeting price-sensitive consumer segments across South Asia and Africa. BIS certification requirements shape product specification tiers for domestic market entry. Maharashtra's electronics manufacturing zones concentrate fitness tracker assembly lines dependent on Bluetooth 5.3 extended range for rural connectivity gaps.
Japan
Aging demographics accelerate demand for standalone health-monitoring devices with direct Wi-Fi cloud upload capability in senior living facilities. METI standards guide photoplethysmography optics miniaturization investments. Kanto region technology clusters specialize in low-power Bluetooth chipset integration for multi-day battery endurance.
Wearable Technology Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the wearable technology market. Silicon-level control over sensor fusion and neural processing units separates vertically integrated players from component-dependent assemblers. Three archetypes dominate: consumer electronics conglomerates with healthcare regulatory infrastructure, GPS-specialized outdoor endurance brands, and ring-form-factor wellness platform operators. Competitive moves concentrate on M&A for biomedical firmware talent and strategic partnerships with specialty pharmacy distribution channels.
Within the integrated technology tier, Apple Inc. and Samsung Electronics Co., Ltd. occupy positions defined by silicon and ecosystem control, while Garmin Ltd. anchors the GPS-dominant outdoor specialist segment. These entities exemplify divergent strategic postures: consumer-scale health-communication convergence versus premium endurance-sports niche capture. The specialist tier includes ring-form-factor operators and industrial safety platform providers competing on materials-science capabilities and subscription attach rates rather than hardware volume scale.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Garmin Ltd. |
| Fitbit LLC |
| Huawei Technologies Co., Ltd. |
| Xiaomi Corporation |
| Alphabet Inc. |
| Sony Group Corporation |
| Adidas AG |
| Others |
Supply Flow & Price Mechanics
Photoplethysmography LED-PD packaging miniaturization is displacing legacy discrete sensor assemblies, simultaneously shifting procurement gravity toward Shenzhen semiconductor foundries and compressing bill-of-materials differentials between premium and mid-tier smartwatch tiers.
Pricing Analysis
Long-term offtake contracts for MEMS wafer supply anchor pricing stability for accelerometer-dependent fitness trackers, while spot-market purchasing for lithium-polymer cells exposes entry-tier assemblers to commodity volatility. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared cardiac event recorders from wellness-only positioning and unbranded white-label devices. Cost compression in the economy tier is intensifying because India PLI-subsidized assembly lines are flooding South Asian and African export markets. Healthcare professionals demonstrate lowest price sensitivity due to reimbursement alignment, while consumers in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for multi-wavelength PPG arrays have extended due to foundry capacity allocation toward automotive lidar applications, forcing wearable OEMs into buffer stock positions. Taiwan, China, and South Korea concentrate supply for MEMS accelerometers, Bluetooth chipsets, and lithium-polymer cells respectively. Taiwan foundry concentration creates single-source vulnerability for gyroscope wafers, with geopolitical contingency threatening shipment schedules. Distribution runs through specialty pharmacy channels for clinical-grade devices and consumer electronics retail for wellness-oriented segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wearable technology demand is recovering from component allocation troughs as hospital-at-home reimbursement expansion pulls continuous monitoring devices into acute-care substitution workflows.
For Market Incumbents: Shield installed base erosion by accelerating FDA 510(k) pathway investments for pulse oximetry and ECG claims before clearance thresholds tighten further. Deepen backward integration into photoplethysmography optics through semiconductor foundry partnerships to secure LED-PD packaging capacity against automotive sector competition.
For New Entrants and Emerging Players: Remote patient monitoring algorithm development services represent an under-served layer where incumbent OEMs lack ISO 13462-certified firmware engineering depth. Target specialty pharmacy distribution partnerships with CVS Health and Walgreens Boots Alliance to bypass saturated consumer electronics retail. Lead with subscription-tier circadian rhythm analytics rather than hardware volume scale.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ring-form-factor wellness platforms holding Oura-equivalent subscription attach rates but lacking clinical-validation infrastructure. Five-to-ten year viability hinges on EU MDR Annex XVI compliance cost absorption and biometric data residency architecture. Watch FDA digital-health pilot program expansions as signal for reimbursement-code alignment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Investment | CMS reimbursement coding alignment unlocks hospital-at-home program participation for cardiac event recorders. |
| Silicon-Level Neural Processing Integration | On-device inference capability collapses power-performance tradeoffs that previously forced battery-life compromises. |
| Specialty Pharmacy Distribution Partnership | CVS Health and Walgreens Boots Alliance infrastructure bypasses traditional consumer electronics retail for clinical-grade devices. |
| EU MDR Annex XVI Parallel Documentation | CE-marked and non-CE product variant maintenance preserves market access as physiological measurement regulations expand. |
| Biomedical Firmware Talent Acquisition | ISO 13462-experienced embedded signal-processing engineers command salary premiums that inflate R&D fixed costs for mid-tier entrants. |
Methodological Framework
Cross-validation between primary interviews with regulatory affairs leads at FDA-cleared wearable OEMs and secondary validation through FDA 510(k) premarket notification databases anchors the qualitative findings. Conversations with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and specialty pharmacy distribution heads inform demand-side dynamics. Bottom-up triangulation against top-down CMS reimbursement coding data and EU MDR technical documentation requirements ensures segmentation integrity.
Sensitivity analysis around MEMS foundry capacity allocation scenarios and lithium-polymer commodity price bands stress-tests projection robustness across the analysis window. Segmentation dimensions span product type, connectivity protocol, end-user archetype, and application maturity, with algorithm training cycle duration modeled as a wearable-specific velocity factor. CAGRs derive from installed base replacement curves and subscription attach rate compounding rather than linear extrapolation.
Underlying assumptions cover FDA digital-health pilot program stability and EU AI Act biometric risk classification implementation timelines, with deviation risk concentrated in Taiwan foundry geopolitical contingency and embedded firmware talent availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
India Smart Wearable Market
Wearable Technology
Women's Watch Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Global Smartwatch Battery Market
Wearable Technology
Water Resistant Watch Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Wearable Computing Market
Wearable Technology
US Pet Wearable Market
Wearable Technology
Bluetooth Wearable Scanner Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Latin America Smartwatch Market
Wearable Technology
3D Printed Wearables Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
APAC Smart Watch Market