
 Intelligent Power Switches Market | 2026-2036
Intelligent Power Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Power Switches Market Outlook
Market Context
Japanese power semiconductor foundries is recalibrating capacity allocation toward automotive-grade intelligent switches as EV production schedules tighten across Toyota, Honda, and Nissan supply chains. Infineon Technologies AG leverages its Dresden fabrication complex to sustain output of 300mm thin-wafer IGBT devices for industrial motor drives. STMicroelectronics anchors its competitive position through integrated silicon carbide substrate sourcing from its Swedish acquisition and in-house epitaxy operations. Texas Instruments Incorporated differentiates via proprietary gallium nitride process technology deployed in high-frequency consumer adapter applications.
Technical Definition and Segment Structure
Intelligent power switches are semiconductor or electromechanical devices incorporating integrated sensing, protection logic, and diagnostic feedback circuits to manage load switching with autonomous fault isolation and real-time status reporting. These components typically operate at voltage classes from 12V automotive battery rails to 1,200V industrial bus levels, with on-resistance specifications below 1 milliohm for high-current MOSFET configurations. MOSFET switches command the largest revenue share due to their dominance in consumer electronics adapters and low-voltage automotive body electronics, while IGBT switches capture the highest absolute growth rate from traction inverter demand in battery electric vehicles. Solid-state technology segments attract premium pricing for applications requiring million-cycle endurance, whereas electromechanical relay switches retain cost advantages in legacy industrial equipment refresh cycles where digital feedback is non-essential.
Regulatory Environment
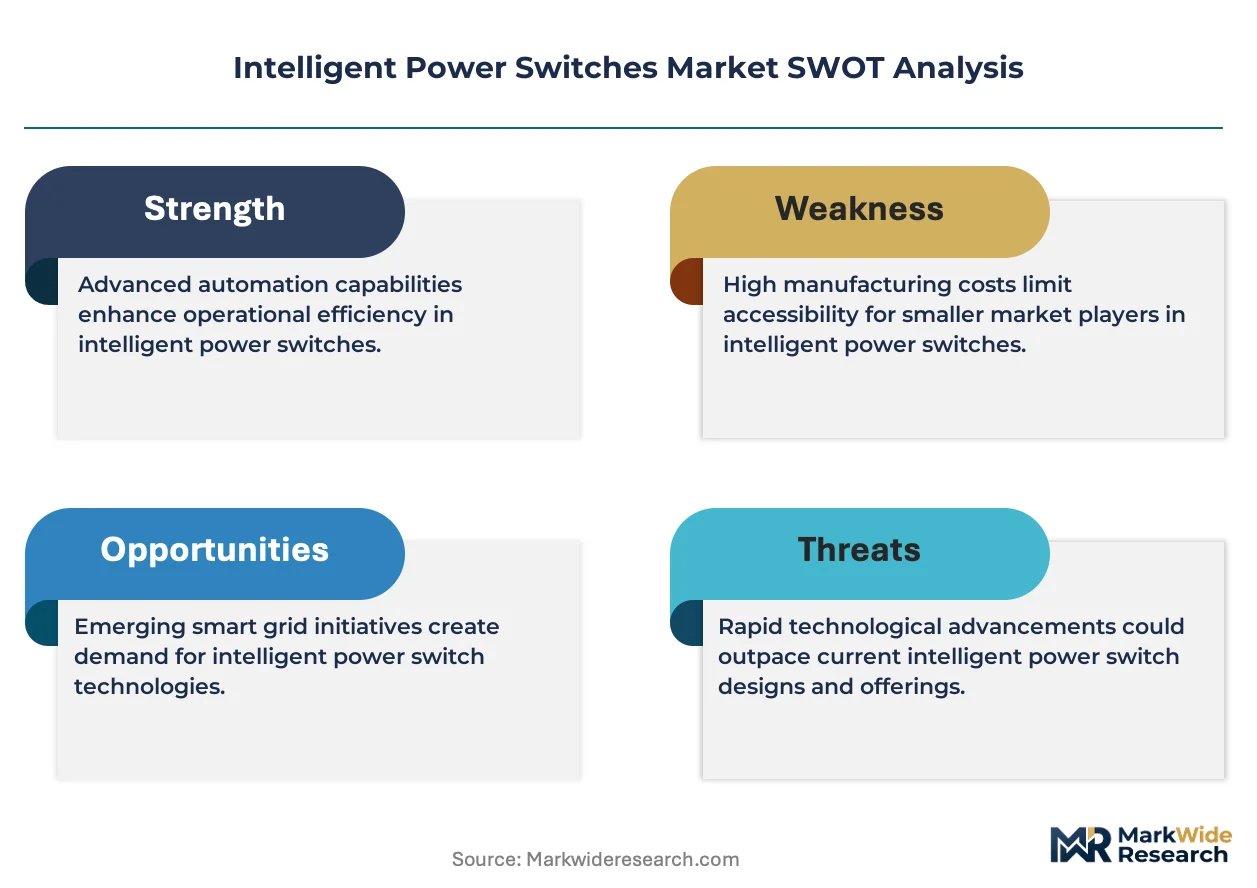
The U.S. NHTSA Federal Motor Vehicle Safety Standards and EPA greenhouse gas emission mandates jointly compel automotive Tier-1 suppliers to specify intelligent switches with embedded diagnostic capability for predictive maintenance and fail-operational architectures. China's MIIT dual carbon goals and GB/T standards for new energy vehicle power electronics are accelerating domestic certification requirements for SiC-based intelligent switch modules in bus and heavy truck platforms. REACH substance restrictions in Europe constrain solder alloy compositions and molding compound chemistries, forcing reformulation of package interconnect systems. Stakeholders must monitor divergence between regional semiconductor subsidy programs and evolving functional safety standards as determinants of manufacturing location and product qualification strategy.
Market Dynamics
Silicon carbide substrate maturation is compressing switching losses in traction inverters, forcing incumbent silicon-MOSFET suppliers to reposition toward body electronics and consumer adapter segments where cost structures still favor legacy technology.
Growth Catalysts
- Automotive Electrification Mandates:EPA greenhouse gas standards and NHTSA safety regulations compel Tier-1 suppliers to embed predictive diagnostic capability in power distribution modules for battery electric vehicles.
- Wide-Bandgap Material Advances:SiC epitaxy improvements from Swedish substrate operations enable 1,200V-class intelligent switches with thermal envelopes exceeding silicon limits.
- Industrial Motor Drive Refresh:Factory automation retrofits across Germany's manufacturing base create replacement demand for 300mm thin-wafer IGBT devices with integrated protection logic.
Market Restraints
- Substrate Supply Concentration:Wolfspeed and Coherent control critical SiC boule capacity, creating single-source vulnerability for 150mm wafer ramps.
- REACH Compliance Costs:ECHA substance restrictions force reformulation of solder alloys and molding compounds, elevating qualification timelines for European automotive certifications.
- Silicon Cost Arbitrage:Mature 8-inch silicon foundry capacity in China's Yangtze River Delta underprices SiC alternatives below 650V operating classes.
Strategic Opportunities
- Heavy Truck Electrification:China's MIIT dual carbon goals and GB/T standards for bus platforms accelerate domestic certification requirements for SiC-based intelligent switch modules.
- GaN Consumer Adapter Penetration:Proprietary gallium nitride process technology enables high-frequency operation in 65W+ fast-charging applications where silicon superjunction MOSFETs face thermal constraints.
- Service-Unbundled Distribution:Direct procurement from foundry-integrated module houses is displacing traditional distributor channels for high-volume automotive programs.
Industry Challenges
- Functional Safety Certification Bottlenecks:ISO 26262 ASIL-D qualification for automotive intelligent switches demands 18-24 month validation cycles that compress product launch windows.
- Epitaxy Equipment Lead Times:MOCVD reactor delivery schedules from Japanese and German toolmakers extend beyond 12 months, constraining SiC capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Power Switches Market |
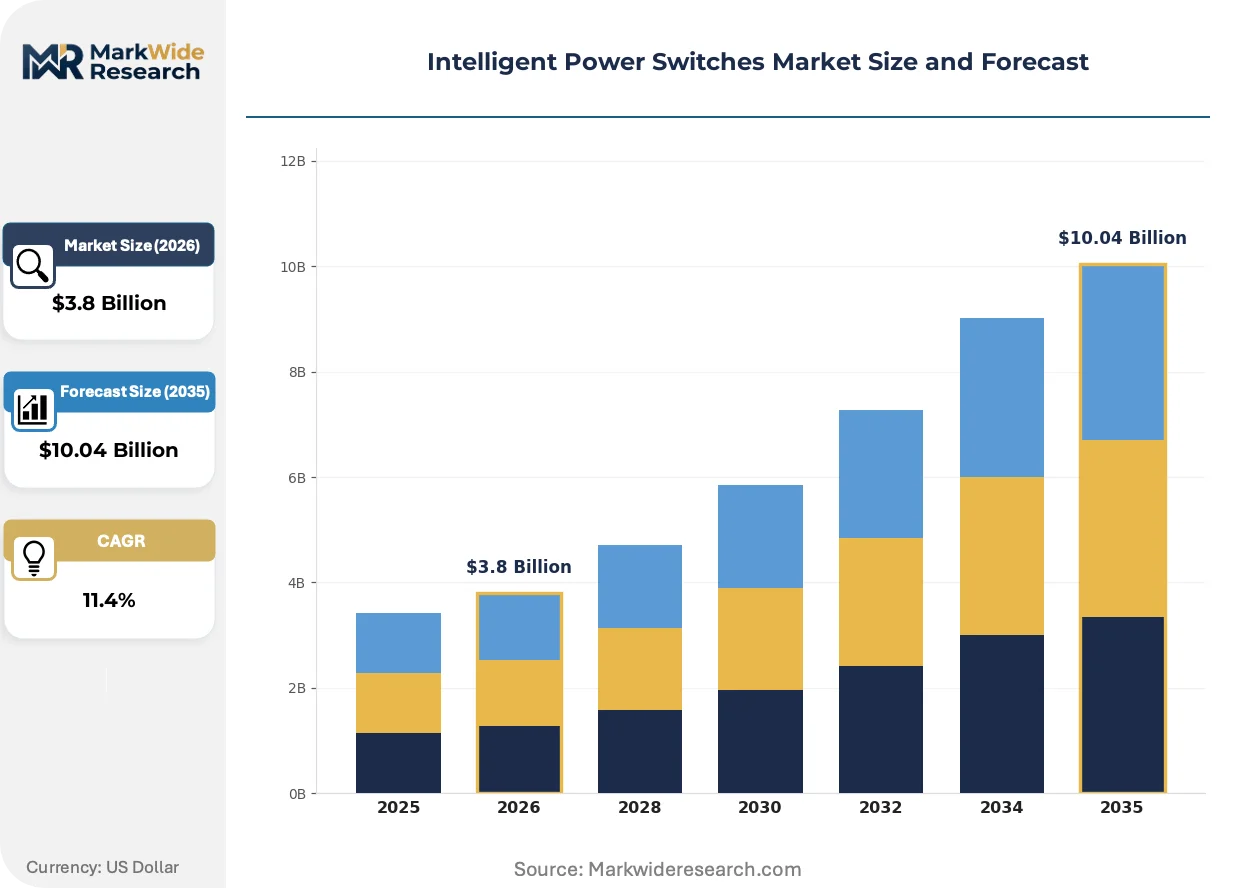
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transistor Switches, Relay Switches, MOSFET Switches, IGBT Switches Application: Consumer Electronics, Industrial Automation, Smart Grids, Automotive Systems Technology: Solid-State Technology, Electromechanical Technology, Hybrid Technology, Digital Technology End User: Manufacturers, OEMs, End Consumers, Device Integrators |
| Companies Covered | ROHM CO., LTD., Fuji Electric Co. LTD, Infineon Technologies AG, Toshiba Electronic Devices & Storage Corporation, Renesas Electronics Corporation, STMicroelectronics, Microchip Technology Inc., onsemi, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Power Switches Market Strategic Shifts
Material substitution and autonomous protection integration are compressing the traditional separation between power switching and system-level diagnostics. These forces are reconfiguring supplier value capture and customer procurement criteria simultaneously.
Silicon carbide MOSFET technology is consolidating position in 800V automotive architectures. Traction inverter programs at Toyota, Honda, and Nissan supply chains are adopting SiC intelligent switches for battery management systems and motor drives. This material transition is consolidating supplier margins around substrate-integrated players while pressuring pure-play silicon foundries to defend remaining 400V platform allocations.
REACH substance restrictions are forcing package interconnect reformulations across European automotive supply chains. ECHA constraints on lead-bearing solders and halogenated molding compounds elevate material qualification burdens. German Tier-1 suppliers are responding by qualifying copper-clip and sintered-die-attach alternatives ahead of 2026 enforcement milestones.
Buyer consolidation around vertically integrated module suppliers is compressing traditional component distribution. Automotive OEMs in Japan and the United States are awarding direct sourcing contracts to foundries with in-house packaging capability. This channel shift is most visible in traction inverter procurement, where module-level qualification replaces discrete component approval workflows.
Intelligent Power Switches Market Segmentation
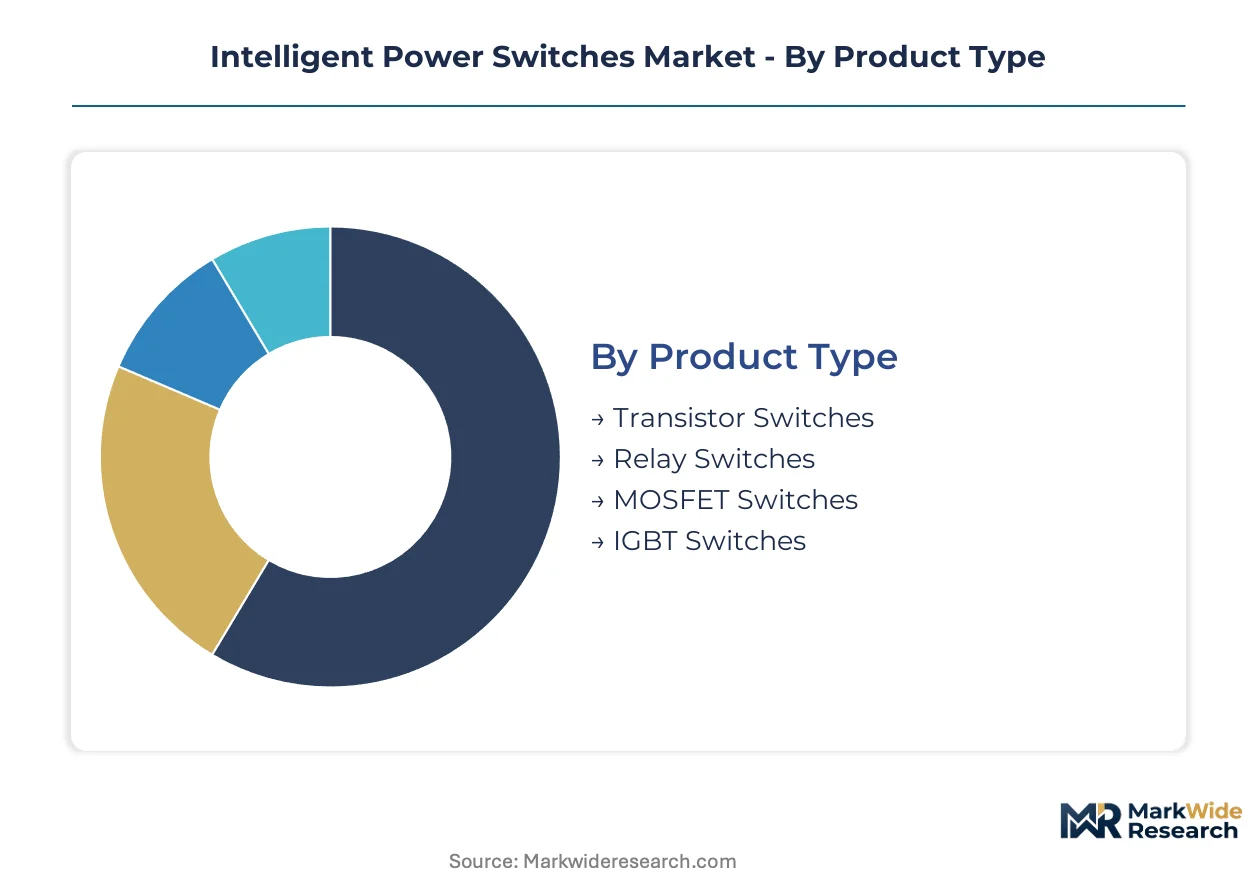
Segmentation in intelligent power switches reveals how technical specifications, thermal envelopes, and diagnostic integration levels map to divergent procurement criteria across automotive, industrial, and consumer verticals. Suppliers must align wafer process technology and package protection features with the fault-tolerance requirements and voltage classes of each target application.
Product Type:
Customization intensity spans from commodity relay replacements to application-specific MOSFET and IGBT designs with embedded sensing and protection logic.
- MOSFET Switches:Metal-oxide-semiconductor field-effect transistors dominate low-voltage automotive body electronics and consumer adapter applications where sub-milliohm on-resistance specifications minimize conduction losses. Demand concentrates in China's Yangtze River Delta manufacturing cluster, where domestic foundries exploit mature 8-inch silicon capacity to underprice wide-bandgap alternatives below 650V classes.
- IGBT Switches:Insulated-gate bipolar transistors integrate high-current handling with gate-controlled switching for traction inverters and industrial motor drives operating at 600V to 1,200V bus levels. Toyota, Honda, and Nissan supply chains in Japan are accelerating procurement of 300mm thin-wafer devices with integrated protection logic as EV production schedules tighten.
- Transistor Switches:Bipolar and Darlington configurations retain niche positions in legacy industrial equipment where simple on-off control suffices and digital feedback is non-essential.
- Relay Switches:Electromechanical contacts maintain cost advantages in refresh cycles of aging factory automation infrastructure across Germany's manufacturing base.
Leading the category by volume: MOSFET Switches. Growing fastest: IGBT Switches.
Application:
Cost tier differentiation separates premium automotive-grade qualification from standard industrial and economy consumer segments.
- Automotive Systems:Battery electric vehicle platforms demand intelligent switches with ISO 26262 ASIL-D functional safety certification and embedded diagnostic capability for predictive maintenance. EPA greenhouse gas standards and NHTSA safety regulations compel Tier-1 suppliers to specify fault-operational architectures in power distribution modules.
- Industrial Automation:Factory motor drives and robotics systems require 1,200V-class devices with million-cycle endurance and real-time status reporting for condition-based monitoring. Germany's manufacturing base is driving replacement demand as retrofit programs upgrade legacy relay-based controls.
- Consumer Electronics:Fast-charging adapters and computing power supplies prioritize high-frequency operation and thermal efficiency in compact form factors.
- Smart Grids:Utility-scale power distribution infrastructure specifies solid-state switches with autonomous fault isolation for grid stability management.
Dominant by revenue: Automotive Systems. Expanding most quickly: Industrial Automation.
Technology:
Volume concentration favors solid-state architectures, while margin capture concentrates in hybrid and digital variants with advanced protection integration.
- Solid-State Technology:Silicon carbide MOSFET and IGBT implementations enable switching frequencies and thermal envelopes exceeding electromechanical limits. Wolfspeed and Coherent substrate advances are reducing switching losses in 800V automotive architectures.
- Digital Technology:Microcontroller-integrated switches with programmable protection thresholds and communication interfaces command premium positioning in automotive body electronics.
- Hybrid Technology:Combinations of solid-state and electromechanical elements balance cost and endurance in medium-voltage industrial applications.
- Electromechanical Technology:Conventional relay mechanisms persist where digital feedback and autonomous fault isolation provide no operational advantage.
Highest shipment volume: Solid-State Technology. Steepest expansion trajectory: Digital Technology.
End User:
Procurement scale and technical specification authority separate large-volume OEM direct sourcing from fragmented integrator and consumer channels.
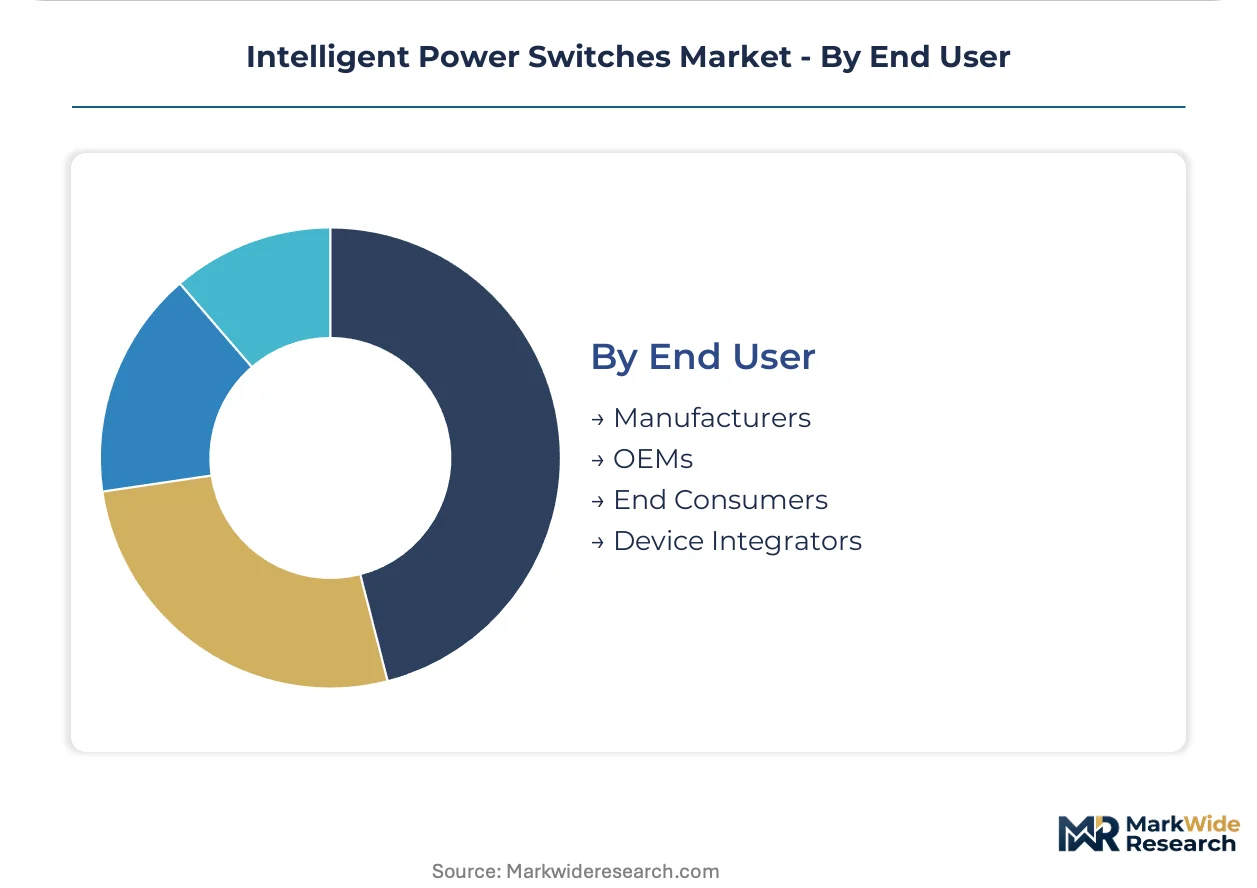
- OEMs:Automotive and industrial original equipment manufacturers award direct contracts to foundry-integrated module houses, displacing traditional distributor channels for traction inverter and motor drive programs.
- Device Integrators:Subsystem suppliers combine intelligent switches with thermal management and control electronics for application-specific module supply to Tier-1 automotive and industrial customers.
- Manufacturers:Component producers purchase discrete switches for integration into downstream equipment across consumer and industrial product lines.
- End Consumers:Replacement and aftermarket procurement of electromechanical relays in legacy industrial maintenance represents minimal revenue contribution.
Controlling procurement volume: OEMs. Gaining share fastest: Device Integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon carbide substrate production concentrates in North Carolina and New York State, anchoring United States supply security for wide-bandgap intelligent switches. This raw-material localization shapes competitive positioning across automotive and industrial demand centers.
United States
EPA greenhouse gas standards and NHTSA safety regulations compel Detroit-based automotive OEMs to specify intelligent switches with embedded diagnostic capability. Wolfspeed's Durham, North Carolina operations supply SiC substrates for 800V traction inverter programs. Michigan's automotive corridor hosts Tier-1 suppliers scaling module-level qualification workflows.
Germany
Industrial motor drive refresh cycles across Baden-Württemberg and Bavaria create replacement demand for IGBT devices with integrated protection logic. ECHA REACH restrictions on lead-bearing solders force reformulation of package interconnect systems ahead of 2026 enforcement. Dresden's fabrication complex sustains output of 300mm thin-wafer devices.
China
MIIT dual carbon goals and GB/T standards for new energy vehicles accelerate domestic certification requirements for SiC-based modules. Yangtze River Delta manufacturing clusters scale 12-inch power semiconductor wafer capacity through domestic foundries and international joint ventures. Shanghai and Suzhou anchor procurement concentration for battery management systems.
Japan
Automotive electrification programs at Toyota, Honda, and Nissan tighten EV production schedules and accelerate procurement of MOSFET and IGBT switches. METI industrial policy supports substrate-integrated players through domestic foundry recalibration toward automotive-grade output. Kyushu and Kansai regions concentrate power semiconductor fabrication capacity.
South Korea
Seoul Capital Area device integrators combine intelligent switches with thermal management for automotive module supply to domestic and export customers. National semiconductor subsidy programs target captive supply of wide-bandgap materials for 800V platform penetration. Busan-Ulsan industrial corridors support packaging and testing infrastructure expansion.
Intelligent Power Switches Market Competitive Environment
Global majors compete with regional champions across substrate integration and foundry-scale dimensions. The vendor base organizes around three tiers: vertically integrated substrate-to-module houses, pure-play silicon foundries defending legacy voltage classes, and specialist device integrators combining protection logic with thermal management. Consolidation pressure concentrates in 800V automotive qualification workflows where module-level approval replaces discrete component sourcing. Dominant competitive moves include backward integration into epitaxy operations and direct OEM contracting displacing traditional distribution channels.
Within the substrate-integrated tier, Infineon Technologies AG and STMicroelectronics exemplify European anchoring through captive supply chains and in-house packaging capability. Texas Instruments Incorporated occupies a position among North American technology-differentiated players leveraging proprietary process architectures. ROHM CO., LTD. and Renesas Electronics Corporation represent Japanese fabricators recalibrating capacity allocation toward automotive-grade intelligent switches as domestic OEM electrification schedules tighten.
| Leading Market Players |
|---|
| ROHM CO., LTD. |
| Fuji Electric Co. LTD |
| Infineon Technologies AG |
| Toshiba Electronic Devices & Storage Corporation |
| Renesas Electronics Corporation |
| STMicroelectronics |
| Microchip Technology Inc. |
| onsemi |
| Texas Instruments Incorporated |
| Others |
Value Chain & Pricing Dynamics
Captive substrate-to-module integration anchors pricing power for Wolfspeed and Coherent in silicon carbide boule supply, while pure-play silicon foundries compete on cost in legacy voltage classes below 650V. This structural divide forces buyers to trade thermal performance premiums against mature silicon cost structures across automotive and industrial procurement workflows.
Pricing Analysis
Warranty and diagnostic service bundling separates premium automotive-grade contracts from unbundled industrial spot purchases. Three-tier pricing structure across automotive-certified, industrial-standard, and economy consumer levels reflects ISO 26262 ASIL-D qualification burdens and volume scale effects. Pricing pressure stems from China's Yangtze River Delta foundries exploiting mature 8-inch silicon capacity to underprice wide-bandgap alternatives. Automotive OEMs exhibit lowest price sensitivity given fail-operational architecture mandates, while consumer adapter manufacturers face acute cost compression.
Supply Chain Analysis
ISO 26262 ASIL-D qualification gates concentrate supply among substrate-integrated players with in-house packaging and epitaxy operations. Raw material flows draw from Wolfspeed's North Carolina boule production, Coherent's New York substrate operations, and Swedish epitaxy facilities. Silicon carbide wafer supply rests on single-source vulnerability for 150mm ramps, with MOCVD reactor lead times from Japanese and German toolmakers extending capacity expansion timelines. Distribution runs through direct OEM contracting for automotive traction inverters, displacing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around substrate-integrated module houses as ISO 26262 ASIL-D qualification timelines and SiC supply concentration force weaker silicon-only players toward niche voltage classes or exit.
For Market Incumbents: Lock in captive SiC substrate supply through long-term offtake agreements with Wolfspeed or Coherent before capacity allocation tightens further. Defend automotive module positions by accelerating in-house packaging qualification workflows to match STMicroelectronics' integrated epitaxy model. Prioritize Dresden or Kyushu capacity additions for 300mm thin-wafer IGBT output to serve Toyota and Honda supply chain demand. For New Entrants and Emerging Players: Device integrators with thermal management expertise represent the most penetrable channel archetype, particularly in Seoul Capital Area automotive module supply where national subsidy programs support captive wide-bandgap material development. Target China's heavy truck electrification segment under MIIT dual carbon goals, where GB/T certification requirements for SiC modules remain less saturated than passenger vehicle traction inverters. Pursue GaN consumer adapter white space where proprietary process technology commands premium positioning above 65W fast-charging applications. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated European or Japanese substrate-to-module houses seeking packaging capability in target geographies. Long-term viability favors foundries with demonstrated automotive qualification track records and in-house epitaxy operations over pure-play silicon players facing margin compression below 650V. Watch MOCVD reactor delivery schedules from Japanese and German toolmakers as the critical inflection signal for SiC capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Captive boule sourcing from Wolfspeed or Coherent insulates margin against raw material concentration risk. |
| Automotive ASIL-D Certification Investment | ISO 26262 qualification opens direct OEM contracting for traction inverter and battery management system modules. |
| GaN Process Technology Licensing | Proprietary high-frequency architectures penetrate 65W+ consumer adapter markets where silicon faces thermal limits. |
| Direct OEM Distribution Channel Development | Module-level qualification workflows displace traditional distributor relationships in high-volume automotive programs. |
| Heavy Truck Platform Certification | China GB/T compliance for SiC modules in bus and truck applications accesses MIIT dual carbon procurement mandates. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs combined with primary interviews across Tier-1 supplier procurement leads, OEM platform engineers, semiconductor foundry operations managers, and power electronics R&D directors. SEC 10-K disclosures, EPA emission standard documentation, NHTSA safety filings, and MIIT new energy vehicle production databases supplied validation benchmarks. Bottom-up wafer capacity estimates and top-down automotive electrification spend projections were triangulated against foundry utilization reports.
Segment-level granularity modeled MOSFET and IGBT product types across automotive systems, industrial automation, consumer electronics, and smart grid applications, with technology splits across solid-state, digital, hybrid, and electromechanical implementations. End-user channels separated OEM direct procurement from device integrator and manufacturer tiers. CAGRs derived from regression analysis of historical silicon carbide adoption curves against EPA and MIIT regulatory enforcement timelines, with cross-validation against vehicle production database trajectories.
Several conditions sit outside the modeled scope, including potential relaxation of EPA greenhouse gas standards, acceleration of REACH substance restriction enforcement beyond 2026 milestones, and breakthroughs in gallium oxide or diamond substrate commercialization. Forecasts reflect assumptions about SiC epitaxy yield improvements and automotive platform voltage standardization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Rotary Limit Switches Market
Switches
Level Switches Market
Switches
South Korea Reed Sensors Switches Market
Switches
Global Safety Switches Market
Switches
Hazardous Location Limit Switches Market
Switches
North America Low Voltage Switchgear Market
Switches
Surface Mount Switch Market
Switches
North America Medium Voltage Switchgear Market
Switches
Low Voltage Disconnect Switch Market
Switches
5G Electromechanical RF Switch Market
Switches
Japan Reed Sensors Switches Market
Switches
UAE Switchgear Market
Switches
UK Reed Sensors Switches Market
Switches
Low Voltage Switchgear Market
Switches
Membrane Switch Market
Switches
Campus Switches Market