
 Event Stream Processing Market | 2026-2036
Event Stream Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Event Stream Processing Market Analysis
Platform licensing revenue is reshaping competitive economics in event stream processing, pulling margin pools away from perpetual software sales toward recurring consumption models. Amazon Web Services leverages its cloud infrastructure scale to dominate managed streaming service delivery. Microsoft anchors enterprise adoption through deep integration with productivity and analytics suites. Confluent specializes in Apache Kafka-based distribution, extending its control over the open-source commercialization layer.
Event stream processing encompasses technologies that continuously ingest, analyze, and act on data in motion rather than stored batches, typically operating at millisecond latencies to enable immediate operational responses. The primary commercial purpose centers on detecting patterns, anomalies, and opportunities as events occur across distributed digital systems. Cloud-based deployment leads in revenue contribution due to elastic scaling economics, while edge computing represents the fastest-expanding configuration as manufacturers push analytics closer to physical assets. Software components capture the deepest margin pools, though services are expanding fastest as enterprises require integration expertise for hybrid architectures.
The EU AI Act imposes transparency obligations on automated decision systems, directly shaping stream processing requirements for explainability and audit trails in European deployments. HIPAA in the United States mandates strict data handling protocols, constraining how healthcare organizations architect real-time patient data pipelines. ISO standards for information security management further condition market access for vendors serving regulated industries. Stakeholders must monitor how emerging AI governance frameworks redefine the boundary between permissible real-time inference and prohibited automated decision-making without human oversight.
Market Dynamics
Platform licensing economics are concentrating margin pools around recurring consumption models, while the EU AI Act and GDPR impose auditable streaming requirements that reshape architectural investments across financial services and automotive verticals.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision systems in European deployments now require explainability layers and immutable audit trails, accelerating investments in compliant stream processing infrastructure.
- Edge analytics in German automotive:Industrial manufacturers are embedding millisecond-latency processing directly onto production lines to enable predictive maintenance and quality control without cloud round-trips.
- Real-time fraud detection:Financial services firms are expanding operational deployments to intercept suspicious transaction patterns as they occur rather than in post-hoc batch analysis.
Market Restraints
- Specialized engineering talent scarcity:The shallow pool of professionals fluent in distributed systems architecture, stream processing frameworks, and low-latency optimization constrains deployment velocity.
- Hybrid integration complexity:Enterprises maintaining on-premises legacy data infrastructure face substantial reconfiguration costs to unify batch and streaming pipelines across cloud-edge environments.
- HIPAA data handling friction:Healthcare organizations in the United States encounter architectural constraints when routing real-time patient data through streaming pipelines, limiting addressable vertical expansion.
Strategic Opportunities
- ISO 27001 certification tailwinds:Information security management standards are becoming table stakes for vendor selection in regulated industries, creating differentiation for pre-certified platform providers.
- Convergence of stream processing and ML inference:The integration of real-time feature engineering with model serving is opening new application categories in predictive maintenance and dynamic pricing.
- Underpenetrated industrial IoT in Japan:METI-supported smart factory initiatives are creating demand for edge-streaming solutions among precision manufacturers with limited incumbent vendor relationships.
Industry Challenges
- Kafka operational expertise gaps:Organizations struggle to hire and retain engineers capable of tuning distributed streaming clusters for production reliability at scale.
- Multi-cloud portability requirements:Buyers increasingly demand workload mobility across AWS, Azure, and GCP, forcing vendors to abstract proprietary optimizations and compress differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Event Stream Processing Market |
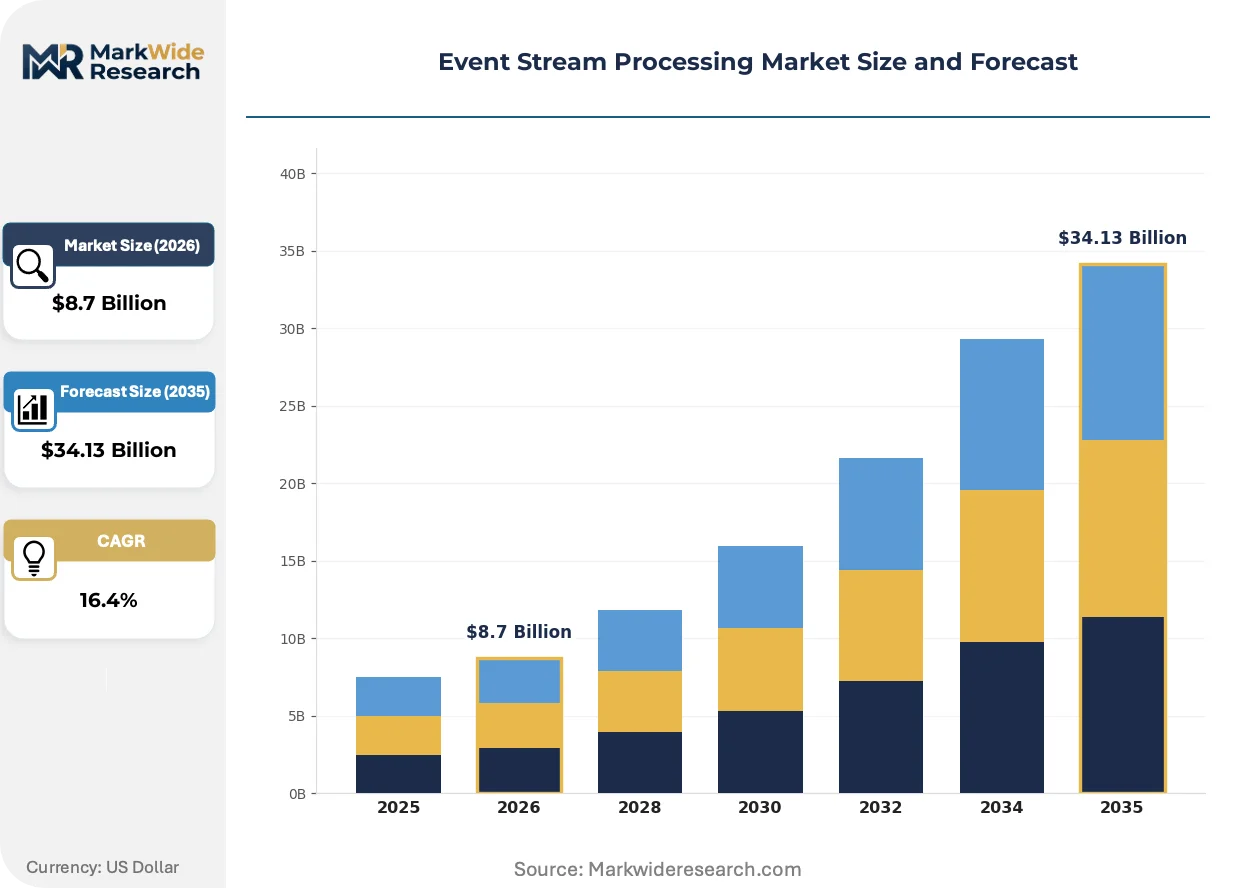
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Services, Platforms, Frameworks Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing End User: Telecommunications, Healthcare, Retail, Financial Services Integration Level: API Integration, Batch Processing, Real-Time Analytics, Others |
| Companies Covered | Amazon Web Services, Microsoft, Confluent, IBM, Google, Aiven, Apache Software Foundation, Estuary, Redpanda Data, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Event Stream Processing Market Emerging Trajectories
Stream-native architectures are displacing bolt-on real-time capabilities, while regulatory pressure on algorithmic transparency and the compression of operational decision windows are reshaping how enterprises evaluate platform investments.
Flink SQL and materialized views are collapsing the boundary between operational databases and stream processing engines, enabling analysts to query continuously updated datasets without separate ETL pipelines. Retail and logistics operators are adopting these capabilities to power live inventory dashboards and dynamic route optimization. The structural consequence is collapsing demand for batch-oriented data warehouses in latency-sensitive applications.
The EU AI Act's risk-based classification system is forcing streaming deployments to incorporate model cards, provenance logging, and human-in-the-loop checkpoints for high-risk automated decisions. Financial services and healthcare providers in Germany, France, and the Netherlands are retrofitting existing pipelines with explainability middleware. This regulatory pressure is accelerating procurement cycles for governance-integrated platforms over pure performance-optimized alternatives.
Consumption-based pricing for managed streaming services is displacing capacity-provisioned contracts as the dominant commercial model. Enterprise buyers in North American technology and media verticals are negotiating spend-commitment structures with automatic scaling triggers rather than fixed cluster sizing. This behavioral shift is most visible among late-majority adopters who prioritize operational expenditure predictability over infrastructure control.
Event Stream Processing Market Segmentation
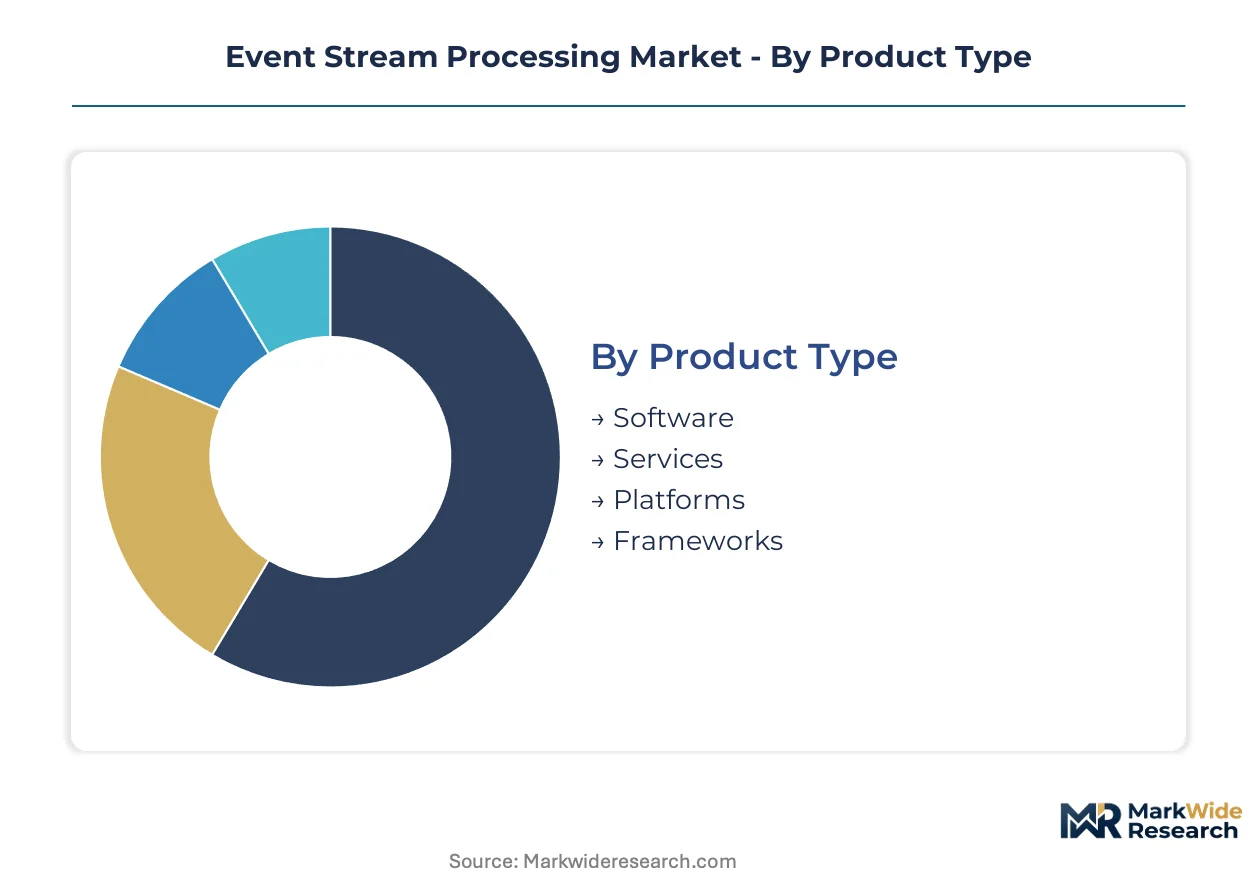
Event stream processing deployments fragment across multiple technical and commercial dimensions. Procurement patterns diverge sharply between latency-sensitive edge configurations and governance-heavy centralized installations.
Product Type:
Software licenses turn over on annual cycles while platform subscriptions refresh monthly, creating divergent cash flow profiles across vendor business models.
- Software:Perpetual and term-licensed codebases deployed on customer-managed infrastructure. German automotive manufacturers favor this model for air-gapped production environments where cloud connectivity remains restricted. Procurement cycles extend to 24-36 months as engineering teams validate latency benchmarks against proprietary hardware configurations.
- Services:Implementation, tuning, and managed operations delivered by specialized integrators. Financial services firms in London and Singapore drive concentrated demand as they retrofit legacy batch architectures for real-time fraud detection pipelines. Talent scarcity extends project timelines and inflates day-rate premiums for Kafka and Flink specialists.
- Platforms:Unified control planes combining ingestion, processing, and observability layers. Retailers operating multi-channel inventory systems select these bundles to collapse vendor management overhead.
- Frameworks:Open-source distributions and commercial support wrappers. Developer-heavy technology companies prefer this route to preserve customization latitude.
Software anchors the volume base while Services gains share at the steepest rate.
Deployment:
Cost tiers stratify sharply between elastic cloud consumption and capital-intensive edge infrastructure buildouts.
- Cloud-Based:Managed streaming services provisioned across AWS, Azure, and GCP regions. North American media and technology verticals dominate consumption, negotiating spend-commitment contracts with automatic scaling triggers. The model sacrifices single-digit latency for operational simplicity.
- Edge Computing:Millisecond-latency processing embedded directly on factory floors, vehicles, and cellular base stations. Japanese precision manufacturers under METI smart factory programs are expanding deployments for predictive maintenance without cloud round-trips. Unit economics remain challenging due to hardware fragmentation.
- Hybrid:Orchestrated workloads spanning on-premises clusters and burst capacity to public cloud. European banks favor this architecture to satisfy GDPR data residency requirements while accessing elastic compute for peak trading windows.
- On-Premise:Self-managed clusters in enterprise data centers. Government and defense contractors maintain this stance for classified workloads.
Cloud-Based carries the deepest revenue concentration while Edge Computing climbs the fastest.
End User:
Application intensity varies dramatically across transaction velocity and regulatory exposure.
- Financial Services:Real-time fraud detection, algorithmic trading, and compliance monitoring at transaction throughputs exceeding millions per second. EU AI Act transparency mandates are forcing upgrades to auditable pipeline architectures across Frankfurt, Paris, and Amsterdam operations centers.
- Telecommunications:Network function virtualization and customer experience optimization. 5G core deployments in South Korea and Finland are embedding stream processing for dynamic bandwidth allocation.
- Healthcare:Patient monitoring and operational analytics. HIPAA constraints limit cloud routing of protected health information, compressing addressable pipeline configurations.
- Retail:Live inventory tracking and dynamic pricing. Omnichannel operators in urban corridors deploy these capabilities to synchronize fulfillment across warehouses and storefronts.
Financial Services commands the premium tier while Telecommunications expands most quickly.
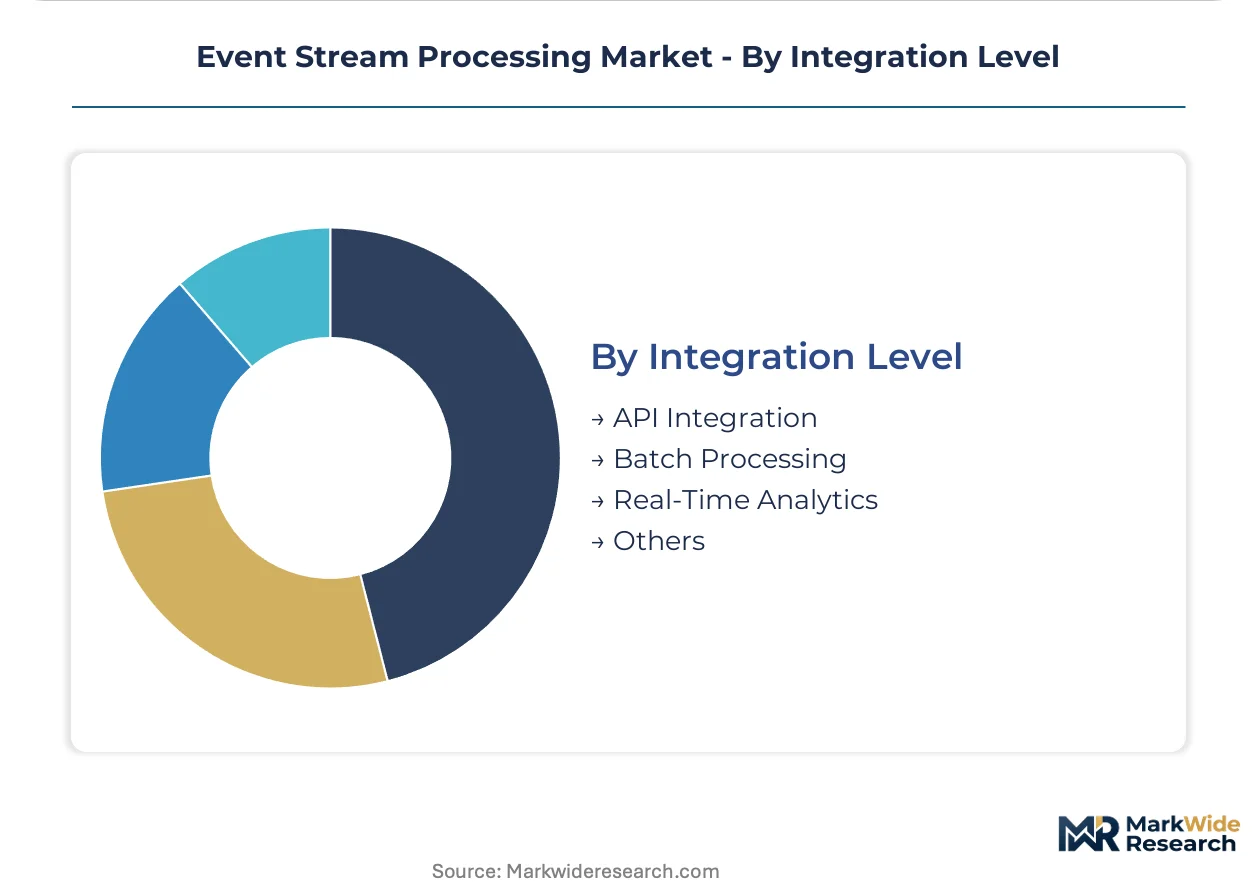
Integration Level:
Customer technical maturity determines whether deployments emphasize plug-and-play connectivity or custom architectural engineering.
- Real-Time Analytics:Continuous query execution against streaming datasets with sub-second refresh intervals. Logistics operators in Rotterdam and Hamburg deploy these capabilities for dynamic route optimization against port congestion and weather disruptions.
- API Integration:Pre-built connectors to enterprise applications and third-party data sources. Mid-market adopters lacking specialized engineering staff gravitate toward this reduced-friction entry point.
- Batch Processing:Periodic synchronization with legacy data warehouse environments. Organizations in transitional migration states maintain this hybrid pattern.
- Others:Custom integration patterns including event sourcing architectures and CQRS implementations. Specialist consultancies dominate this长尾 segment.
Real-Time Analytics anchors current deployment value while API Integration attracts the broadest new-customer inflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity for millisecond-latency edge configurations, while North American media firms negotiate aggressive cloud consumption discounts. European financial services accept premium pricing for GDPR-compliant audit architectures. Healthcare providers in the United States face rigid budget ceilings under HIPAA operational constraints.
Germany
Automotive manufacturers in Stuttgart and Munich drive demand for air-gapped production-line stream processing. The EU AI Act mandates explainability layers for automated quality-control decisions. Bavarian precision engineering clusters are retrofitting existing pipelines with immutable audit trails to satisfy risk-based classification requirements.
United States
Technology and media verticals in Seattle and San Francisco dominate managed service consumption through spend-commitment contracts. HIPAA constrains real-time patient data architectures for healthcare operators in Boston and New York. Financial services firms in Chicago and Charlotte expand fraud detection deployments with sub-second pattern recognition.
Japan
METI smart factory programs accelerate edge-streaming procurement among Nagoya-area precision manufacturers. The country's national industrial standards body conditions market access through information security management certifications. Osaka-based electronics assemblers embed predictive maintenance analytics directly onto production equipment.
United Kingdom
London financial services drive concentrated demand for hybrid architectures satisfying GDPR data residency. The Financial Conduct Authority's operational resilience requirements shape procurement criteria for real-time trading infrastructure. Manchester and Edinburgh technology clusters are expanding managed service partnerships for elastic compute burst capacity.
South Korea
Seoul telecommunications operators embed stream processing within 5G core deployments for dynamic bandwidth allocation. The national radio research agency regulates network function virtualization standards. Busan smart port initiatives deploy continuous analytics for container routing optimization against congestion patterns.
Event Stream Processing Market Vendor Landscape
Capability concentration sits with specialized streaming infrastructure vendors; scale advantage sits with hyperscale cloud operators. The market structures around three tiers: managed service platforms with elastic consumption economics, open-source commercialization specialists controlling distribution layers, and enterprise integrators bundling implementation expertise. Strategic moves center on consumption-based pricing displacement of perpetual licenses and ISO 27001 certification acquisition for regulated industry access.
Within the open-source commercialization tier, Confluent and Redpanda Data occupy positions anchoring Apache Kafka ecosystem control. Among hyperscale operators, Amazon Web Services exemplifies infrastructure-scale delivery dominance. Microsoft sits within the enterprise productivity integration vector, leveraging analytics suite bundling for adoption lock-in. These three archetypes represent the primary competitive vectors reshaping procurement patterns across financial services and industrial verticals.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Confluent |
| IBM |
| Aiven |
| Apache Software Foundation |
| Estuary |
| Redpanda Data |
| Others |
Supply Flow & Price Mechanics
Frankfurt-to-Amsterdam fiber corridors carry latency-sensitive traffic that compresses pricing power for edge-deployed stream processing hardware while amplifying premiums for managed service bundles. This logistics-cost asymmetry between physical infrastructure and cloud abstraction layers concentrates margin capture among hyperscale operators who amortize fiber investments across multi-tenant consumption pools.
Pricing Analysis
Managed operations contracts and consumption-based platform subscriptions now drive lifetime value capture beyond initial software licensing. Three-tier pricing structure across premium, standard, and economy levels segments buyers by latency requirements and audit complexity, with financial services firms accepting premium tiers for EU AI Act compliance while mid-market retailers negotiate standard tiers with capped burst allowances. Cost compression in standard-tier cloud streaming reflects hyperscale capacity additions across AWS, Azure, and GCP regions. Healthcare providers under HIPAA operational constraints exhibit highest price sensitivity due to rigid budget ceilings, whereas German automotive manufacturers demonstrate lowest elasticity for air-gapped edge configurations.
Supply Chain Analysis
Upstream semiconductor fabrication for low-latency networking silicon centers on Taiwan, South Korea, and the United States, with advanced node production concentrated among TSMC and Samsung foundries. Apache Kafka and Apache Flink distributions draw from open-source committer communities anchored in California, Germany, and India, while proprietary platform development rests on captive engineering centers in Seattle, Redmond, and Mountain View. Single-source vulnerability in specialized FPGA acceleration chips for sub-millisecond edge processing threatens deployment timelines for precision manufacturers. Distribution runs through direct enterprise sales for platform contracts and specialized systems integrators for hybrid architecture deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
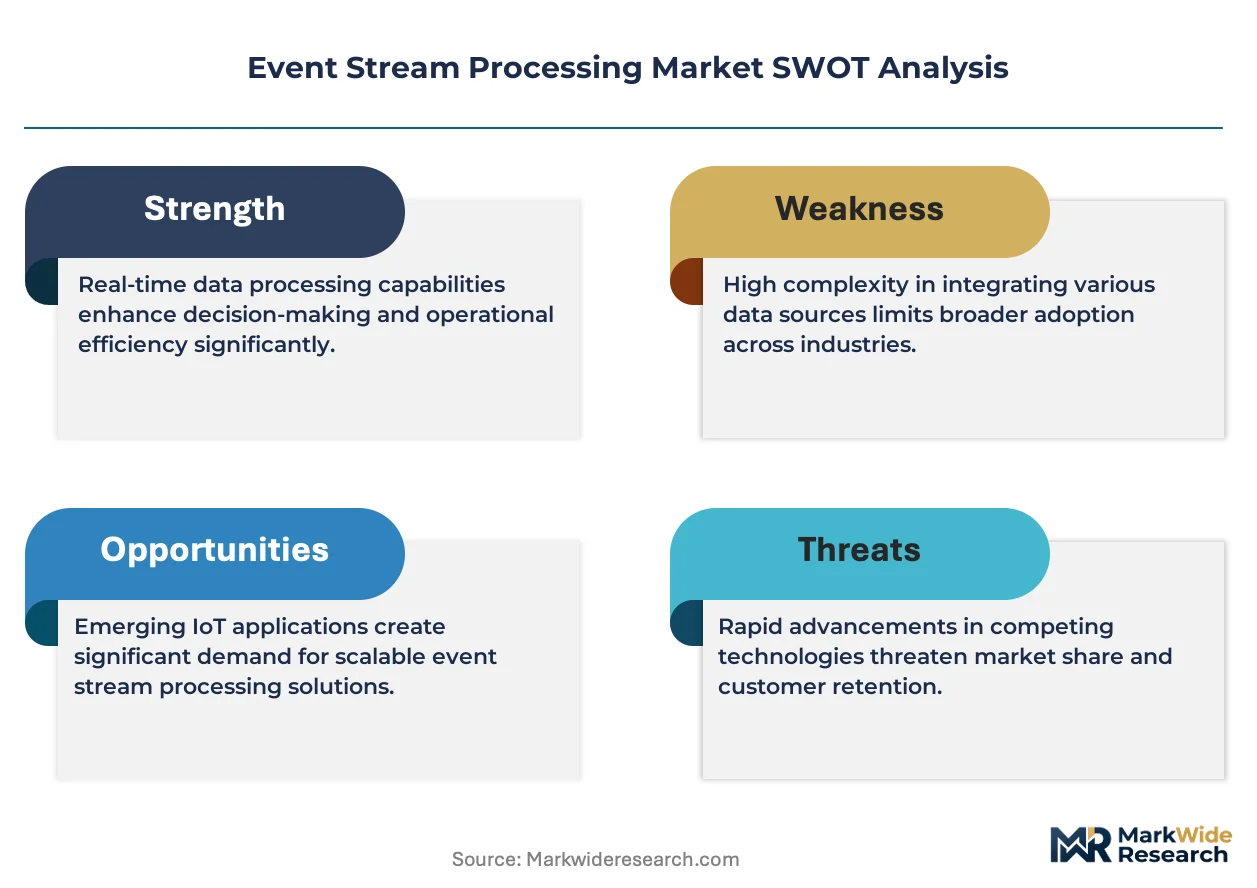
Event stream processing functions as a service-attach market where managed operations and consumption-based platform subscriptions expand faster than perpetual software licenses, rewarding vendors who embed recurring revenue layers into initial deployments.
For Market Incumbents: Build switching-cost moats through deep integration with enterprise productivity suites and analytics platforms. Defensive priorities center on ISO 27001 certification acquisition for regulated industry access and Kafka distribution layer control through committer influence and commercial support bundling. Threats from Redpanda Data and Aiven compress margins in open-source commercialization tiers, demanding differentiated governance-integrated platform positioning.
For New Entrants and Emerging Players: Establish a beachhead in Japanese precision manufacturing under METI smart factory programs where incumbent vendor relationships remain limited. White-space targets include edge-streaming solutions for predictive maintenance in Nagoya-area automotive clusters and Flink SQL materialized view deployments for mid-market retailers lacking specialized engineering staff. Go-to-market leverage rests on channel partnerships with regional systems integrators fluent in hybrid cloud-edge architectures.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial automation conglomerates divesting non-core streaming analytics units to focus on hardware manufacturing. Long-term viability frames around 5-10 year regulatory tailwinds from EU AI Act transparency mandates and GDPR audit requirements sustaining demand for governance-integrated platforms. Signal to monitor: procurement cycle acceleration among German automotive manufacturers retrofitting existing pipelines with explainability middleware.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep embedding with Microsoft analytics suites locks in enterprise productivity workflows. |
| Acquisition of Specialist Firm | Kafka operational expertise gaps favor targeted purchases of Flink tuning consultancies. |
| Geographic Expansion | Edge computing deployments in Stuttgart automotive clusters capture EU AI Act compliance premiums. |
| Strategic Partnership | Channel alliances with London financial services integrators accelerate hybrid architecture adoption. |
| Product Launch | Flink SQL materialized view offerings collapse ETL pipeline demand for Rotterdam logistics operators. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and open-source foundation governance records to establish vendor positioning and technology adoption trajectories. Primary interviews engaged platform engineering directors at financial services firms in Frankfurt and London, IT procurement officers at German automotive manufacturers, and integration specialists at Singapore-based systems integrators. Bottom-up deployment sizing across cloud, edge, and hybrid configurations was triangulated against top-down market aggregation from vendor revenue disclosures and channel partner capacity estimates.
Forecast inputs span deployment model, organization size, vertical application intensity, integration complexity tier, and regional regulatory cluster across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic elasticity assumptions for technology capital expenditure. Industry-specific inputs include EU AI Act implementation timelines affecting European financial services procurement cycles and METI smart factory program funding allocations driving Japanese edge computing adoption.
Stress conditions across interest rate sensitivity for cloud consumption commitments, talent scarcity constraints on deployment velocity, and regulatory enforcement variance for GDPR and HIPAA were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding open-source commercialization dynamics and hyperscale pricing discipline. Cross-checking against vendor-specific earnings call commentary on platform subscription growth rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Crowd Analytics Market
Analytics
FMCG Spending on Analytics Market
Analytics
Statistical Analytics Market
Analytics
Edge Analytics Market
Analytics
App Analytics Market
Analytics
Web Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Global Graph Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Audio and Video Analytics Software Market
Analytics
Marketing Mix Optimization Market
Analytics
Data Analytics Market
Analytics
Automated Analytics Market
Analytics
Data Wrangling Market
Analytics
Data Discovery Market
Analytics
North America HR Analytics Market