
 APAC Location Analytics Market | 2026-2036
APAC Location Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Location Analytics Market Outlook
Multi-source data partnerships is pivoting as the dominant sourcing pattern across APAC location analytics procurement. Esri leverages its established geospatial software ecosystem to sustain enterprise loyalty across Australian government accounts. Google anchors cloud-native mapping services for retail optimization clients seeking real-time consumer movement intelligence. HERE Technologies competes through proprietary HD mapping assets that dominate automotive and logistics use cases in Japan and South Korea.
Location analytics encompasses the processing, visualization, and predictive modeling of geospatial data to derive operational intelligence from positional information, typically integrating GPS coordinates, IoT sensor streams, and satellite imagery through machine learning pipelines. The technology serves commercial and governmental purposes ranging from fleet routing optimization to urban density planning and disaster response coordination. Geospatial analytics solutions currently command the largest solution footprint, while cloud-based deployments represent the fastest-expanding delivery mode as municipal buyers in Indonesia and Vietnam shift from capital-intensive on-premises infrastructure. Machine Learning integration within location platforms is where margin pools concentrate, given the premium pricing attached to predictive spatial modeling versus basic mapping visualization.
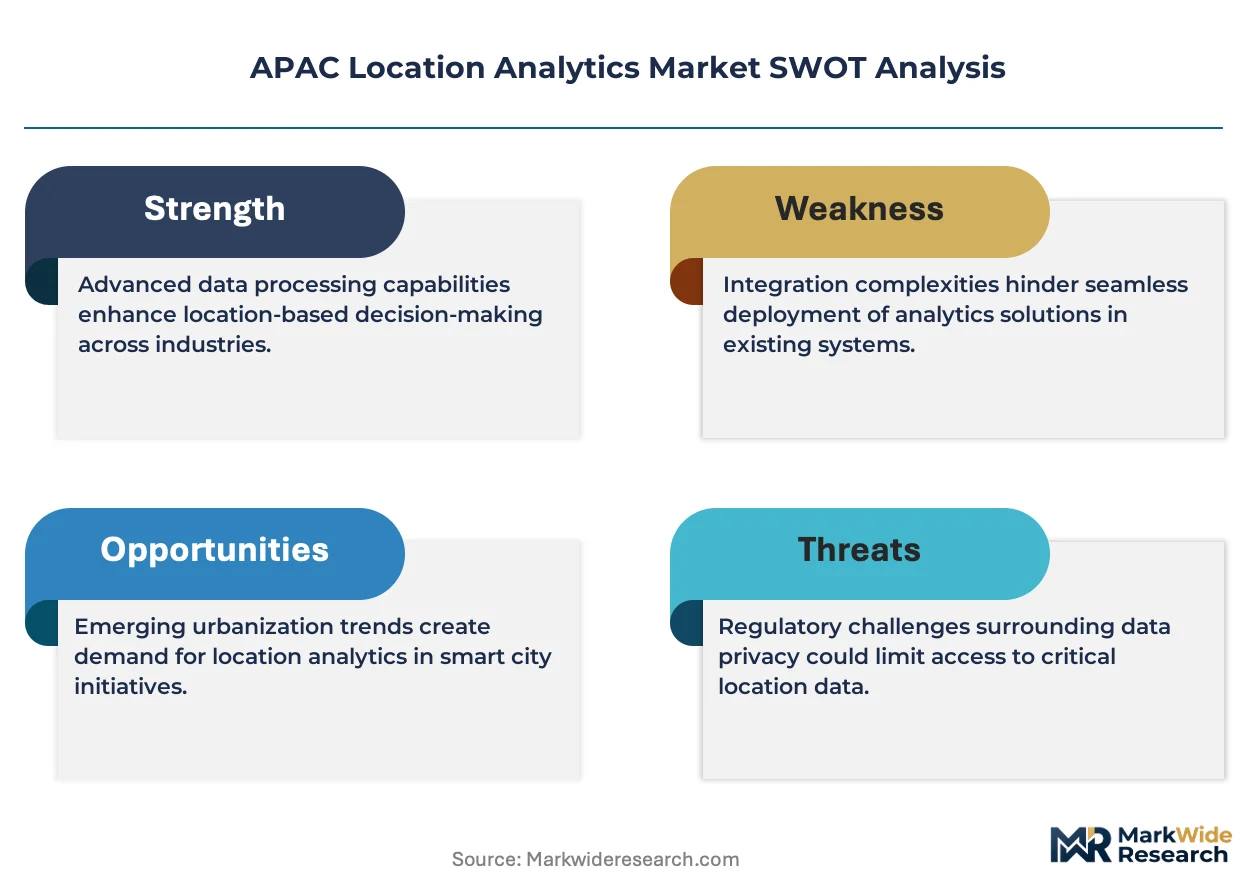
China's MIIT enforces GB standards for geospatial data security that restrict cross-border data flows and mandate domestic cloud hosting for sensitive location datasets. India's BIS certification requirements for surveying equipment and the TRAI framework for telecom-derived location data collectively shape product compliance costs and market access timelines for foreign platform vendors. Japan's METI promotes IoT and smart city standards that accelerate interoperability expectations across municipal procurement. Stakeholders must monitor how divergent data localization regimes across these jurisdictions affect architecture decisions for regional platform rollouts.
Market Dynamics
Municipal procurement criteria across Southeast Asia are accelerating platform deployments as smart city mandates hardwire geospatial intelligence into urban infrastructure planning. China's MIIT data localization rules and India's BIS certification requirements are forcing foreign vendors to re-architect regional delivery models around domestic cloud hosting and equipment standards.
Growth Catalysts
- Smart city mandates:India's Smart Cities Mission and China's dual carbon goals are embedding location analytics into municipal master planning. Urban density modeling now drives procurement decisions for geospatial infrastructure across metropolitan clusters.
- Automotive HD mapping demand:Autonomous vehicle development in Japan and South Korea is consuming proprietary high-definition map datasets. Logistics fleet optimization is expanding the addressable base beyond passenger mobility.
- IoT sensor proliferation:Real-time positional streams from connected devices are enriching predictive spatial models. Machine learning pipelines now ingest GPS coordinates alongside satellite imagery for operational intelligence.
Market Restraints
- Cross-border data friction:China's GB standards restrict geospatial data flows and mandate domestic hosting for sensitive location datasets. Foreign platform vendors face extended compliance timelines and architecture redesign costs.
- Input cost concentration:Cloud compute and specialized surveying equipment supply concentrates among limited vendor pools. BIS certification requirements for Indian surveying equipment add procurement friction and extend deployment cycles.
- Technical interoperability gaps:Divergent smart city standards across Indonesia, Vietnam, and Thailand fragment platform integration. Municipal buyers struggle to unify legacy on-premises systems with cloud-native deployments.
Strategic Opportunities
- Underpenetrated Indonesian and Vietnamese metros:Municipal buyers in these markets are shifting from capital-intensive on-premises infrastructure to cloud-based delivery. First-mover platform vendors can anchor long-term subscription relationships.
- Machine learning premium pricing:Predictive spatial modeling commands margin pools above basic mapping visualization. Vendors with proprietary ML pipelines can differentiate pricing tiers around forecasting accuracy.
- METI IoT standard alignment:Japan's interoperability promotion creates pathway for regional platform rollouts. Vendors certifying against METI frameworks gain procurement preference across adjacent East Asian markets.
Industry Challenges
- Geospatial data science talent scarcity:Machine learning engineers with spatial statistics expertise remain concentrated in China and India. Platform vendors face recruitment competition from automotive and logistics end-users.
- Legacy system integration complexity:Municipal IT departments in Southeast Asia maintain decades-old cadastral databases. Cloud-native location platforms require expensive middleware development for data harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Location Analytics Market |
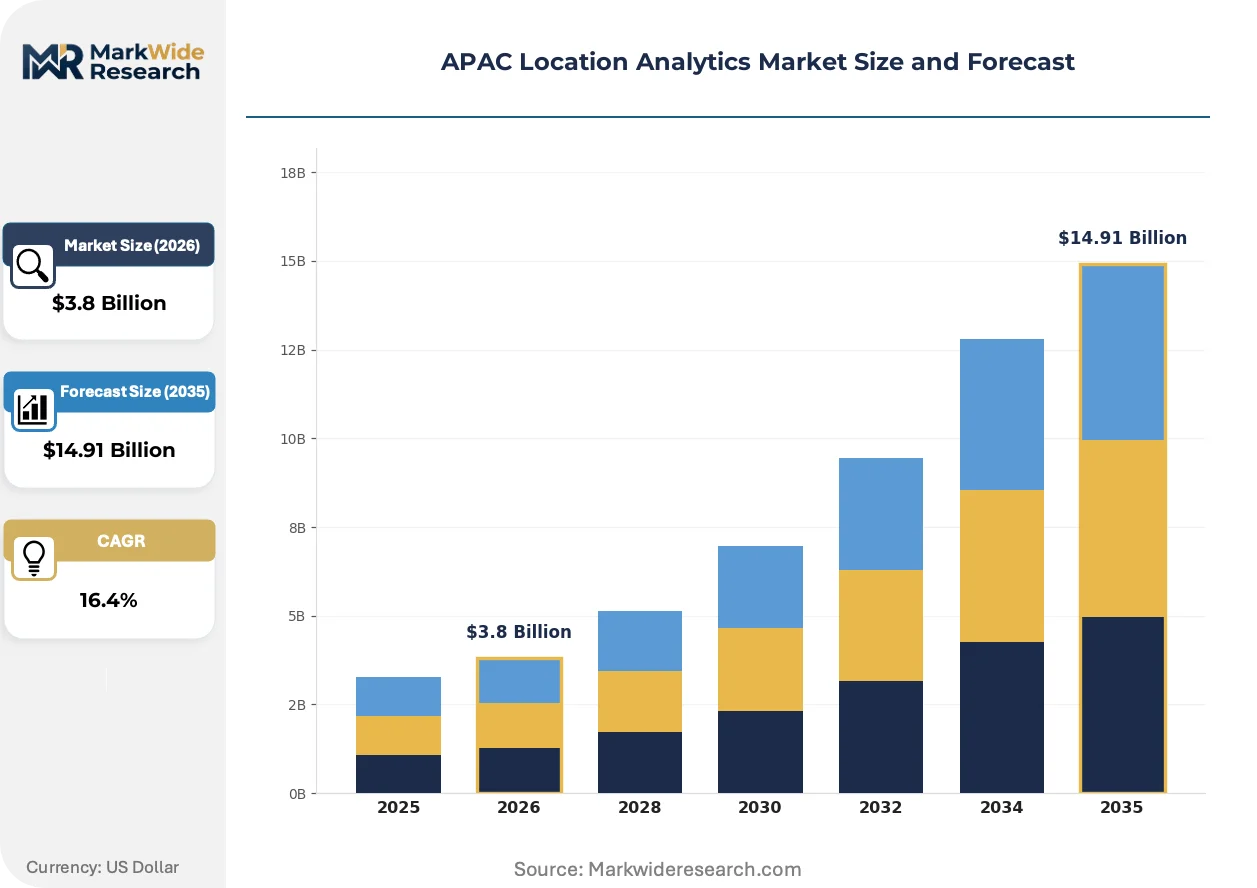
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Retail Optimization, Smart City Planning, Supply Chain Management, Fleet Tracking Technology: Geospatial Analytics, GPS, IoT, Machine Learning End User: Government Agencies, Transportation, Enterprises, Logistics Firms Solution: Cloud-Based, On-Premises, Hybrid, Open Source |
| Companies Covered | Esri, Google, Microsoft, Oracle, SAS Institute, HERE Technologies, Cisco Systems, IBM, SAP SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Location Analytics Market Strategic Shifts
Machine learning is compressing the value chain between raw geospatial data capture and predictive intelligence delivery. Platform architecture decisions now pivot on whether vendors own ML training pipelines or license them from specialized providers.
Edge computing hardware is integrating directly with location analytics platforms to process IoT sensor streams at reduced latency. Smart city operators in Vietnam and Indonesia are deploying these configurations to enable real-time traffic flow optimization without backhauling raw data to centralized clouds. The structural consequence is that margin pools are shifting toward hardware-software bundled offerings that vendors with captive edge device supply can capture.
China's MIIT enforcement of GB standards for geospatial data security is fragmenting regional platform architectures. Domestic cloud hosting mandates for sensitive location datasets are forcing foreign vendors to establish separate China-specific instances. Automotive and logistics segments with cross-border operations face the steepest compliance burden as they maintain parallel data sovereignty configurations.
Municipal procurement patterns are consolidating around multi-source data partnerships rather than single-vendor geospatial platforms. Australian government accounts now require interoperability between established geospatial software ecosystems and emerging cloud-native mapping services. The shift is most visible in retail optimization use cases where real-time consumer movement intelligence demands API-first platform selection criteria.
APAC Location Analytics Market Segmentation
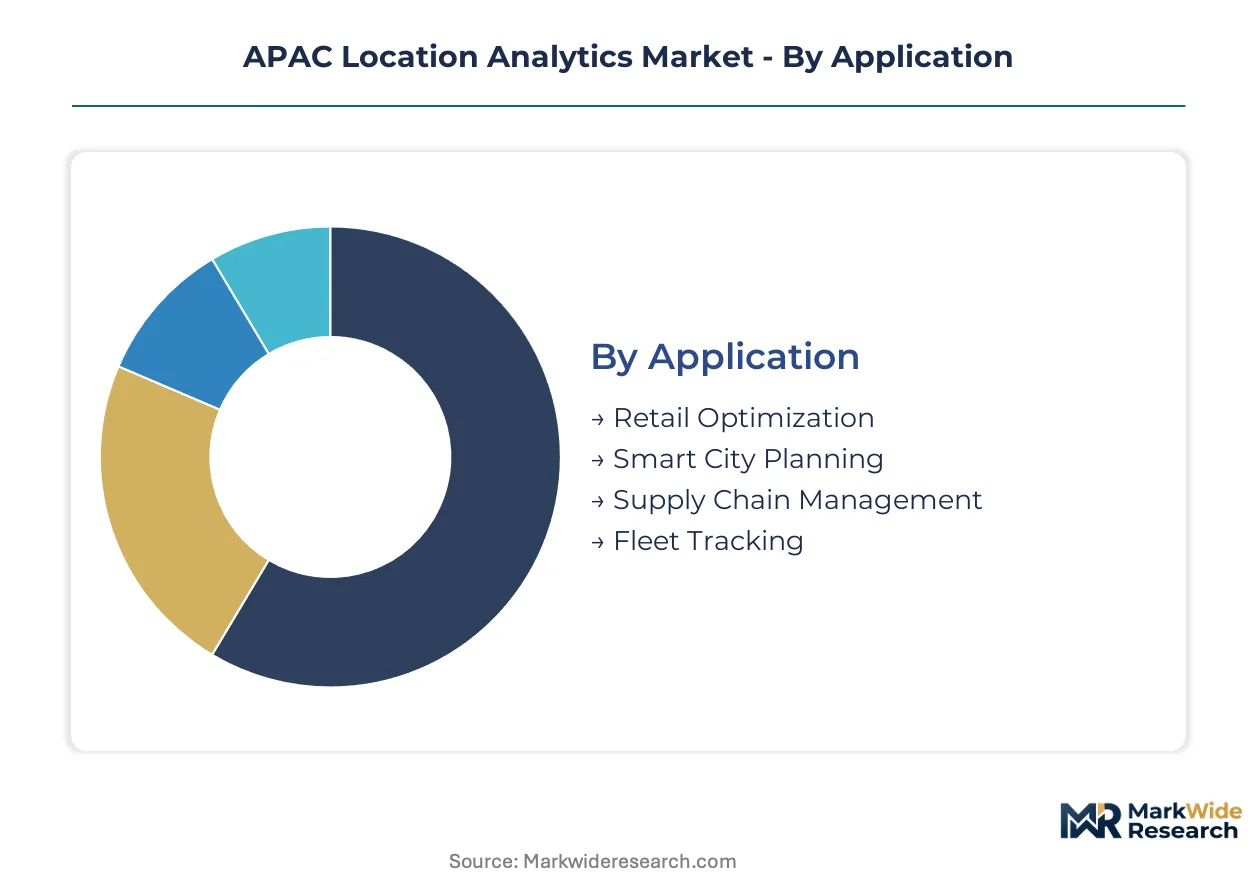
Segmentation in APAC location analytics reveals how procurement priorities diverge across municipal, commercial, and logistics buyers. Each dimension exposes distinct technical requirements and compliance constraints that reshape vendor positioning across the region.
Application:
Retail buyers prioritize real-time consumer movement intelligence while government agencies anchor procurement around urban density modeling capabilities.
- Retail Optimization:Real-time foot traffic analysis and consumer journey mapping drive platform selection. Australian retail chains and Singaporean mall operators are consolidating spend around API-first solutions that ingest mobile location signals for merchandising decisions.
- Smart City Planning:Urban density modeling and disaster response coordination define functional requirements. India's Smart Cities Mission and China's Yangtze River Delta cluster are embedding geospatial intelligence into master planning procurement.
- Supply Chain Management:Warehouse location optimization and route efficiency modeling serve manufacturing hubs.
- Fleet Tracking:Real-time vehicle positioning and driver behavior analytics address logistics compliance needs.
Volume sits with Smart City Planning; growth tilts toward Retail Optimization.
Technology:
Technology selection separates buyers seeking predictive intelligence from those requiring basic spatial visualization.
- Geospatial Analytics:Spatial data processing and visualization platforms currently command the largest solution footprint. Municipal buyers in Indonesia and Vietnam rely on these systems for cadastral mapping and infrastructure planning.
- Machine Learning:Predictive spatial modeling pipelines command premium pricing tiers above basic mapping tools. ML integration concentrates margin pools as vendors differentiate around forecasting accuracy for traffic flow and consumer movement.
- GPS:Satellite-based positioning provides foundational location data for fleet and asset tracking.
- IoT:Connected sensor streams enable real-time positional intelligence at reduced latency.
Geospatial Analytics dominates current deployments; Machine Learning is climbing the fastest.
End User:
End user type determines compliance burden and integration complexity for platform vendors.
- Government Agencies:Municipal procurement mandates require domestic cloud hosting and BIS-certified surveying equipment. India's urban corridors and China's metros are reshaping vendor architectures around data localization rules.
- Transportation:Autonomous vehicle developers in Japan and South Korea consume proprietary HD map datasets. METI interoperability standards accelerate procurement expectations across adjacent East Asian markets.
- Enterprises:Retail and manufacturing buyers prioritize cloud-native delivery and API accessibility.
- Logistics Firms:Fleet operators demand real-time routing optimization with cross-border data sovereignty configurations.
Government Agencies anchor procurement volume; Transportation is gaining share fastest.
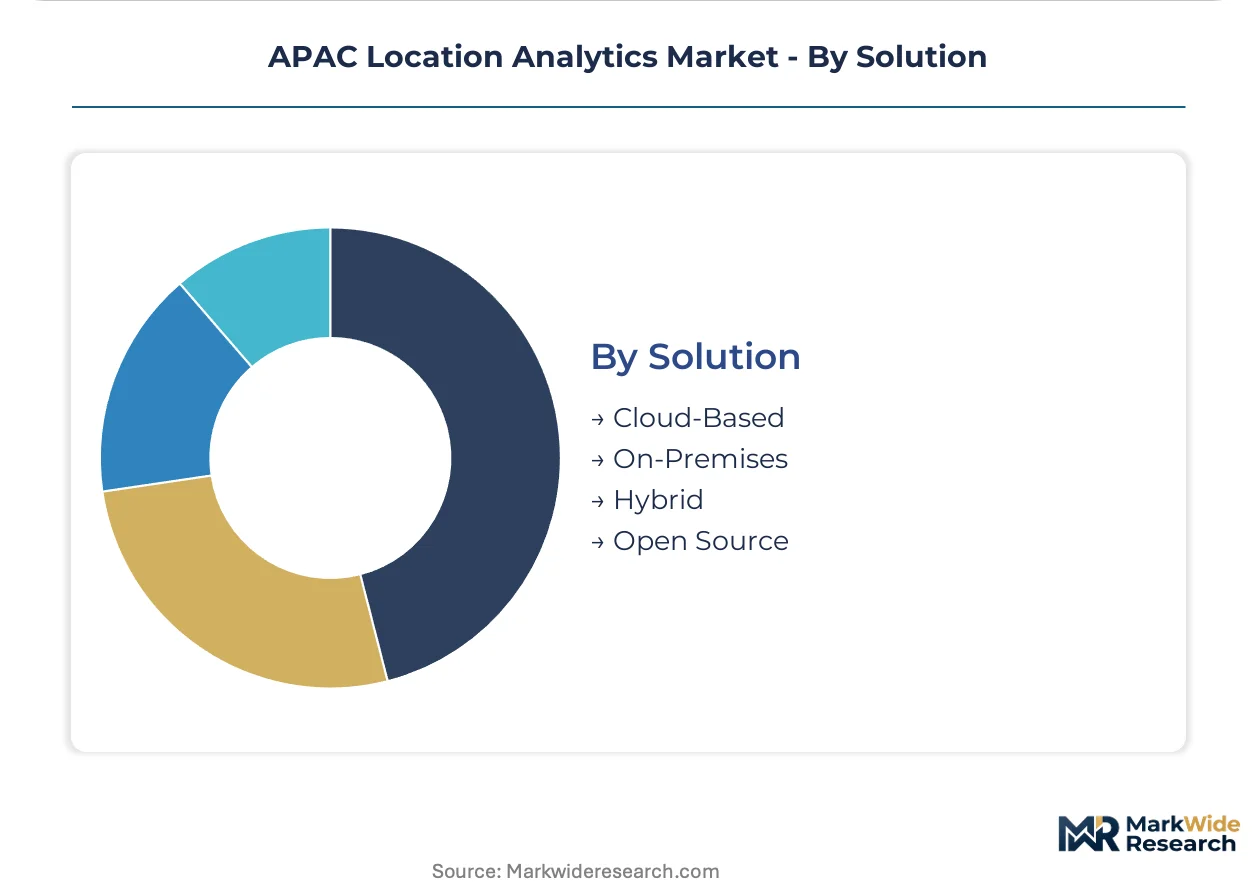
Solution:
Delivery mode selection reflects capital availability and data sensitivity trade-offs across buyer segments.
- Cloud-Based:Subscription delivery eliminates capital-intensive infrastructure investments. Municipal buyers in Indonesia and Vietnam are shifting from on-premises systems to cloud-native deployments for traffic management and urban planning.
- Hybrid:Mixed architectures balance sensitive data on-premises with scalable cloud analytics. China's MIIT domestic hosting mandates for geospatial datasets force foreign vendors toward hybrid configurations.
- On-Premises:Legacy installations persist where data sovereignty requirements prohibit external hosting.
- Open Source:Cost-constrained buyers in emerging metros adopt community-supported platforms with limited vendor support.
On-Premises retains legacy installed base; Cloud-Based shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geospatial data reserves and satellite ground station infrastructure anchor regional supply chains across the Asia-Pacific. MIIT data localization mandates and BIS certification requirements reshape vendor deployment architectures from Mumbai to Shanghai.
China
Autonomous vehicle development and smart city densification drive platform consumption. MIIT enforces GB standards restricting cross-border geospatial flows and mandating domestic cloud hosting. The Yangtze River Delta cluster embeds location analytics into municipal master planning for carbon neutrality tracking.
India
Urban corridor expansion and logistics fleet modernization accelerate procurement. BIS certification requirements for surveying equipment and TRAI frameworks for telecom-derived location data extend vendor compliance timelines. The Delhi-Mumbai Industrial Corridor anchors geospatial infrastructure deployment for freight optimization.
Japan
HD mapping for automotive autonomy and METI-promoted IoT interoperability standards concentrate demand. METI smart city frameworks accelerate procurement expectations across municipal buyers. The Kanto region around Tokyo dominates predictive spatial modeling deployments for disaster response coordination.
South Korea
Connected vehicle ecosystems and logistics automation reshape platform requirements. National geospatial data policies emphasize domestic processing for sensitive location datasets. The Seoul Capital Area concentrates real-time traffic flow optimization deployments leveraging edge-integrated sensor networks.
Australia
Government accounts sustain enterprise loyalty through multi-source data partnership mandates. Federal procurement criteria require interoperability between established geospatial software ecosystems and cloud-native mapping services. Sydney and Melbourne anchor retail optimization deployments consuming real-time consumer movement intelligence.
APAC Location Analytics Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors re-architect delivery models around data sovereignty requirements. The vendor base separates into three tiers: established geospatial software ecosystems, cloud-native mapping service providers, and specialized HD mapping asset holders. Two archetypes command distinct positioning: legacy platform vendors defending installed base relationships, and cloud-native entrants capturing municipal buyers shifting from on-premises infrastructure. Competitive moves concentrate on M&A for ML pipeline capabilities and geographic expansion through domestic cloud hosting partnerships.
Within the established geospatial tier, Esri exemplifies platform vendors sustaining government account loyalty through multi-decade deployment relationships. Google and Microsoft occupy positions as cloud-native anchors for retail optimization clients seeking API-first consumer movement intelligence. HERE Technologies represents the specialized mapping archetype, with proprietary HD datasets dominating automotive and logistics use cases in Japan and South Korea.
| Leading Market Players |
|---|
| Esri |
| Microsoft |
| Oracle |
| SAS Institute |
| HERE Technologies |
| Cisco Systems |
| IBM |
| SAP SE |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals gate qualified supply for geospatial infrastructure vendors and restrict premium-tier pricing access to platforms demonstrating carbon-neutral cloud hosting certifications. MIIT domestic hosting mandates compound this filtering effect by disqualifying foreign architectures that cannot demonstrate localized data sovereignty compliance.
Pricing Analysis
Warranty and service bundling separates premium subscriptions from unbundled entry tiers in APAC location analytics procurement. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by ML pipeline depth and BIS certification status for surveying equipment. Cost compression in standard tiers intensifies because Indonesian and Vietnamese municipal buyers prioritize cloud-native delivery over capital-intensive on-premises alternatives. Government agencies exhibit lowest price sensitivity given compliance-driven procurement mandates, while logistics firms face acute margin pressure from cross-border data sovereignty configuration costs.
Supply Chain Analysis
Cloud compute capacity rests on concentrated hyperscaler infrastructure across China, Singapore, and Australia. Specialized surveying equipment feeds from Japanese and South Korean precision manufacturing bases, while HD mapping datasets draw from proprietary automotive sensor networks. Single-source vulnerability concentrates in domestic cloud hosting partnerships required by MIIT and BIS frameworks. Distribution runs through systems integrators with established government procurement relationships rather than direct vendor-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC location analytics operates as a supply-constrained market where geospatial data science talent scarcity props pricing for predictive spatial modeling capabilities above basic visualization tiers.
For Market Incumbents: Deepen vertical integration into edge computing hardware to capture margin pools shifting toward bundled software-software offerings. Anchor government account loyalty through multi-decade deployment relationships while defending against cloud-native entrants by accelerating METI interoperability certification. Capacity addition in Indonesia and Vietnam secures first-mover subscription relationships as municipal buyers abandon on-premises infrastructure.
For New Entrants and Emerging Players: Domestic cloud hosting partners provide the fastest pathway to MIIT and BIS compliance without full architectural rebuild. White-space targets concentrate in Indonesian and Vietnamese metros shifting from capital-intensive on-premises systems, plus retail optimization use cases demanding API-first consumer movement intelligence. Position around machine learning premium pricing by demonstrating forecasting accuracy for traffic flow and urban density modeling.
For Investors and Strategic Acquirers: METI IoT standard certification announcements are the leading indicator that procurement preference is consolidating around interoperability-aligned vendors. The five-to-ten year viability window favors acquisition targets with proprietary HD mapping datasets and established domestic cloud hosting partnerships. Monitor BIS certification timeline extensions as signals of vendor compliance burden and market access friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cloud Hosting Partnership | MIIT GB standards compliance unlocks China municipal procurement access. |
| Machine Learning Pipeline Acquisition | Predictive spatial modeling capabilities command premium pricing tiers. |
| METI IoT Standard Certification | Interoperability alignment accelerates procurement preference across East Asia. |
| Edge Computing Hardware Integration | Real-time sensor processing captures margin pools in Vietnam and Indonesia. |
| BIS Certification Investment | Surveying equipment compliance extends vendor access across Indian urban corridors. |
Study Parameters
Trade publications, regulatory filings from MIIT and BIS, and municipal procurement databases formed the secondary backbone of this analysis. Primary interviews with smart city planning officers, geospatial platform engineers, logistics fleet operators, and government IT procurement managers combined with secondary validation to triangulate market sizing. Bottom-up segmentation modeling across deployment mode, application vertical, and end-user type integrated with top-down macroeconomic trend analysis.
Historical trendline analysis of platform adoption rates and cloud migration patterns anchored the projection framework. Segmentation dimensions modeled include solution delivery mode, application use case, technology type, and regional regulatory cluster. CAGRs were derived through regression analysis of adoption velocity indicators and procurement cycle timing. Forecast inputs incorporated IoT sensor deployment trajectories and smart city mandate implementation schedules.
Caveats apply where MIIT enforcement intensity or BIS certification timeline revisions could materially shift the outlook for foreign vendor market access. Forecasts reflect assumptions around data localization regime stability and municipal budget continuity for geospatial infrastructure investment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Sales Performance Management Market
Analytics
Spain Geospatial Analytics Market
Analytics
Emotion Analytics Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
US Video Analytics Market
Analytics
APAC Operational Intelligence Market
Analytics
Embedded Business Intelligence Market
Analytics
Operational Intelligence Market
Analytics
Document Analytics Market
Analytics
Identity Analytics Market
Analytics
US Predictive Analytics Market
Analytics
Lead Intelligence Software Market
Analytics
North America HR Analytics Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Europe Predictive Analytics Market