
 3D Photogrammetry Software Market | 2026-2036
3D Photogrammetry Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Photogrammetry Software Market Insights
Buyer concentration across the architecture and engineering sector is broadening as mid-sized construction firms and independent surveyors adopt photogrammetry tools previously reserved for large enterprises. Pix4D SA leverages its Swiss R&D base to sustain leadership in drone-based mapping workflows. Agisoft LLC anchors its position through specialized desktop processing that appeals to researchers and cultural heritage specialists with limited cloud connectivity. Hexagon AB competes by extending its sensor-to-software ecosystem across surveying and infrastructure monitoring applications.
3D photogrammetry software reconstructs dense point clouds and textured mesh models from overlapping two-dimensional photographs, typically requiring sub-pixel image matching accuracy and camera calibration parameters to achieve millimeter-grade measurement fidelity. The primary commercial purpose centers on deriving measurable three-dimensional geometry from passive optical capture without active laser or structured-light hardware. Desktop software retains the largest installed base among precision users who demand local processing control over sensitive site data, while cloud-based software captures the fastest expansion as SaaS deployment lowers upfront licensing barriers for smaller surveying practices. Cultural heritage represents a concentrated margin pool where grant-funded institutions prioritize accuracy over speed and accept premium pricing for specialized toolsets.
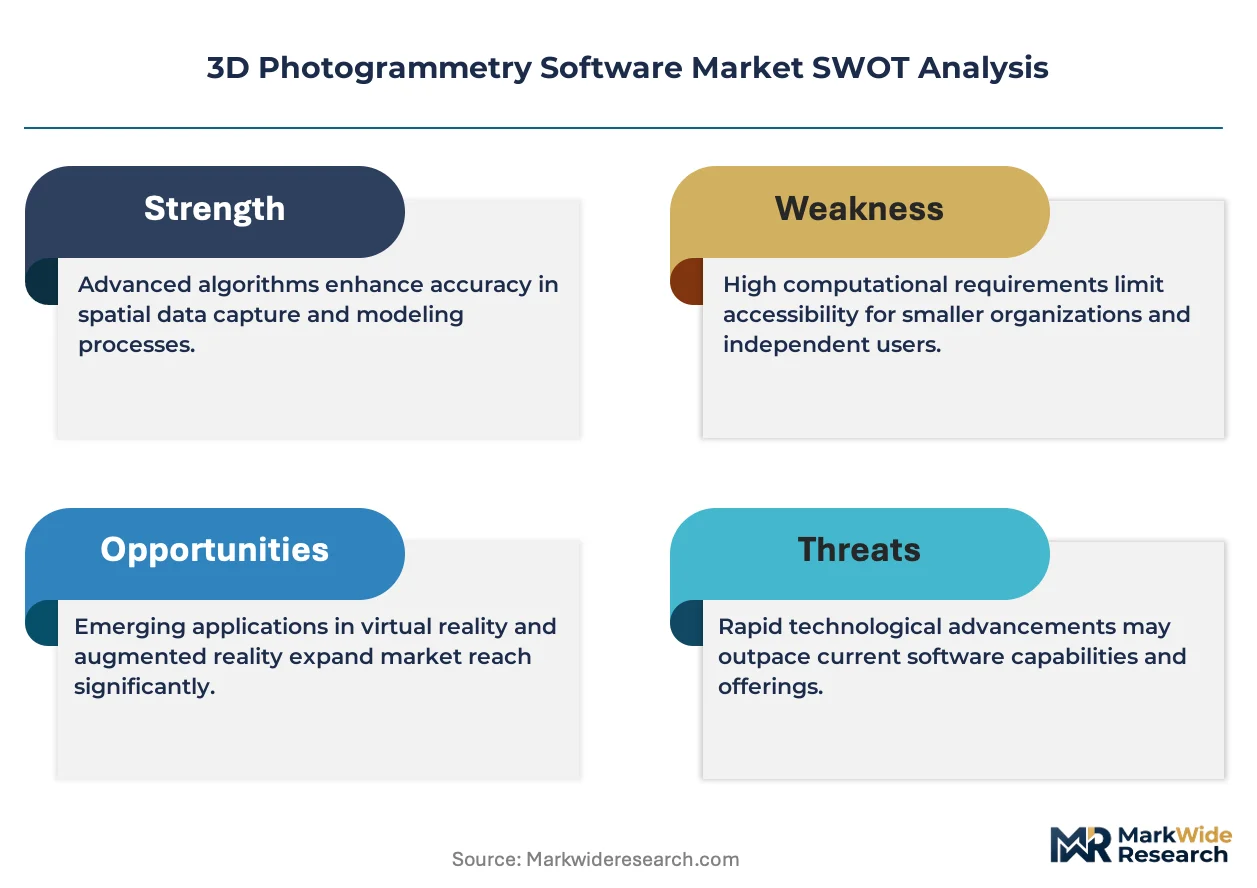
FAA Part 107 regulations in the United States govern commercial drone operations that supply aerial imagery into photogrammetry pipelines, while EASA drone standards across Europe harmonize flight permissions for surveying missions. GDPR constraints on geospatial data storage in the European Union push vendors toward on-premises and hybrid deployment architectures that keep sensitive coordinates within client-controlled infrastructure. Stakeholders must weigh data sovereignty requirements against the scalability of cloud-native processing as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
The EU AI Act is forcing photogrammetry vendors to reengineer cloud-based feature extraction pipelines, creating a structural divergence between compliant European architectures and less-regulated alternatives elsewhere. This regulatory pressure compounds with GDPR data localization mandates to reshape deployment choices across the value chain.
Growth Catalysts
- Construction digitization mandates:Infrastructure ministries in Germany and France now require as-built documentation in BIM-compatible formats, pulling photogrammetry into standard contractor workflows.
- EASA drone harmonization:Standardized flight permissions across 30 European countries reduce operational friction for aerial surveying missions feeding photogrammetry pipelines.
- Lidar cost compression:Falling sensor prices in the $500-2,000 range are expanding hybrid capture workflows that blend photogrammetry with active ranging for vegetation-penetrating surveys.
Market Restraints
- GPU supply concentration:Taiwan-based foundry capacity constraints create 6-12 month lead times for workstation-class processors essential to dense point cloud generation.
- GDPR territoriality:Cross-border transfer restrictions on geospatial coordinates block pure-SaaS models for defense and critical infrastructure clients in the European Union.
- Photogrammetry-lidar substitution:Active scanning systems achieve reliable results in low-light and textureless environments where passive optical methods fail.
Strategic Opportunities
- Heritage digitization grants:Italy's €300 million cultural recovery fund and similar programs in Spain are creating dedicated budget lines for monument documentation using precision photogrammetry.
- AI-photogrammetry convergence:Neural radiance fields and Gaussian splatting techniques are compressing processing times from hours to minutes for real-time inspection applications.
- Mobile edge deployment:Tablet-based processing workflows are penetrating mid-sized surveying practices in Poland and Czechia that previously outsourced computation.
Industry Challenges
- Photogrammetrist skill scarcity:Accurate camera calibration and ground control point placement require specialized training that university programs in geomatics are not producing at sufficient scale.
- Multi-sensor integration complexity:Combining imagery from drones, ground vehicles, and handheld devices into unified coordinate systems demands proprietary middleware that fragments vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Photogrammetry Software Market |
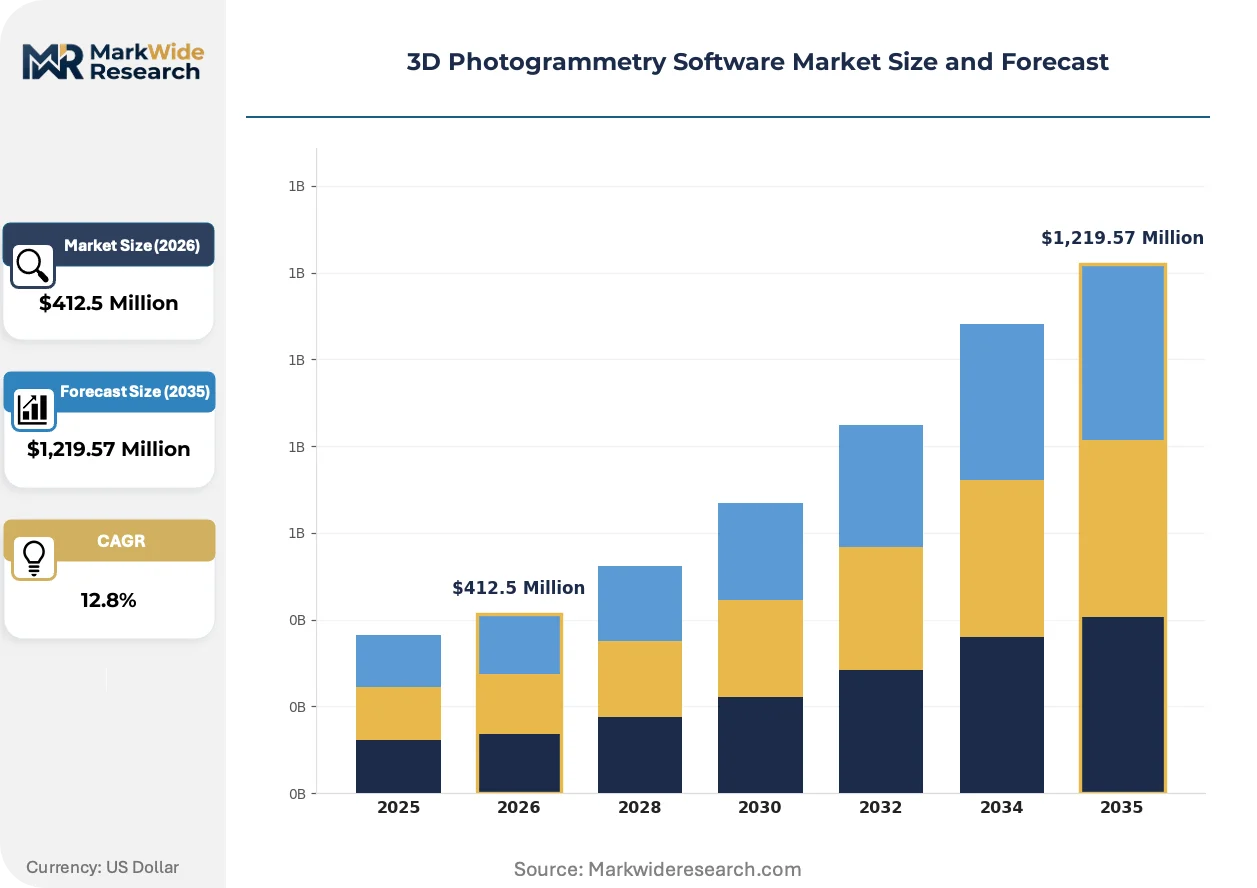
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,219.57 Million |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Mobile Software, Cloud-based Software, Plug-ins Industry Vertical: Construction, Surveying, Agriculture, Cultural Heritage End User: Architects, Surveyors, Engineers, Researchers Deployment: On-premises, SaaS, Hybrid, Enterprise |
| Companies Covered | Pix4D SA, Agisoft LLC, Autodesk Inc., Bentley Systems Inc., PhotoModeler Technologies, DroneDeploy Inc., Hexagon AB, Trimble Inc., RealityCapture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Photogrammetry Software Market Trends and Innovations
Computational photography techniques are absorbing traditional photogrammetry workflows, compressing the boundary between capture hardware and software reconstruction. This convergence is redistributing value from standalone processing licenses toward integrated sensor-software bundles.
Neural radiance fields (NeRF) are absorbing volumetric reconstruction tasks previously handled by multi-view stereo pipelines. Archaeological documentation teams in Greece and Turkey are adopting NeRF-based tools for rapid site recording without dense ground control. The technology is absorbing market share from conventional mesh-generation workflows by eliminating the need for explicit camera calibration in many use cases.
The EU AI Act's risk classification framework is redefining permissible automation in cloud-based feature extraction. High-risk applications including infrastructure safety assessments now require human-in-the-loop validation, extending project timelines by 15-30 percent for affected workflows. German engineering consultancies are responding by maintaining hybrid processing architectures that route sensitive computations through on-premises nodes while using cloud burst capacity for non-critical tasks.
Subscription-based licensing is displacing perpetual purchase models among mid-sized surveying practices in France and the Netherlands. Channel partners are unbundling implementation services from software access fees, creating transparent cost structures that accelerate procurement cycles. This shift is most visible in the Benelux region, where cooperative purchasing consortia negotiate enterprise terms for independent surveyor networks.
3D Photogrammetry Software Market Segmentation
Segmentation in 3D photogrammetry software reveals how processing location, user expertise, and data sensitivity shape purchasing patterns. Vendors calibrate licensing models and feature depth to match the technical sophistication and compliance requirements of distinct buyer clusters.
Product Type:
Customization versus standardization divides this category, with configurable pipelines at one extreme and turnkey workflows at the other.
- Desktop Software:Installs on local workstations with full GPU acceleration for dense point cloud generation. Heritage preservation agencies in Germany and France favor this model to retain custody of sensitive site coordinates under GDPR territoriality rules.
- Cloud-based Software:Processes imagery through distributed server infrastructure with pay-per-project pricing. Mid-sized surveying practices in Poland and Czechia are migrating to this model to eliminate capital expenditure on rendering hardware.
- Mobile Software:Tablet and smartphone applications enabling field-optimized preview and lightweight reconstruction.
- Plug-ins:Extensions integrating photogrammetry capabilities into CAD and BIM platforms.
Leading the category by volume: Desktop Software. Growing fastest: Cloud-based Software.
Industry Vertical:
Margin concentration follows project complexity, with heritage and infrastructure applications commanding premium pricing over commoditized agricultural monitoring.
- Construction:Drives demand for as-built documentation and progress monitoring integrated with BIM workflows. German infrastructure ministries now mandate BIM-compatible deliverables, pulling photogrammetry into standard contractor procurement.
- Cultural Heritage:Grant-funded monument documentation prioritizes sub-millimeter accuracy over processing speed. Italy's €300 million cultural recovery fund and similar Spanish programs are creating dedicated budget lines for precision digitization.
- Surveying:Professional geomatics services requiring cadastral-grade measurement fidelity and legal traceability.
- Agriculture:Crop health monitoring and yield estimation through normalized difference vegetation index extraction from aerial imagery.
Highest margin pool: Cultural Heritage. Expanding most quickly: Construction.
End User:
Technical depth separates buyers who configure camera calibration parameters from those consuming automated reconstruction outputs.
- Surveyors:Licensed geomatics professionals requiring ground control point integration and coordinate system transformation. EASA drone harmonization across 30 European countries reduces operational friction for aerial surveying missions feeding their workflows.
- Engineers:Infrastructure and structural specialists applying photogrammetry to deformation monitoring and safety assessments. EU AI Act risk classifications now mandate human-in-the-loop validation for automated feature extraction in critical infrastructure, extending project timelines.
- Architects:Design professionals leveraging photogrammetry for site context modeling and existing conditions documentation.
- Researchers:Academic and institutional users with limited cloud connectivity prioritizing offline processing and reproducible workflows.
Largest installed base: Surveyors. Steepest adoption curve: Engineers.
Deployment:
Data sovereignty requirements fragment deployment architecture between client-controlled infrastructure and scalable cloud-native platforms.
- On-premises:Complete processing within client-managed data centers or workstations. Defense and critical infrastructure clients in the European Union select this model to satisfy GDPR cross-border transfer restrictions on geospatial coordinates.
- SaaS:Pure cloud delivery with browser-based interfaces and elastic compute scaling. Subscription licensing is displacing perpetual purchase models among mid-sized surveying practices in France and the Netherlands.
- Hybrid:Sensitive computations routed through on-premises nodes with cloud burst capacity for non-critical tasks. German engineering consultancies are responding to EU AI Act compliance pressure by maintaining this architecture.
- Enterprise:Dedicated infrastructure with customized service level agreements and priority support tiers.
Dominant revenue model: On-premises. Gaining share fastest: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for 3D photogrammetry software clusters in Germany, where engineering consultancies and heritage preservation agencies drive precision surveying tool adoption. Construction digitization mandates across European infrastructure ministries are pulling photogrammetry into standard contractor workflows.
Germany
Bavarian engineering clusters and Berlin-Brandenburg heritage agencies anchor European demand for millimeter-grade measurement fidelity. The EU AI Act risk classification framework mandates human-in-the-loop validation for automated infrastructure safety assessments, extending project timelines for cloud-based workflows. Stuttgart-based surveying consortia are deploying hybrid processing architectures to satisfy GDPR territoriality requirements.
France
Île-de-France infrastructure ministries now require BIM-compatible as-built documentation, standardizing photogrammetry in public procurement. EASA drone harmonization reduces operational friction for aerial surveying missions feeding reconstruction pipelines. Lyon engineering consultancies are migrating from perpetual licenses to subscription models through cooperative purchasing consortia.
United States
Construction firms in Texas and California are expanding photogrammetry deployment for site monitoring and progress documentation. FAA Part 107 regulations govern commercial drone operations supplying aerial imagery into processing pipelines. Pacific Northwest technology clusters are piloting neural radiance field techniques for real-time inspection applications.
Italy
Grant-funded monument documentation in Lazio and Tuscany prioritizes sub-millimeter accuracy over processing speed. Italy's €300 million cultural recovery fund creates dedicated budget lines for precision digitization workflows. Florence heritage agencies favor desktop processing models to retain custody of sensitive archaeological coordinates.
Poland
Mid-sized surveying practices in Warsaw and Krakow are adopting tablet-based edge processing to eliminate capital expenditure on rendering hardware. GDPR cross-border transfer restrictions block pure-SaaS models for defense clients, pushing vendors toward hybrid deployments. Silesian engineering firms leverage EASA-standardized flight permissions for corridor mapping missions.
3D Photogrammetry Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-native reconstruction and mobile edge deployment. The vendor base spans Swiss precision engineering specialists, Russian desktop software developers, and Nordic sensor-to-software conglomerates. Three archetypes dominate: sensor-integrated platform builders, standalone processing specialists, and cloud-native SaaS providers. Competitive moves center on hybrid deployment architecture development and heritage-focused feature set diversification.
Within the sensor-integrated tier, Hexagon AB and Trimble Inc. exemplify platform builders extending hardware-software ecosystems across surveying applications. Pix4D SA represents the standalone specialist archetype, leveraging Swiss R&D proximity to European precision users. Agisoft LLC anchors the desktop processing segment for researchers with limited connectivity. Autodesk Inc. and Bentley Systems Inc. occupy positions between CAD platform incumbency and photogrammetry module integration.
| Leading Market Players |
|---|
| Pix4D SA |
| Agisoft LLC |
| Autodesk Inc. |
| Bentley Systems Inc. |
| PhotoModeler Technologies |
| DroneDeploy Inc. |
| Hexagon AB |
| Trimble Inc. |
| RealityCapture |
| Others |
Pricing and Supply Chain Analysis
Swiss precision-software specialists and Nordic sensor-to-software conglomerates anchor pricing discipline through controlled release cycles and tiered licensing architectures. Their ownership structures—ranging from venture-backed scale-ups to publicly traded industrial holdings—shape both supply-side investment priorities and the premium commanded by desktop processing licenses over cloud-native alternatives.
Pricing Analysis
Volume concentrates in subscription SaaS tiers while margin pools in perpetual desktop licenses for heritage and defense applications. Price differentiation hinges on certification grade—ISO 17025 traceability for surveying deliverables—and vertical integration depth with sensor hardware bundles. Pricing pressure stems from GPU supply concentration extending workstation procurement timelines and compressing mid-tier margins. Mid-sized surveying practices in Poland and Czechia exhibit highest price sensitivity, migrating aggressively to pay-per-project cloud models, whereas German heritage agencies accept premium pricing for GDPR-compliant on-premises custody.
Supply Chain Analysis
EU AI Act domestic-content requirements for high-risk automated feature extraction are reshaping vendor sourcing toward European-sourced compute infrastructure. Software development concentrates in Switzerland, Sweden, and the United States, with GPU hardware dependency tethered to Taiwan-based foundry capacity. Supply chain risk centers on single-source vulnerability for workstation-class processors essential to dense point cloud generation. Distribution runs through specialized geomatics resellers in Germany and France, direct enterprise sales for defense contracts, and cooperative purchasing consortia aggregating independent surveyor networks in the Benelux region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU foundry capacity constraints prop pricing power for vendors controlling hybrid deployment architectures, as six-to-twelve month processor lead times block cost-sensitive competitors from scaling dense reconstruction workflows.
For Market Incumbents: Deepen hybrid infrastructure investments to satisfy EU AI Act human-in-the-loop mandates and GDPR territoriality requirements, insulating premium pricing from pure-SaaS challengers. Acquire tablet-based edge processing capabilities to capture mid-sized surveying practices in Central Europe migrating from outsourced computation. Prioritize heritage-focused feature sets—sub-millimeter accuracy toolsets, multi-spectral texture mapping—to defend margin pools in grant-funded monument documentation against neural radiance field disruptors. For New Entrants and Emerging Players: App-store distribution and tablet-optimized workflows offer low-friction entry into Polish and Czech mid-tier surveying practices previously priced out of workstation-class software. Target mobile edge deployment as the most penetrable wedge, leveraging neural radiance field compression to deliver real-time inspection capabilities without dense ground control infrastructure. Pursue cooperative purchasing consortia in the Benelux region as channel partners, unbundling implementation services from software access fees to accelerate procurement cycles. For Investors and Strategic Acquirers: EASA drone harmonization implementation across remaining member states is the leading indicator that aerial surveying mission volume will inflect, pulling photogrammetry pipeline demand upward. Long-term viability favors vendors with sensor-software ecosystem integration and heritage specialization, as construction digitization mandates commoditize standard as-built documentation. Watch for GPU supply normalization signals—foundry capacity expansion announcements or workstation processor lead time compression—as the inflection point where pricing power shifts from hybrid-architecture incumbents toward cloud-native scale challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Architecture Development | EU AI Act compliance and GDPR territoriality requirements route sensitive computations through on-premises nodes while accessing cloud burst capacity. |
| Neural Radiance Field Integration | Archaeological documentation teams in Greece and Turkey adopt NeRF-based tools for rapid site recording without dense ground control. |
| Heritage-Focused Feature Set Diversification | Italy's cultural recovery fund and Spanish monument programs create dedicated budget lines for sub-millimeter accuracy digitization workflows. |
| Mobile Edge Processing Launch | Tablet-based workflows penetrate mid-sized surveying practices in Poland and Czechia that previously outsourced computation to cloud services. |
| Sensor-Software Ecosystem Extension | Hexagon AB and Trimble Inc. leverage hardware-software bundling to capture surveying applications requiring integrated coordinate system transformation. |
Research Methodology
Document review covered EASA regulatory filings, EU AI Act implementation guidance, GDPR territoriality case law, and heritage digitization grant program announcements, complemented by interviews with geomatics software product managers, surveying equipment procurement leads at German engineering consultancies, cultural heritage digitization program officers in Italy and Spain, and cloud infrastructure architects at photogrammetry SaaS providers. Secondary validation drew from SEC filings of publicly traded sensor-to-software conglomerates, hyperscaler capex disclosures for GPU infrastructure, and trade data on workstation-class processor imports. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from licensing revenue disclosures and reseller channel surveys.
Segment-level outputs across deployment model, end-user technical sophistication, and industry vertical were projected over the analysis window using adoption curve modeling calibrated to BIM mandate implementation timelines and EASA flight permission standardization progress. CAGRs were derived from elasticity-adjusted price-volume relationships and technology substitution coefficients capturing neural radiance field penetration rates. Forecast inputs incorporated GPU supply constraint duration scenarios, EU AI Act enforcement intensity gradients across member states, and heritage grant program renewal probabilities.
The model holds under sustained GPU supply scarcity and phased EU AI Act implementation; deviation in foundry capacity normalization or accelerated regulatory harmonization would shift competitive positioning toward cloud-native architectures. Forecasts reflect assumptions on drone flight permission standardization velocity and desktop-to-cloud migration elasticity in mid-tier surveying segments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
3D Technology Market
3D Technology
Europe 3D Telepresence Market
3D Technology
3D Simulation Software Market
3D Technology
3D Scanner Market
3D Technology
Mobile 3D Market
3D Technology
3D Reconstruction Market
3D Technology
Europe 3D 4D Technology Market
3D Technology
Smartphone 3D Camera Market
3D Technology
3D CAD Market
3D Technology
Generative Design Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
Molecular Modeling Market
3D Technology
3D Rendering Market
3D Technology
Global 3D 4D Technology Market
3D Technology
3D Mobile Mapping Market
3D Technology
APAC 3D 4D Technology Market