
 Anti-Acne Cosmetics Market | 2026-2036
Anti-Acne Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Acne Cosmetics Market Intelligence
Subscription-based replenishment programs is repositioning how consumers acquire anti-acne regimens, shifting transactions from one-time retail purchases into recurring revenue streams. Procter & Gamble Co. leverages its mass-market distribution infrastructure to sustain volume leadership in accessible price tiers. Estée Lauder Companies Inc. anchors its premium positioning through dermatologist-validated formulations that command higher per-unit margins. Murad LLC specializes in professional-channel exclusivity, competing against retail-centric rivals by controlling clinic and spa access points.
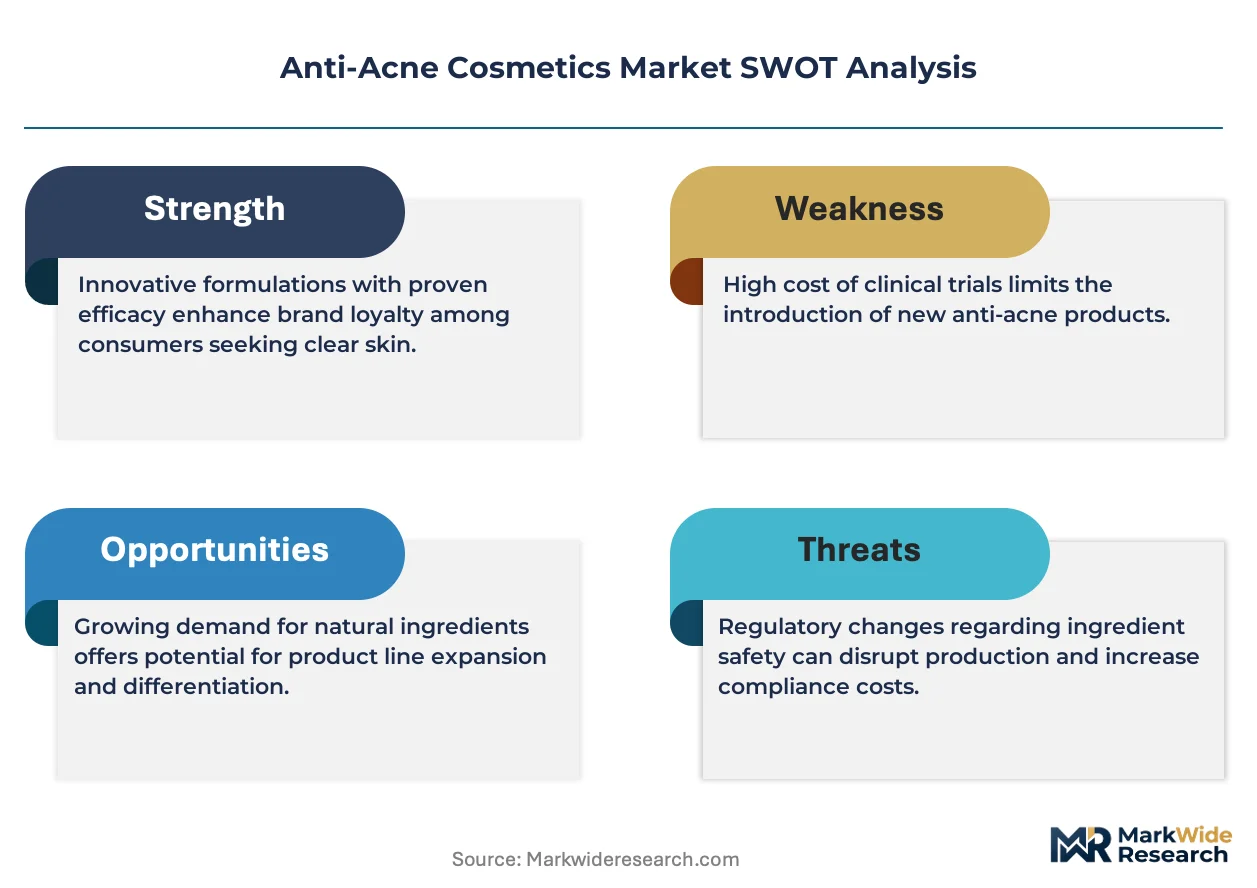
Anti-acne cosmetics comprise topical preparations containing active concentrations of salicylic acid, benzoyl peroxide, or retinoids, formulated to reduce sebum production, comedone formation, and Cutibacterium acnes colonization on facial and truncal skin. These products serve both aesthetic and therapeutic purposes, bridging over-the-counter skincare with clinically oriented skin health management. Gels dominate the product type landscape due to their lightweight vehicle compatibility with oily and acne-prone skin profiles, while cleansers represent the fastest-expanding category as double-cleansing routines gain adherence among young adults. Salicylic acid remains the anchor ingredient across mass-market lines, though retinoid-infused formulations capture disproportionate margin pools through prescription-adjacent positioning and tolerability innovations.
FDA oversight of over-the-counter acne drug products under the monograph system governs active ingredient concentrations and labeling claims in the United States, while REACH and the EU Cosmetics Regulation mandate exhaustive safety dossiers and nanomaterial disclosures for European market access. China's NMPA implements separate registration pathways for cosmetics containing drug-like actives, creating compliance complexity for brands seeking cross-border e-commerce penetration. Stakeholders must monitor evolving classification thresholds that could reclassify high-strength retinoid cosmetics as pharmaceutical products, fundamentally altering distribution channels and marketing permissible.
Market Dynamics
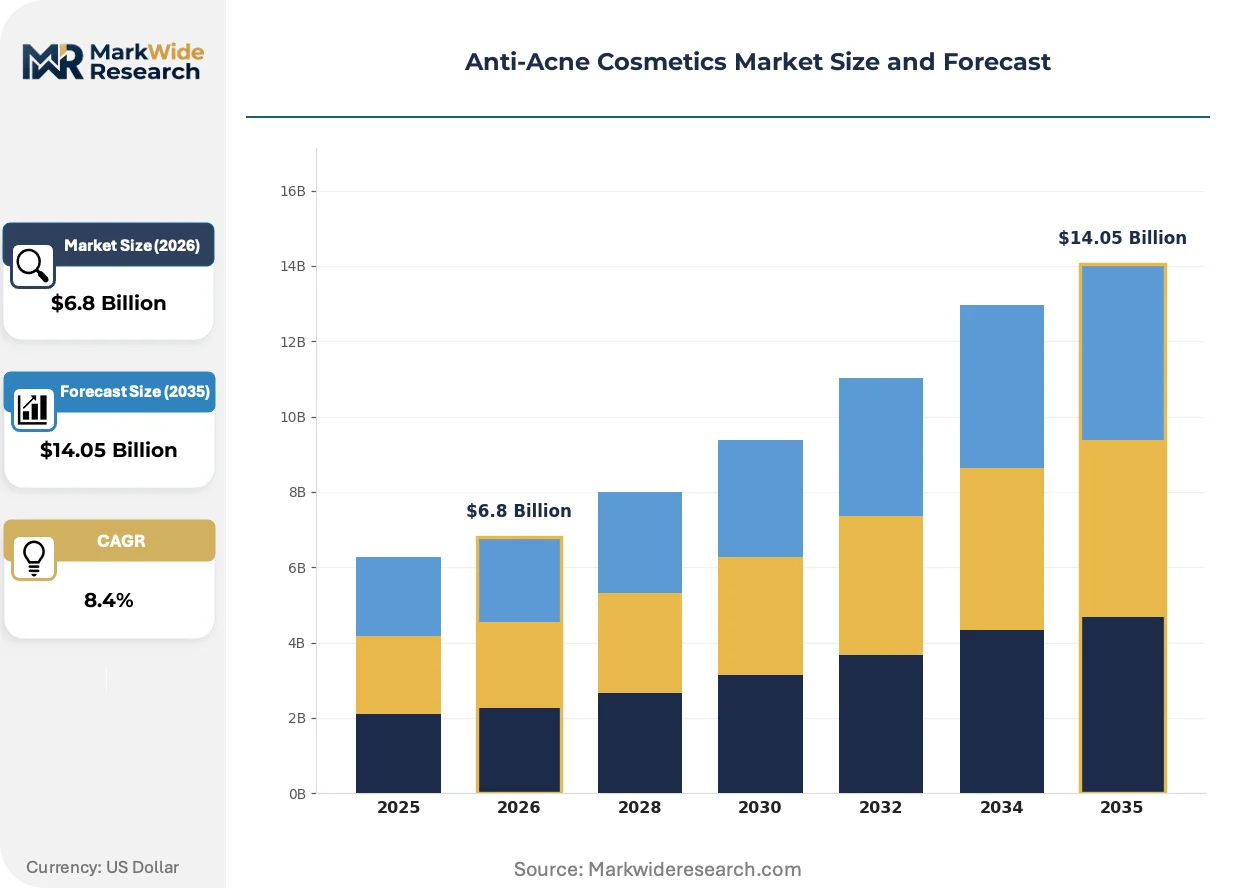
Subscription-based replenishment programs are consolidating consumer acquisition patterns around recurring revenue models, while professional-channel exclusivity and KOL-driven education in China's tier-one cities reshape competitive positioning across price tiers.
Growth Catalysts
- EU MDR and REACH frameworks:Tightening ingredient disclosure requirements accelerate premium brand differentiation through transparency credentials, rewarding compliant manufacturers with accelerated pharmacy and clinic access.
- Dermatology clinics and medispas:Professional-grade formulations gain traction as these channels validate efficacy claims through supervised application protocols, converting skeptical consumers to higher-margin regimens.
- KOL-driven skincare education:Live-streaming commerce in Shanghai, Beijing, and Guangzhou compresses purchase consideration cycles, enabling direct-to-consumer brands to bypass traditional retail gatekeepers.
Market Restraints
- Active ingredient supply concentration:Benzoyl peroxide and retinoid precursor manufacturing clusters in India and China create vulnerability to export restriction shocks and currency volatility.
- China NMPA registration pathways:Separate approval tracks for cosmetics containing drug-like actives impose 18-24 month compliance timelines, freezing cross-border e-commerce penetration for reformulated products.
- Prescription retinoid substitution:Generic tretinoin and adapalene availability through tele-dermatology platforms undercuts premium cosmetic retinoid pricing power in the United States.
Strategic Opportunities
- Truncal acne applications:Back and chest treatment formats remain underdeveloped relative to facial SKUs, offering first-mover margin expansion through spray and body-wash vehicle innovations.
- Double-cleansing routine adoption:Young adult consumers in Seoul and Tokyo demonstrate willingness to layer oil-based precleansers with salicylic acid foams, expanding basket size and replenishment frequency.
- US FDA monograph modernization:Anticipated updates to over-the-counter acne drug standards may permit novel active combinations, rewarding early dossier investment with temporary exclusivity windows.
Industry Challenges
- Formulation stability expertise:Retinoid oxidation control and benzoyl peroxide crystallization prevention require specialized chemist talent scarce outside established dermatology R&D hubs.
- Legacy ERP integration:Subscription billing and personalized regimen algorithms demand reconfiguration of inventory management systems originally architected for wholesale batch fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Acne Cosmetics Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Creams, Foams, Cleansers Key Ingredients: Salicylic Acid, Benzoyl Peroxide, Retinoids, Alpha Hydroxy Acids Age Group: Teens, Young Adults, Adults, Seniors Delivery Mode: Topical, Oral, Combination, Spot Treatment |
| Companies Covered | L'Oréal S.A., Procter & Gamble Co., Johnson & Johnson Services, Inc., Estée Lauder Companies Inc., Unilever, Neutrogena, Murad LLC, Clinique Laboratories, LLC, Proactiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Acne Cosmetics Market Strategic Shifts & Innovations
Microbiome-targeted actives and tolerability-engineered retinoid delivery systems are consolidating technical differentiation, while regulatory divergence between pharmaceutical and cosmetic classification thresholds forces portfolio architecture decisions.
Encapsulated retinol and retinaldehyde delivery systems are consolidating efficacy claims previously reserved for prescription tretinoin. Dermatology clinics in Germany and South Korea adopt these formulations for pre- and post-procedure protocols, compressing the boundary between cosmetic and therapeutic positioning. This convergence is consolidating margin pools around tolerability innovation rather than raw active concentration.
China's NMPA is tightening borderline product scrutiny, forcing brands to pre-register retinoid strengths above 0.3% through pharmaceutical pathways. Domestic manufacturers in Guangdong province accelerate dossier preparation, while cross-border sellers retreat to lower-concentration SKUs. This regulatory friction is fragmenting product availability between domestic and import channels.
Young adult buyers in tier-one Chinese cities compress repurchase cycles through algorithm-driven replenishment apps. Tmall and Douyin integration enables skin-progression photo tracking that triggers automatic refills, displacing discretionary retail browsing. This behavioral shift concentrates loyalty around platforms owning the data layer rather than brands owning the relationship.
Anti-Acne Cosmetics Market Segmentation
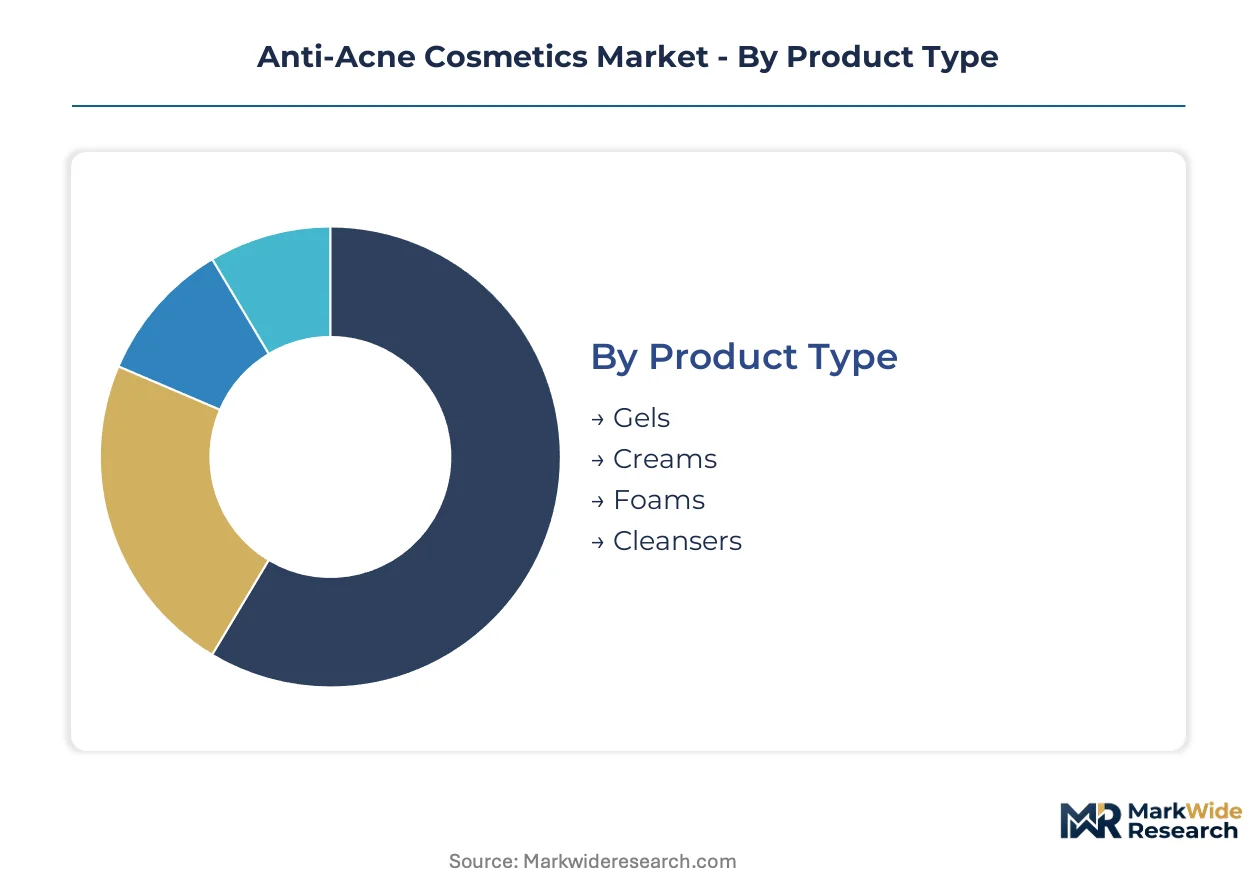
Anti-acne cosmetics demand fragments across formulation vehicles, active chemistries, and life-stage skin biology, requiring manufacturers to architect portfolios that span sebum-control mechanisms and tolerability thresholds. Each segmentation axis carries distinct margin profiles and regulatory exposure, from OTC monograph compliance in the United States to NMPA registration tiers in China.
Product Type:
Formulation vehicle selection determines occlusivity, spreadability, and active penetration depth against follicular occlusion patterns.
- Gels:Water-based matrices with minimal lipid content suit oily and acne-prone facial skin without comedogenic residue. Demand concentrates in dermatology clinics across Germany and South Korea where clinicians prescribe gel vehicles for post-procedure tolerability.
- Cleansers:Surfactant systems delivering salicylic acid or benzoyl peroxide during wash-off contact time. Double-cleansing adoption in Seoul and Tokyo accelerates replenishment frequency among young adult consumers layering oil-based precleansers.
- Creams:Emulsion vehicles with higher lipid fractions target drier skin subtypes and truncal applications where barrier support matters.
- Foams:Aerosolized or pump-dispensed formats enable uniform coverage across back and chest treatment zones with minimal manual spreading.
Gels lead on scale; cleansers lead on momentum.
Key Ingredients:
Active chemistry selection governs mechanism of action, regulatory classification risk, and pricing power through concentration thresholds.
- Salicylic Acid:Beta-hydroxy acid with keratolytic and comedolytic properties operating at 0.5-2% concentrations under FDA monograph. Mass-market lines in the United States anchor portfolios here for OTC accessibility without prescription friction.
- Retinoids:Vitamin A derivatives including retinol, retinaldehyde, and prescription-adjacent concentrations requiring stability engineering. Encapsulation innovations in Swiss and German R&D hubs capture premium positioning through tolerability differentiation.
- Benzoyl Peroxide:Antimicrobial oxidizing agent effective against Cutibacterium acnes with concentration-dependent irritation tradeoffs.
- Alpha Hydroxy Acids:Glycolic and lactic acids providing superficial exfoliation with less follicular penetration than salicylic acid.
Salicylic acid leads on scale; retinoids lead on momentum.
Age Group:
Sebum production kinetics and hormonal drivers shift treatment priorities across developmental stages.
- Teens:Peak androgen-driven sebum output with treatment-naive skin tolerating higher irritation thresholds. School-based screening programs in Japan and South Korea drive early regimen initiation.
- Young Adults:Persistent acne extending into twenties with lifestyle-triggered flares from stress and cosmetic occlusion. Subscription replenishment apps in Shanghai and Beijing concentrate loyalty through algorithm-driven refill triggers.
- Adults:Late-onset acne with slower cell turnover requiring gentler actives and barrier-supportive co-formulations.
- Seniors:Acne rosacea overlap and medication-induced breakouts demanding non-irritating vehicles with anti-inflammatory positioning.
Teens lead on scale; young adults lead on momentum.
Delivery Mode:
Application architecture determines contact time, targeting precision, and systemic exposure risk.
- Topical:Direct skin application with localized action and minimal systemic absorption. This mode dominates pharmacy and clinic dispensing in France and Italy where supervised application protocols validate efficacy claims.
- Spot Treatment:High-concentration localized application for inflammatory lesions, enabling consumer self-triage without full-face regimen commitment.
- Combination:Layered topical systems or topical-oral pairings addressing multiple acne pathogenesis pathways simultaneously.
- Oral:Systemic delivery through nutraceutical or prescription-adjacent routes, typically positioned outside cosmetic classification to avoid NMPA pharmaceutical registration in China.
Topical leads on scale; spot treatment leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities outpace US coastal metros in KOL-driven premium uptake, while Germany's dermatology channel validates efficacy claims through supervised protocols. Regulatory divergence between FDA monograph systems and NMPA registration tiers fragments product availability across major markets.
United States
FDA monograph compliance anchors mass-market salicylic acid and benzoyl peroxide lines, while tele-dermatology platforms expand generic tretinoin access. The OTC acne drug framework permits concentrations up to 2% for salicylic acid and 10% for benzoyl peroxide without prescription friction. Greater Boston and San Francisco Bay Area clusters concentrate tolerability-engineered retinoid R&D for clinic-dispensed formulations.
China
Shanghai, Beijing, and Guangzhou compress purchase cycles through live-streaming commerce and algorithm-driven replenishment apps. NMPA registration pathways impose 18-24 month timelines for cosmetics containing drug-like actives above 0.3% retinoid concentrations. Guangdong province manufacturers accelerate pharmaceutical dossier preparation as borderline scrutiny tightens, fragmenting domestic versus import channel availability.
Germany
Dermatology clinics across Berlin and Munich validate professional-grade formulations through supervised application protocols, converting skeptical consumers to higher-margin regimens. EU MDR and REACH frameworks reward compliant manufacturers with accelerated pharmacy and clinic access through transparency credentials. Baden-Württemberg hosts encapsulation innovation clusters engineering retinaldehyde delivery systems for pre- and post-procedure protocols.
South Korea
Seoul's young adult consumers demonstrate willingness to layer oil-based precleansers with salicylic acid foams, expanding basket size through double-cleansing adherence. School-based screening programs drive early regimen initiation among treatment-naive teens. The MFDS maintains alignment with international cosmetic standards while domestic manufacturers pioneer microbiome-targeted active development.
Japan
Tokyo and Osaka concentrate demand for gentle, barrier-supportive co-formulations addressing adult late-onset acne with slower cell turnover. METI oversight ensures exhaustive safety documentation for active concentrations near pharmaceutical thresholds. Kanto region R&D hubs specialize in oxidation-control technologies for retinoid stability in humid climates.
Anti-Acne Cosmetics Market Key Industry Players
Top-tier vendors anchor premium dermatology channels, while mass-market players sustain volume leadership through accessible price tiers. Mid-tier specialists compete on formulation vehicle innovation and subscription retention mechanics. Three archetypes dominate: multinational conglomerates with mass-market distribution infrastructure, premium houses with clinic-validated positioning, and professional-channel exclusives controlling spa and medispa access points. Competitive moves concentrate on M&A for R&D capability acquisition and strategic partnerships with tele-dermatology platforms.
Within the premium-tier vector, Estée Lauder Companies Inc. and Murad LLC exemplify divergent channel strategies—one leveraging dermatologist validation for margin expansion, the other enforcing professional exclusivity against retail-centric rivals. Procter & Gamble Co. anchors mass-market scale through replenishment program integration and shelf-space dominance. These three entities collectively illustrate how pricing power fragments across accessibility, clinical credibility, and controlled distribution architectures.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Procter & Gamble Co. |
| Johnson & Johnson Services, Inc. |
| Estée Lauder Companies Inc. |
| Unilever |
| Neutrogena |
| Murad LLC |
| Clinique Laboratories, LLC |
| Proactiv |
| Others |
Cost & Logistics Intelligence
Dermatology clinics and medispas concentrate procurement power for professional-grade formulations, anchoring a three-tier pricing structure across premium, standard, and economy levels that segments by channel access and clinical validation depth.
Pricing Analysis
Capacity additions in Guangdong province are reshaping price floors for benzoyl peroxide and retinoid precursor supply. Premium-mid-economy pricing differentiation separates dermatologist-validated clinic lines from mass-market retail SKUs and private-label economy tiers. Cost compression in standard retail channels is intensifying because tele-dermatology platforms expand generic tretinoin availability. Young adult consumers in Chinese tier-one cities show lowest price sensitivity, while teen segments in mass-market US channels exhibit highest elasticity.
Supply Chain Analysis
Direct-to-clinic channels handle professional-grade formulation demand, while mass-market distribution feeds retail and e-commerce replenishment programs. Active ingredient manufacturing clusters in India and China supply benzoyl peroxide and retinoid precursors. Formulation stability expertise draws from Swiss and German R&D hubs. Single-source vulnerability concentrates in encapsulated delivery system technology held by specialty chemical suppliers. Distribution runs through dermatology clinics, pharmacy chains, and platform-integrated direct-to-consumer apps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU MDR and REACH framework tightening accelerates premium brand differentiation through transparency credentials.
For Market Incumbents: Deploy clinic channel exclusivity to defend margin pools against tele-dermatology substitution. Consolidate R&D capability in encapsulation innovation clusters across Baden-Württemberg to preempt tolerability-engineered retinoid competition. Capacity addition threats from Guangdong manufacturers require accelerated pharmaceutical dossier preparation for borderline product registration.
For New Entrants and Emerging Players: Enter via truncal acne application formats where spray and body-wash vehicle innovations remain underdeveloped relative to facial SKUs. Target young adult subscription replenishment apps in Shanghai and Beijing where algorithm-driven refill triggers concentrate loyalty. White-space exists in microbiome-targeted actives with pre- and post-procedure protocol validation.
For Investors and Strategic Acquirers: Consumer goods conglomerates with dermatology portfolio gaps are the most active acquirer in this space. Long-term viability hinges on regulatory navigation capability across FDA monograph, EU REACH, and NMPA registration tiers. Acquisition target archetype: mid-tier specialists with formulation vehicle innovation and subscription retention mechanics. Watch NMPA borderline product scrutiny intensity as inflection signal for pharmaceutical reclassification risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Swiss and German R&D hubs capture premium positioning through tolerability differentiation. |
| Clinic Channel Partnership Expansion | Berlin and Munich dermatology protocols validate efficacy claims for higher-margin regimens. |
| Subscription Replenishment Platform Integration | Tmall and Douyin algorithm-driven refills displace discretionary retail browsing in tier-one cities. |
| NMPA Pharmaceutical Dossier Preparation | Guangdong manufacturers accelerate registration to preempt borderline product reclassification. |
| Truncal Acne Format Development | Back and chest treatment innovations offer first-mover margin expansion through spray vehicles. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with dermatology clinic procurement managers, cosmetic chemists at encapsulation R&D hubs, brand managers at multinational conglomerates, and regulatory affairs leads navigating NMPA registration pathways supplied forward-looking intelligence. Secondary validation drew from FDA monograph filings, EU MDR compliance databases, China customs import records, and MFDS cosmetic safety documentation. Bottom-up SKU-level modeling and top-down category sizing triangulated market estimates.
Historical reference periods anchored projection assumptions across the analysis window. Segmentation dimensions spanned formulation vehicle, active chemistry, age-group skin biology, and delivery mode. CAGRs derived from trend extrapolation against regulatory milestone timing and channel shift velocity. Forecast inputs incorporated KOL-driven education penetration rates in Chinese tier-one cities and tele-dermatology platform expansion trajectories in the United States.
Inputs from primary stakeholder interviews were available through the study window; gaps in proprietary subscription retention data introduce uncertainty bands around replenishment revenue forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Luxury Cosmetics Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Post-Shave Care Market
Beauty & Personal Care
Salon Service Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
Colombia Cosmetics Products Market
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
North America Bath and Shower Products Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
US Cosmetics Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Personal Care Contract Manufacturing Market
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
Personal Care Shower and Bath Market