
 Anti-Dandruff Shampoo Market | 2026-2036
Anti-Dandruff Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Dandruff Shampoo Market Insights
Subscription-based replenishment programs and software-driven personalization engines are shifting how anti-dandruff shampoo reaches households. Procter & Gamble leverages its direct-to-consumer platforms to sustain recurring revenue streams. Unilever anchors its portfolio through pharmacy-led distribution networks in emerging markets. L'Oréal differentiates via dermatological endorsement channels that command premium positioning.
Anti-dandruff shampoo comprises surfactant-based cleansing systems incorporating active ingredients such as zinc pyrithione, ketoconazole, or selenium sulfide at concentrations between 1% and 2%, designed to modulate Malassezia yeast populations and reduce scalp flaking. The medicated segment dominates volume due to clinical efficacy claims and pharmacy channel placement, while natural-origin formulations represent the fastest-expanding margin pool as clean-label preferences intensify among adult end users. Liquid formulations occupy the majority share, though gel formats are gaining traction among teen consumers seeking residue-free sensory profiles.
The US FDA regulates anti-dandruff products as over-the-counter drugs under monograph conditions, dictating permissible active concentrations and labeling requirements. The EU ECHA enforces REACH compliance for cosmetic biocides, while India's CDSCO monitors medicated shampoo claims through its cosmetics regulation framework. Stakeholders must monitor evolving ingredient restriction lists and channel-specific compliance costs as formulation complexity intensifies across jurisdictions.
Market Dynamics
The EU REACH framework is electrifying formulation chemistry across the anti-dandruff shampoo sector, forcing manufacturers to retire zinc pyrithione and selenium sulfide in favor of bio-based alternatives that satisfy biocide restrictions while preserving clinical efficacy against Malassezia yeast.
Growth Catalysts
- Pharmacy channel expansion:Emerging markets in Brazil and Nigeria are witnessing pharmacy-led distribution networks displace general trade, elevating medicated shampoo penetration among clinically motivated buyers.
- CDSCO cosmetics framework:India's streamlined approval pathways for medicated personal care products are accelerating product registration timelines and reducing compliance uncertainty for multinational entrants.
- Scalp microbiome sequencing:Advances in genomic profiling are enabling precision-targeted active ingredient selection, improving therapeutic outcomes for resistant dandruff phenotypes.
Market Restraints
- Active ingredient supply concentration:Ketoconazole API production clusters in select East Asian manufacturing hubs, exposing formulators to single-source dependency risks and input cost volatility.
- REACH biocide reclassification:The European Chemicals Agency's tightening restrictions on conventional anti-fungal actives are forcing costly reformulation cycles and portfolio rationalization.
- Natural-origin efficacy gap:Plant-derived alternatives struggle to match the rapid onset of clinical improvement delivered by synthetic actives, limiting premium pricing power in medicated segments.
Strategic Opportunities
- Subscription personalization engines:Direct-to-consumer platforms leveraging scalp assessment algorithms can capture recurring revenue through tailored product sequencing and usage optimization coaching.
- South Korean regulatory sandbox:The MFDS pilot program for novel cosmetic-drug hybrids offers accelerated market access for next-generation scalp therapeutics with dual aesthetic-therapeutic positioning.
- Teen sensory segmentation:Gel-format, residue-free formulations targeting adolescent preference profiles remain underdeveloped relative to adult-centric liquid standards.
Industry Challenges
- Formulation chemist scarcity:The intersection of cosmetic science and dermatological pharmacology demands specialized expertise that outpaces current graduate pipeline output.
- Multi-jurisdiction labeling harmonization:Divergent monograph requirements between the US FDA and EU ECHA force parallel packaging runs and inventory fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Dandruff Shampoo Market |
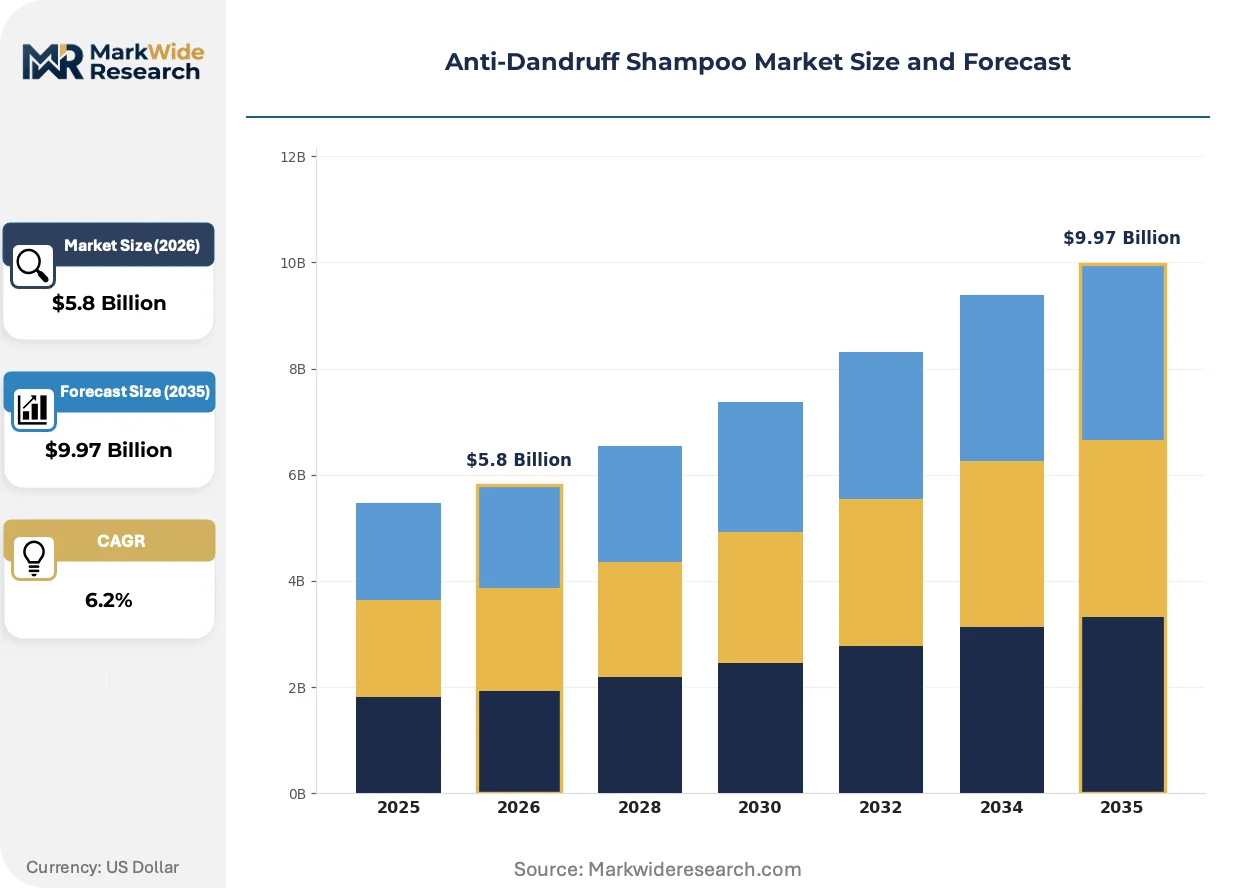
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.97 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medicated, Natural, Herbal, Cosmetic Formulation: Liquid, Cream, Gel, Foam End User: Adults, Teens, Children, Seniors Distribution Channel: Supermarkets, Online Retailers, Pharmacies, Salons |
| Companies Covered | Henkel, Amorepacific, Procter & Gamble, Keune, Pierre Fabre, Unilever, Kao, Himalaya Drug, L'Oréal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Dandruff Shampoo Market Trends and Innovations
Formulation science is diverging along two paths: clinical-grade efficacy verification and clean-label ingredient transparency. This bifurcation is reshaping R&D investment allocation and channel positioning strategies simultaneously.
Encapsulated delivery systems employing lipid nanoparticle carriers are electrifying active ingredient stability and scalp penetration profiles. Dermatology clinics in Germany and South Korea are adopting these platforms for patient-specific therapeutic protocols. The technology is compressing the performance gap between cosmetic and prescription-grade scalp treatments.
REACH authorization requirements for residual biocide concentrations are mandating analytical testing protocols that exceed prior self-certification standards. Third-party laboratory capacity in the European Union is experiencing bottlenecks as reformulation deadlines approach. Smaller manufacturers without captive testing infrastructure face extended time-to-market cycles.
Urban Indian consumers are migrating from sachet-based trial purchases toward bottle commitments through quick-commerce platforms. Blinkit and Zepto are disintermediating traditional kirana networks for anti-dandruff replenishment in metropolitan corridors. This behavioral shift concentrates volume with platform-integrated brands capable of same-day fulfillment infrastructure.
Anti-Dandruff Shampoo Market Segmentation
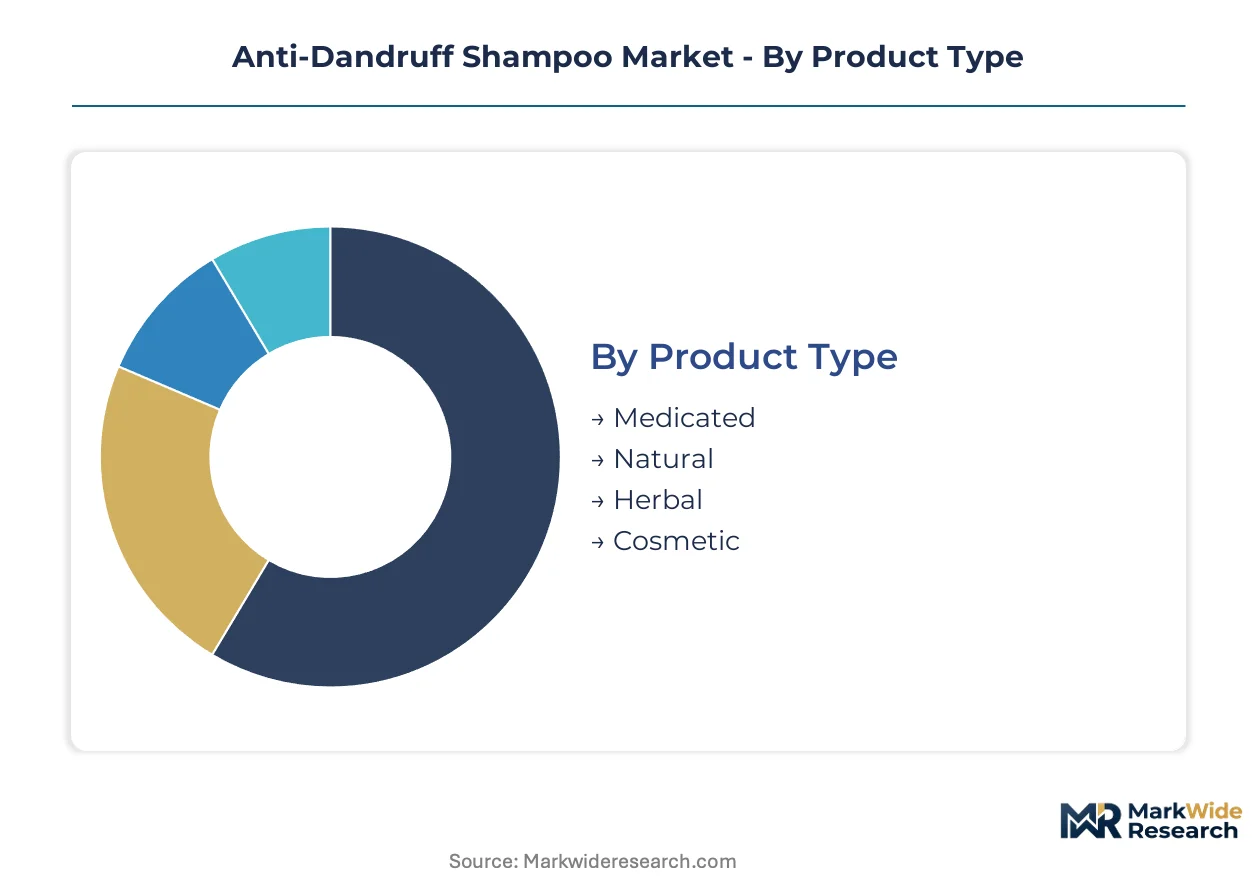
Anti-dandruff shampoo manufacturers segment portfolios to match distinct scalp conditions, sensory preferences, and purchase contexts. Each category reveals divergent margin structures and channel dependencies that shape resource allocation decisions.
Product Type:
Consumers upgrade from basic cleansing to targeted therapeutic solutions as scalp health awareness spreads through pharmacy and dermatology channels.
- Medicated:Zinc pyrithione, ketoconazole, or selenium sulfide formulations at 1-2% concentration deliver clinical efficacy against Malassezia yeast proliferation. Pharmacy networks in Brazil and Nigeria concentrate demand among clinically motivated buyers seeking rapid flake reduction.
- Natural:Plant-derived actives such as tea tree oil and salicylic acid from willow bark address clean-label preferences without synthetic biocides. Urban consumers in Germany and South Korea drive fastest expansion as REACH restrictions intensify scrutiny of conventional anti-fungal compounds.
- Herbal:Ayurvedic and traditional medicine-inspired blends incorporating neem, amla, and shikakai target heritage-conscious segments in India and Southeast Asia.
- Cosmetic:Aesthetic-focused variants prioritizing fragrance profiles and packaging design over therapeutic claims capture impulse purchases in general trade.
Medicated sits at the top of the volume ranking, with Natural climbing the fastest.
Formulation:
Texture preferences correlate with age demographics and hair type, driving parallel development tracks across viscosity and residue profiles.
- Liquid:Standard pourable consistency dominates manufacturing scale and shelf placement economics across mass retail.
- Cream:Thicker emulsion systems deliver conditioning benefits for coiled or chemically treated hair textures.
- Gel:Transparent, residue-free formats with rapid rinse properties attract teen users in South Korea and urban India seeking sensory differentiation from parental product choices.
- Foam:Aerosol or pump-dispensed mousse formats reduce application friction for mobility-limited seniors and institutional care settings.
Liquid retains dominant volume share, while Gel gains share fastest among format innovations.
End User:
Life-stage segmentation determines active ingredient potency, fragrance intensity, and packaging safety requirements.
- Adults:Core revenue base spanning therapeutic and maintenance regimens with highest per-capita consumption frequency.
- Teens:Oil-control and social-acceptance drivers concentrate demand in gel formats and subscription personalization platforms.
- Children:Mild surfactant systems with tear-free formulations face stringent safety testing under FDA and EU cosmetic directives.
- Seniors:Dry-scalp variants with reduced cleansing aggression address age-related sebum production decline and skin barrier fragility.
Adults anchor revenue concentration, with Teens showing steepest expansion trajectory through digital-native purchase channels.
Distribution Channel:
Channel selection determines margin capture, regulatory compliance burden, and consumer education depth.
- Supermarkets:Mass-market velocity with promotional dependency and slotting fee structures that compress net margins for mid-tier brands.
- Online Retailers:Direct-to-consumer platforms enable subscription personalization and scalp assessment algorithms that lock in recurring revenue streams.
- Pharmacies:Professional endorsement environment supports premium pricing for medicated claims under CDSCO and FDA monograph frameworks.
- Salons:Stylist recommendation channel delivers trial conversion for professional-grade formulations with elevated per-unit economics.
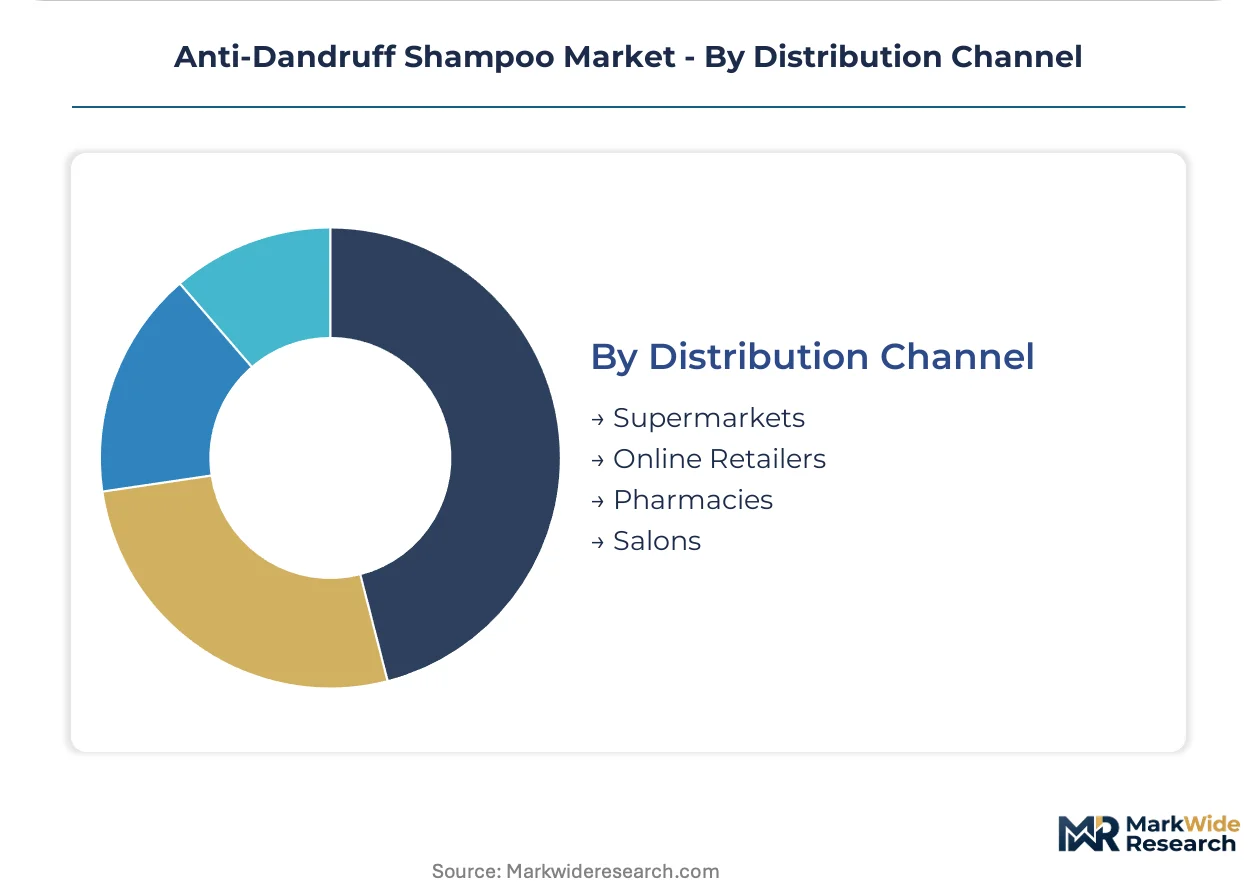
Supermarkets maintain volume leadership, with Online Retailers expanding most quickly through quick-commerce integration in Indian metros.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pharmacy-led distribution networks contrast with India's quick-commerce acceleration, illustrating how emerging markets diverge in channel evolution despite shared category expansion trajectories.
United States
Adult consumers sustain volume concentration through therapeutic maintenance regimens and dermatologist-recommended protocols. The FDA monograph framework governs permissible active concentrations and labeling claims for over-the-counter drug classification. Manufacturing clusters in New Jersey and Ohio support formulation chemistry capabilities serving North American pharmacy and mass retail channels.
Germany
Clean-label preferences intensify demand for natural-origin formulations as REACH biocide restrictions reshape permissible ingredient portfolios. The ECHA authorization requirements mandate analytical testing protocols exceeding prior self-certification standards. Berlin and Hamburg host third-party laboratory capacity experiencing bottlenecks as reformulation deadlines approach smaller manufacturers.
India
Young adult urban consumers migrate from sachet-based trial purchases toward bottle commitments through quick-commerce platforms. The CDSCO cosmetics framework streamlines approval pathways for medicated personal care products, accelerating registration timelines for multinational entrants. Mumbai and Bangalore concentrate platform-integrated brand operations capable of same-day fulfillment infrastructure.
Brazil
Pharmacy-led distribution networks displace general trade, elevating medicated shampoo penetration among clinically motivated buyers. ANVISA regulates cosmetic and drug classifications for scalp therapeutic claims. São Paulo anchors formulation manufacturing serving Latin American markets with elevated compliance infrastructure.
South Korea
Teen consumers drive gel-format adoption seeking residue-free sensory profiles distinct from parental product choices. The MFDS pilot program for novel cosmetic-drug hybrids offers accelerated market access for next-generation scalp therapeutics. Seoul concentrates R&D investment in encapsulated delivery systems employing lipid nanoparticle carriers.
Anti-Dandruff Shampoo Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational consumer goods conglomerates anchoring pharmacy and mass retail channels while regional Ayurvedic and natural-origin specialists capture heritage-conscious niches. The structure concentrates among three to five global players with dermatological endorsement capabilities and direct-to-consumer platform integration. Strategic archetypes include science-backed medicated specialists, clean-label natural originators, and platform-native personalization engines. Competitive moves center on subscription infrastructure deployment and REACH-compliant reformulation acceleration.
Among European-headquartered conglomerates, Unilever and L'Oréal occupy positions spanning mass-market velocity through premium dermatological tiers. Procter & Gamble exemplifies the direct-to-consumer archetype with recurring revenue platform architecture. Himalaya Drug represents the heritage Ayurvedic specialist segment with natural-origin formulation credibility in South Asian markets.
| Leading Market Players |
|---|
| Henkel |
| Amorepacific |
| Procter & Gamble |
| Keune |
| Pierre Fabre |
| Unilever |
| Kao |
| Himalaya Drug |
| L'Oréal |
| Others |
Pricing and Supply Chain Analysis
Captive API manufacturing in select East Asian hubs anchors supply positioning and pricing power for ketoconazole-dependent formulators, while REACH-driven reformulation cycles force portfolio rebalancing toward higher-margin natural-origin tiers.
Pricing Analysis
Capacity additions in India and Vietnam are reshaping price floors for surfactant and botanical active inputs. Pricing stratifies across premium dermatological endorsements, standard pharmacy-channel medicated lines, and economy-tier general trade sachets. Cost compression in synthetic biocide formulations is intensifying because ECHA authorization requirements extend development timelines. Price-sensitive buyers in Nigeria and Southeast Asia concentrate in sachet and small-format bottle tiers, while German and South Korean consumers absorb premiums for clean-label natural alternatives.
Supply Chain Analysis
Single-source vulnerability sits with ketoconazole API production concentrated in China and South Korea. Formulation chemistry draws from zinc pyrithione feedstocks, selenium sulfide precursors, and encapsulated lipid nanoparticle carriers. Tariff exposure on biocide imports into the European Union compounds reformulation cost pressures. Distribution runs through pharmacy-led networks in Brazil and Nigeria, quick-commerce platforms in Indian metros, and direct-to-consumer subscription engines for personalized regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this category rests on REACH-compliant natural-origin tier migration and subscription-based recurring revenue capture that reduces customer acquisition cost burdens.
For Market Incumbents: Cement pharmacy channel control in Brazil and Nigeria through exclusive distribution agreements with regional drugstore chains. Accelerate captive supply of botanical actives to offset ketoconazole API concentration risk. Defend against platform-native entrants by integrating scalp assessment algorithms into existing direct-to-consumer infrastructure.
For New Entrants and Emerging Players: Teen consumers seeking residue-free gel formats represent an underserved buyer archetype with limited incumbent specialization. Capture white space in South Korean and urban Indian quick-commerce channels where sensory differentiation commands trial conversion. Deploy influencer-driven education campaigns on scalp microbiome science to bypass traditional pharmacy endorsement gatekeepers.
For Investors and Strategic Acquirers: Roll-up economics work for regional Ayurvedic specialists with CDSCO-registered natural-origin portfolios because India's streamlined approval pathways reduce regulatory friction for scaled platforms. Target heritage brands with existing botanical supply relationships and pharmacy network density. Watch ECHA biocide restriction expansion timelines as inflection indicators for accelerated natural-origin substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation | ECHA authorization deadlines force accelerated R&D allocation toward bio-based actives. |
| Direct-to-Consumer Platform Launch | Subscription personalization engines capture recurring revenue through scalp assessment algorithms. |
| Pharmacy Channel Expansion | ANVISA-regulated networks in Brazil elevate medicated product penetration among clinical buyers. |
| Botanical API Backward Integration | In-house cultivation of neem and tea tree oil feedstocks reduces synthetic biocide dependency. |
| Teen Sensory Format Development | Gel-format innovation in South Korea addresses residue-free preferences distinct from adult liquids. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with brand managers at multinational consumer goods conglomerates, category buyers at Indian quick-commerce platforms, pharmacy procurement heads in Brazil, and CDSCO regulatory consultants combined with secondary validation from customs records, Nielsen retail audit data, FDA OTC monograph filings, and ECHA biocide authorization databases. Triangulation across these sources ensures demand-side consumption patterns align with manufacturing capacity and ingredient supply trajectories.
Input-output matrices connect active ingredient supply concentrations with formulation output by product tier across the projection horizon. Segmentation dimensions modeled include medicated versus natural-origin product type, liquid versus gel formulation, adult versus teen end-user, and pharmacy versus online distribution channel. CAGRs derive from regression analysis of historical consumption velocity against regulatory event timelines and channel shift elasticities. Forecast inputs incorporate REACH reformulation deadline impacts and quick-commerce penetration curves in Indian metropolitan corridors.
Underlying measurement precision varies by segment; pharmacy-channel medicated volumes carry tighter precision than emerging natural-origin tiers where consumer switching behavior remains less established. Forecasts reflect documented assumptions on regulatory enforcement intensity and platform adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Nail Polish Remover Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Body Care Products Market
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
South Korea Dermocosmetics Market
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
Rice Shampoo Bar Market