
 Post-Shave Care Market | 2026-2036
Post-Shave Care Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Shave Care Market Analytics
ISO 16128 certification for natural and organic cosmetics is bifurcating the competitive landscape into compliant premium suppliers and conventional formulators. Procter & Gamble leverages its massive R&D infrastructure to validate claims through clinical testing protocols. Beiersdorf anchors its position in European pharmacies through Nivea Men's dermatological heritage and controlled distribution. Shiseido Company, Limited differentiates via Japanese fermentation-derived ingredients that command shelf space in Asian specialty retailers.
Post-shave care encompasses topical formulations applied after hair removal to restore skin barrier function, reduce irritation, and prevent folliculitis through active ingredients such as allantoin, witch hazel extract, or bisabolol at specified concentrations. Aftershave balm leads product type value pools due to higher per-unit pricing and repeat purchase frequency among consumers with sensitive skin. Alcohol-free formulations within the formulation segment show the fastest trajectory as regulatory scrutiny on drying agents intensifies and hydration claims require substantiation. Professional salons application remains a concentrated but slower-growing channel where bulk procurement and private-label substitution compress margins.
FDA oversight of cosmetic labeling in the United States and ECHA enforcement of REACH restricted substances in Europe jointly elevate compliance costs for synthetic fragrance and preservative systems. The EU Green Deal's chemical sustainability targets are forcing reformulation timelines across multinational portfolios. Stakeholders must monitor evolving patch-testing requirements and biobased content thresholds as these standards increasingly determine market access rather than merely product positioning.
Market Dynamics
Post-shave care formulation is splitting along dermatological certification lines, with ISO 16128 natural cosmetics standards and REACH chemical restrictions forcing simultaneous portfolio duplication for multinational suppliers serving divergent regulatory environments.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Biobased content mandates in Europe accelerate reformulation investments that spill into premium positioning elsewhere.
- Urban male skincare ritualization:Daily application frequency in United States, Germany, and China metro markets expands addressable volume beyond traditional occasional-use occasions.
- Fermentation-derived actives:Japanese biotechnology processes yield novel post-shave ingredients with substantiated barrier-repair claims that command specialty retail placement.
Market Restraints
- Synthetic preservative substitution costs:REACH Annex XVII restricted substances force replacement of paraben and formaldehyde-releasing systems with more expensive alternatives.
- Professional salon channel margin compression:Bulk procurement practices and private-label substitution in European and North American barbershop supply chains limit branded pricing power.
- Alcohol-based aftershave demand collapse:Drying agent aversion among sensitive-skin consumers strand legacy inventory and dedicated production assets.
Strategic Opportunities
- Pharmacy channel expansion in Germany:Dermatologist recommendation networks and reimbursement-adjacent positioning unlock premium pricing for clinically validated formulations.
- Cross-category skincare convergence:Post-shave balms incorporating SPF and anti-aging actives capture morning routine consolidation among time-constrained professionals.
- Subscription direct-to-consumer models:Replenishment automation builds predictable recurring revenue and reduces customer acquisition cost dependence on retail slotting.
Industry Challenges
- Clinical substantiation capability gaps:Smaller formulators lack in-house dermatological testing infrastructure to validate barrier-repair and anti-irritation claims against tightening advertising standards.
- Biobased raw material supply volatility:Agricultural input dependence for natural extracts creates formulation cost instability and batch-to-batch consistency management burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Shave Care Market |
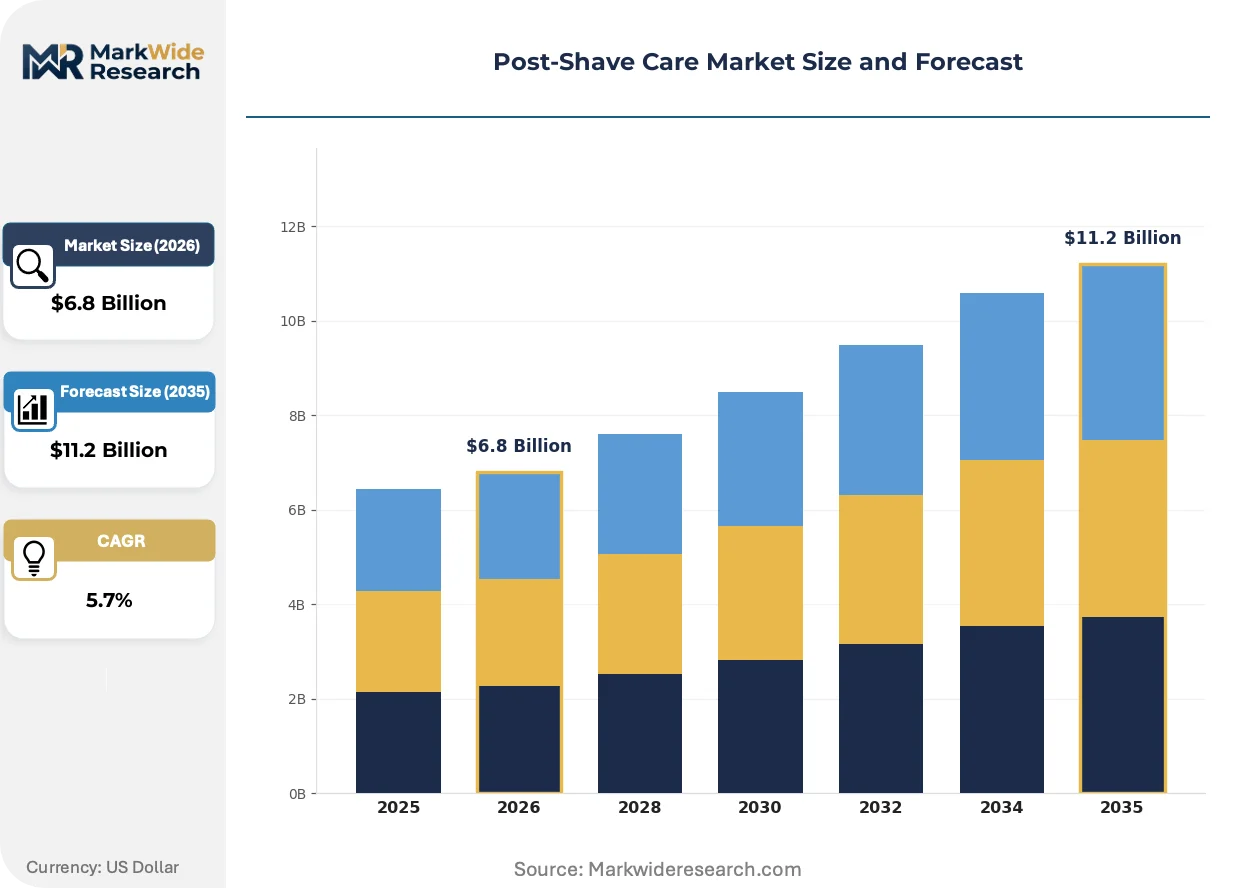
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aftershave Balm, Shaving Cream, Post-Shave Lotion, Sensitive Skin Gel Application: Men's Grooming, Skincare Routine, Professional Salons, Personal Care Formulation: Alcohol-Free, Natural Ingredients, Hydrating, Anti-Inflammatory Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Procter & Gamble, Unilever, L'Oréal, Beiersdorf, Colgate-Palmolive Company, Coty Inc., Edgewell Personal Care, Estée Lauder Companies Inc., Shiseido Company, Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Shave Care Market Evolving Landscape
Formulation science and distribution architecture are diverging simultaneously, with biotechnology-enabled ingredient platforms reshaping product development timelines while channel fragmentation reconfigures how formulations reach end users.
Japanese fermentation biotechnology is bifurcating the active ingredient supply base, with koji-derived compounds and yeast filtrates providing clinically demonstrable anti-inflammatory performance. Specialty retailers in Asian markets and prestige apothecaries in Western Europe are prioritizing these provenance-linked inputs. Conventional synthetic suppliers face compression in premium tiers while commodity natural extracts lose differentiation power.
REACH authorization requirements for fragrance allergens are forcing disclosure granularity that exposes proprietary formulation structures. Multinational suppliers must reformulate legacy portfolios or accept ingredient transparency that enables competitor reverse-engineering. German and French regulatory enforcement through ECHA and national competent authorities is tightest, compressing launch timelines for pan-European product introductions.
Barbershop service bundling is restructuring professional channel economics, with post-shave application becoming a ritualized finishing step rather than retail add-on sale. Independent grooming establishments in Brooklyn, London, and Tokyo are developing house-branded aftercare lines that displace third-party procurement. This vertical integration captures margin previously split between service provider and product supplier, most visible in high-rent urban districts where customer lifetime value justifies captive brand investment.
Post-Shave Care Market Segmentation
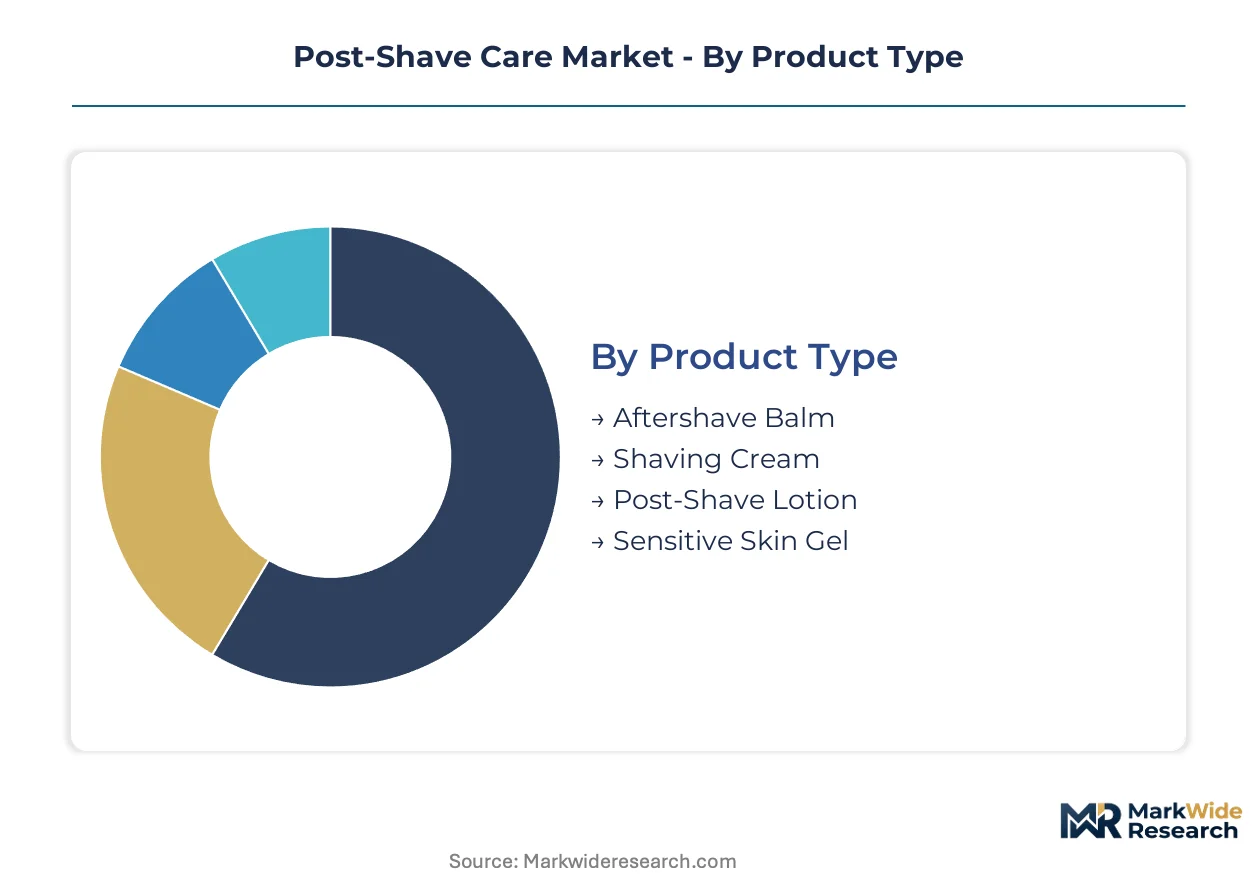
Post-shave care manufacturers must navigate four distinct segmentation axes simultaneously. Product type and formulation choices determine regulatory compliance pathways, while application context and distribution channel selection govern margin capture and brand positioning economics.
Product Type:
Aftershave balm and shaving cream concentrate manufacturing investment in the United States and Germany, whereas sensitive skin gel production serves export-oriented Asian markets through Japanese fermentation technology platforms.
- Aftershave Balm:Emulsion-based formulations containing allantoin, bisabolol, or witch hazel extract at therapeutic concentrations. Demand concentrates among urban professionals in United States metro markets where dermatologist-tested claims support premium pricing and subscription replenishment models.
- Shaving Cream:Lathering surfactant systems with stearic acid or coconut oil bases that precede blade contact. German pharmacy channels and Chinese e-commerce platforms drive volume, with ISO 16128-certified natural variants commanding shelf space in European specialty retailers.
- Post-Shave Lotion:Lightweight fluid formulations for rapid absorption. Asian male consumers in Tokyo and Seoul favor lotion textures over heavier balms in humid climates.
- Sensitive Skin Gel:Hydrocolloid-based cooling systems with aloe vera or centella asiatica. Japanese koji-derived actives differentiate premium tiers in domestic and export markets.
Aftershave balm commands the established base. The steepest expansion runs through sensitive skin gel.
Application:
Cost tier stratification separates ritualized daily use from occasional professional service occasions, with men's grooming and skincare routine applications absorbing formulation R&D investment while salon channels face margin compression.
- Men's Grooming:Integrated morning routine products combining post-shave care with SPF or anti-aging actives. United States and Chinese metro markets show highest adoption of multifunctional formats among time-constrained professionals.
- Skincare Routine:Dermatological positioning through barrier-repair claims and clinical testing protocols. German pharmacy reimbursement-adjacent placement and Japanese fermentation-derived ingredient stories support premium tier pricing.
- Professional Salons:Bulk procurement environments in Brooklyn, London, and Tokyo barbershops where house-branded lines displace third-party suppliers.
- Personal Care:Mass-market accessibility through supermarket and online retail channels with price-sensitive volume orientation.
Men's grooming anchors manufacturer revenue. Skincare routine applications are climbing the fastest as clinical substantiation requirements tighten.
Formulation:
REACH Annex XVII enforcement and EU Green Deal biobased mandates are forcing parallel portfolio development, with alcohol-free and natural ingredient lines requiring separate supply chains from conventional formulations.
- Alcohol-Free:Glycerin and hyaluronic acid-based hydration systems replacing ethanol-denatured legacy formats. Regulatory scrutiny on drying agents through ECHA and FDA labeling oversight accelerates conversion in Europe and the United States.
- Natural Ingredients:ISO 16128-compliant botanical extracts and agricultural inputs. Supply volatility from weather-dependent raw material sourcing creates batch consistency management burdens for formulators.
- Hydrating:Ceramide and niacinamide-enriched barrier-repair formulations with substantiated moisture retention claims.
- Anti-Inflammatory:Bisabolol, allantoin, or Japanese yeast filtrate actives targeting folliculitis prevention and irritation reduction.
Natural ingredients command the established base. The steepest expansion runs through alcohol-free as regulatory pressure intensifies.
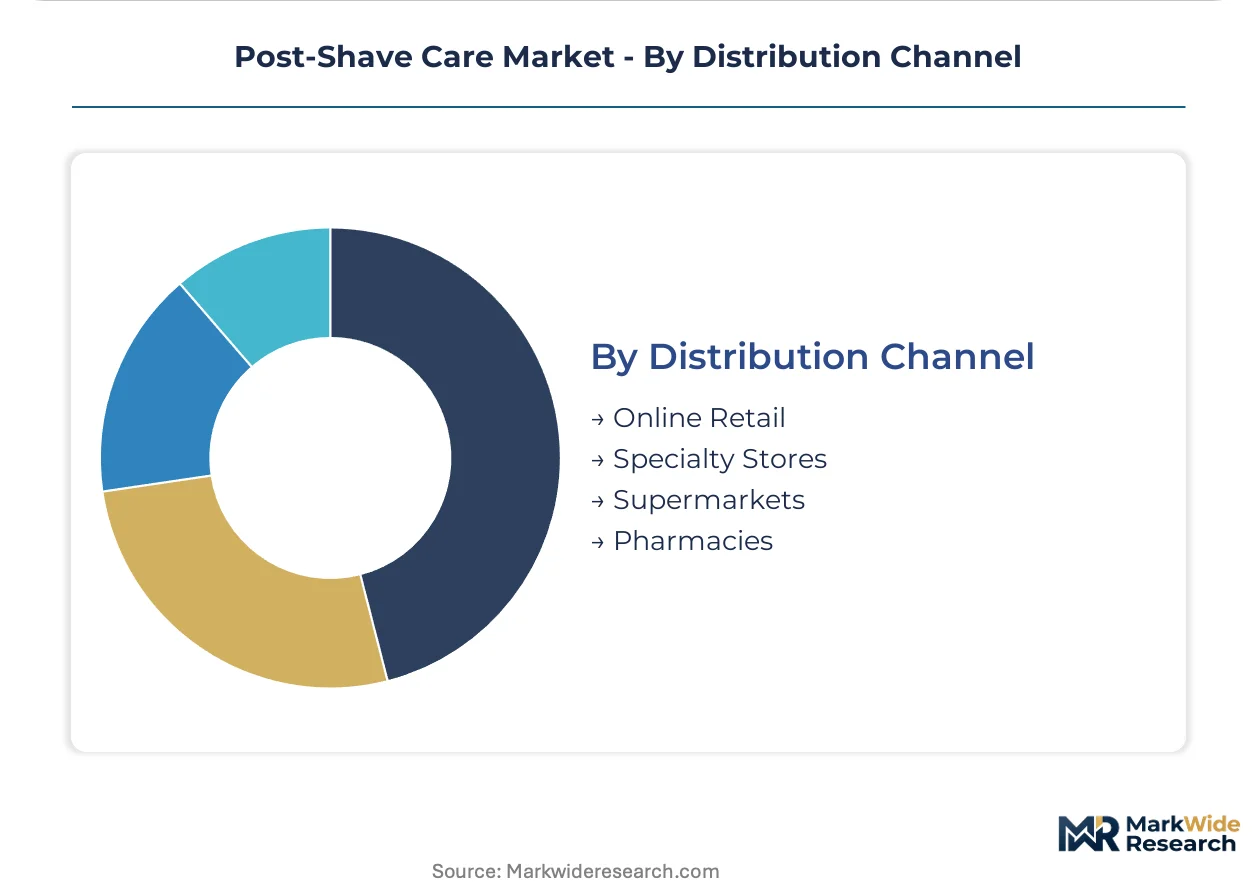
Distribution Channel:
Customer acquisition economics favor subscription direct-to-consumer models, though pharmacy and specialty store channels retain premium positioning power through recommendation networks and tactile evaluation.
- Online Retail:Replenishment automation and algorithmic personalization reducing customer acquisition cost dependence. Chinese e-commerce platforms and United States subscription services concentrate growth investment.
- Specialty Stores:Curated apothecary environments in Paris, Tokyo, and New York where provenance-linked Japanese fermentation ingredients justify shelf space premiums.
- Supermarkets:Mass-market volume throughput with compressed margins and private-label substitution pressure.
- Pharmacies:German and French dermatologist recommendation networks enabling clinically validated formulation pricing power.
Pharmacies command the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal chemical sustainability targets and REACH Annex XVII enforcement are reshaping formulation requirements across key markets. FDA labeling oversight in the United States and Japan's METI guidelines on biobased content are creating parallel compliance pathways that multinational suppliers must navigate simultaneously.
United States
Urban male professionals in New York and Los Angeles metro areas are driving daily application frequency for post-shave balms with SPF integration. FDA oversight of cosmetic labeling mandates substantiation for hydration and barrier-repair claims, elevating compliance costs for synthetic fragrance systems. Brooklyn barbershops are developing house-branded aftercare lines that displace third-party suppliers through vertical integration.
Germany
Pharmacy channel expansion anchors demand, with dermatologist recommendation networks enabling premium pricing for clinically validated formulations. ECHA enforcement of REACH restricted substances forces replacement of paraben and formaldehyde-releasing preservative systems with costlier alternatives. The Eindhoven Region and North Rhine-Westphalia concentrate fermentation technology R&D investment for natural cosmetic actives.
China
SAMR and NMPA regulations on cosmetic ingredient disclosure are tightening advertising standards for post-shave products claiming anti-inflammatory benefits. Yangtze River Delta manufacturing clusters, particularly Shanghai and surrounding provinces, dominate domestic production of sensitive skin gel formulations. E-commerce platforms concentrate subscription service growth investment among time-constrained professionals in Beijing and Shenzhen.
Japan
METI guidelines on biobased content thresholds are accelerating adoption of koji-derived and yeast filtrate actives in domestic formulations. Tokyo and Osaka specialty retailers prioritize provenance-linked fermentation ingredients that command shelf space premiums over commodity natural extracts. Kanto region biotechnology platforms yield novel barrier-repair compounds with clinically demonstrable performance.
United Kingdom
London and Southeast England grooming establishments are adopting ritualized post-shave application as a service bundling strategy. MHRA alignment with REACH authorization requirements for fragrance allergens exposes proprietary formulation structures to competitor reverse-engineering. Midlands-based formulators face compressed margins from supermarket private-label substitution pressure.
Post-Shave Care Market Competitive Landscape
Listed leaders compete with private specialists across certification and distribution dimensions, creating a tiered structure where scale advantages meet agility in regulatory compliance. The market splits between multinational consumer goods conglomerates with massive R&D infrastructure and regional specialists leveraging dermatological heritage or biotechnology platforms. Three archetypes dominate: clinical validators with pharmacy channel control, fermentation technology specialists with Asian provenance stories, and mass-market operators with subscription direct-to-consumer automation. Competitive moves concentrate on portfolio diversification into alcohol-free and natural ingredient lines, plus geographic expansion through e-commerce platform partnerships.
Within the clinical validator tier, Procter & Gamble and Beiersdorf exemplify divergent approaches to dermatological positioning. Procter & Gamble leverages its Cincinnati-based scale to validate claims through extensive clinical testing protocols. Beiersdorf anchors its Hamburg GmbH structure in European pharmacy networks through controlled distribution heritage. Shiseido Company, Limited occupies a distinct position among fermentation technology specialists, with its Tokyo-based platform representing Japanese biotechnology-derived ingredient differentiation in Asian specialty retail channels.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| L'Oréal |
| Beiersdorf |
| Colgate-Palmolive Company |
| Coty Inc. |
| Edgewell Personal Care |
| Estée Lauder Companies Inc. |
| Shiseido Company, Limited |
| Others |
Value Network & Pricing Analysis
Ninety-day reformulation cycles for REACH-compliant preservatives compress margin buffers for multinational suppliers while amplifying pricing power for ISO 16128-certified natural ingredient specialists. Inventory velocity diverges sharply between German pharmacy channels with extended payment terms and Chinese e-commerce platforms demanding just-in-time replenishment.
Pricing Analysis
Certification level creates the primary spread between premium tiers, with ISO 16128-compliant formulations commanding shelf space premiums in European specialty retail against conventional synthetic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects dermatological validation intensity, subscription automation, and raw material provenance. Pricing pressure stems from private-label substitution in supermarket channels where bulk procurement erodes branded pricing power. Professional barbershops in Brooklyn and London show highest price sensitivity due to house-brand vertical integration, while German pharmacy consumers absorb premiums for clinically substantiated barrier-repair claims.
Supply Chain Analysis
Germany and Japan anchor fermentation technology R&D for koji-derived actives, while China concentrates sensitive skin gel manufacturing in Yangtze River Delta clusters. Biobased raw material sourcing draws from agricultural inputs subject to weather-dependent volatility, particularly for centella asiatica and aloe vera extracts. Single-source vulnerability concentrates in Japanese yeast filtrate suppliers serving premium Asian specialty retail channels. Distribution runs through pharmacy networks in Germany, subscription direct-to-consumer platforms in the United States, and e-commerce marketplaces in China with divergent margin capture economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
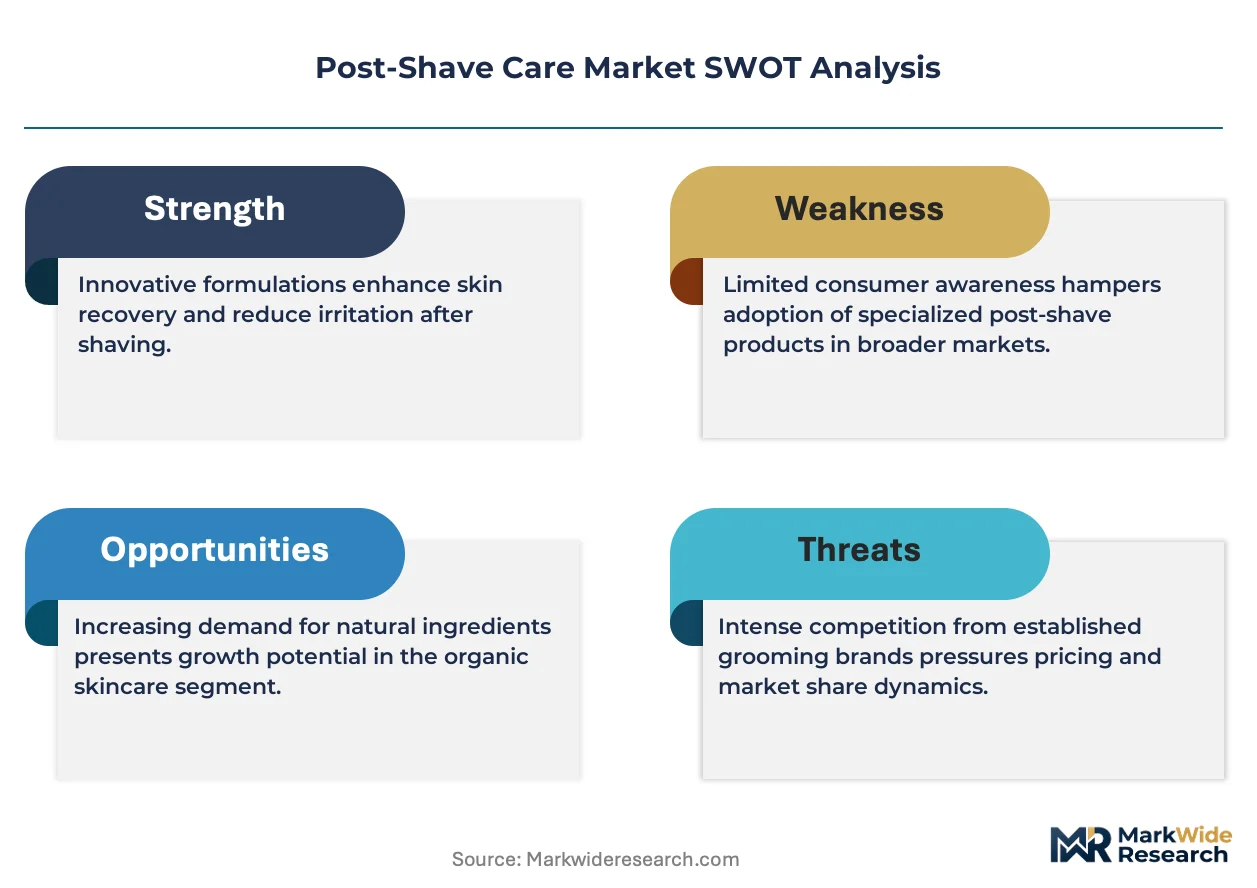
Incumbents face substitution pressure from vertically integrated barbershop house brands capturing margin previously split between service and product suppliers.
For Market Incumbents: Shield pharmacy channel positioning through accelerated ISO 16128 certification investment before REACH Annex XVII enforcement tightens further. Deepen captive supply of fermentation-derived actives via partnerships with Kanto region biotechnology platforms to secure ingredient differentiation against emerging Japanese specialists. Control distribution through exclusive dermatologist recommendation networks in Germany and France where reimbursement-adjacent placement sustains premium pricing. For New Entrants and Emerging Players: Subscription replenishment automation gaps in the United States metro markets offer white-space entry points where incumbents rely on legacy retail slotting. Target alcohol-free formulation segments in European markets where regulatory pressure outpaces incumbent reformulation timelines. Pursue direct-to-consumer launch with algorithmic personalization to reduce customer acquisition cost dependence against established brand recognition. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory divergence between REACH-compliant Europe and FDA-oversight United States forces portfolio duplication that rewards agile mid-cap formulators. Acquisition focus centers on ISO 16128-certified specialists with proven pharmacy channel access and in-house dermatological testing infrastructure. Watch ECHA enforcement intensity against fragrance allergens as the signal for margin compression timing in synthetic-dependent legacy portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 16128 Certification Investment | REACH and EU Green Deal compliance unlocks premium pharmacy channel access across German and French markets. |
| Fermentation Technology Partnership | Koji-derived active sourcing from Japanese biotechnology platforms differentiates barrier-repair claims in Asian specialty retail. |
| Subscription Direct-to-Consumer Launch | Algorithmic personalization reduces acquisition costs against retail slotting dependence in United States metro markets. |
| Pharmacy Channel Expansion | Dermatologist recommendation networks in Germany enable clinically validated pricing power adjacent to reimbursement systems. |
| Alcohol-Free Portfolio Conversion | Regulatory scrutiny on drying agents through ECHA and FDA labeling mandates accelerates demand capture from legacy format collapse. |
Research Methodology
Desk research of regulatory filings through ECHA and FDA databases, trade customs records, and specialty retail audit data preceded structured interviews with brand managers at multinational consumer goods conglomerates, pharmacy category buyers in Germany and France, fermentation technology R&D directors in Japan, and subscription platform operators in the United States. Primary fieldwork with barbershop owners in Brooklyn, London, and Tokyo captured vertical integration trends displacing third-party procurement. Bottom-up volume modeling across product type, formulation, and distribution channel segments triangulated against top-down macroeconomic indicators.
Variance decomposition isolates regulatory compliance cost shocks, raw material price volatility, and channel mix shifts as primary forecast drivers across the projection horizon. Segmentation dimensions modeled include product type hierarchy, certification tier, application context, and geographic regulatory cluster. CAGRs derive from iterative convergence of historical trajectory analysis and scenario-weighted forward projection. Industry-specific inputs incorporate REACH authorization timelines for fragrance allergens, METI biobased content threshold evolution, and SAMR disclosure requirement tightening in China.
Material uncertainties — agricultural input weather disruption, ECHA enforcement intensity variation, and barbershop vertical integration acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and consumer preference stability toward alcohol-free and natural ingredient formulations. Recalibration cycles align with material shifts in REACH Annex XVII updates, FDA labeling guidance revisions, and biobased content mandate implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Personal Care Products Market
Beauty & Personal Care
Germany Lip Care Products Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
Rice Shampoo Bar Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
Coffee Beauty Products Market
Beauty & Personal Care
Deodorant & Anti-Perspirant Market
Beauty & Personal Care
Bath and Shower Products Market
Beauty & Personal Care
South Korea Beauty and Personal Care Products Market
Beauty & Personal Care
South America Hair Styling Products Market