
 Deodorant Roll-Ons Market | 2026-2036
Deodorant Roll-Ons Market Size, Share, and Industry Trends Forecast 2026-2036
Deodorant Roll-Ons Market Outlook
A shift from outsourced fragrance compounding toward in-house botanical extraction is recalibrating supply economics for roll-on manufacturers. Henkel AG & Co. KGaA leverages captive laboratories in Düsseldorf to control alcohol-free formulation pipelines. Unilever PLC anchors its European production network through centralized mixing facilities in the Netherlands. Procter & Gamble competes via scale advantages in antiperspirant active sourcing across North American and Asian plants.
Deodorant roll-ons are liquid or semi-liquid personal hygiene products dispensed through a rotating ball mechanism, typically containing aluminum salts, emollients, and antimicrobial agents in a water or silicone base, designed to reduce perspiration and neutralize body odor. The product category serves daily consumer hygiene routines across mass retail and pharmacy channels. Natural formulations now command premium shelf positioning as EU REACH compliance costs squeeze conventional paraben-based lines. Antiperspirant variants still dominate volume throughput in supermarket distribution, though alcohol-free segments are gaining faster velocity through pharmacy and online retail channels. Online retail itself is restructuring margin pools by disintermediating traditional wholesale markups for specialty and eco-friendly sub-brands.
EU REACH and the EU Green Deal chemical sustainability framework constrain raw material sourcing for European manufacturers, while FDA monograph standards govern antiperspirant active concentrations in the United States. These dual regulatory architectures elevate compliance spending but simultaneously create barriers against low-cost import competition. Stakeholders must monitor evolving biodegradability certifications and state-level chemical disclosure laws as decisive filters for market access and consumer trust.
Market Dynamics
EU REACH chemical disclosure mandates and the EU Green Deal's biodegradability requirements are forcing reformulation across aluminum salt and paraben-based product lines, compressing legacy supply economics while elevating compliance costs for conventional manufacturers.
Growth Catalysts
- EU Green Deal chemical footprint frameworks:Mandatory disclosure protocols accelerate consumer migration toward certified natural and aluminum-free variants, expanding premium shelf space in pharmacy channels.
- Young adult urban demographics:Concentrated demand in metropolitan centers drives velocity for portable, travel-format roll-ons with extended wear claims.
- Botanical extraction capabilities:In-house captive laboratories enable manufacturers to bypass fragrance compounders and capture margin from alcohol-free formulation pipelines.
Market Restraints
- Aluminum salt input volatility:Antiperspirant active sourcing faces price instability from concentrated North American and Asian chemical suppliers.
- REACH compliance cost escalation:Registration, evaluation, and authorization expenses for legacy paraben-based formulations squeeze mid-tier brand economics.
- Technical limitation in natural efficacy:Plant-derived antimicrobial agents deliver shorter protection windows than synthetic alternatives, constraining clinical claim substantiation.
Strategic Opportunities
- Pharmacy channel expansion:Dermocosmetic positioning and clinician endorsement unlock professional recommendation networks for sensitive-skin variants.
- Online retail disintermediation:Direct-to-consumer platforms bypass wholesale markups and enable subscription models for specialty eco-friendly sub-brands.
- CSRD-aligned sustainability reporting:Corporate sustainability disclosure requirements create procurement preference for suppliers with verified biodegradability certifications.
Industry Challenges
- Formulation chemist scarcity:Talent gaps in aluminum-free antiperspirant chemistry delay pipeline development for next-generation efficacy claims.
- Certification timeline compression:EU Ecolabel and Nordic Swan accreditation processes extend go-to-market schedules by 8-14 months for natural-positioned launches.
- Supply chain reconfiguration friction:Migration from synthetic to botanical inputs requires new supplier qualification protocols and quality control infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deodorant Roll-Ons Market |
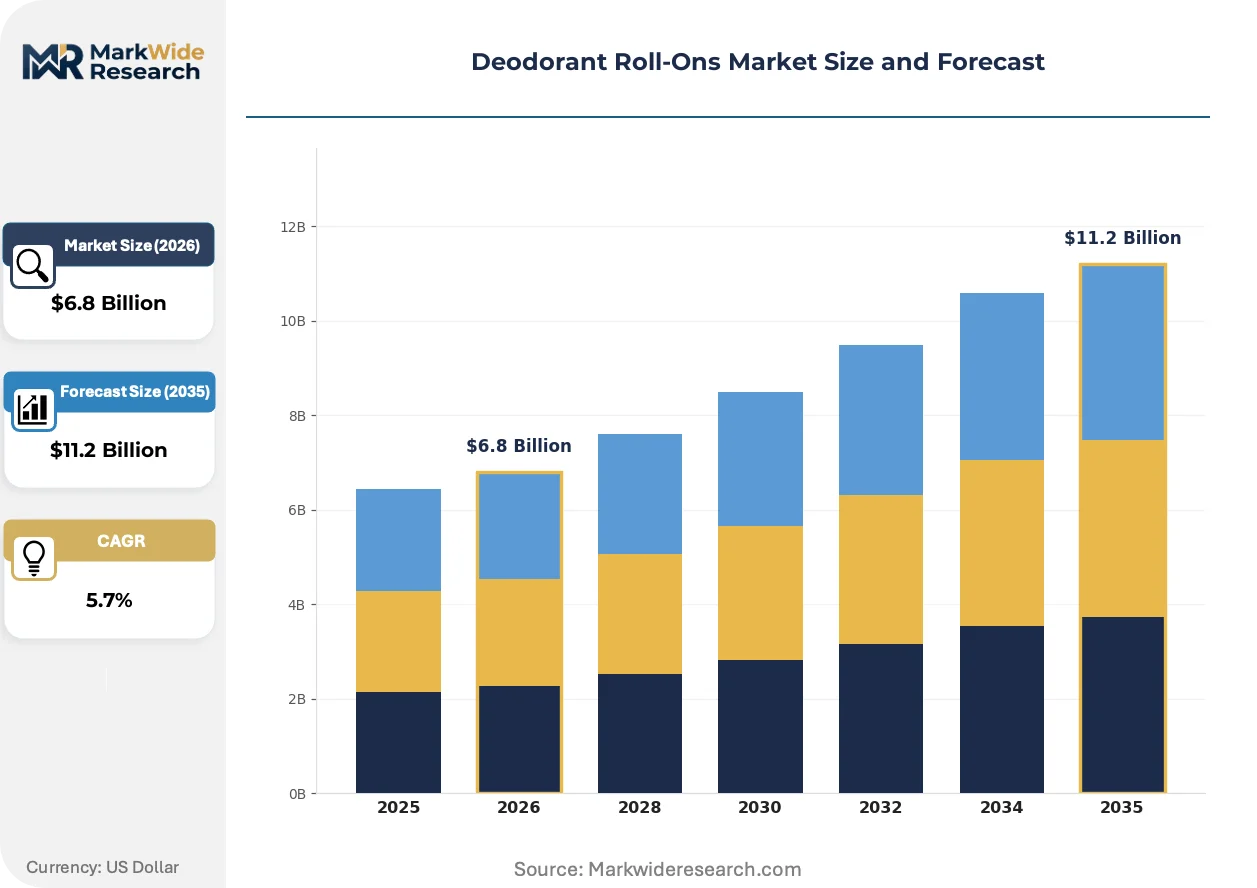
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Antiperspirant, Scented, Unscented Formulation: Alcohol-Free, Herbal, Eco-Friendly, Paraben-Free Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies Target Demographic: Women, Men, Unisex, Teens |
| Companies Covered | Henkel AG & Co. KGaA, Kao Corporation, Unilever PLC, L'Oreal, Church & Dwight, Procter & Gamble, Colgate-Palmolive, Lion Corporation, Beiersdorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deodorant Roll-Ons Market Strategic Shifts
Reformulation chemistry and channel restructuring are converging to redefine competitive advantage, with regulatory pressure acting as the primary accelerant of product architecture change.
Encapsulated fragrance release systems are electrifying the sensory experience architecture of premium roll-ons, enabling timed scent diffusion across 24-hour wear claims. Urban professional buyers in Germany and France are adopting these formats at accelerating velocity through pharmacy and selective distribution. This technology is electrifying margin structures by justifying 40-60% price premiums over standard emulsion bases.
REACH authorization restrictions on cyclosiloxanes (D4/D5/D6) are eliminating silicone carrier fluids from European formulations, forcing migration toward water-based and natural oil suspensions. Manufacturers with captive extraction capabilities in the Netherlands and Germany are capturing share as importers face compliance barriers. Antiperspirant variants targeting mass retail are most affected, with reformulation costs passed through to shelf prices.
Subscription-based replenishment models are restructuring purchase behavior for eco-conscious households, displacing supermarket stock-up cycles with algorithmic delivery timing. Specialty sub-brands with biodegradable certifications are capturing this shift through direct channels in the United Kingdom and Scandinavian markets. Young adult urban renters demonstrate highest adoption rates, driven by convenience positioning and packaging waste reduction claims.
Deodorant Roll-Ons Market Segmentation
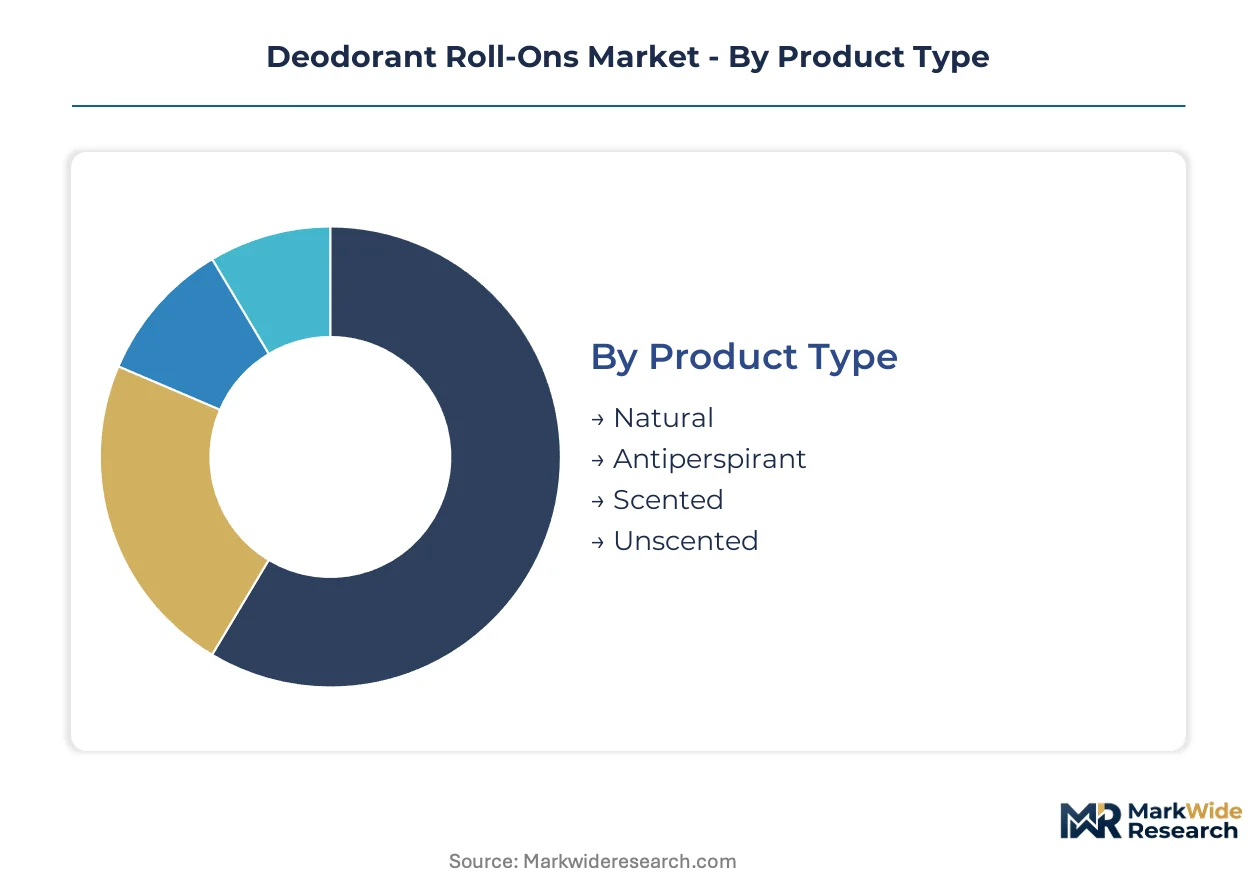
Deodorant roll-on segmentation reveals divergent margin structures across formulation chemistry and channel access. Volume throughput concentrates in mass-market antiperspirant variants, while premium capture flows through pharmacy-positioned natural lines with biodegradability certifications.
Product Type:
Volume leadership sits with clinically-positioned antiperspirant formats, while premium shelf space migrates toward aluminum-free and botanical-positioned variants responding to EU REACH disclosure mandates.
- Natural:Aluminum-free formulations utilizing plant-derived antimicrobial agents and essential oil suspensions. Demand concentrates in German and French pharmacy channels where EU Green Deal compliance elevates shelf positioning for certified biodegradable variants.
- Antiperspirant:Aluminum salt-based formulations delivering clinically-substantiated perspiration reduction through eccrine gland blocking. Volume throughput dominates supermarket distribution in the United Kingdom and Germany, though reformulation costs from REACH restrictions compress margin structures for legacy lines.
- Scented:Fragrance-enhanced emulsions incorporating synthetic or botanical aromatic compounds for extended wear claims.
- Unscented:Fragrance-free formulations targeting sensitive-skin demographics and clinical endorsement networks.
Mature deployment sits with Antiperspirant. Newer deployment is concentrated in Natural.
Formulation:
Alcohol-free chemistry commands dermocosmetic positioning, while paraben-free migration accelerates under ECHA authorization pressure.
- Alcohol-Free:Water and silicone-based carriers eliminating ethanol to reduce irritation potential. Captive extraction capabilities in Düsseldorf and Dutch mixing facilities enable manufacturers to bypass fragrance compounders and control margin pools for sensitive-skin variants.
- Herbal:Botanical extraction-based suspensions utilizing tea tree, witch hazel, or sage-derived actives. Young adult urban adopters in London and Paris drive velocity through online retail channels seeking packaging waste reduction claims.
- Eco-Friendly:Biodegradable-certified formulations meeting Nordic Swan and EU Ecolabel standards.
- Paraben-Free:Preservative systems utilizing phenoxyethanol or sodium benzoate alternatives to conventional parabens.
Supply concentration favors Alcohol-Free manufacturing. Certification complexity is expanding fastest for Eco-Friendly.
Distribution Channel:
Supermarket throughput anchors volume economics, while disintermediated direct channels capture subscription-driven premium migration.
- Online Retail:Algorithmic replenishment platforms bypassing wholesale markups for specialty sub-brands. Young adult urban renters in Scandinavian markets demonstrate highest adoption rates for biodegradable-certified subscription models with convenience positioning.
- Supermarkets:Mass retail distribution capturing stock-up purchase cycles for antiperspirant variants. Shelf space allocation in Tesco and Carrefour networks across the United Kingdom and France prioritizes volume throughput over margin capture.
- Specialty Stores:Selective distribution for premium and travel-format positioning.
- Pharmacies:Clinician endorsement networks unlocking professional recommendation for sensitive-skin and dermocosmetic variants.
Margin extraction runs deepest through Online Retail. Infrastructure investment is concentrating in Pharmacies.
Target Demographic:
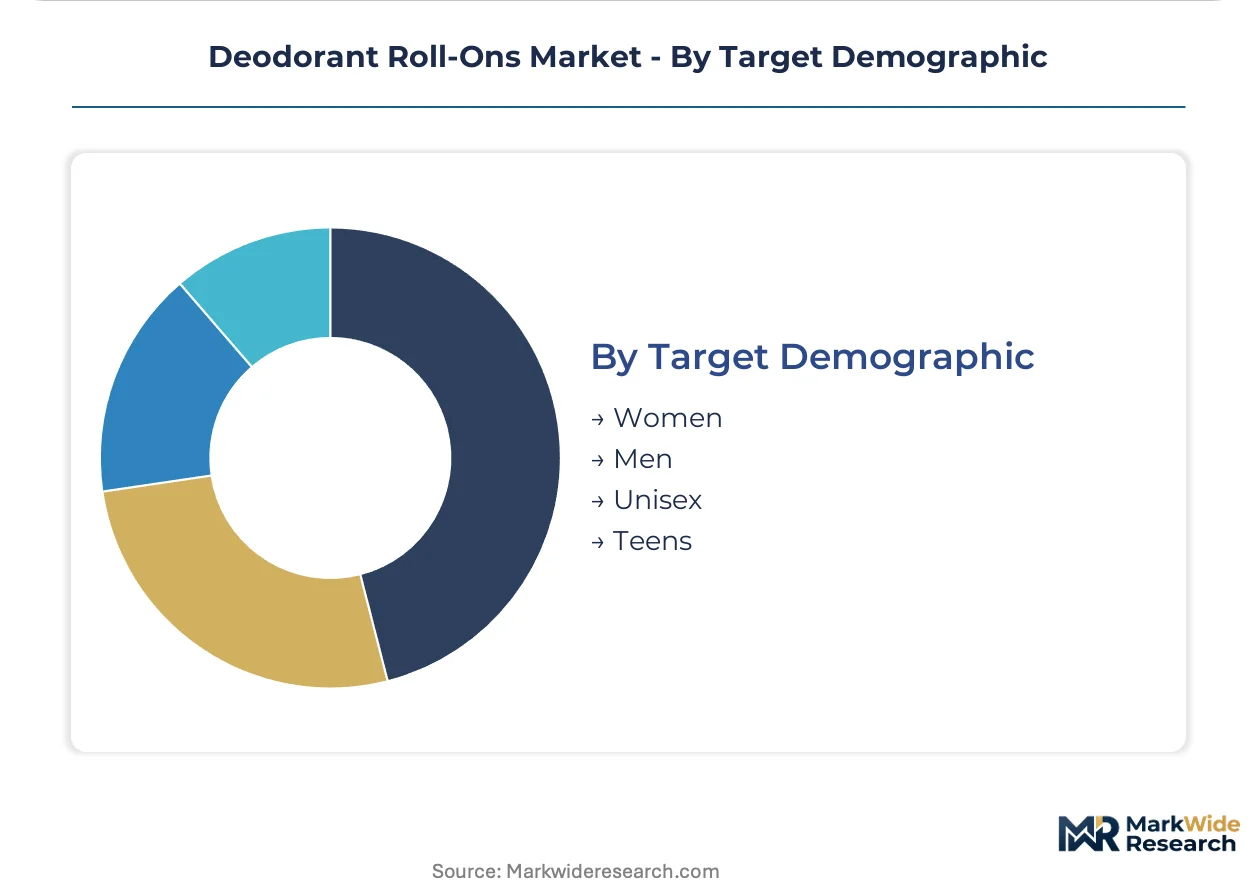
Women's segments dominate historical revenue, while unisex positioning captures format-neutral urban professional demand.
- Women:Historically concentrated demand for scented and clinical-care variants with extended wear claims. Pharmacy channel penetration in Germany supports premium capture through dermocosmetic endorsement networks.
- Men:Sports and active-positioned formulations with higher aluminum salt concentrations for perspiration control. Supermarket distribution in the United Kingdom favors larger-format packaging with value-oriented pricing.
- Unisex:Neutral fragrance profiles and minimalist packaging design targeting shared household purchase.
- Teens:Entry-level price positioning with gentle formulation chemistry for first-time category adoption.
Established revenue concentration sits with Women. Demographic expansion is climbing the fastest in Unisex.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum salt feedstock availability and captive botanical extraction infrastructure anchor demand concentration across specific national markets. Regulatory divergence between EU REACH frameworks and FDA monograph standards creates distinct competitive zones. Germany, France, the United Kingdom, the United States, and Japan represent the primary national concentrations where formulation chemistry and channel access determine market position.
Germany
Pharmacy channel penetration and dermocosmetic endorsement networks drive premium capture for sensitive-skin variants. EU REACH authorization restrictions on cyclosiloxanes force rapid reformulation toward water-based suspensions. Captive laboratories in Düsseldorf enable manufacturers to control alcohol-free formulation pipelines and bypass external fragrance compounders.
France
Urban professional adoption of encapsulated fragrance release systems accelerates through selective distribution channels. ANSM oversight of cosmetic ingredient safety elevates compliance requirements for aluminum salt concentrations. Paris and Lyon anchor demand for premium travel-format roll-ons with extended wear claims and minimalist packaging aesthetics.
United Kingdom
Subscription-based replenishment models capture eco-conscious households through algorithmic delivery timing. The UK's post-EU regulatory alignment creates uncertainty for REACH-dependent supply chains. London's young adult urban renters demonstrate highest adoption rates for biodegradable-certified direct-to-consumer brands with packaging waste reduction positioning.
United States
FDA monograph standards govern antiperspirant active concentrations, creating distinct formulation requirements from European counterparts. Mass retail distribution through supermarket networks prioritizes volume throughput for aluminum salt-based clinical variants. North American chemical suppliers concentrate antiperspirant active sourcing, exposing manufacturers to input price volatility.
Japan
PMDA cosmetic safety standards and METI chemical management frameworks constrain formulation choices for imported products. Unisex positioning and neutral fragrance profiles capture shared household purchase behavior in metropolitan Tokyo and Osaka. Local manufacturers emphasize compact, travel-friendly formats aligned with commuter culture and workplace hygiene norms.
Deodorant Roll-Ons Market Competitive Environment
Backward integration into captive botanical extraction dominates the current landscape as manufacturers seek margin control over alcohol-free pipelines. The vendor base concentrates around three strategic tiers: multinational FMCG conglomerates with centralized mixing facilities, mid-sized dermocosmetic specialists with pharmacy channel access, and emerging direct-to-consumer brands leveraging subscription economics. Two competitive moves define current positioning: vertical control over fragrance supply chains and disintermediation of wholesale markups through online retail platforms.
Among European-based manufacturers, Henkel AG & Co. KGaA exemplifies the captive laboratory archetype with Düsseldorf-based formulation control. Unilever PLC anchors scale-driven production through Netherlands-centered mixing networks. Procter & Gamble occupies a position representing North American supply concentration in antiperspirant active sourcing. These three entities collectively illustrate the divergence between in-house extraction capabilities and centralized manufacturing scale as alternative competitive foundations.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Kao Corporation |
| Unilever PLC |
| L'Oreal |
| Church & Dwight |
| Procter & Gamble |
| Colgate-Palmolive |
| Lion Corporation |
| Beiersdorf AG |
| Others |
Value Chain & Pricing Dynamics
Young adult urban renters in London and Scandinavian capitals anchor demand for subscription-priced biodegradable roll-ons, locking in algorithmic replenishment models that bypass wholesale markups and compress shelf-price elasticity for conventional supermarket formats.
Pricing Analysis
Warranty-equivalent satisfaction guarantees now bundle with premium pharmacy-positioned roll-ons, unbundling from mass-market antiperspirant lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and captive extraction origin. Cost compression in aluminum-free segments is intensifying because REACH compliance expenses cascade through reformulation pipelines. Supermarket buyers exhibit highest price sensitivity, while pharmacy-channel adopters of dermocosmetic variants accept 40-60% premiums for encapsulated fragrance release systems.
Supply Chain Analysis
Formulation chemist scarcity in the Netherlands and Germany constrains captive laboratory expansion for alcohol-free pipelines. Supply concentrates in Dutch mixing facilities and Düsseldorf extraction centers, with North American chemical suppliers feeding aluminum salt dependencies. Single-source vulnerability sits with concentrated antiperspirant active sourcing from Asian and North American chemical plants. Distribution runs through centralized European production networks serving pharmacy and supermarket channels, with direct-to-consumer platforms disintermediating wholesale layers for subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Botanical extraction capacity bottlenecks prop pricing power for manufacturers with captive laboratories, constraining supply response to EU Green Deal-mandated reformulation demand.
For Market Incumbents: Deploy captive extraction capabilities to defend margin pools against REACH-authorized import competition. Accelerate Nordic Swan and EU Ecolabel certification timelines for natural-positioned lines to preempt mid-tier brand encroachment. Consolidate pharmacy channel relationships in Germany and France before clinician endorsement networks saturate. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for biodegradable-certified sub-brands targeting young adult urban renters in London and Scandinavian markets. White-space sits with travel-format aluminum-free variants for metropolitan professional commuters. Algorithmic replenishment timing anchored to household consumption patterns unlocks recurring revenue without wholesale margin sacrifice. For Investors and Strategic Acquirers: The window for entry favors mid-sized dermocosmetic specialists with pharmacy channel access and pending biodegradability certifications. Long-term viability hinges on backward integration into botanical extraction rather than reliance on fragrance compounders. Watch ECHA authorization expansions beyond cyclosiloxanes as the inflection signal for accelerated legacy line obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Botanical Extraction Investment | Henkel's Düsseldorf laboratories demonstrate margin control over alcohol-free formulation pipelines. |
| Biodegradability Certification Acceleration | Nordic Swan and EU Ecolabel accreditation unlocks pharmacy shelf positioning and premium pricing. |
| Direct-to-Consumer Platform Launch | Algorithmic subscription models bypass Tesco and Carrefour wholesale markups for eco-conscious households. |
| Pharmacy Channel Expansion | Clinician endorsement networks in Germany and France professionalize sensitive-skin variant recommendation. |
| Aluminum-Free Reformulation Pipeline | REACH authorization pressure on aluminum salts forces next-generation antiperspirant chemistry development. |
Study Parameters
Multi-period observation of EU REACH authorization timelines and EU Green Deal compliance cost trajectories anchored the trend analysis, supplemented by interviews with formulation chemists, pharmacy category buyers, fragrance compounder procurement leads, and dermocosmetic brand managers. Secondary validation drew from ECHA substance restriction databases, Nordic Swan certification registries, customs import records for aluminum salt feedstocks, and Nielsen retail audit data for European personal care channels. Bottom-up volume triangulation across product type, formulation chemistry, and distribution channel converged with top-down market sizing.
Input-output matrices mapped aluminum salt input volatility, captive extraction capacity expansion, and certification timeline compression against demand elasticity across pharmacy, supermarket, and online retail channels. Segmentation dimensions modeled include product type, formulation chemistry, distribution channel, and target demographic, with CAGRs derived from regression analysis of historical volume throughput and regulatory-driven substitution elasticities. Industry-specific forecast inputs incorporated Ecolabel adoption curves and clinician endorsement network penetration rates.
The model holds under stable REACH authorization schedules and continued EU Green Deal enforcement; deviation in ECHA expansion of restricted substance lists or suspension of biodegradability certification programs would shift volume trajectories and margin pool distributions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
United Kingdom Hair Care Market
Beauty & Personal Care
Male Grooming Products Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Rice Shampoo Bar Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
E-Pharmacy Beauty and Personal Care (BPC) Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
Eyelash Curler Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
Europe Beauty and Personal Care Products Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Face Oil Market