
 Salon Service Market | 2026-2036
Salon Service Market Size, Share, and Industry Trends Forecast 2026-2036
Salon Service Market Intelligence
Plant-based keratin alternatives are repositioning service economics across mid-tier salon chains. Great Clips leverages its franchise scale to standardize botanical treatment protocols at thousands of locations. Regis Corporation anchors its portfolio through salon-brand retail integration, while European Wax Center specializes in single-service dominance with waxing-centric studio formats.
Salon services encompass professional hair, nail, skin, and cosmetic treatments delivered in licensed commercial settings using regulated products and specialized equipment. Service delivery requires cosmetology-licensed practitioners operating under state board hygiene protocols, with chemical processing services subject to ventilation and disposal standards. Hair styling and nail care command the largest revenue pools, though skin treatments capture superior per-visit margins as consumers prioritize facial aesthetics. Men now represent the fastest-expanding customer type, prompting dedicated barber-studio concepts and male-focused product lines. Mobile services are gaining structural traction by eliminating real estate overhead and reaching suburban markets with limited salon density.
State cosmetology boards enforce practitioner licensing and sanitation protocols that shape market entry barriers across the United States. OSHA workplace chemical exposure limits and FDA cosmetic ingredient regulations constrain product formulation choices, while the EU REACH framework restricts certain hair dye precursors imported through multinational product lines. Stakeholders must monitor clean beauty certification standards and franchise disclosure rule evolution as these frameworks increasingly determine competitive access and consumer trust.
Market Dynamics
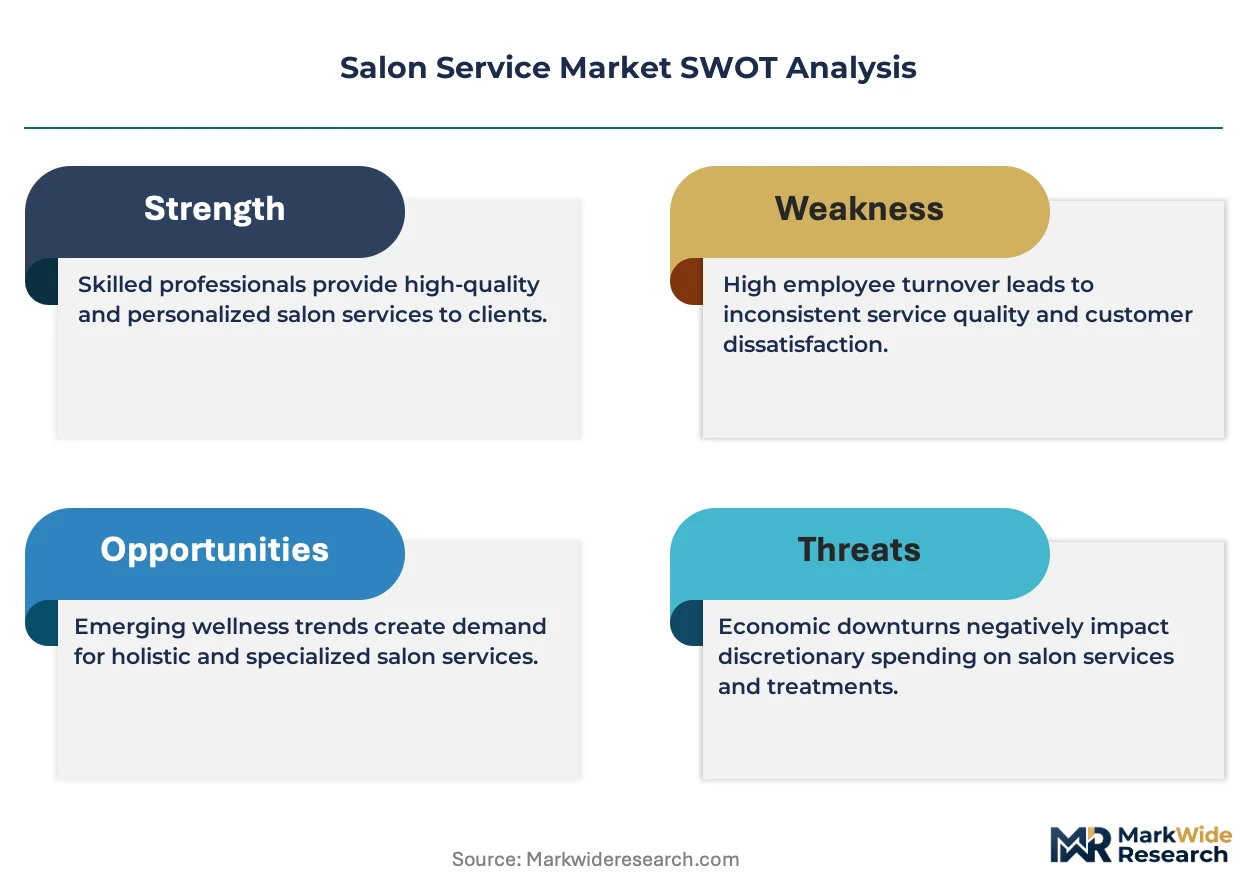
Clean beauty mandates from the FDA and EU REACH are forcing wholesale product reformulation across the salon service sector, compressing margins for legacy chemical treatments while creating entry points for botanical alternatives.
Growth Catalysts
- EU REACH chemical restrictions:Formaldehyde-free mandates accelerate adoption of plant-based keratin alternatives in European salons.
- Men's grooming normalization:Dedicated barber-studio concepts capture underpenetrated male demand previously served by unlicensed barbershops.
- Mobile service platforms:Real estate-free delivery models reach suburban markets with limited salon density.
Market Restraints
- Licensed practitioner scarcity:State cosmetology board certification timelines constrain workforce expansion.
- Ventilation infrastructure costs:OSHA workplace chemical exposure compliance requires capital-intensive salon retrofits.
- At-home treatment substitution:Professional-grade retail kits threaten recurring salon visit frequency.
Strategic Opportunities
- India tier-2 cities:Rising disposable income and limited organized salon penetration create whitespace for franchise expansion.
- Skin treatment service bundling:Superior per-visit margins from facial aesthetics offset hair service commoditization.
- Clean beauty certification convergence:USDA Organic and EU Ecolabel alignment builds cross-border consumer trust.
Industry Challenges
- Licensed aesthetician recruitment:Specialized facial treatment certification scarcity limits skin service capacity expansion.
- Legacy POS integration:Appointment-booking platform migration creates operational friction for independent salon operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salon Service Market |
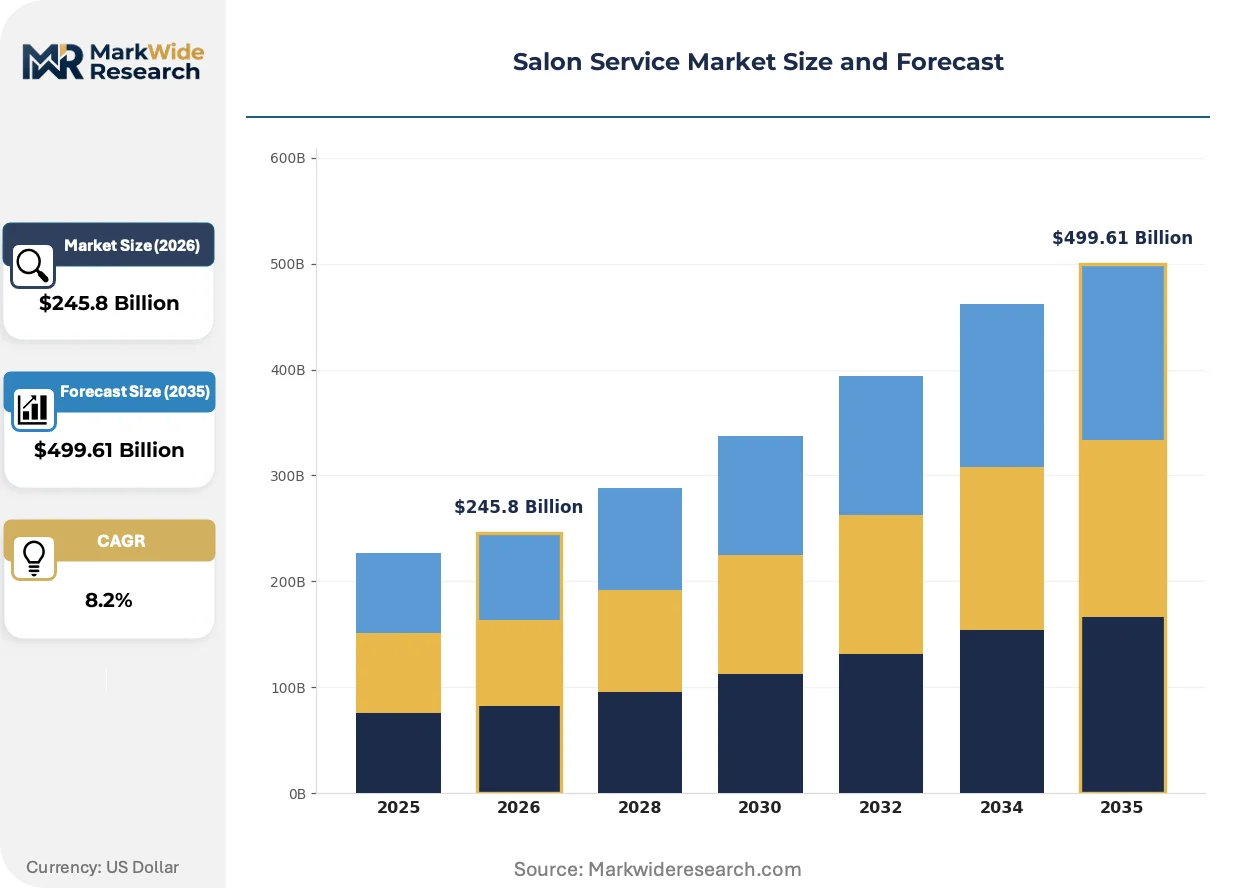
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $499.61 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hair Styling, Nail Care, Skin Treatments, Makeup Services Customer Type: Women, Men, Children, Seniors Product Offering: Organic Products, Professional Tools, Hair Color, Skincare Lines End User: Salons, Spas, Mobile Services, At-Home Services |
| Companies Covered | Sport Clips, Cost Cutters, Great Clips, Regis Corporation, European Wax Center, Supercuts, Fantastic Sams, Aveda Corporation, SmartStyle Hair Salons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salon Service Market Strategic Shifts & Innovations
Botanical formulation chemistry and service delivery digitization are restructuring competitive economics across the salon service sector. Regulatory pressure on traditional chemical processes accelerates material substitution timelines.
Plant-derived keratin treatments are overtaking formaldehyde-based straightening protocols in mid-tier salon chains. Stylists in California and New York adopt these alternatives to preempt state-level chemical disclosure litigation. The shift compresses per-treatment service times while eliminating ventilation infrastructure requirements.
EU REACH restrictions on hair dye precursors imported through multinational product lines reshape formulation supply chains. Manufacturers reformulate pigment chemistry to maintain EU market access. North American salons face ingredient inconsistency as global brands regionalize product portfolios.
Subscription-based membership models displace walk-in pricing in suburban markets. Consumers pre-commit to monthly service allowances, shifting revenue predictability to operators. Texas and Florida franchise networks pilot these structures to reduce appointment no-show rates.
Salon Service Market Segmentation
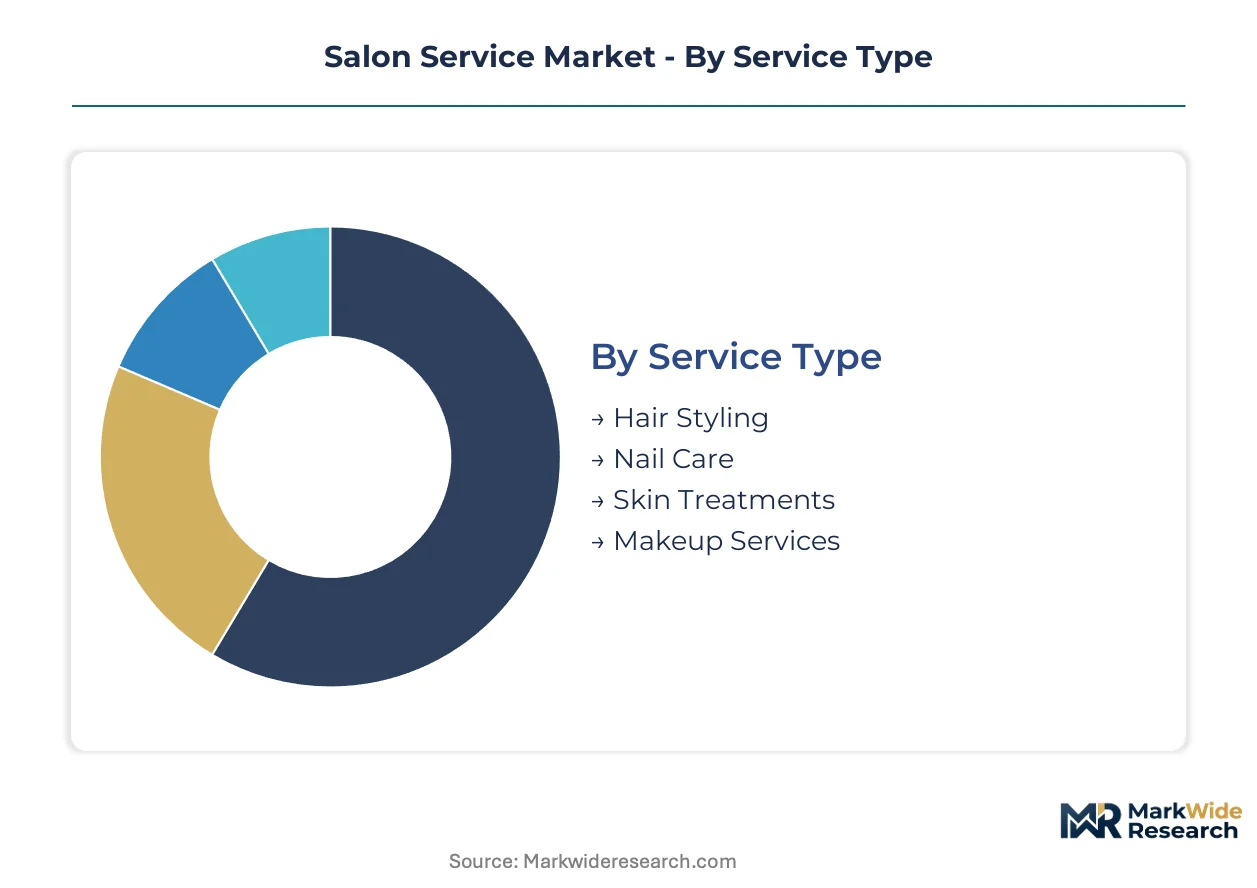
Service segmentation in the salon market determines capital allocation, regulatory exposure, and margin structure. Distinct equipment, licensing, and real estate requirements create divergent economics across service categories. Understanding these boundaries guides franchise expansion and product line decisions.
Service Type:
Capital intensity varies sharply across service types, with chemical processing infrastructure demanding the heaviest upfront investment.
- Hair Styling:Chemical straightening, coloring, and cutting services require ventilation systems, shampoo stations, and styling chairs. Demand concentrates in suburban United States markets where Great Clips and Regis franchise density is highest, constrained by OSHA chemical exposure compliance costs.
- Skin Treatments:Facial aesthetics and therapeutic skin services use specialized equipment including steamers, microdermabrasion machines, and LED therapy devices. European Wax Center captures premium margins through single-service studio formats focused on waxing-centric protocols.
- Nail Care:Manicure and pedicure stations need less square footage but demand rigorous sanitation infrastructure and ventilation for acrylic and gel applications.
- Makeup Services:Event and bridal makeup requires minimal fixed equipment, operating through portable kit-based delivery with lower real estate overhead.
Hair Styling absorbs the bulk of installed capacity; Skin Treatments are expanding most quickly.
Customer Type:
Demographic targeting shapes service menu design, pricing architecture, and marketing channel selection.
- Women:The established core customer base drives volume across all service categories, with higher visit frequency and service bundling propensity. California and New York salons prioritize female clientele through comprehensive service portfolios and loyalty programs.
- Men:Dedicated barber-studio concepts now capture previously underpenetrated demand, with specialized protocols for beard grooming and scalp treatments. Texas franchise networks pilot male-focused membership models to reduce no-show rates.
- Children:Family-oriented salon chains operate with scaled equipment, themed environments, and expedited service protocols to accommodate shorter attention spans.
- Seniors:Specialized services address thinning hair, sensitive skin, and mobility accommodations, often delivered through in-home or accessible studio formats.
Women command the largest revenue pool; Men are climbing the fastest as grooming normalization accelerates.
Product Offering:
Product positioning determines regulatory pathway, margin contribution, and cross-selling opportunity within service delivery.
- Organic Products:Plant-derived formulations bypass formaldehyde restrictions under EU REACH and California disclosure mandates. FDA clean beauty guidance accelerates adoption as salons preempt litigation risk.
- Hair Color:Permanent and semi-permanent dyes face ingredient inconsistency as global brands regionalize portfolios to comply with EU hair dye precursor restrictions.
- Skincare Lines:Professional-grade facial products capture superior retail margins, with salon-brand integration anchoring Regis Corporation's portfolio strategy.
- Professional Tools:Styling instruments and equipment represent recurring capital expenditure with lower margin contribution but essential service enablement.
Hair Color dominates current inventory investment; Organic Products are gaining share fastest as reformulation mandates spread.
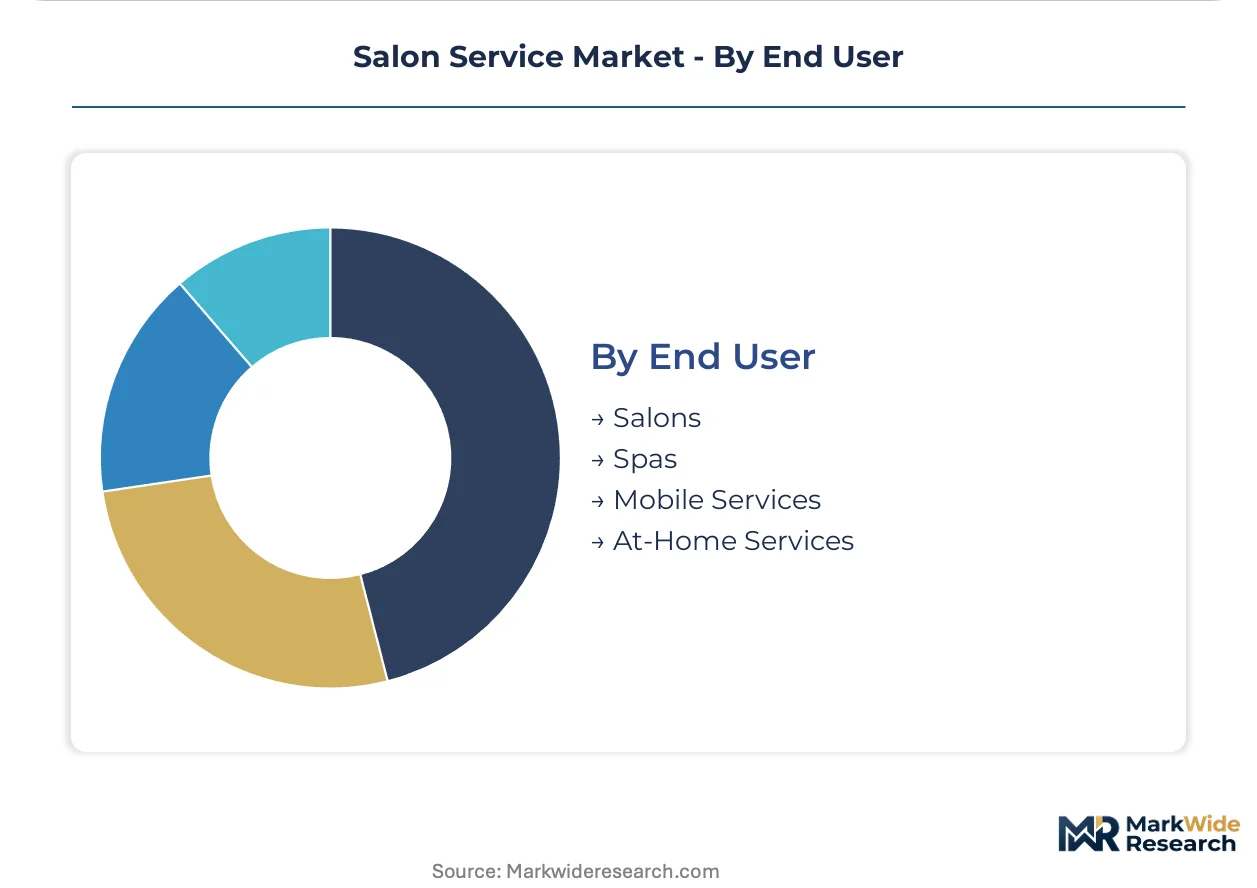
End User:
Delivery format selection dictates real estate strategy, regulatory jurisdiction, and customer acquisition economics.
- Salons:Traditional licensed commercial settings operate under state board hygiene protocols with fixed cost structures. United States franchise density concentrates demand in strip mall and suburban retail locations.
- Mobile Services:Real estate-free delivery models reach markets with limited salon density, eliminating overhead while requiring vehicle-based equipment transport and scheduling optimization.
- Spas:Integrated wellness destinations bundle salon services with massage and hydrotherapy, commanding premium pricing through experience differentiation.
- At-Home Services:Independent practitioners and platform-coordinated freelancers operate with minimal fixed investment, competing on convenience and personalized scheduling.
Salons retain the majority of service volume; Mobile Services are expanding most quickly as platform coordination improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States franchise networks concentrate the highest salon service revenue density, with strip mall penetration and premium service adoption driving regional performance variation.
United States
Suburban retail corridors in Texas and Florida pilot subscription membership models to reduce appointment no-shows. OSHA workplace chemical exposure limits mandate ventilation infrastructure investments that compress margins for independent operators. California and New York stylists preempt state-level chemical disclosure litigation by adopting botanical keratin protocols.
Germany
EU REACH formaldehyde-free mandates accelerate plant-based treatment adoption across mid-tier salon chains. ECHA chemical restrictions on hair dye precursors force manufacturers to regionalize pigment formulations. Berlin and Hamburg anchor demand for clean beauty certification alignment with EU Ecolabel standards.
United Kingdom
London's premium studio density supports facial aesthetics service bundling with superior per-visit margins. The country's national cosmetic regulator enforces post-Brexit ingredient disclosure requirements that diverge from EU REACH timelines. Manchester and Birmingham franchise networks expand male-focused barber-studio concepts.
India
Rising disposable income in tier-2 cities creates whitespace for organized salon franchise expansion. BIS standards for cosmetic product safety shape import requirements for professional-grade formulations. Maharashtra and Karnataka urban clusters concentrate early clean beauty certification adoption among premium operators.
Australia
Mobile service platforms gain structural traction in suburban markets with limited salon density. TGA cosmetic ingredient regulations align with FDA guidance on clean beauty claims. Sydney and Melbourne anchor demand for skin treatment service bundling as consumers prioritize facial aesthetics.
Salon Service Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with franchise networks consolidating suburban United States markets while independent studios retain urban premium positioning. The vendor base organizes around three archetypes: scale-driven franchise operators, single-service specialists, and botanical formulation integrators. M&A activity concentrates on regional salon chain consolidation, while technology licensing partnerships enable legacy POS platform migration.
Among franchise-scale operators, Great Clips, Regis Corporation, and European Wax Center exemplify divergent strategic positioning. Great Clips anchors the high-volume, standardized service tier through botanical treatment protocol deployment. Regis Corporation sits within the portfolio-integrated segment, linking salon-brand retail to service delivery. European Wax Center occupies the single-service dominance position with waxing-centric studio formats that capture premium margins through specialization.
| Leading Market Players |
|---|
| Sport Clips |
| Cost Cutters |
| Great Clips |
| Regis Corporation |
| European Wax Center |
| Supercuts |
| Fantastic Sams |
| Aveda Corporation |
| SmartStyle Hair Salons |
| Others |
Cost & Logistics Intelligence
Suburban franchise networks in Texas and Florida anchor demand concentration for subscription-based membership models, compressing walk-in pricing premiums while locking in recurring revenue streams. This buyer archetype concentration shifts pricing power toward operators who can pre-commit service allowances through digital booking platforms.
Pricing Analysis
Volume-driven hair styling absorbs the bulk of service throughput at compressed per-visit rates, while skin treatment bundling captures superior margins through facial aesthetics specialization. Three-tier pricing structure across premium botanical protocols, standard chemical services, and economy express cuts differentiates offerings. Pricing pressure stems from at-home treatment substitution eroding visit frequency among cost-conscious segments. Price sensitivity concentrates in male grooming entrants and family-oriented chains, while premium skin service buyers exhibit minimal elasticity.
Supply Chain Analysis
Licensed aesthetician scarcity in California and New York constrains service capacity expansion for high-margin facial protocols. Professional-grade formulation manufacturing concentrates in the United States, Germany, and India, with botanical keratin alternatives drawing from agricultural feedstock regions. Raw material dependencies include plant-derived active compounds, specialized wax formulations, and LED therapy device components. Single-source vulnerability runs through EU REACH-compliant pigment suppliers facing regionalized reformulation mandates. Distribution runs through franchise-coordinated wholesale networks and direct-to-salon platform procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed practitioner scarcity props service pricing across skin treatment and chemical processing categories, creating durable margin protection for operators who secure workforce pipelines. This supply-constrained structure favors early movers in certification-forward positioning.
For Market Incumbents: Extend botanical protocol standardization across franchise footprints to preempt state-level chemical disclosure litigation. Lock in exclusive supply agreements with EU REACH-compliant formulation manufacturers before regionalization fragments ingredient consistency. Channel control through captive retail product lines anchors Regis Corporation's portfolio integration model against pure-service competitors.
For New Entrants and Emerging Players: Enter via mobile service platforms targeting suburban markets with limited salon density in Australia and India tier-2 cities. Whitespace concentrates in male-focused membership models and clean beauty-certified studio formats. Go-to-market leverage rests on platform-coordinated scheduling optimization eliminating real estate overhead.
For Investors and Strategic Acquirers: The window for entry favors single-service specialists with clean beauty certification alignment and scalable studio economics. Long-term viability hinges on regulatory compliance infrastructure rather than location density alone. Watch FDA clean beauty guidance evolution and EU Ecolabel adoption velocity as inflection indicators for formulation substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Protocol Standardization | Great Clips deploys plant-based keratin alternatives across thousands of franchise locations to preempt chemical litigation. |
| Subscription Membership Model | Texas and Florida franchise networks reduce no-show rates through pre-committed monthly service allowances. |
| Clean Beauty Certification Alignment | USDA Organic and EU Ecolabel convergence builds cross-border consumer trust for premium positioning. |
| Mobile Service Platform Expansion | Real estate-free delivery models reach Australian suburban markets with limited salon density. |
| Single-Service Studio Specialization | European Wax Center captures premium margins through waxing-centric formats with superior per-visit economics. |
Research Approach
Independent corroboration across salon operator interviews, franchise development executives, and state cosmetology board officials underwrites the qualitative findings. Primary fieldwork engaged licensed practitioners, product formulation specialists, and retail channel managers across the United States, Germany, and India. Secondary validation drew from FDA cosmetic ingredient guidance, EU ECHA restriction updates, BIS standards documentation, and franchise disclosure filings. Bottom-up service volume modeling and top-down market sizing triangulate around consistent demand parameters.
Comparable-period anchoring to pre-pandemic service frequency baselines and post-recovery membership adoption curves structured the forecast window. Segmentation dimensions span service type, customer demographic, product positioning, and delivery format across the projection horizon. CAGRs derive from trend-line extrapolation moderated by regulatory substitution timelines and workforce expansion constraints. Forecast inputs incorporate OSHA compliance cost trajectories and EU REACH reformulation adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated clean beauty mandate enforcement or licensed practitioner supply shocks. Projections reflect assumptions about franchise network expansion velocity and mobile platform coordination maturation. Material deviation in FDA guidance timing or state-level chemical disclosure litigation volume warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Australia Skin Care Products Market
Beauty & Personal Care
Personal Care Products Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
Beauty and Wellness Products Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Natural and Organic Personal Care Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Nail Care Products Market
Beauty & Personal Care
United Kingdom Hair Care Market
Beauty & Personal Care
Colombia Cosmetics Products Market