
 Colombia Cosmetics Products Market | 2026-2036
Colombia Cosmetics Products Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Cosmetics Products Market Outlook
Subscription-based replenishment services for skincare routines is consolidating as a distinct revenue layer in Colombia, shifting one-time purchases into recurring revenue relationships. L'Oréal S.A. leverages its dermatological brand architecture to anchor premium positioning in urban centers. Natura &Co sustains its direct-sales heritage while expanding into pharmacy channels. Belcorp competes through a representative network that controls last-mile distribution across secondary cities.
Cosmetics products encompass topical formulations designed for skin, hair, and personal adornment, typically incorporating emulsifiers, active ingredients, and preservation systems manufactured through batch processing and cold-blending techniques to ensure stability and sensory performance. Skin Care and Fragrances capture disproportionate margin pools as Colombian consumers prioritize dermatological efficacy and signature scent identity. Hair Care maintains volume leadership through salon-dependent professional lines, while Makeup growth concentrates in social-commerce-driven trial formats. Brand Positioning stratifies sharply, with Natural and Eco-Friendly tiers commanding shelf-space premiums in specialty retailers despite higher unit costs.
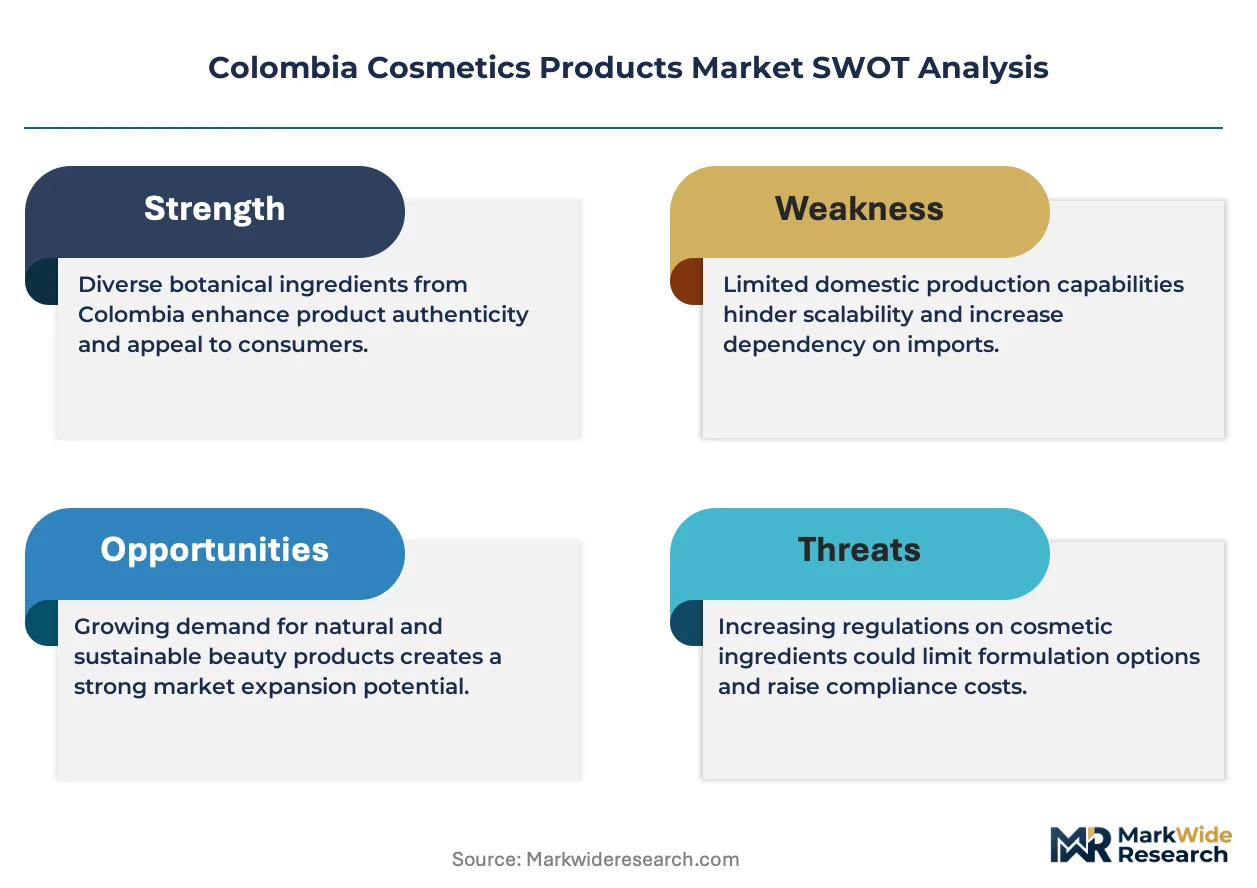
Colombia's INVIMA enforces cosmetic registration requirements that determine market entry timelines and ingredient disclosure standards, while the country's adherence to Mercosur technical regulations harmonizes labeling protocols with regional trade partners. The Ministry of Health and Social Protection coordinates with customs authorities to intercept non-compliant imports at Cartagena and Bogotá air freight terminals. Stakeholders must monitor how impending updates to Andean Community cosmetic directives reshape formulation benchmarks and cross-border e-commerce liability frameworks.
Market Dynamics
Formaldehyde-free hair straightening technologies are forcing formulation overhauls across Colombia's professional salon channel, compressing legacy product cycles while INVIMA registration timelines determine competitive entry sequencing.
Growth Catalysts
- INVIMA Registration Pathway:The regulatory framework mandates pre-market approval for all cosmetic imports, creating defensible positions for early registrants who secure shelf space in pharmacy chains before competitors clear documentation hurdles.
- Salon Channel Expansion:Professional beauty services in Medellín's clustering districts are absorbing premium hair care volumes, pulling manufacturer investment toward stylist education and back-bar format development.
- Subscription Replenishment Models:Skincare brands are converting Bogotá's urban consumers into recurring revenue relationships through automated delivery schedules tied to product usage cycles.
Market Restraints
- Import Dependency for Active Ingredients:Colombia lacks domestic production of specialized emulsifiers and preservation systems, exposing formulators to freight cost volatility and currency fluctuation risks at Cartagena port terminals.
- INVIMA Compliance Timelines:Registration review periods extend competitive launch windows, particularly for novel cosmetic actives requiring safety dossier substantiation that exceeds regional Mercosur harmonization standards.
- Professional Service Concentration:Hair care volume depends on salon channel health, concentrating demand risk in Medellín and Bogotá service clusters vulnerable to discretionary spending compression.
Strategic Opportunities
- Pharmacy Channel Penetration:Direct-to-consumer brands are securing shelf placement in Colombia's expanding pharmacy retail network, accessing dermatologist referral traffic that validates premium positioning.
- Eco-Friendly Certification Alignment:INVIMA's anticipated adoption of Andean Community environmental labeling standards will reward early movers with formulation transparency credentials that command specialty retailer premiums.
- Social Commerce Integration:Trial-size makeup formats distributed through influencer networks are compressing customer acquisition costs in secondary cities beyond traditional representative coverage zones.
Industry Challenges
- Formulation Talent Scarcity:Cosmetic chemists with expertise in cold-blending stability systems remain concentrated in Bogotá, constraining regional manufacturer expansion and forcing reliance on imported technical services.
- Legacy Distribution Integration:Direct-sales networks must reconcile representative commission structures with e-commerce pricing transparency, creating channel conflict resolution costs that erode margin capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Cosmetics Products Market |
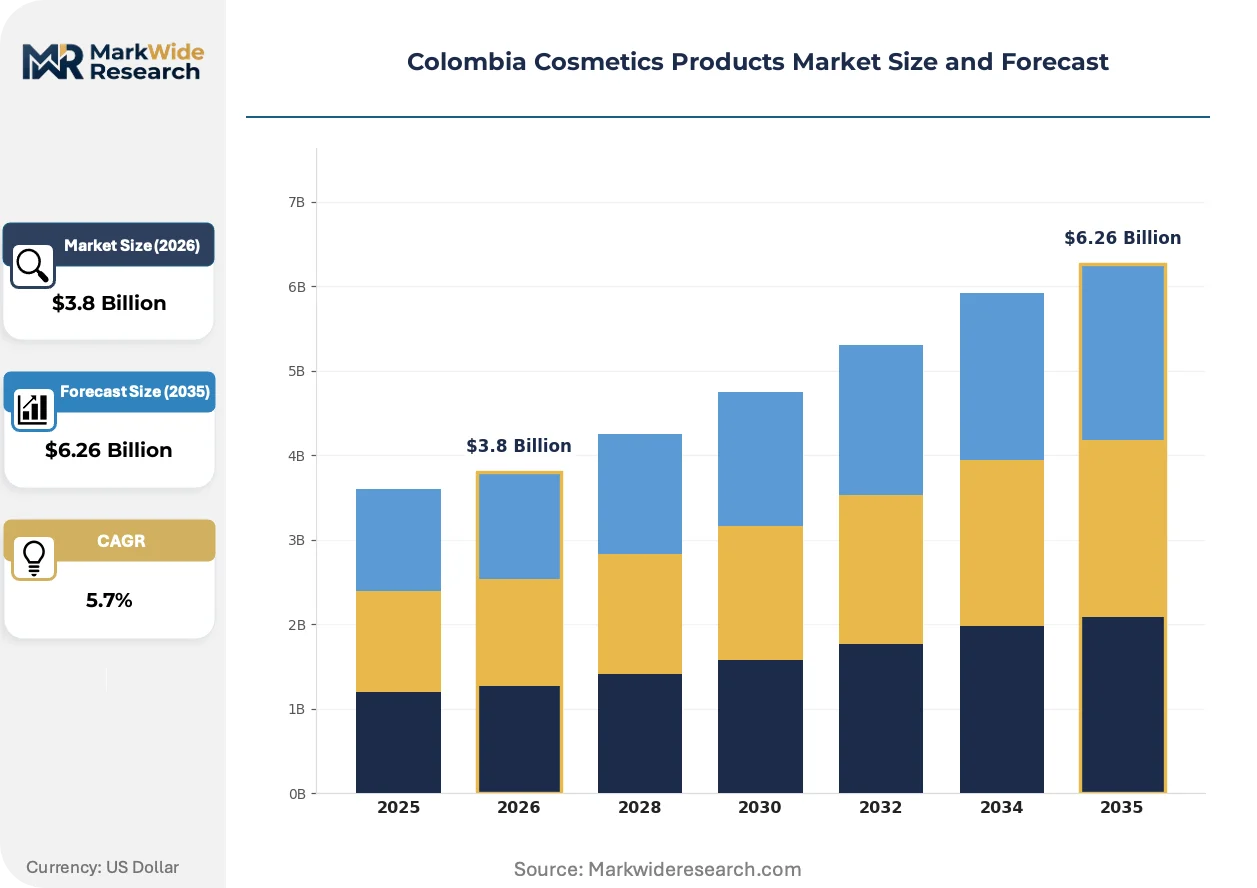
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Makeup, Fragrances Customer Type: Retail Consumers, Salons, Pharmacies, Online Shoppers Distribution Channel: Department Stores, Specialty Retailers, E-commerce, Direct Sales Brand Positioning: Luxury, Mass Market, Eco-Friendly, Natural |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., Avon Products Inc., Natura &Co, Belcorp, Shiseido Company Limited, Oriflame Cosmetics Global SA, Christian Dior SE, Yanbal Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Cosmetics Products Market Strategic Shifts
Biotechnology-derived actives and digital skin diagnostics are rewriting product development cycles in Colombia, compressing the gap between laboratory innovation and retail shelf placement while regulatory transparency mandates reshape competitive disclosure requirements.
Plant-based peptide synthesis is converging with traditional emulsifier chemistry to deliver dermatological efficacy claims without synthetic preservative load. Premium skincare brands in Bogotá's retail corridor are adopting these hybrid formulations at accelerated pace, enabling price positioning that separates certified clean beauty tiers from conventional mass-market alternatives.
INVIMA's alignment with Mercosur technical regulations is harmonizing ingredient disclosure standards across Andean Community trade partners, forcing reformulation of imports that previously operated under divergent labeling protocols. Colombian manufacturers serving cross-border e-commerce channels are absorbing compliance costs most acutely in fragrance and sun care categories where allergen declaration requirements have tightened.
Colombian consumers are prioritizing dermatological consultation before cosmetic purchase, shifting volume toward pharmacy channels that offer skin analysis services. This behavior concentrates in urban centers where dermatologist density supports appointment availability, displacing traditional department store beauty counter traffic and forcing brand investment in professional education partnerships.
Colombia Cosmetics Products Market Segmentation
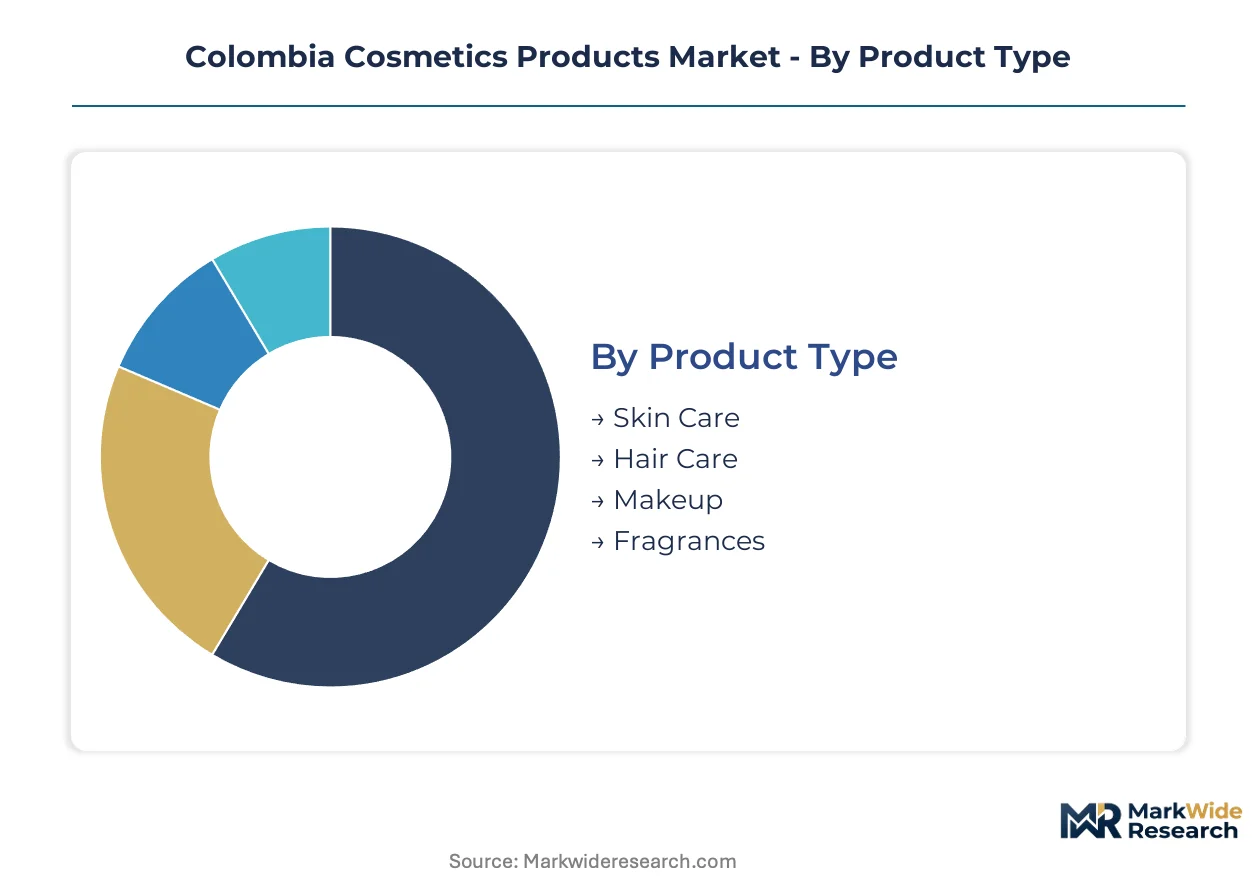
Colombia's cosmetics market fragments across product formulation priorities, professional service dependencies, and channel access hierarchies that determine margin capture. Each segmentation layer reveals distinct competitive dynamics between Bogotá's premium corridor concentration and Medellín's salon-cluster expansion.
Product Type:
Supply concentration in active ingredient sourcing tilts formulation investment toward segments with defensible margin structures and regulatory clarity under INVIMA protocols.
- Skin Care:Emulsifier-based formulations with biotechnology-derived peptides dominate R&D allocation. Demand clusters in Bogotá's pharmacy retail corridor where dermatologist consultation validates premium pricing.
- Hair Care:Professional salon lines absorb manufacturer investment in stylist education and back-bar formats. Medellín's beauty service districts pull volume through formaldehyde-free straightening technology transitions.
- Makeup:Social-commerce trial formats compress customer acquisition costs in secondary cities beyond traditional representative coverage.
- Fragrances:Signature scent identity commands disproportionate margin pools in urban centers with established brand heritage presence.
Today's leader: Skin Care. Tomorrow's challenger: Hair Care.
Customer Type:
Channel-specific purchasing behaviors separate recurring revenue relationships from transactional volume plays across Colombia's urban hierarchy.
- Retail Consumers:Subscription-based replenishment models convert Bogotá households into automated delivery schedules tied to usage cycles.
- Salons:Professional service clusters in Medellín concentrate demand for back-bar formats and stylist-exclusive product lines.
- Pharmacies:Dermatologist referral traffic validates premium positioning as skin analysis services displace department store beauty counter volume.
- Online Shoppers:Influencer-network distribution of trial-size formats penetrates secondary cities with compressed acquisition economics.
Current volume anchor: Salons. Expansion frontier: Pharmacies.
Distribution Channel:
Physical retail density versus digital penetration rates determine working capital intensity and margin erosion exposure across Colombia's geography.
- Department Stores:Traditional beauty counter traffic faces displacement from pharmacy channel skin analysis services.
- Specialty Retailers:Eco-Friendly and Natural tier brands command shelf-space premiums despite higher unit costs.
- E-commerce:Cross-border channels absorb acute compliance costs in fragrance and sun care categories under tightened allergen declaration requirements.
- Direct Sales:Representative commission structures conflict with e-commerce pricing transparency, forcing channel conflict resolution investments.
Dominant incumbent: Direct Sales. Fastest share gain: E-commerce.
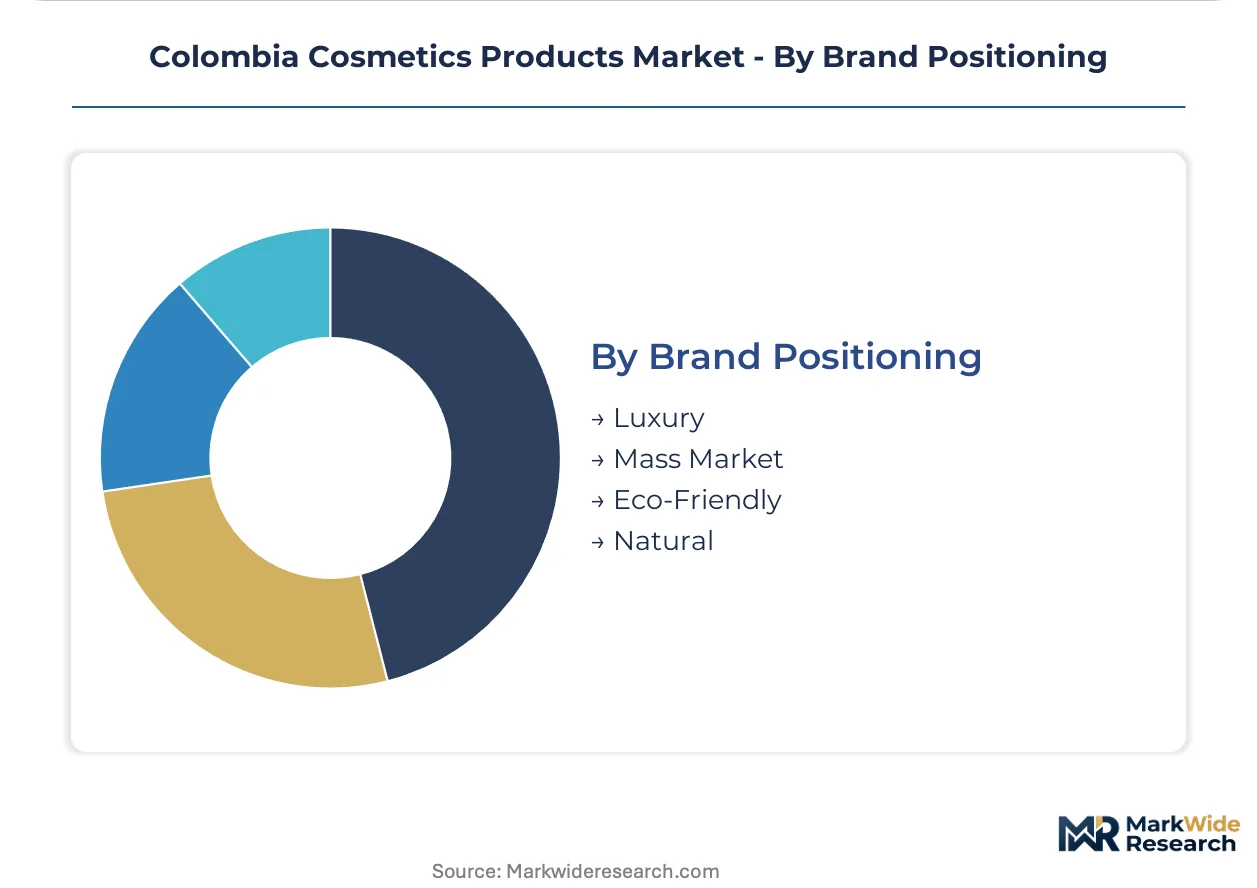
Brand Positioning:
Certification tier and ingredient transparency credentials stratify pricing power and retailer access in Colombia's regulatory environment.
- Luxury:Dermatological brand architecture anchors urban premium positioning through professional education partnerships.
- Mass Market:Volume leadership depends on representative network last-mile distribution across secondary cities.
- Eco-Friendly:Anticipated Andean Community environmental labeling standards will reward early movers with specialty retailer premiums.
- Natural:Plant-based peptide synthesis enables price separation from conventional mass-market alternatives through hybrid formulation claims.
Premium tier leader: Luxury. Momentum position: Eco-Friendly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's salon professional channel absorbs larger absolute volumes than Colombia's, yet Colombian consumers demonstrate stronger pharmacy-channel migration for dermatologist-validated skincare purchases.
Bogotá
Pharmacy retail corridors concentrate dermatological brand penetration where INVIMA registration credentials validate premium shelf placement. The Ministry of Health coordinates with customs authorities at El Dorado International Airport to intercept non-compliant cosmetic imports. Urban households in Chapinero and Usaquén districts drive subscription-based replenishment model adoption for peptide-based skincare routines.
Medellín
Beauty service clusters in El Poblado and Laureles absorb professional hair care volumes through formaldehyde-free straightening technology transitions. Salon channel expansion pulls manufacturer investment toward stylist education programs and back-bar format development. The Antioquia departmental government supports vocational training initiatives that feed technical talent into cosmetic formulation laboratories.
Cali
Social-commerce trial formats penetrate secondary city consumers through influencer network distribution of makeup miniatures. The Valle del Cauca industrial zone hosts contract manufacturing facilities serving Andean Community cross-border e-commerce channels. Pacific port access through Buenaventura exposes formulators to freight cost volatility in active ingredient imports.
Barranquilla
Caribbean coastal consumer preferences favor fragrance identity purchases with established brand heritage presence. The Atlántico departmental commerce secretariat monitors Mercosur labeling protocol compliance for imported cosmetic goods. Local retail distributors serve as intermediaries for Colombian manufacturers seeking Panama and Central American market entry.
Cartagena
Port terminal customs operations determine competitive entry sequencing for international cosmetic brands through INVIMA registration verification. Tourism-driven duty-free retail channels concentrate fragrance and luxury skincare transactions in the walled city district. Free trade zone status attracts regional distribution center investments serving Venezuela and Ecuador re-export flows.
Colombia Cosmetics Products Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational dermatological houses commanding pharmacy shelf space while direct-sales networks retain last-mile control in secondary cities. Market structure tilts toward representative-based distribution heritage, though e-commerce penetration is compressing traditional commission structures. Three archetypes dominate: multinational science-backed brands, Latin American direct-sales incumbents, and emerging clean-beauty specialists. Competitive moves center on pharmacy channel penetration investments and subscription infrastructure buildout.
Within the multinational tier, L'Oréal S.A. and The Estée Lauder Companies Inc. occupy positions anchored by dermatological brand architecture and professional education partnerships. Among Latin American direct-sales heritage players, Natura &Co and Belcorp exemplify the representative-network model that controls secondary city distribution, while Avon Products Inc. sits within the same archetype with established catalog-based consumer relationships.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Avon Products Inc. |
| Natura &Co |
| Belcorp |
| Shiseido Company Limited |
| Oriflame Cosmetics Global SA |
| Christian Dior SE |
| Yanbal Corporation |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock indices in the US Gulf Coast and Northeast Asia cascade through Colombian cosmetic formulation costs, compressing margin structures for mass-market emulsifier-dependent products while biotechnology-derived active premiums widen pricing stratification between pharmacy-tier dermatological lines and salon-channel professional formats.
Pricing Analysis
Capacity additions in Brazil's specialty chemical sector are reshaping price floors for preservation systems imported through Cartagena port terminals. Three-tier pricing structure across premium, standard, and economy levels separates INVIMA-registered dermatological brands from mass-market representative-distributed lines and unregistered gray-market imports. Pricing pressure stems from currency fluctuation exposure in active ingredient procurement, with Bogotá pharmacy-channel buyers exhibiting lowest price sensitivity due to dermatologist validation, while Cali's social-commerce makeup purchasers drive trial-size format competition.
Supply Chain Analysis
Regional distribution centers in Bogotá's free trade zones and Medellín's industrial corridors anchor hub-and-spoke patterns serving pharmacy chains and salon clusters. Brazil, the United States, and China supply concentrated emulsifier and peptide active inputs, with Colombian formulators drawing from Argentine botanical extract sources for natural-tier certification alignment. Single-source vulnerability concentrates in Chinese preservation system suppliers, while distribution runs through Belcorp and Natura representative networks controlling last-mile access in secondary cities beyond urban retail density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Colombia's cosmetics market rests on biotechnology-derived active cost curves flattening and pharmacy-channel premium tier absorption accelerating in Bogotá and Medellín urban corridors.
For Market Incumbents: Acquire cold-blending formulation laboratories in Antioquia department to secure technical talent scarcity against emerging clean-beauty specialists. Consolidate stylist education program control in Medellín salon clusters to defend professional hair care volume against formaldehyde-free technology disruptors. INVIMA registration dossier depth remains the priority lever for pharmacy shelf access. For New Entrants and Emerging Players: Secondary city pharmacy networks outside Bogotá-Medellín concentration represent underserved buyer archetype penetration opportunities with compressed customer acquisition costs. Social-commerce trial-size makeup distribution through Cali and Barranquilla influencer networks offers fastest beachhead, while eco-friendly certification alignment captures specialty retailer shelf premiums ahead of anticipated Andean Community environmental labeling adoption. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturers possessing INVIMA-registered facility status and cross-border e-commerce fulfillment capabilities for Andean Community markets. Long-term viability hinges on biotechnology peptide synthesis integration and pharmacy-channel revenue mix expansion. Watch INVIMA registration queue clearance velocity as inflection indicator for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| INVIMA Registration Acceleration | Early dossier submission secures pharmacy shelf placement before competitor documentation hurdles. |
| Biotechnology Active Integration | Plant-based peptide synthesis enables price separation from synthetic preservative-dependent mass-market alternatives. |
| Subscription Infrastructure Buildout | Automated replenishment models convert Bogotá households into recurring revenue relationships. |
| Salon Channel Education Investment | Stylist certification programs in Medellín lock in professional hair care volume commitment. |
| Eco-Friendly Certification Pre-Positioning | Andean Community environmental labeling alignment captures specialty retailer premiums. |
Study Parameters
Coverage spans Colombia's five major metropolitan zones, with primary inputs from each region's pharmacy retail corridors, salon service clusters, and port terminal customs operations. The analysis combines structured interviews with cosmetic brand managers, INVIMA regulatory affairs specialists, pharmacy chain category buyers, and salon network distributors with secondary validation from customs import records, INVIMA registration databases, and Nielsen retail audit data for beauty and personal care categories. Bottom-up volume triangulation across product segments and top-down value reconciliation against trade flow data anchor the analytical framework.
Rate-of-change decomposition separates volume growth drivers from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including product type, customer channel, distribution format, and brand positioning tier, with regional urban hierarchy as an additional industry-specific dimension. CAGRs derive from trend-line extrapolation of historical registration volumes, adjusted for INVIMA procedural timeline changes and salon channel expansion rates in Medellín's clustering districts. Biotechnology active adoption curves and subscription model penetration rates inform segment-specific growth assumptions.
Inputs from INVIMA registration databases and pharmacy retail audit panels were available through the study window; gaps in informal channel volume estimation and cross-border e-commerce transaction flows introduce uncertainty bands around secondary city penetration forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
E-Pharmacy Beauty and Personal Care (BPC) Market
Beauty & Personal Care
India Antibacterial Soap Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Intimate Wash Care Products Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
DIY Eyelash Extension Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
US Cosmetics Market
Beauty & Personal Care
Aftershave Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
North America Beauty Devices Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Anti Stretch Mark Products Market