
 North America Bath and Shower Products Market | 2026-2036
North America Bath and Shower Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bath and Shower Products Market Analytics
Biodegradable surfactant chemistry is tilting formulation priorities across the North America bath and shower sector, compelling manufacturers to rebuild product architectures from raw material inputs upward. Procter & Gamble Co. leverages its captive oleochemical supply chain to secure consistent feedstock for sulfate-free body wash lines. Unilever plc anchors its North American position through concentrated manufacturing footprint in the Midwest. Colgate-Palmolive Company differentiates via specialized antibacterial bar soap production that meets institutional procurement specifications.
Bath and shower products comprise rinse-off cleansing and conditioning preparations formulated with surfactants, emollients, preservatives, and functional actives, typically manufactured through batch emulsification or continuous saponification processes at pH ranges of 5.0 to 7.5 for skin compatibility. Body wash and shower gel formulations command the largest volume share within product type segmentation, though organic-positioned variants are capturing disproportionate margin expansion. The moisturizing formulation segment leads value generation due to premium pricing elasticity, while exfoliating and antibacterial categories face reformulation headwinds from regulatory scrutiny on microplastic beads and certain biocidal actives.
The FDA governs cosmetic safety labeling and ingredient restrictions under the Federal Food, Drug, and Cosmetic Act, while EPA oversight applies to antimicrobial claims that trigger pesticide registration requirements; California's Proposition 65 enforcement has additionally forced disclosure and reformulation of phthalate and formaldehyde-releasing preservative systems. The FTC monitors green marketing claims, creating compliance complexity for brands positioning products as natural or sustainable. Stakeholders must monitor pending federal fragrance allergen disclosure legislation and state-level chemical restriction cascades that could fragment formulation requirements across the United States and Canada.
Market Dynamics
The North America bath and shower sector is undergoing a forced architectural rebuild as biodegradable surfactant chemistry replaces petroleum-derived feedstocks, compelling manufacturers to revalidate entire formulation pipelines from raw material sourcing through finished product stability testing.
Growth Catalysts
- California Proposition 65 enforcement:Disclosure mandates for phthalates and formaldehyde-releasing preservatives have accelerated clean-label innovation, creating first-mover advantages for reformulated portfolios.
- Direct-to-consumer subscription channels:Urban centers in California and New York have achieved critical mass in recurring revenue models, locking in predictable demand for premium body wash and shower gel lines.
- Plant-derived formulation chemistry:Oleochemical feedstock availability from Midwest agricultural processing is enabling sulfate-free surfactant production at commercial scale.
Market Restraints
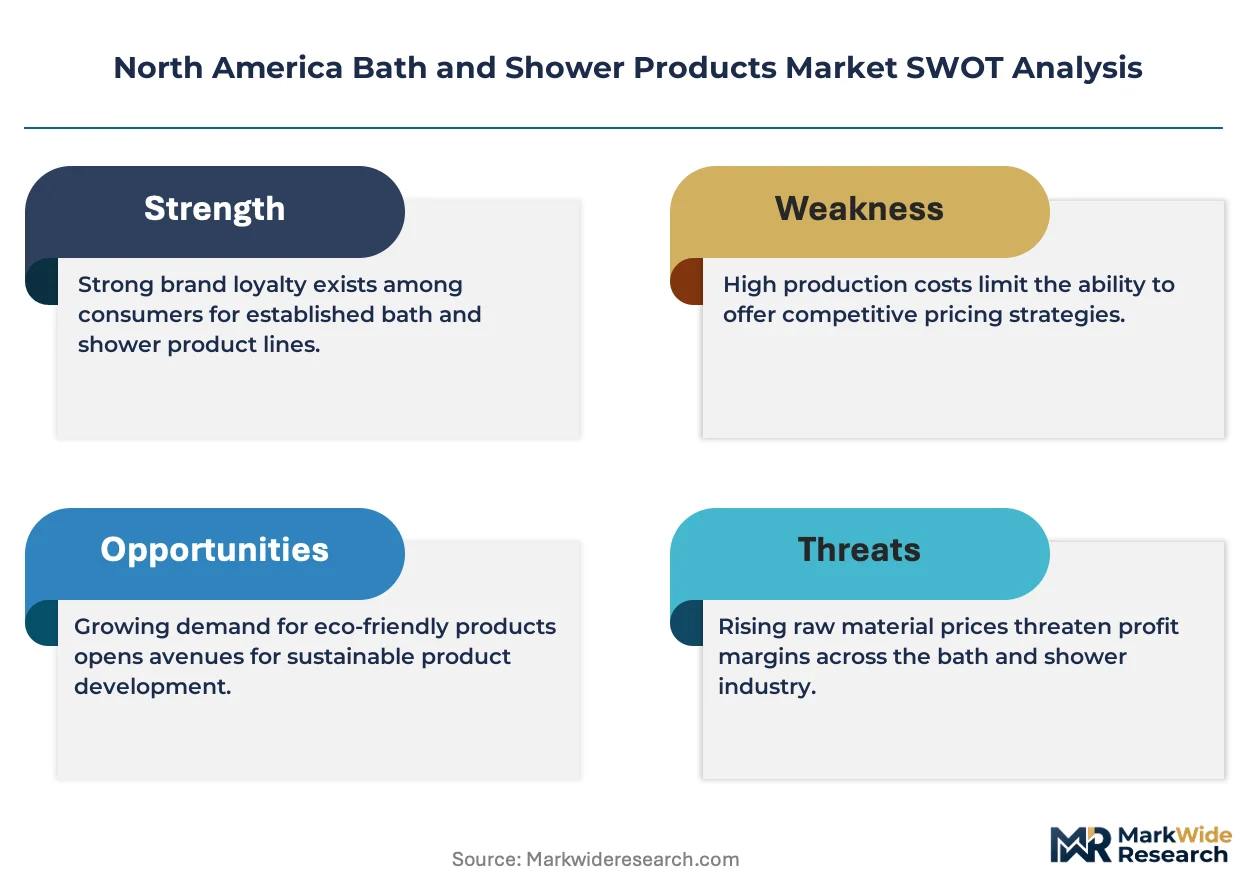
- Palm and coconut oil price volatility:Tropical weather disruptions and shipping constraints create margin compression for manufacturers dependent on these primary oleochemical inputs.
- FDA antimicrobial review uncertainty:Ongoing evaluation of triclosan and alternative biocidal actives forces parallel formulation tracks, raising R&D overhead without guaranteed approval pathways.
- Microplastic bead substitution costs:Exfoliating product lines require physical abrasive reformulation, with natural alternatives like jojoba esters and ground nut shells carrying higher unit costs and supply constraints.
Strategic Opportunities
- Institutional procurement specifications:Healthcare and hospitality sectors are consolidating antibacterial bar soap purchasing around specialized manufacturing capabilities, rewarding dedicated production assets.
- Fragrance allergen disclosure legislation:Pending federal mandates would create compliance barriers for imported formulations, favoring domestic manufacturers with established transparency protocols.
- Midwest manufacturing concentration:Unilever's concentrated production footprint demonstrates logistics advantages for serving central U.S. distribution networks, suggesting expansion capacity for regional players.
Industry Challenges
- Reformulation timeline compression:Simultaneous state-level chemical restriction cascades across California, New York, and emerging jurisdictions fragment formulation requirements, forcing multiple SKUs for single products.
- Green marketing claim substantiation:FTC enforcement actions against natural and sustainable positioning require documented supply chain verification, raising compliance costs for smaller brands without captive sourcing.
- Batch emulsification scale-up constraints:Transitioning from pilot-scale biodegradable surfactant testing to continuous saponification at commercial volume introduces stability and homogeneity risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bath and Shower Products Market |
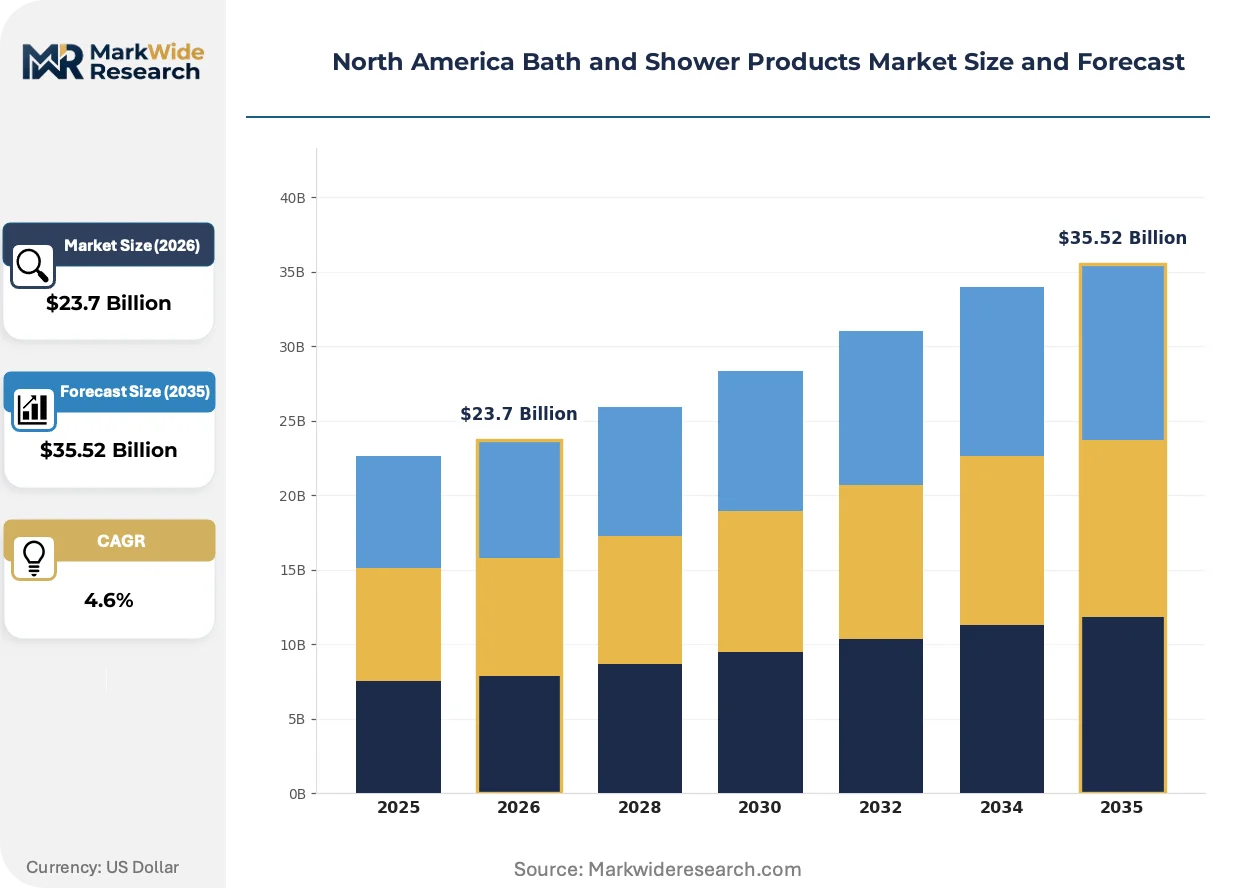
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $35.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shower Gel, Bath Bombs, Body Wash, Bar Soap Formulation: Moisturizing, Exfoliating, Antibacterial, Organic Application: Personal Care, Spa Treatments, Aromatherapy, Home Use Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Procter & Gamble Co., Unilever plc, Colgate-Palmolive Company, L'Oréal, Henkel AG & Co. KGaA, Kenvue Inc., Johnson & Johnson, Beiersdorf AG, Bath & Body Works LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bath and Shower Products Market Evolving Landscape
Formulation science, regulatory transparency mandates, and channel restructuring are converging to reshape competitive position in North American rinse-off personal care. These forces favor manufacturers with vertical control over feedstock quality and direct consumer relationships.
Sulfate-free surfactant systems are collapsing the traditional distinction between mass-market cleansing efficacy and premium skin compatibility claims. Millennial and Gen Z buyers in coastal metropolitan markets are adopting these formulations at replacement rates that exceed historical category switching cycles. This technology compression is eliminating the mid-tier price band that previously separated clinical-positioned body washes from basic cleansing bars.
California's Proposition 65 enforcement has established a de facto North American standard for chemical disclosure that exceeds federal FDA labeling requirements. Manufacturers now face dual-track compliance: minimal federal cosmetic safety labeling alongside granular state-mandated ingredient transparency. The moisturizing formulation segment, with its premium pricing elasticity, has absorbed these compliance costs most readily through packaging redesign and reformulation investment.
Subscription-based replenishment is displacing traditional retail shelf purchase patterns for core bath and shower categories. Direct-to-consumer platforms in California and New York metropolitan areas are capturing household penetration through algorithmic reordering and personalized scent profiling. This channel shift is most visible among dual-income urban households seeking convenience without sacrificing clean-beauty positioning.
North America Bath and Shower Products Market Segmentation
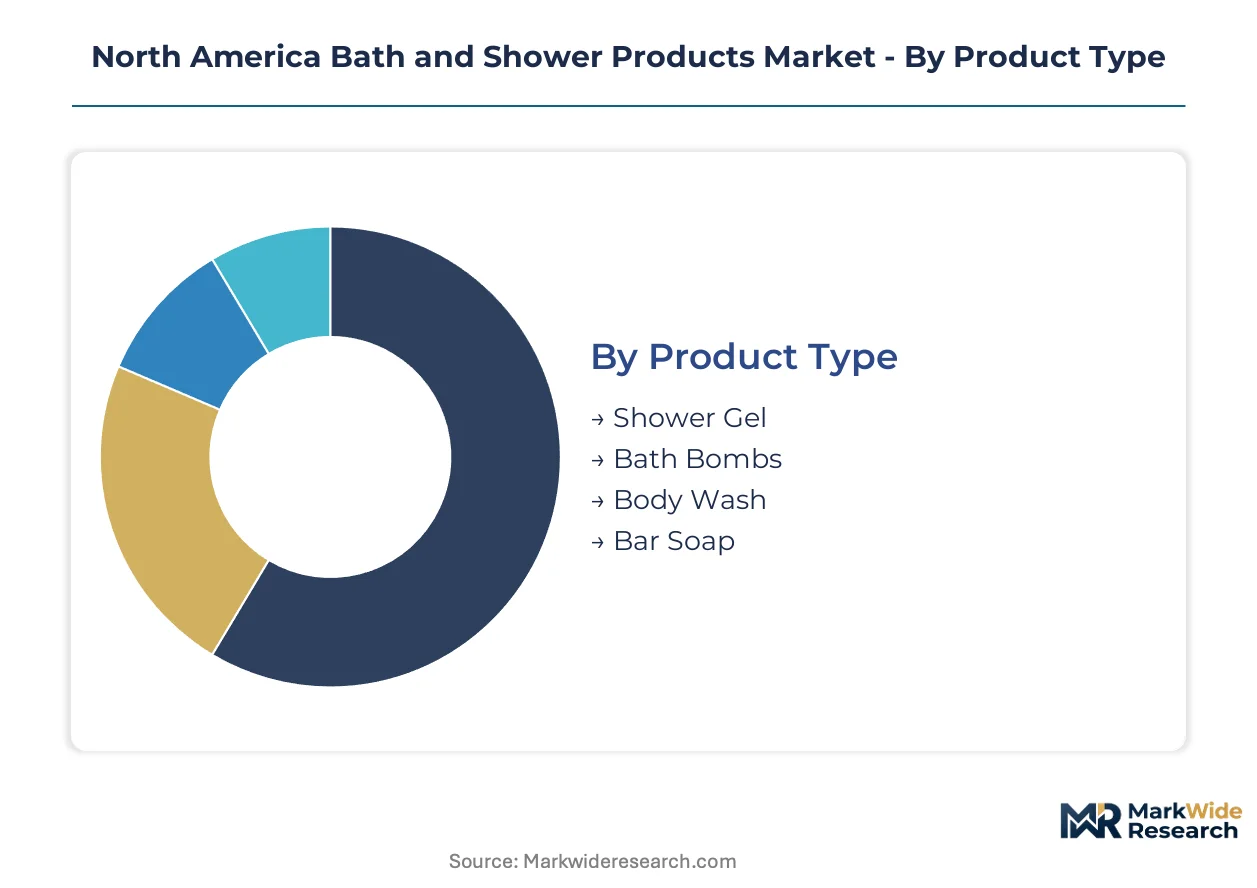
Segmentation in the North America bath and shower sector reveals how formulation chemistry, channel structure, and end-use applications create distinct competitive battlegrounds. Manufacturers must align R&D investment and distribution strategy to the specific margin profiles and regulatory exposures of each segment cluster.
Product Type:
Cost tier differentiation separates mass-market cleansing efficacy from premium skin compatibility positioning across rinse-off categories.
- Body Wash:Liquid surfactant formulations dominate volume throughput in North American retail, with sulfate-free variants capturing disproportionate margin expansion in California and New York metropolitan subscription channels. Procter & Gamble's captive oleochemical supply chain secures feedstock consistency for reformulated lines responding to FDA antimicrobial review pressures.
- Bar Soap:Solid cleansing bars retain institutional procurement relevance through concentrated manufacturing economics and antibacterial specification compliance. Colgate-Palmolive maintains dedicated production assets serving healthcare and hospitality sector consolidation.
- Shower Gel:Thickened aqueous formulations with elevated fragrance loads target premium positioning through sensory differentiation.
- Bath Bombs:Effervescent solid preparations with aesthetic and aromatherapy positioning command gift and occasion-based purchasing.
Body Wash commands the established base. The steepest expansion runs through Bar Soap institutional specifications.
Formulation:
Application requirements and regulatory exposure divide formulation priorities between functional efficacy claims and clean-label positioning.
- Moisturizing:Emollient-rich surfactant systems with pH-balanced delivery (5.0-7.5) generate premium pricing elasticity through skin barrier positioning. California's Proposition 65 enforcement has accelerated adoption as manufacturers absorb compliance costs through packaging redesign investment.
- Organic:Plant-derived chemistry with certified feedstock traceability captures clean-beauty retail infrastructure concentration in coastal urban centers. Midwest agricultural oleochemical processing enables commercial-scale sulfate-free production.
- Antibacterial:Biocidal active formulations face FDA review uncertainty on triclosan alternatives, forcing parallel R&D tracks without guaranteed approval pathways.
- Exfoliating:Physical abrasive systems require microplastic bead substitution with natural alternatives like jojoba esters, carrying higher unit costs and supply constraints.
Moisturizing formulations anchor value generation. Organic-positioned variants are climbing the fastest through margin expansion.
Application:
Customer type and usage context determine packaging formats, fragrance architecture, and channel placement strategy.
- Personal Care:Daily cleansing routines drive replenishment velocity through direct-to-consumer subscription models with algorithmic reordering in dual-income urban households.
- Home Use:Family-scale purchasing concentrates in supermarket and mass retail channels with value-oriented multi-pack configurations.
- Spa Treatments:Professional service integration demands bulk formats with treatment-specific scent profiles and institutional procurement relationships.
- Aromatherapy:Wellness-positioned scent delivery targets specialty retail with therapeutic claim substantiation requirements.
Personal Care secures recurring revenue density. Spa Treatments present the steepest expansion trajectory through professional channel development.
Distribution Channel:
Volume concentration and margin capture diverge between physical retail infrastructure and digital-native replenishment platforms.
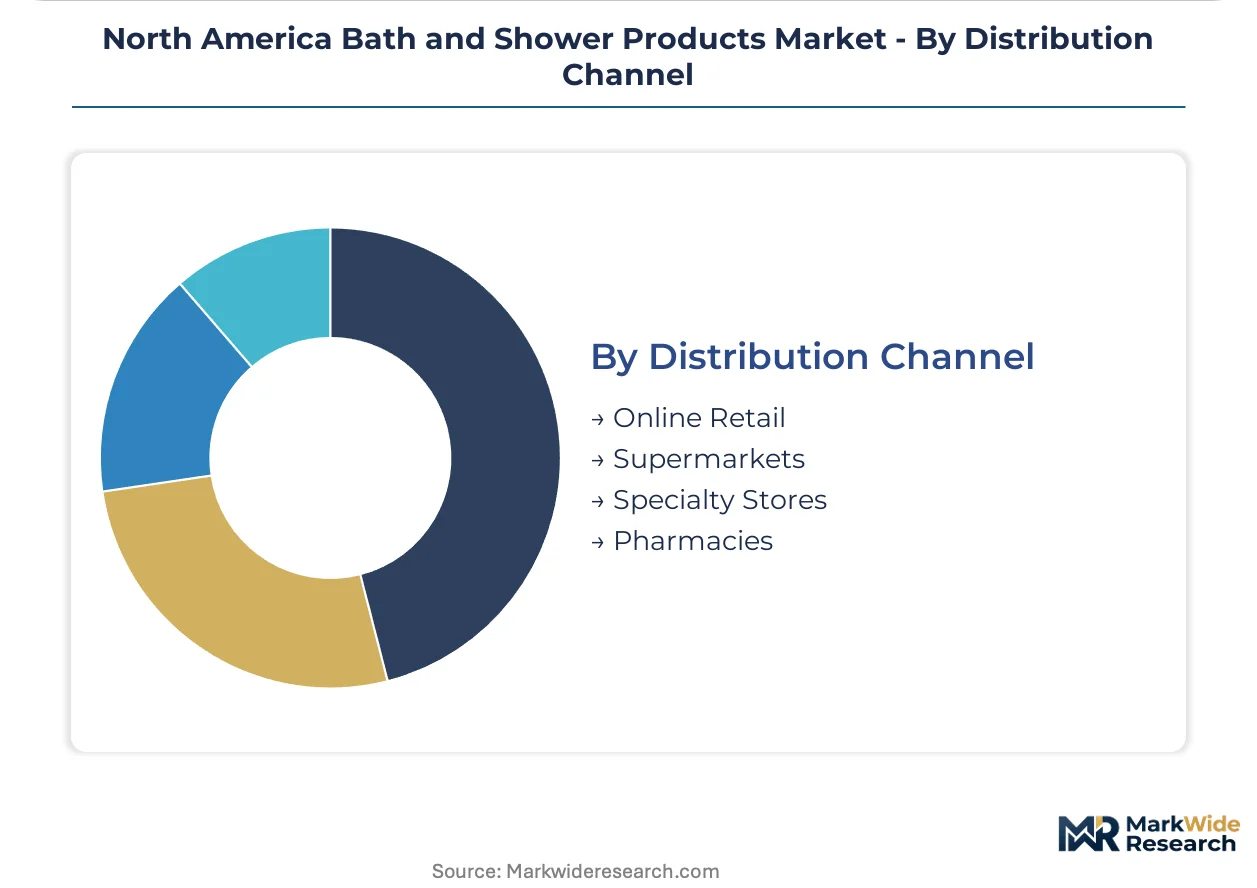
- Online Retail:Direct-to-consumer platforms with subscription mechanics achieve household penetration through personalized scent profiling and clean-beauty algorithmic curation in California and New York critical mass markets.
- Supermarkets:Mass-market volume throughput depends on shelf space negotiation and promotional frequency for family replenishment purchasing.
- Specialty Stores:Curated clean-beauty retail infrastructure in California enables premium positioning with granular ingredient transparency disclosure exceeding federal requirements.
- Pharmacies:Clinical credibility positioning supports dermatologist-recommended and sensitive-skin formulation distribution with pharmacist consultation integration.
Supermarkets maintain volume dominance. Online Retail is gaining share fastest through subscription model lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian oleochemical exports flow primarily to United States manufacturing clusters, while Mexican surfactant imports serve maquiladora production along the border states. This trade corridor shapes raw material sourcing patterns across the North American bath and shower sector.
United States
California's Proposition 65 enforcement drives clean-label reformulation investment from Los Angeles and San Francisco Bay Area formulators. FDA oversight of triclosan alternatives under the Federal Food, Drug, and Cosmetic Act creates compliance complexity for antibacterial product lines. The Midwest manufacturing belt, anchored by Illinois and Ohio production facilities, concentrates sulfate-free surfactant output for national distribution.
Canada
Health Canada and PMRA dual oversight governs antimicrobial claims and cosmetic safety labeling across provincial markets. Prairie agricultural processing in Manitoba and Saskatchewan supplies canola-derived oleochemical feedstocks to United States manufacturers. Toronto and Vancouver serve as clean-beauty retail infrastructure nodes for premium import distribution.
Mexico
Nuevo León and Jalisco industrial corridors host contract manufacturing for United States brand owners seeking nearshore production. Mexican regulatory alignment with FDA cosmetic safety frameworks simplifies cross-border formulation standardization. Mexico City metropolitan demand concentrates mass-market volume through supermarket and pharmacy channels.
North America Bath and Shower Products Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: multinational consumer goods conglomerates with captive oleochemical supply chains, specialized personal care manufacturers with institutional procurement relationships, and direct-to-consumer native brands with subscription platform infrastructure. Competitive positioning depends on backward integration into agricultural feedstock sourcing and algorithmic customer retention mechanics rather than traditional shelf-space negotiation.
Among conglomerate-tier operators, Procter & Gamble Co., Unilever plc, and Colgate-Palmolive Company exemplify distinct strategic positioning within the sector. Procter & Gamble represents upstream supply chain control through captive oleochemical sourcing. Unilever occupies a position emphasizing concentrated manufacturing footprint advantages. Colgate-Palmolive anchors the institutional specification compliance archetype for healthcare and hospitality procurement channels.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| Unilever plc |
| Colgate-Palmolive Company |
| L'Oréal |
| Henkel AG & Co. KGaA |
| Kenvue Inc. |
| Johnson & Johnson |
| Beiersdorf AG |
| Bath & Body Works LLC |
| Others |
Value Network & Pricing Analysis
Palm and coconut oil price volatility determines both pricing tier spreads and supply chain shape across the North America bath and shower sector. Tropical weather disruptions and shipping constraints force manufacturers to absorb margin compression or pass costs through premium positioning, while simultaneously driving geographic diversification of oleochemical sourcing.
Pricing Analysis
Formulation-generation pricing gaps separate petroleum-derived surfactant systems from emerging biodegradable alternatives and next-generation plant-derived chemistry. Three-tier pricing structure across premium organic, standard mass-market, and economy private-label levels stratifies by certification grade and feedstock traceability. Pricing pressure stems from FDA antimicrobial review uncertainty forcing parallel R&D tracks without guaranteed approval pathways. Institutional procurement buyers in healthcare and hospitality sectors exhibit lowest price sensitivity due to specification compliance requirements, while mass-market family purchasers show highest elasticity.
Supply Chain Analysis
Export-control regime limitations on specialized processing equipment constrain domestic manufacturing scale-up for advanced biodegradable surfactant production. Geographic supply concentration centers on Southeast Asian palm and coconut oil production, Midwest United States agricultural processing for canola-derived feedstocks, and Canadian prairie oleochemical exports. Raw material dependencies include tropical vegetable oils, sulfate-free surfactant precursors, and natural exfoliant alternatives like jojoba esters. Single-source vulnerability from tropical weather disruption creates procurement risk. Distribution runs through concentrated Midwest manufacturing hubs serving national retail and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward institutional procurement consolidators and algorithmic subscription platforms, fragmenting traditional retail negotiation leverage. Healthcare and hospitality sector purchasing consolidation rewards specialized manufacturing capabilities over brand equity alone.
For Market Incumbents: Build captive oleochemical supply chain moats through backward integration into Midwest agricultural processing and Southeast Asian sourcing partnerships. Secure FDA pre-approval pathways for antimicrobial alternatives ahead of regulatory finalization. Expand sulfate-free production capacity in Illinois and Ohio manufacturing clusters to serve subscription channel volume commitments.
For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription mechanics targeting dual-income urban households in California and New York metropolitan markets. Penetrate the exfoliating segment reformulation opportunity with jojoba ester and ground nut shell alternatives commanding premium positioning. Deploy personalized scent profiling algorithms to lock in recurring revenue density ahead of mass-market imitation.
For Investors and Strategic Acquirers: Pending federal fragrance allergen disclosure legislation reshapes the acquisition landscape toward domestic manufacturers with established transparency protocols. Long-term viability favors targets with vertical control over feedstock quality and clean-beauty retail infrastructure relationships. Watch California Proposition 65 enforcement cascades to New York and emerging state jurisdictions as signal for formulation compliance investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Oleochemical Supply Chain Development | Procter & Gamble's Midwest agricultural partnerships secure consistent sulfate-free feedstock for reformulated body wash lines. |
| Direct-to-Consumer Subscription Platform Launch | Algorithmic reordering mechanics in California and New York achieve household penetration through personalized scent profiling. |
| Antibacterial Specification Compliance Investment | Colgate-Palmolive's dedicated production assets capture healthcare and hospitality procurement consolidation. |
| Natural Exfoliant Alternative Sourcing | Jojoba ester and ground nut shell substitution addresses microplastic bead regulatory bans with premium positioning. |
| Fragrance Allergen Disclosure Infrastructure | Granular ingredient transparency protocols prepare domestic manufacturers for pending federal mandate compliance barriers. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers, category buyers at retailers, supply planners, and channel sales heads and refined through secondary validation. Primary research drew from structured interviews with formulation scientists at multinational consumer goods conglomerates, procurement leads at institutional healthcare and hospitality buyers, and subscription platform operators in California and New York. Secondary sources included Nielsen retail audit data, FDA cosmetic ingredient filings, EPA antimicrobial registration databases, and customs trade records for oleochemical imports. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, formulation chemistry, application context, and distribution channel structure. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and channel shift acceleration. Industry-specific forecast inputs incorporated FDA review timeline assumptions for triclosan alternatives and California Proposition 65 enforcement propagation patterns.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending and tropical commodity price indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and subscription channel penetration rates. Material shifts in FDA antimicrobial approval pathways or state-level chemical restriction cascades would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
E-Pharmacy Beauty and Personal Care (BPC) Market
Beauty & Personal Care
South Korea Beauty and Personal Care Products Market
Beauty & Personal Care
Philippines Beauty & Personal Care Market
Beauty & Personal Care
Aluminium-Free Deodorants Market
Beauty & Personal Care
South America Deodorants Market
Beauty & Personal Care
US Cosmetics Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Plant-Based Skincare Products Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
UV Nail Gel Lamp Market