
 Ammonium Fluoride Solution Market | 2026-2036
Ammonium Fluoride Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Fluoride Solution Market Insights
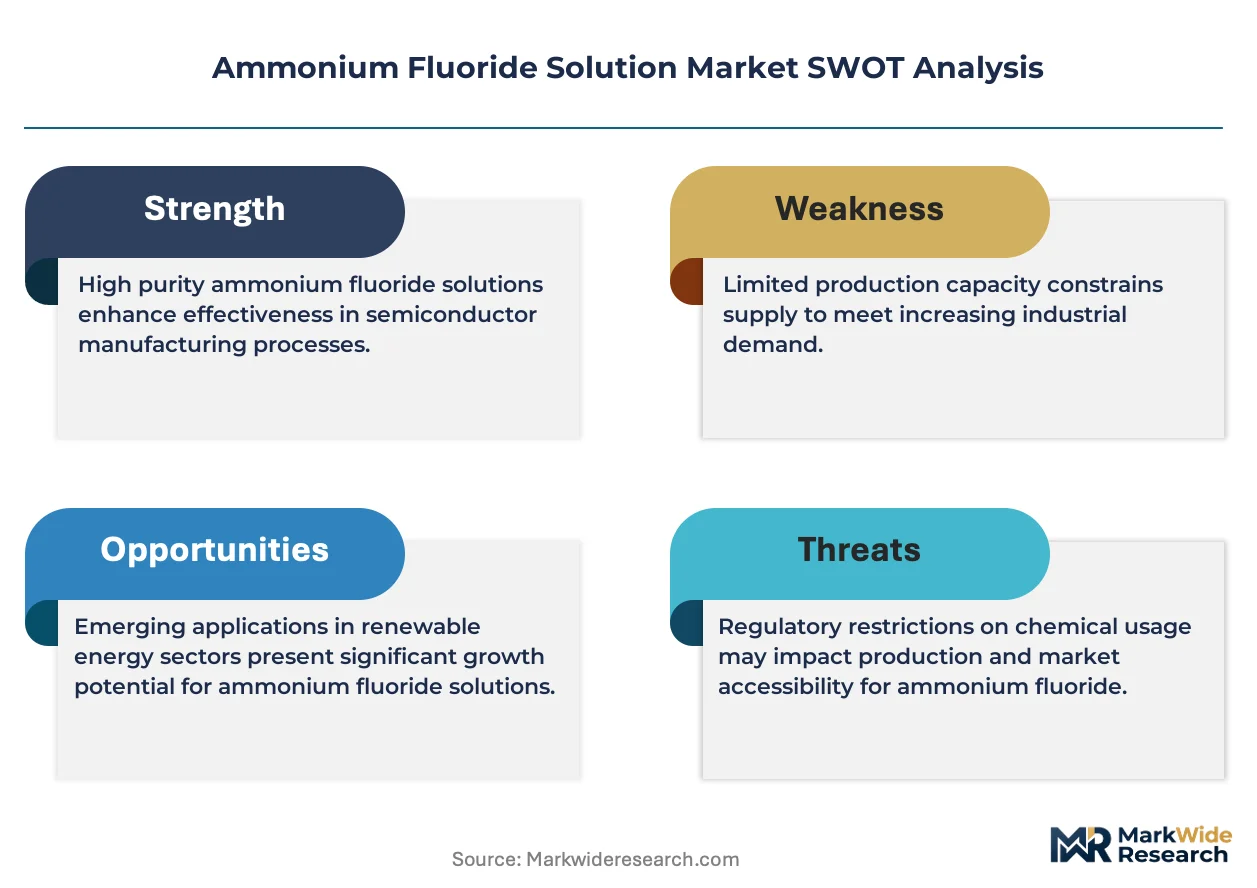
Hydrofluoric acid alternatives in wet etching is repositioning ammonium fluoride solution as a safer, more controllable chemistry for sub-7nm chip fabrication. Solvay leverages its integrated fluorochemical chain to secure electronics-grade supply contracts across European fabs. Stella Chemifa anchors Japanese semiconductor material flows through dedicated ultra-pure production lines. Juhua Group dominates domestic Chinese volume through captive hydrogen fluoride feedstock and regional distribution density.
Ammonium fluoride solution is an inorganic compound (NH₄F) typically supplied as an aqueous liquid at concentrations between 40% and 50% by weight, functioning as a buffered fluoride source for controlled silicon oxide and silicon nitride etching in semiconductor wafer processing. Industrial-grade formulations serve metal finishing and glass frosting applications where moderated fluoride activity prevents substrate damage. Liquid product type leads shipment volumes due to handling efficiency in automated fab chemical delivery systems, while reagent-grade specifications capture the highest margin pools from EUV lithography-compatible purity requirements. Semiconductor end-user demand outpaces chemical manufacturing offtake as foundry capital expenditure shifts toward advanced node capacity.
EPA hazardous waste rules and OSHA permissible exposure limits constrain US production site permitting and worker safety compliance costs for ammonium fluoride manufacturers. REACH registration and the EU F-Gas Regulation impose downstream tracking obligations on fluorinated chemical supply chains entering European electronics markets. China's MEE enforces wastewater fluoride discharge standards that filter smaller producers from supplying tier-one semiconductor fabs. Stakeholders must monitor regulatory divergence between jurisdictions as purity certifications become the decisive barrier for qualifying new supply sources.
Market Dynamics
Semiconductor foundry migration toward sub-5nm nodes is forcing ammonium fluoride solution suppliers to recalibrate purity specifications and regional production footprints simultaneously.
Growth Catalysts
- Advanced Node Etching Demand:Sub-7nm logic and memory fabs require buffered fluoride chemistries with metallic impurity levels below 10 parts per trillion. This specification tier commands supply priority from qualified producers.
- REACH Article 33 Compliance:Electronics-grade ammonium fluoride meeting RoHS restricted substance thresholds secures automatic qualification for EU semiconductor material procurement frameworks.
- Pyeongtaek Cluster Expansion:Samsung and SK Hynix capacity additions in South Korea's Gyeonggi province are concentrating regional demand for just-in-time chemical delivery systems.
Market Restraints
- Hydrogen Fluoride Feedstock Volatility:Anhydrous HF pricing fluctuations transmit directly to ammonium fluoride solution cost structures, compressing margin predictability for non-integrated producers.
- Chinese Supply Concentration:Captive HF production by domestic conglomerates limits third-party ammonium fluoride entrants from securing competitively priced raw material in the Yangtze River Delta corridor.
- Aqueous Transport Constraints:Corrosive liquid classification under IMDG and ADR regulations elevates cross-border logistics costs and restricts intercontinental sourcing flexibility for fabs.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for domestic chip fabrication create virgin demand territory absent entrenched supplier relationships.
- EUV Resist Stripping Applications:Post-lithography cleaning processes are adopting dilute ammonium fluoride formulations as alternatives to solvent-based chemistries.
- On-Site Generation Systems:Modular production units at fab perimeters bypass transport regulatory burdens while securing supply continuity for critical etching operations.
Industry Challenges
- Ultra-Pure Certification Timelines:SEMI Standard C3 qualification for advanced node supply requires 18-24 month validation cycles that lock out new entrants during demand surges.
- Fluoride Wastewater Treatment:MEE discharge limits in China and EPA effluent guidelines in the US force capital-intensive calcium fluoride precipitation infrastructure at production sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Fluoride Solution Market |
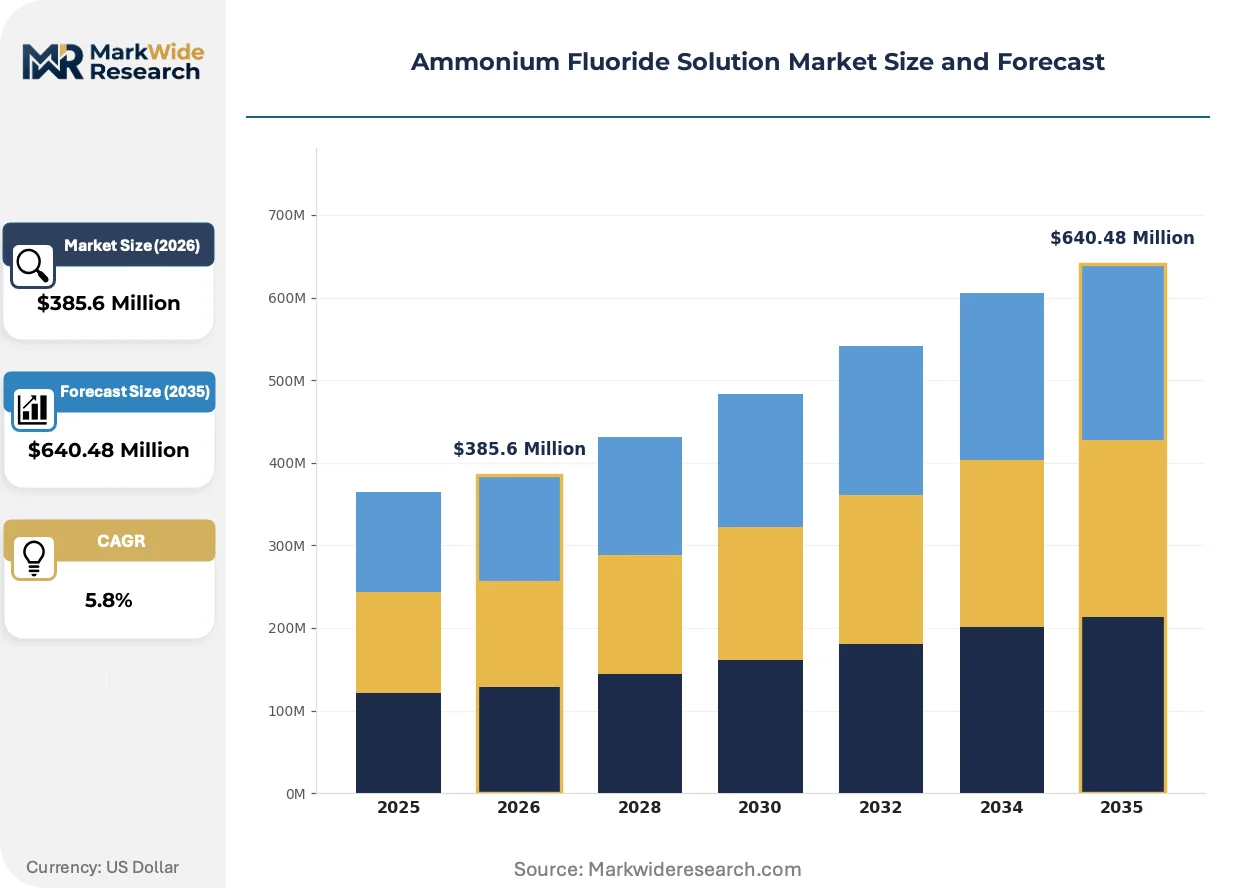
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Crystalline, Powder, Granular Grade: Reagent Grade, Industrial Grade, Technical Grade, Pharmaceutical Grade Application: Etching Agent, Cleaner, Electronics, Metal Finishing End User: Chemical Manufacturing, Semiconductor, Laboratory, Construction |
| Companies Covered | Solvay, Stella Chemifa, Taisu Daikin, Fujian Kings Fluoride, Juhua Group, Fubao Group, Morita Chemical Industries, Zibo Linzi Liyuan Chemical, Yingpeng Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Fluoride Solution Market Trends and Innovations
Wet etching chemistry is undergoing specification bifurcation as leading-edge fabs separate from legacy node producers in purity requirements and supply chain governance.
Point-of-use filtration with 0.03-micron-rated membranes is overtaking centralized bulk chemical distribution in advanced semiconductor facilities. Taiwan Semiconductor Manufacturing and Intel Foundry Services have adopted pod-based delivery with inline final filtration. This architecture compresses contamination risk windows and reduces fab-side chemical handling infrastructure.
EU F-Gas Regulation phasedown schedules are tightening reporting obligations for fluorinated compound imports into European electronics markets. Downstream users must now document supply chain custody from primary chemical manufacture through fab consumption. German and Dutch semiconductor clusters are prioritizing suppliers with ECHA-registered substance dossiers and third-party verified carbon footprint disclosures.
Long-term purchase agreements with fixed volume floors are displacing spot market procurement for electronics-grade ammonium fluoride. Samsung's Materials Business Group and Intel's Supply Chain Organization have pioneered five-year contracts with price reopener clauses tied to HF feedstock indices. This contracting model concentrates procurement leverage among top-tier foundries while marginalizing smaller fabless design houses in chemical allocation priority.
Ammonium Fluoride Solution Market Segmentation
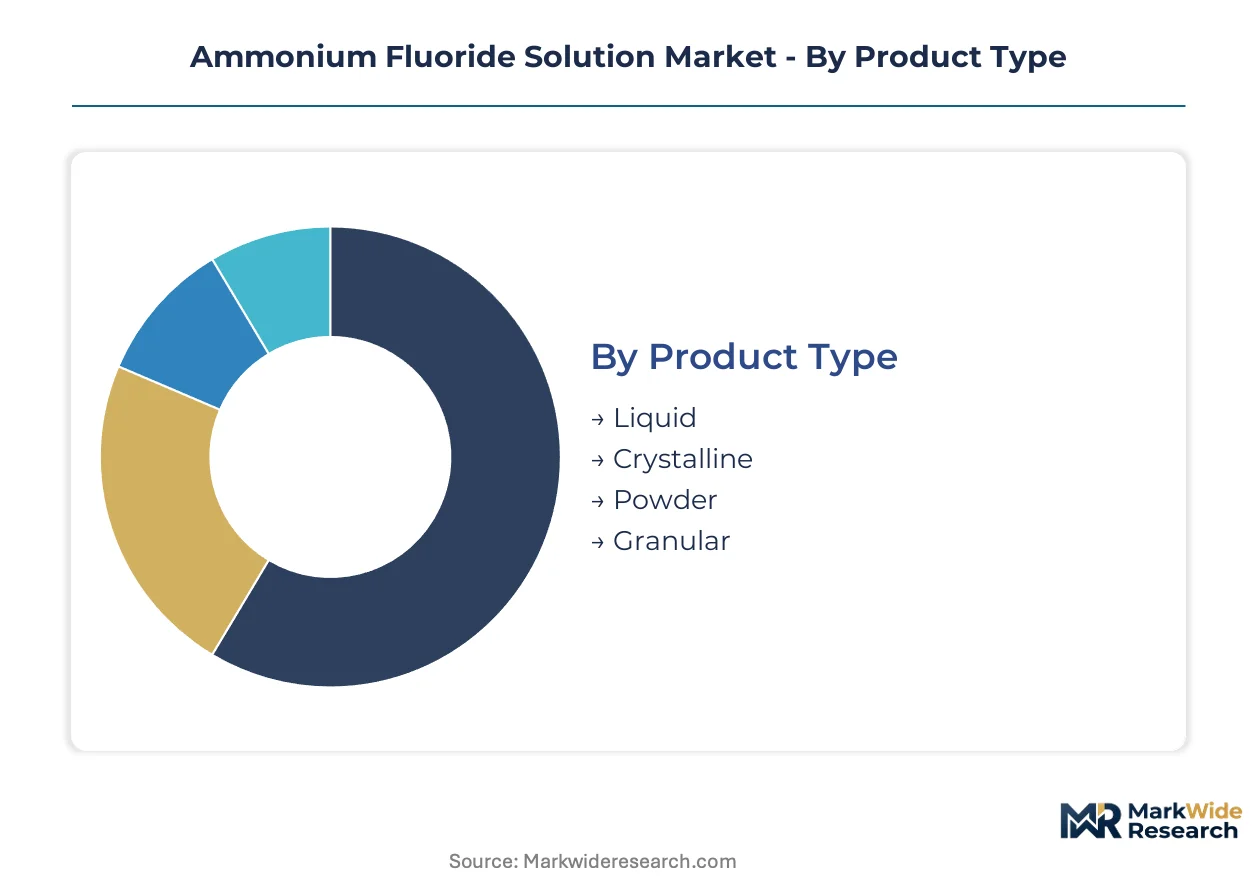
Segmentation in ammonium fluoride solution markets tracks the divergence between high-purity electronics specifications and commodity industrial applications. Each dimension reveals distinct buyer priorities, from SEMI C3 certification thresholds in semiconductor fabs to cost-per-kilogram efficiency in metal finishing operations.
Product Type:
Liquid formulations dominate procurement decisions where automated chemical delivery systems and contamination control drive total cost of ownership calculations.
- Liquid:Aqueous solutions at 40-50% concentration enable direct integration with fab chemical distribution infrastructure. Samsung's Pyeongtaek cluster and Intel's Arizona fabs specify liquid delivery with point-of-use filtration to compress contamination risk windows.
- Crystalline:Solid-phase NH₄F offers extended shelf stability and reduced transport classification burdens for remote semiconductor facilities. Taiwan Semiconductor Manufacturing sources crystalline material for on-site dissolution systems at select legacy node facilities.
- Powder:Fine particulate grades serve laboratory reagent preparation and small-batch electronics cleaning where precise concentration control matters.
- Granular:Coarse crystalline forms support metal finishing tank maintenance and glass etching operations requiring moderated fluoride release rates.
Volume sits with Liquid; growth tilts toward Crystalline.
Grade:
Purity certification tiers separate qualified semiconductor suppliers from commodity chemical producers, with metallic impurity specifications spanning six orders of magnitude.
- Reagent Grade:Metallic impurities below 10 parts per trillion meet EUV lithography and sub-7nm etching requirements. Reagent-grade supply concentrates among producers with SEMI Standard C3 qualification and ECHA-registered REACH dossiers.
- Industrial Grade:Moderated purity specifications serve glass frosting, wood preservation, and general metal finishing where substrate damage prevention outweighs trace contamination concerns. China's Yangtze River Delta metalworking clusters absorb regional industrial-grade volume.
- Technical Grade:Intermediate purity tier bridges electronics and industrial applications, capturing printed circuit board cleaning and photovoltaic cell texturing demand.
- Pharmaceutical Grade:USP-compliant specifications support dental fluoride preparations and pharmaceutical intermediates with documented batch traceability.
Revenue concentrates in Reagent Grade; expansion accelerates fastest in Technical Grade.
Application:
End-use chemistry requirements dictate formulation buffering, concentration precision, and packaging protocols across divergent process environments.
- Etching Agent:Buffered fluoride chemistry selectively removes silicon oxide and silicon nitride layers in wafer patterning. Sub-5nm logic nodes require etching agents with particle counts below 0.03 microns per milliliter.
- Electronics:Post-lithography cleaning and resist stripping applications are adopting dilute ammonium fluoride formulations as alternatives to solvent-based chemistries at Samsung and SK Hynix facilities.
- Cleaner:Precision cleaning of vacuum chambers and process equipment employs controlled fluoride activity to remove metallic residues without substrate attack.
- Metal Finishing:Surface activation and oxide removal in electroplating pre-treatment lines utilize industrial-grade formulations where process control tolerances are wider.
Etching Agent commands the premium pricing tier; Electronics is climbing the fastest.
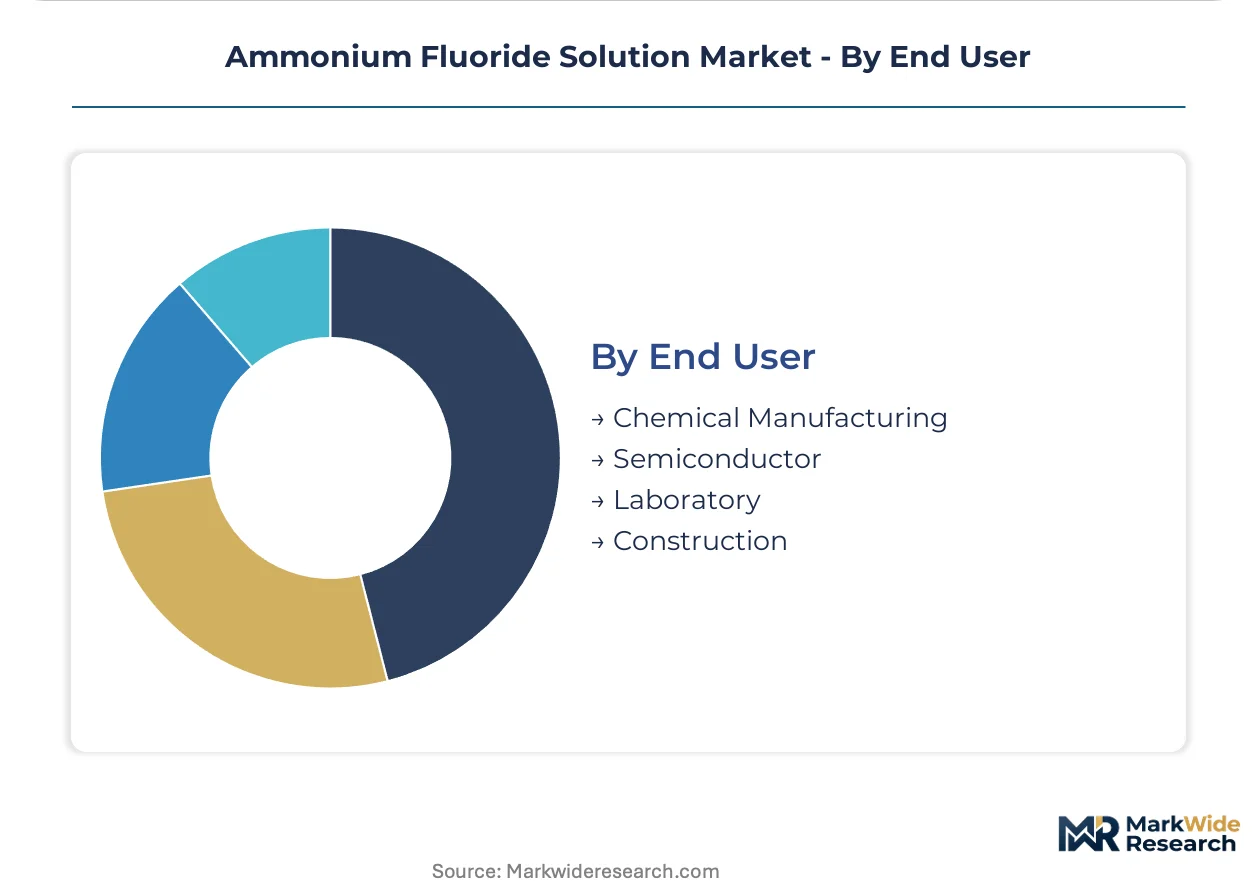
End User:
Customer scale and qualification requirements fragment supply relationships between multinational foundries and dispersed industrial accounts.
- Semiconductor:Foundry capital expenditure on advanced node capacity concentrates demand among qualified suppliers with five-year contract structures. Intel's Supply Chain Organization and Samsung's Materials Business Group negotiate volume floors tied to hydrogen fluoride feedstock indices.
- Chemical Manufacturing:Downstream formulators repackage ammonium fluoride into blended etching solutions and specialty cleaning chemistries for resale to electronics and industrial markets.
- Laboratory:Research institutions and analytical facilities consume reagent-grade material in gram-to-kilogram quantities with stringent documentation requirements.
- Construction:Concrete surface treatment and specialty glass manufacturing absorb technical-grade volume in regional construction chemical supply chains.
Semiconductor dominates procurement leverage; Chemical Manufacturing offers the most stable offtake profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyeongtaek's semiconductor cluster anchors East Asian demand concentration, while China's Yangtze River Delta special economic zones drive captive supply integration. EPA and OSHA frameworks in the United States elevate compliance costs for non-integrated producers. European REACH dossiers and F-Gas Regulation tracking concentrate procurement leverage among ECHA-registered suppliers.
China
MEE wastewater fluoride discharge standards filter smaller producers from tier-one semiconductor fabs. Juhua Group's captive hydrogen fluoride feedstock secures cost advantages in the Yangtze River Delta corridor. Zhejiang and Jiangsu provinces concentrate electronics-grade formulation capacity near Shanghai's lithography equipment hubs.
South Korea
Samsung and SK Hynix expansion in Gyeonggi province concentrates just-in-time chemical delivery demand. Korean environmental ministry enforcement of industrial effluent standards elevates production site compliance investments. Pyeongtaek's semiconductor mega-cluster hosts dedicated ultra-pure ammonium fluoride buffer facilities.
United States
Intel Foundry Services and Texas Instruments drive advanced node etching chemistry procurement. EPA hazardous waste rules and OSHA permissible exposure limits constrain greenfield production site permitting. Arizona and Oregon fabs specify point-of-use filtration systems with liquid delivery integration.
Japan
Stella Chemifa anchors ultra-pure production lines through dedicated semiconductor material flows. METI industrial policy supports domestic etching chemistry supply chain resilience. Kyushu and Hiroshima prefectures concentrate legacy and advanced node fab capacity with regional supplier qualification.
Germany
Solvay leverages integrated fluorochemical chains to secure electronics-grade supply contracts across European fabs. EU F-Gas Regulation phasedown schedules tighten import reporting obligations for fluorinated compounds. Saxony-Anhalt's chemical corridor hosts REACH-registered production with third-party verified carbon disclosures.
Ammonium Fluoride Solution Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with reagent-grade supply consolidating around SEMI-qualified producers while industrial-grade fragments across regional formulators. Three archetypes dominate: integrated fluorochemical conglomerates with captive HF feedstock, ultra-pure specialists with dedicated fab qualification teams, and regional distributors repackaging technical-grade volume. Competitive moves concentrate on backward integration into anhydrous HF production and five-year contract structures with price reopener clauses.
Within the integrated conglomerate tier, Solvay and Juhua Group exemplify upstream control strategies that compress raw material cost volatility. Stella Chemifa occupies a position among ultra-pure specialists serving Japanese and Taiwanese foundry networks. These three anchors represent divergent geographic and structural approaches to securing semiconductor material procurement frameworks.
| Leading Market Players |
|---|
| Solvay |
| Stella Chemifa |
| Taisu Daikin |
| Fujian Kings Fluoride |
| Juhua Group |
| Fubao Group |
| Morita Chemical Industries |
| Zibo Linzi Liyuan Chemical |
| Yingpeng Chemicals |
| Others |
Pricing and Supply Chain Analysis
Captive hydrogen fluoride production anchors supply positioning and pricing power across the ammonium fluoride solution market. Juhua Group's in-house HF feedstock insulates margin structures from raw material volatility that compresses non-integrated competitors in China's Yangtze River Delta corridor.
Pricing Analysis
Volume concentrates in industrial-grade formulations while margins concentrate in reagent-grade supply. Three-tier pricing structure across reagent, technical, and industrial grades separates SEMI C3-qualified producers from commodity formulators. Cost compression in technical-grade segments is intensifying because captive HF producers in China flood regional markets with undifferentiated supply. Chemical manufacturing end-users exhibit highest price sensitivity due to repackaging margin constraints, while semiconductor fabs prioritize qualification status over unit cost.
Supply Chain Analysis
Skilled chemical process engineers concentrate in Zhejiang, Jiangsu, and Gyeonggi provinces where semiconductor material production clusters have matured. Supply draws from anhydrous HF, ammonia, and high-purity water inputs. Single-source vulnerability runs through Chinese HF feedstock concentration amid export licensing uncertainties. Distribution runs through just-in-time chemical delivery systems at fab perimeters, bypassing traditional warehousing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH Article 33 and SEMI Standard C3 certification erect barrier-to-entry moats. ECHA-registered dossiers and third-party verified purity documentation now separate qualified suppliers from price-competitive but unqualified regional formulators.
For Market Incumbents: Hedge against hydrogen fluoride feedstock volatility through backward integration into anhydrous HF production or long-term purchase agreements with price reopener clauses. Solvay's integrated fluorochemical chain exemplifies upstream control that secures electronics-grade contract renewals. Capacity expansion in India's Gujarat or Karnataka clusters captures PLI scheme incentives before supplier relationships crystallize. For New Entrants and Emerging Players: EUV resist stripping technology offers a technology-first wedge into post-lithography cleaning applications where solvent substitution creates virgin specification requirements. India's Semiconductor Mission presents the most penetrable geography absent entrenched supplier relationships. Target on-site generation system partnerships with emerging fabs seeking supply continuity without transport regulatory burdens. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking semiconductor material portfolio expansion. Long-term viability hinges on qualification timeline compression and captive feedstock access. Watch for MEE wastewater enforcement actions in China as inflection indicators that filter marginal producers and concentrate share among compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anhydrous HF | Juhua Group's captive feedstock secures cost advantages in Yangtze River Delta supply. |
| SEMI Standard C3 Qualification Investment | EUV-compatible purity certification unlocks five-year contract structures with Intel and Samsung. |
| On-Site Generation System Deployment | Modular fab-perimeter units bypass IMDG transport classification and secure supply continuity. |
| India Semiconductor Mission Partnership | PLI scheme incentives create virgin demand territory before supplier relationships entrench. |
| REACH Dossier Registration Completion | ECHA-registered substances secure automatic qualification for EU foundry procurement frameworks. |
Research Methodology
SEC 10-K filings, customs and trade databases, and semiconductor industry association reports formed the secondary backbone of this analysis. Primary interviews with plant managers at ammonium fluoride production facilities, procurement leads at downstream foundries, technical R&D directors at fluorochemical specialists, and distribution channel partners in East Asia validated secondary findings. Bottom-up and top-down triangulation cross-checked volume estimates against hydrogen fluoride feedstock consumption patterns and fab capacity announcements.
Bottom-up modeling aggregated segment-level demand across grade tiers, end-use applications, and regional production hubs. Top-down constraints calibrated aggregate market size against anhydrous HF supply availability and semiconductor capital expenditure flows. CAGRs derived from regression analysis of historical foundry capacity additions and purity specification escalation trends. Modeled inputs included EUV lithography adoption curves, REACH enforcement intensity, and on-site generation system penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden MEE wastewater enforcement escalations or HF feedstock export restrictions. Forecasts reflect documented assumptions regarding foundry capital expenditure continuity and regulatory compliance cost trajectories. Material deviation in SEMI qualification timelines or REACH registration deadlines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Embossing Powder Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Drug Formulation Market