
 Anti-Gelling Agent Market | 2026-2036
Anti-Gelling Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Gelling Agent Market Analytics
REACH is broadening the cost-of-entry calculus for synthetic anti-gelling agent suppliers entering European coatings and personal care markets. DuPont de Nemours, Inc. leverages its fluoropolymer heritage to navigate stricter substance authorization requirements. Cargill, Incorporated anchors its position through backward integration into plant-derived feedstocks for bio-based alternatives. Ingredion Incorporated differentiates via enzymatic modification platforms that reduce reliance on petrochemical precursors.
Anti-gelling agents are chemical additives that disrupt intermolecular hydrogen bonding or polymer cross-linking to maintain fluid viscosity stability across temperature and shear variations, typically dosed at 0.1–2.0% w/w depending on base fluid chemistry. These compounds prevent gelation in hydraulic fracturing fluids, food starch slurries, and cosmetic emulsions where uncontrolled thickening would halt processing or degrade product performance. Natural anti-gelling agents derived from cellulose derivatives and plant gums command premium positioning in food and pharmaceutical applications where clean-label requirements restrict synthetic options. Synthetic variants still dominate oil and gas applications due to predictable thermal degradation profiles and lower unit costs at bulk scale. Powder and granular forms lead in chemical manufacturing end uses where dry blending integrates with existing compounding lines, while liquid emulsions gain ground in personal care for easier cold-process formulation.
The EPA regulates anti-gelling agents used in oilfield applications under the Toxic Substances Control Act, requiring premanufacture notification for novel chemistries while the FDA governs food-contact and pharmaceutical grades through food additive petitions and drug master files. BIS certification in India adds another compliance layer for suppliers targeting downstream chemical manufacturing in that market. Stakeholders must monitor how evolving per- and polyfluoroalkyl substance restrictions in multiple jurisdictions reshape acceptable molecular architectures for high-performance synthetic grades.
Market Dynamics
REACH authorization timelines are compressing the synthetic anti-gelling agent supplier base in Europe, forcing accelerated reformulation investments and selective market exits before 2030 substance evaluation deadlines.
Growth Catalysts
- Hydraulic fracturing intensity:High-volume slickwater operations in US shale basins require reliable flow assurance additives that maintain viscosity stability across temperature and shear variations.
- REACH substance authorization:European chemical reformulation mandates are redirecting R&D budgets toward bio-based molecular architectures with compliant degradation profiles.
- Clean-label food processing:Consumer preference for recognizable ingredient lists is elevating demand for cellulose-derived and plant-gum anti-gelling agents in starch slurry applications.
Market Restraints
- Petrochemical feedstock volatility:Synthetic anti-gelling agent production remains exposed to propylene oxide and ethylene oxide price swings that compress formulation margins.
- Fluoropolymer regulatory friction:Per- and polyfluoroalkyl substance restrictions across multiple jurisdictions are narrowing the addressable market for high-performance synthetic grades with thermal stability advantages.
- Natural extract supply concentration:Guar gum and locust bean gum sourcing clusters in India and Pakistan create geographic concentration risk for bio-based alternatives.
Strategic Opportunities
- Enzymatic modification platforms:Biotechnology approaches that reduce reliance on petrochemical precursors are opening premium positioning in pharmaceutical and cosmetic applications.
- India chemical manufacturing:BIS certification requirements create a protected market segment for compliant suppliers targeting downstream compounding operations.
- Dual carbon policy alignment:China's national carbon neutrality targets are incentivizing domestic producers to develop plant-derived feedstock supply chains for export competitiveness.
Industry Challenges
- Cross-jurisdictional substance authorization:Suppliers must maintain parallel EPA TSCA premanufacture notifications, REACH dossiers, and FDA food additive petitions with divergent data requirements.
- Legacy formulation integration:Oilfield service companies face technical friction when substituting bio-based anti-gelling agents into established hydraulic fracturing fluid systems with validated performance baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Gelling Agent Market |
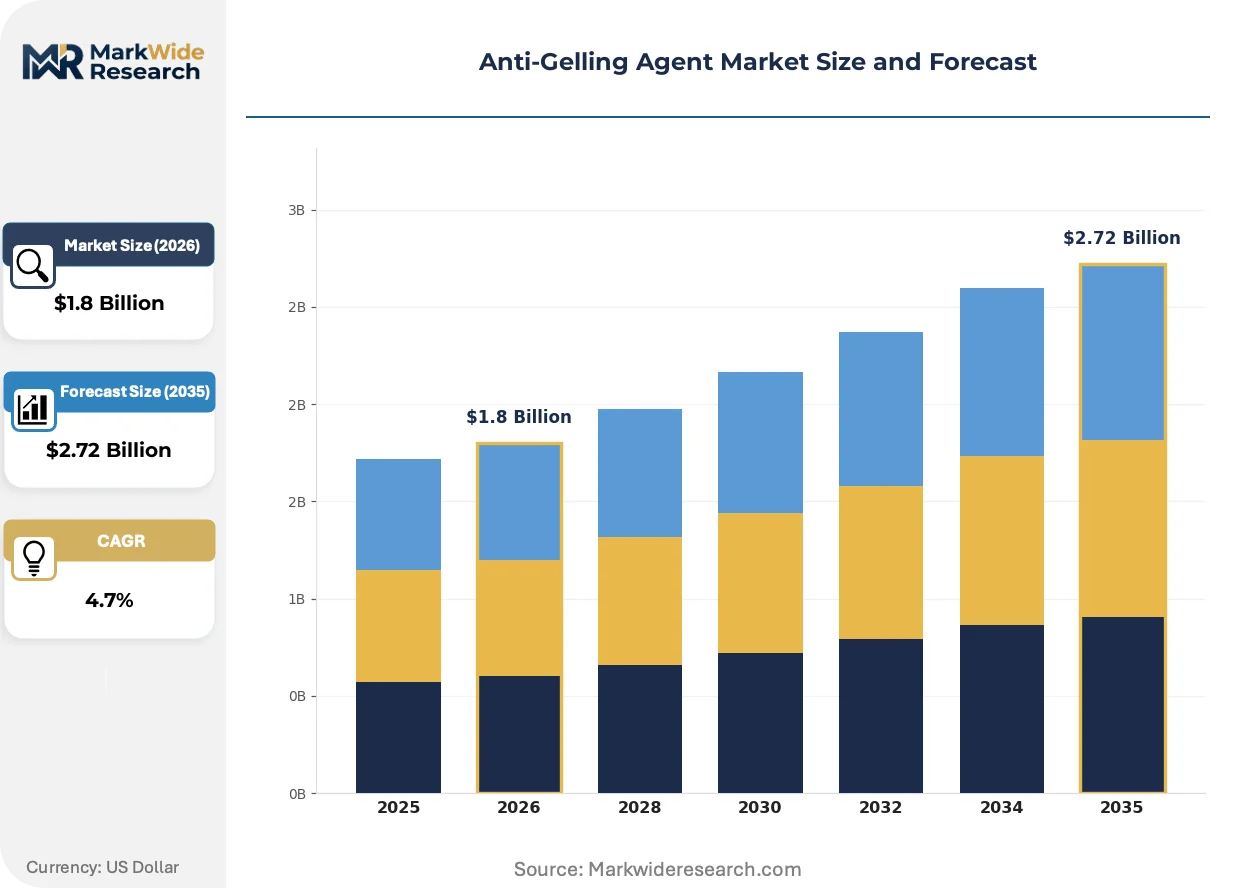
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Semi-Synthetic, Bio-Based Application: Food Preservation, Oil & Gas, Personal Care, Coatings End User: Food Industry, Chemical Manufacturing, Cosmetic Industry, Pharmaceuticals Form: Liquid, Powder, Granular, Emulsion |
| Companies Covered | DuPont de Nemours, Inc., Ingredion Incorporated, Cargill, Incorporated, International Flavors and Fragrances, Ashland Global Holdings, Archer Daniels Midland Company, Kerry Group plc, Gelita AG, Tate and Lyle plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Gelling Agent Market Evolving Landscape
Formulation science is converging with biotechnology to reduce petrochemical dependency while maintaining performance thresholds in high-stress applications.
Enzymatic modification of polysaccharide feedstocks is unifying the performance gap between synthetic and natural anti-gelling agents. Food and pharmaceutical manufacturers are adopting these hybrid architectures at accelerated pilot scales. The technology is unifying previously separate supplier categories into integrated biotech-chemical platforms that control molecular architecture from fermentation through functionalization.
REACH authorization deadlines are compressing the viable synthetic chemistry set for European coatings and personal care applications. ECHA substance evaluation timelines are forcing premature product lifecycle exits for non-compliant molecular architectures. Oilfield chemical suppliers with European exposure are redirecting reformulation investments toward bio-based alternatives with compliant degradation profiles.
Specification-driven procurement is consolidating buyer power among oilfield service companies and multinational food processors. Long-term supply agreements with embedded technical service requirements are displacing spot-market purchasing for critical viscosity control additives. This consolidation is most visible in US shale basins where operator consolidation has reduced the number of qualified chemical procurement decision points.
Anti-Gelling Agent Market Segmentation
Anti-gelling agent procurement patterns diver sharply across end-use verticals, with oilfield operators prioritizing thermal stability specifications while food manufacturers enforce clean-label compliance thresholds that reshape supplier qualification criteria.
Product Type:
Supply concentration for synthetic grades in Texas and Louisiana petrochemical corridors contrasts with dispersed agricultural sourcing for bio-based alternatives across Midwest processing facilities.
- Natural:Cellulose derivatives and plant gums extracted from guar and locust bean clusters in India and Pakistan serve food and pharmaceutical applications where FDA food additive petitions and clean-label requirements restrict synthetic options. Demand concentrates in starch slurry processing for ready-to-eat meals and controlled-release drug formulations.
- Synthetic:Ethylene oxide and propylene oxide derivatives manufactured along the US Gulf Coast dominate hydraulic fracturing fluids in Permian and Marcellus shale basins, delivering predictable thermal degradation profiles that oilfield service companies validate against established performance baselines.
- Semi-Synthetic:Chemically modified natural polymers bridge performance gaps in cosmetic emulsions.
- Bio-Based:Fermentation-derived architectures gain traction in European coatings reformulations driven by REACH authorization timelines.
Synthetic grades absorb the bulk of installed capacity; bio-based alternatives are expanding most quickly.
Application:
Volume scale separates commodity purchasers from specialty buyers, with shale operators consuming anti-gelling agents by the tanker-load against gram-scale dosing in pharmaceutical formulations.
- Oil & Gas:High-volume slickwater operations in US shale basins require reliable flow assurance additives dosed at 0.1–2.0% w/w to maintain viscosity stability across temperature and shear variations during hydraulic fracturing, with procurement consolidated among integrated oilfield service companies.
- Food Preservation:Cellulose-derived anti-gelling agents prevent uncontrolled thickening in starch slurries for processed foods, with clean-label preferences elevating plant-gum alternatives in applications governed by FDA food additive regulations.
- Personal Care:Liquid emulsion forms integrate into cold-process cosmetic formulations for easier manufacturing.
- Coatings:REACH-compliant reformulations in European industrial coatings redirect toward bio-based molecular architectures.
Oil & Gas commands the greatest absolute volume; Food Preservation is climbing the fastest as clean-label requirements harden.
End User:
Regulatory jurisdiction determines molecular architecture acceptance, with FDA drug master files governing pharmaceutical grades against EPA TSCA premanufacture notifications for oilfield applications.
- Food Industry:Multinational processors specify cellulose derivatives and plant gums for starch slurry applications where recognizable ingredient lists satisfy consumer clean-label demands, with supply agreements embedding technical service requirements that displace spot-market purchasing.
- Chemical Manufacturing:Powder and granular forms integrate with dry blending operations in downstream compounding facilities, with BIS certification requirements in India creating protected market segments for compliant suppliers.
- Cosmetic Industry:Cold-process formulation preferences favor liquid emulsion delivery systems.
- Pharmaceuticals:Enzymatic modification platforms reduce petrochemical precursor reliance in controlled-release drug applications.
Chemical Manufacturing absorbs the bulk of installed capacity; Pharmaceuticals is gaining share fastest on biotech platform adoption.
Form:
Physical state selection tracks manufacturing process integration, with dry blending lines in chemical manufacturing favoring powder and granular forms against liquid handling infrastructure in personal care.
- Powder:Dry blending compatibility dominates chemical manufacturing end uses where existing compounding lines integrate anti-gelling agents without process reconfiguration, with supply concentration in Midwest toll processing facilities serving regional formulators.
- Liquid:Emulsion forms penetrate personal care manufacturing for cold-process formulation ease, with dosing precision advantages in small-batch cosmetic production.
- Granular:Intermediate particle size reduces dust generation in food processing environments.
- Emulsion:Pre-dispersed architectures simplify incorporation into aqueous coating systems.
Powder absorbs the bulk of installed capacity; Liquid is expanding most quickly on personal care manufacturing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along the US Gulf Coast concentrate anti-gelling agent manufacturing capacity. Texas and Louisiana petrochemical corridors anchor synthetic production. REACH compliance timelines in Europe redirect investment toward bio-based alternatives.
United States
Permian and Marcellus shale basins drive hydraulic fracturing fluid demand. EPA TSCA premanufacture notifications govern novel chemistry introductions. Houston-area chemical manufacturing clusters process ethylene oxide derivatives for oilfield service companies.
Germany
REACH authorization deadlines compress viable synthetic chemistry sets for coatings applications. ECHA substance evaluation timelines force premature product lifecycle exits. Industrial chemical production concentrates in North Rhine-Westphalia's Ruhr Valley manufacturing belt.
China
Dual carbon policy targets incentivize plant-derived feedstock supply chain development. SAMR and MEE oversight shapes domestic chemical registration pathways. Yangtze River Delta chemical parks host fermentation-derived architecture pilot facilities.
India
Guar gum sourcing clusters in Rajasthan and Gujarat serve food and pharmaceutical applications. BIS certification requirements create protected market segments for compliant suppliers. Maharashtra chemical manufacturing corridors integrate powder-form anti-gelling agents into dry blending operations.
United Kingdom
Cosmetic cold-process formulation preferences elevate liquid emulsion demand. UK REACH divergence from EU frameworks creates parallel compliance obligations. Southeast England personal care manufacturing hubs source enzymatically modified polysaccharide feedstocks.
Anti-Gelling Agent Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across product type boundaries. Market structure tilts toward consolidation among integrated chemical suppliers with captive feedstock positions. Three archetypes dominate: petrochemical-derived synthetic producers, agricultural-commodity processors with backward integration, and biotechnology platforms leveraging enzymatic modification. Capacity expansion and strategic partnerships represent the primary competitive vectors as firms secure compliant degradation profiles ahead of regulatory deadlines.
Within the diversified conglomerate tier, DuPont de Nemours, Inc. and Cargill, Incorporated exemplify contrasting feedstock strategies. DuPont occupies a position anchored in fluoropolymer heritage navigating stricter substance authorization requirements. Cargill sits within the agricultural-commodity processor archetype with upstream control over plant-derived feedstocks. Ingredion Incorporated represents the biotechnology platform approach, differentiating via enzymatic modification capabilities that reduce petrochemical precursor reliance.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Ingredion Incorporated |
| Cargill, Incorporated |
| International Flavors and Fragrances |
| Ashland Global Holdings |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Gelita AG |
| Tate and Lyle plc |
| Others |
Value Network & Pricing Analysis
REACH authorization timelines in Europe gate both qualified supply and premium-tier pricing access, compressing the viable synthetic chemistry set while elevating bio-based alternatives that command formulation premiums for compliant degradation profiles.
Pricing Analysis
Short lead-time premiums separate contract-based purchasers from spot-market buyers in hydraulic fracturing chemical procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FDA food additive petition holders capturing margin premiums in pharmaceutical applications. Cost compression in synthetic grades is intensifying because propylene oxide feedstock volatility erodes formulation margins. Oilfield service companies exhibit lowest price sensitivity due to performance validation requirements, while downstream chemical manufacturers in India face acute price pressure under BIS certification compliance costs.
Supply Chain Analysis
Ethylene oxide and propylene oxide derivatives rest on US Gulf Coast petrochemical corridors in Texas and Louisiana, with guar gum and locust bean gum sourcing anchored in Rajasthan and Gujarat clusters across India and Pakistan. Synthetic production draws from ethylene oxide, propylene oxide, and fluoropolymer feedstocks, while bio-based alternatives hinge on cellulose derivatives, plant gum extracts, and fermentation-derived polysaccharides. Single-source vulnerability concentrates in South Asian agricultural processing for natural grades. Distribution runs through integrated oilfield service companies with embedded technical service requirements displacing spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-gelling agent sector sits in a technology-transition phase as enzymatic modification platforms displace petrochemical-derived synthetic architectures across food, pharmaceutical, and cosmetic applications.
For Market Incumbents: Deploy backward integration into plant-derived feedstocks to secure compliant supply chains ahead of REACH authorization deadlines. Synthetic suppliers face substitution pressure from bio-based alternatives with validated degradation profiles; incumbents must accelerate enzymatic modification R&D investments to defend formulation margins in European coatings and personal care markets.
For New Entrants and Emerging Players: Enter via BIS-certified supply agreements targeting Maharashtra chemical manufacturing corridors where compliance requirements create protected market segments. White-space opportunity concentrates in fermentation-derived architectures for Chinese domestic producers aligning with dual carbon policy targets; go-to-market leverage rests on technical service partnerships with multinational food processors seeking clean-label starch slurry solutions.
For Investors and Strategic Acquirers: REACH substance evaluation deadline acceleration is the leading indicator that synthetic chemistry supplier base consolidation will intensify. Five-to-ten year viability favors biotechnology platforms with enzymatic modification capabilities over petrochemical-dependent synthetics; acquisition target archetype spans integrated biotech-chemical platforms controlling molecular architecture from fermentation through functionalization. Watch ECHA authorization timeline compression as the inflection signal for premature product lifecycle exits.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plant-Derived Feedstocks | Cargill's upstream control over agricultural supply chains anchors bio-based positioning ahead of REACH deadlines. |
| Enzymatic Modification Platform Investment | Ingredion's biotechnology capabilities reduce petrochemical precursor reliance in pharmaceutical-grade applications. |
| Long-term Supply Agreement with Embedded Technical Service | Oilfield service companies consolidate procurement power through performance-validated viscosity control contracts. |
| Joint Venture for Fermentation-Derived Architecture Scale-Up | Yangtze River Delta chemical parks host pilot facilities aligning with China's dual carbon policy targets. |
| Green Manufacturing Transition for REACH Compliance | European coatings reformulations redirect R&D budgets toward bio-based molecular architectures with compliant degradation profiles. |
Research Methodology
Document review covered SEC 10-K filings, ECHA substance evaluation dossiers, and customs trade data, complemented by interviews with plant managers at Gulf Coast petrochemical facilities, procurement leads at oilfield service companies, and technical R&D directors at food ingredient manufacturers. Secondary validation drew from FDA food additive petitions, EPA TSCA premanufacture notifications, and BIS certification records. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and regional production hub dimensions.
Segment-level value outputs tracked natural, synthetic, semi-synthetic, and bio-based grades across oil and gas, food preservation, personal care, and coatings applications throughout the forecast period. The analytical framework modeled end-use industry demand, formulation specification tiers, and regulatory compliance clusters. CAGRs derived from historical trajectory analysis adjusted for REACH authorization timeline compression and hydraulic fracturing intensity in US shale basins. Industry-specific inputs incorporated ethylene oxide feedstock pricing volatility and guar gum harvest yield variability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH substance restriction expansion or abrupt hydraulic fracturing activity contraction. Projections reflect assumptions around enzymatic modification technology maturation and bio-based feedstock supply chain scaling. A small set of named triggers—ECHA authorization deadline acceleration, EPA TSCA novel chemistry pathway changes, and South Asian agricultural supply disruption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Embossing Powder Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Gelling Agent Market