
 Global Formulation Development Outsourcing Market | 2026-2036
Global Formulation Development Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Formulation Development Outsourcing Market Foresight
Oncology and biologics pipelines from biotechnology firms is realigning formulation outsourcing demand toward complex parenteral and inhalation platforms. Lonza Group AG leverages its biologics manufacturing scale to anchor high-potency compound development. Catalent Inc. competes through integrated clinical-to-commercial packaging networks. Thermo Fisher Scientific Inc. dominates analytical development with its global laboratory footprint.
Formulation development outsourcing encompasses the transfer of drug product design, stability characterization, and process scale-up from pharmaceutical sponsors to specialized contract service providers, typically involving particle size engineering, excipient compatibility screening, and forced degradation studies under ICH Q1A conditions. The service generates value by compressing development timelines and reducing capital expenditure for sponsor companies lacking in-house capabilities. Pre-formulation and analytical development segments lead current revenue contribution due to their position at the front of development timelines. Injectable formulations represent the fastest-growing application category as monoclonal antibody and mRNA therapies expand. Commercialization support commands premium pricing through dedicated team engagement models that embed contract staff within sponsor quality systems.
FDA enforces Current Good Manufacturing Practice standards that dictate validation protocols for outsourced formulation batches, while EMA's ICH Q3D elemental impurity guidelines force additional analytical scope into development contracts. India's CDSCO and BIS frameworks impose parallel stability and bioequivalence requirements that shape local outsourcing specifications. Stakeholders must monitor evolving FDA quality metrics guidance and EMA revision timelines to calibrate capacity investments and geographic service expansion.
Market Dynamics
Biologics pipelines from biotechnology firms are compressing development timelines and forcing sponsors to externalize complex parenteral formulation work to specialized CDMOs with validated high-potency handling capabilities.
Growth Catalysts
- FDA Stability Requirements:Tightened ICH Q1A submission standards compel sponsors to outsource forced degradation studies and pre-formulation data packages to contract laboratories with established regulatory track records.
- mRNA Therapeutics:Lipid nanoparticle encapsulation complexity for nucleic acid drugs drives demand for specialized injectable formulation expertise beyond in-house pharmaceutical capabilities.
- Germany:Concentration of biologics manufacturing clusters around Basel-Lörrach creates spillover demand for integrated analytical and formulation development services.
Market Restraints
- Excipient Supply Concentration:Limited qualified suppliers of high-purity lipids and specialized polymers for complex injectables create input bottlenecks and price volatility.
- EMA ICH Q3D Compliance:Elemental impurity guidelines force additional analytical scope into development contracts, extending timelines and inflating fixed-cost structures.
- High-Potency Containment:Isolator technology and facility segregation requirements for cytotoxic compounds limit the addressable supplier base to capital-intensive CDMOs.
Strategic Opportunities
- Inhalation Platforms:Dry powder and nebulized biologic delivery remains underdeveloped relative to injectables, offering white space for formulation specialists with particle engineering capabilities.
- India CDSCO Alignment:Harmonization of stability and bioequivalence requirements with ICH standards positions Indian CDMOs to capture incremental sponsor volume seeking cost-optimized development paths.
- Continuous Manufacturing:Convergence of process analytical technology with formulation development enables real-time release testing and compresses scale-up cycles for commercial supply.
Industry Challenges
- Lyophilization Expertise Gap:Shortage of process engineers capable of designing robust freeze-dry cycles for unstable biologics constrains capacity expansion at mid-tier service providers.
- Technology Transfer Complexity:Integration of sponsor-developed cell lines and analytical methods into CDMO quality systems generates validation delays and batch failure risks during project onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Formulation Development Outsourcing Market |
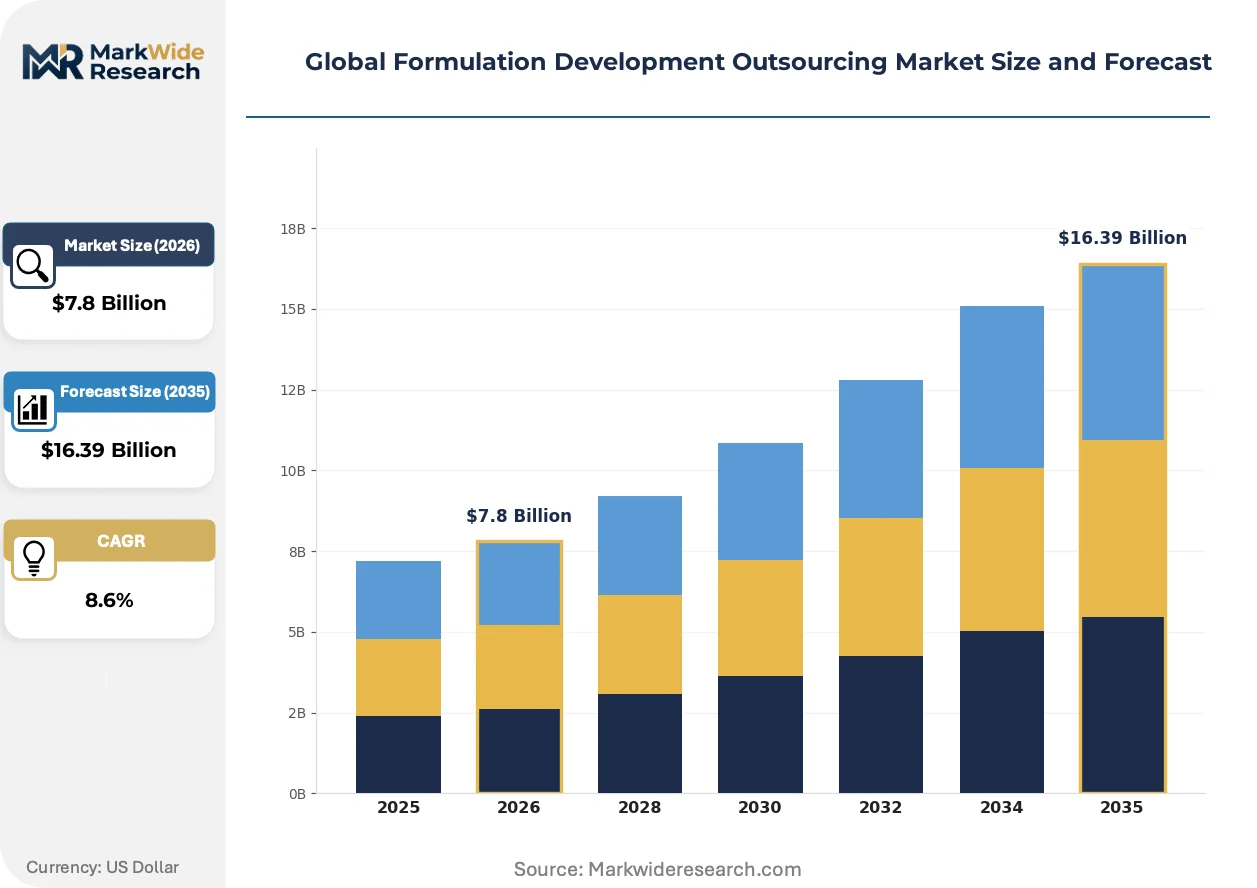
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pre-formulation, Formulation Design, Stability Testing, Analytical Development, Commercialization Support Application: Oral Solids, Topical Preparations, Injectable Formulations, Inhalation Products, Transdermal Systems End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Nutraceutical Developers, Vaccine Manufacturers Delivery Model: On-Premise, Remote Collaboration, Hybrid Model, Dedicated Team, Flexible Engagement |
| Companies Covered | Catalent Inc., Charles River Laboratories International, Inc., Lonza Group AG, Thermo Fisher Scientific Inc., Intertek Group plc, SGS S.A., Labcorp, Eurofins Scientific SE, Aizant Drug Research Solutions Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Formulation Development Outsourcing Market Shifts & Advancements
Formulation development outsourcing is absorbing digitalization pressures and quality-system convergence that reshape how sponsors select and manage contract partners across development phases.
Artificial intelligence platforms for excipient compatibility prediction and stability modeling are absorbing computational chemistry investments previously retained in-house. Mid-cap biotechnology firms without physical laboratory infrastructure are adopting these tools fastest. The technology is absorbing front-end development risk and compressing pre-formulation timelines from months to weeks.
EMA's revision timelines for ICH Q5A viral safety guidelines are forcing additional process characterization into early-phase contracts. Viral clearance validation for cell-derived biologics now requires parallel documentation that extends analytical development scope. European sponsors are responding by embedding contract staff within sponsor quality systems to accelerate regulatory dialogue.
Sponsor procurement teams are consolidating vendor panels and demanding integrated clinical-to-commercial service bundles that eliminate handoff friction. Traditional fee-for-service relationships are yielding to dedicated team engagement models with embedded FTE commitments. This pattern is most visible among United States-based oncology sponsors managing complex antibody-drug conjugate pipelines across multiple CDMO touchpoints.
Global Formulation Development Outsourcing Market Segmentation
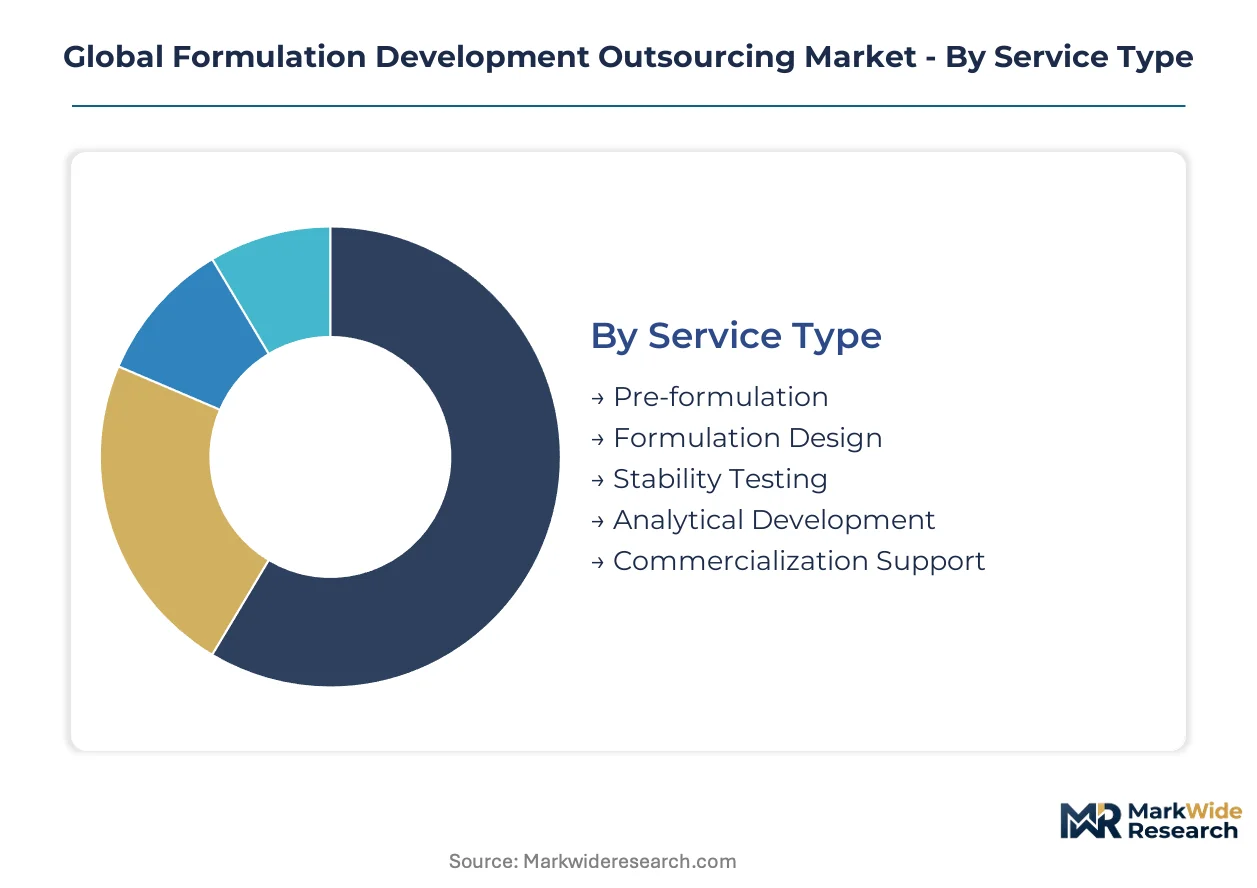
Service specialization in formulation development outsourcing determines how sponsors structure vendor relationships across development phases. Segment boundaries reflect technical capability depth, regulatory validation requirements, and the capital intensity needed to serve distinct therapeutic modalities.
Service Type:
Standalone analytical services operate independently from integrated development programs, while pre-formulation and stability testing embed into broader sponsor-CMO partnerships.
- Pre-formulation:Physicochemical characterization, solubility profiling, and excipient compatibility screening establish the foundation for downstream formulation decisions. Sponsors in Germany and the United States outsource these capabilities to compress early-phase timelines and avoid laboratory capital expenditure.
- Formulation Design:Active pharmaceutical ingredient processing into stable dosage forms requires particle engineering expertise and process analytical technology integration. Biotechnology firms developing monoclonal antibodies concentrate demand for high-potency parenteral formats in CDMOs with validated isolator infrastructure.
- Stability Testing:Forced degradation studies under ICH Q1A conditions generate regulatory submission packages.
- Analytical Development:Method validation and impurity profiling support quality control framework construction.
- Commercialization Support:Dedicated team engagement models embed contract staff within sponsor quality systems for technology transfer.
Volume placements concentrate in Analytical Development; the faster expansion belongs to Commercialization Support.
Application:
Route-of-administration selection drives facility specialization and containment requirements across CDMO networks.
- Injectable Formulations:Lipid nanoparticle encapsulation for mRNA therapeutics and antibody-drug conjugates demands sterile manufacturing suites and validated aseptic processing. United States oncology sponsors externalize these programs to CDMOs with FDA-inspected high-potency capabilities.
- Inhalation Products:Dry powder and nebulized biologic delivery requires particle size engineering and cascade impaction testing. European sponsors in Switzerland and Germany pursue these platforms for respiratory and systemic biologic administration.
- Oral Solids:Tablet and capsule development remains the largest application by project volume.
- Topical Preparations:Semi-solid formulation for dermatological and transdermal delivery.
- Transdermal Systems:Patch-based drug delivery with adhesion and permeation optimization.
Injectable Formulations command premium pricing tiers; Inhalation Products are climbing the fastest.
End User:
Customer scale and internal capability depth determine outsourcing scope and contract structure preferences.
- Biotechnology Firms:Mid-cap companies without manufacturing infrastructure externalize entire development sequences from pre-formulation through commercialization. These sponsors in the United States and India adopt flexible engagement models and AI-enabled excipient screening to compensate for limited in-house analytical capacity.
- Pharmaceutical Companies:Large sponsors selectively outsource complex formats while retaining oral solid capabilities internally.
- Contract Research Organizations:Service providers subcontracting specialized formulation capabilities.
- Nutraceutical Developers:Dietary supplement and functional food formulation outsourcing.
- Vaccine Manufacturers:Adjuvant formulation and thermostability optimization for immunization products.
Pharmaceutical Companies anchor contract value; Biotechnology Firms are expanding most quickly.
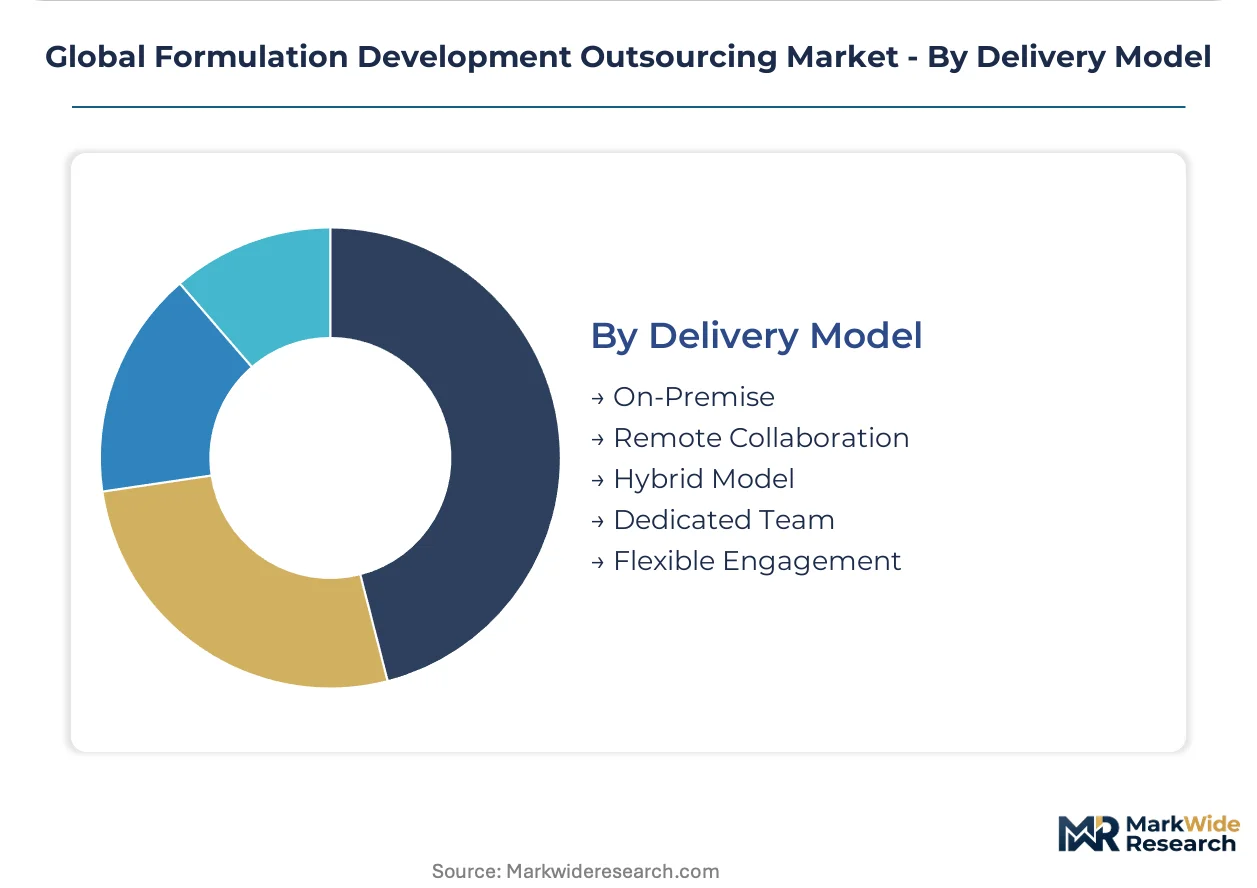
Delivery Model:
Engagement structure reflects sponsor risk tolerance, project complexity, and the need for regulatory integration depth.
- Dedicated Team:Embedded FTE commitments with full integration into sponsor quality systems and regulatory submission processes. Oncology sponsors managing multi-CDMO antibody-drug conjugate pipelines in the United States favor this model to accelerate FDA dialogue and reduce handoff friction.
- Hybrid Model:Blended on-site and remote collaboration combining physical laboratory access with digital project management.
- On-Premise:Full-time sponsor personnel at CDMO facilities for technology transfer oversight.
- Remote Collaboration:Digital-first project execution with limited physical presence.
- Flexible Engagement:Milestone-based contracts with variable scope adjustment.
Dedicated Team structures capture the largest contract values; Hybrid Models are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and pharmaceutical clusters around Basel-Lörrach concentrate formulation development capacity through targeted tax incentives and infrastructure investment. These zones attract sponsor companies seeking cost-optimized development paths and integrated analytical services.
United States
Oncology sponsors and mRNA therapeutic developers drive demand for high-potency parenteral formulation expertise. FDA enforces Current Good Manufacturing Practice standards that dictate validation protocols for outsourced batches. The Greater Boston and San Francisco Bay Area biotech corridors concentrate CDMO partnerships for antibody-drug conjugate pipelines.
Germany
Biologics manufacturing clusters around Basel-Lörrach generate spillover demand for integrated analytical and formulation development services. EMA's ICH Q3D elemental impurity guidelines force additional analytical scope into development contracts. The Rhine-Neckar and Munich regions host specialized CDMOs with validated isolator infrastructure for cytotoxic compounds.
India
Mid-cap biotechnology firms without manufacturing infrastructure externalize entire development sequences from pre-formulation through commercialization. CDSCO and BIS frameworks impose parallel stability and bioequivalence requirements that shape local outsourcing specifications. Hyderabad and Mumbai pharmaceutical corridors attract sponsor volume seeking cost-optimized development paths with ICH-aligned quality systems.
Switzerland
Specialized inhalation and biologic delivery platforms concentrate around Basel's cross-border pharmaceutical ecosystem. Swissmedic stability requirements align with EMA submission standards for pre-formulation data packages. The Basel-Lörrach tri-national region anchors high-potency compound development through shared regulatory track records.
United Kingdom
Cell and gene therapy developers externalize complex formulation work to CDMOs with viral clearance validation capabilities. MHRA post-Brexit regulatory alignment with ICH Q5A guidelines extends analytical development scope for cell-derived biologics. The Cambridge-Oxford-London golden triangle concentrates sponsor demand for integrated clinical-to-commercial service bundles.
Global Formulation Development Outsourcing Market Competitive Landscape
Top-tier vendors anchor integrated biologics manufacturing, while mid-cap specialists occupy niche formulation segments. The vendor base stratifies across three capability tiers: full-service CDMOs with global laboratory footprints, regional players with specialized containment infrastructure, and analytical-focused laboratories serving front-end development. Two dominant competitive moves reshape positioning: dedicated team engagement models that embed contract staff within sponsor quality systems, and M&A activity targeting particle engineering and lyophilization expertise.
Within the full-service CDMO tier, Lonza Group AG and Catalent Inc. represent archetypes of scale-driven biologics manufacturing integration. Thermo Fisher Scientific Inc. exemplifies the analytical development specialist with global laboratory footprint expansion. These three entities occupy positions across the capability spectrum from high-potency parenteral formulation to commercialization support, reflecting the market's segmentation between manufacturing-anchored and laboratory-anchored service models.
| Leading Market Players |
|---|
| Catalent Inc. |
| Charles River Laboratories International, Inc. |
| Lonza Group AG |
| Thermo Fisher Scientific Inc. |
| Intertek Group plc |
| SGS S.A. |
| Labcorp |
| Eurofins Scientific SE |
| Aizant Drug Research Solutions Private Limited |
| Others |
Supply & Pricing Matrix
Captive supply of high-purity lipids and specialized polymers anchors both the supply position and pricing power for CDMOs serving complex injectable formulation programs. Sponsors face asymmetric cost structures where isolator infrastructure investments and EMA ICH Q3D compliance scope create natural pricing tiers across service providers.
Pricing Analysis
Lead-time-driven pricing premiums apply to dedicated team engagement models with embedded FTE commitments, while spot project work commands lower rates. Three-tier pricing structure across premium, standard, and economy levels separates FDA-inspected high-potency facilities from regional players and analytical-only laboratories. Cost compression in mid-tier segments is intensifying because biotechnology sponsors are consolidating vendor panels and demanding integrated service bundles. Mid-cap biotechnology firms without manufacturing infrastructure exhibit highest price sensitivity; oncology sponsors managing antibody-drug conjugate pipelines show lowest sensitivity due to regulatory risk aversion.
Supply Chain Analysis
Single-source vulnerability sits with qualified suppliers of lipid nanoparticle encapsulation materials for mRNA therapeutics. Manufacturing concentration spans Germany, Switzerland, and the United States for validated high-potency containment infrastructure. Input dependencies center on high-purity lipids, specialized polymers, and isolator-grade excipients. Tariff exposure on imported analytical instrumentation and single-use bioprocessing components constrains capacity expansion timelines. Distribution runs through sponsor quality system integration with embedded contract staff rather than transactional project handoffs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward control over high-potency containment infrastructure and lyophilization expertise determines long-term positioning. Players are pursuing upstream asset capture to defend margin structures against excipient supply concentration.
For Market Incumbents: Acquire lyophilization expertise and validated isolator infrastructure to defend against emerging mid-tier CDMOs with AI-enabled pre-formulation capabilities. Consolidate particle engineering capabilities through targeted capability additions in the Basel-Lörrach corridor. EMA's ICH Q5A revision timelines threaten analytical development margin structures without embedded sponsor quality system integration. For New Entrants and Emerging Players: CDSCO alignment with ICH stability standards in India opens a window for cost-optimized development paths capturing mid-cap biotechnology sponsor volume. Target inhalation platform formulation services as the most penetrable white space relative to saturated injectables capacity. Pursue hybrid delivery model positioning combining remote AI-enabled excipient screening with selective on-premise technology transfer presence. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by full-service CDMOs seeking analytical development footprint expansion. Long-term viability favors vertically integrated players with validated high-potency capabilities and embedded sponsor engagement models. Watch EMA quality metrics guidance implementation as the inflection signal for capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capability Acquisition | Freeze-dry cycle design expertise addresses the critical capacity constraint for unstable biologics development. |
| Isolator Infrastructure Investment | Validated containment for cytotoxic compounds limits competition to capital-intensive CDMOs with FDA inspection records. |
| Embedded Team Engagement Model | Dedicated FTE commitments within sponsor quality systems reduce handoff friction and accelerate FDA dialogue timelines. |
| AI-Enabled Pre-formulation Platform | Computational chemistry investments compress early-phase timelines from months to weeks for mid-cap biotechnology sponsors. |
| CDSCO ICH Alignment Certification | Harmonized stability requirements position Indian facilities to capture incremental sponsor volume seeking cost optimization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, CDMO procurement managers, and formulary directors combined with FDA submission databases, EMA inspection records, ClinicalTrials.gov protocols, and CDSCO registration data. Bottom-up service provider capacity assessments and top-down sponsor outsourcing expenditure patterns underwent cross-validation.
Segmentation-level modeling applied service type, application route, end-user scale, and delivery model dimensions across the projection horizon. Analytical development, pre-formulation, and commercialization support volumes were built from facility-level capacity utilization and sponsor pipeline data. CAGRs derived from regression analysis against biologics pipeline expansion and regulatory submission volume trends. Forecast inputs incorporated mRNA therapeutic development velocity and ICH guideline implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for continuous manufacturing integration would alter the outlook. Forecasts reflect assumptions regarding EMA revision implementation and FDA quality metrics adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Embossing Powder Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Template Preparation Kits Market