
 Gelling Agent Market | 2026-2036
Gelling Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Gelling Agent Market Analysis
Ingredient customization revenue is rewriting profit distribution across the value chain. Cargill Incorporated leverages its global supply network to secure raw material streams for pectin and carrageenan production. CP Kelco anchors its position through specialized fermentation capabilities in microbial polysaccharides. Kerry Group competes by integrating flavor and texture solutions for ready-meal manufacturers.
Gelling agents are hydrocolloid substances that form three-dimensional networks through hydrogen bonding, ionic cross-linking, or thermal gelation, typically functioning at concentrations between 0.5% and 3.0% by weight to provide viscosity, stability, and texture control in formulated products. Their primary commercial purpose spans food structuring, pharmaceutical controlled-release matrices, and personal care rheology modification. Pectin commands mature margin pools in fruit-based applications where acid-sugar gelling remains irreplaceable, while carrageenan captures growth in dairy alternatives driven by plant-based formulation trends. Gelatin sustains entrenched demand in pharmaceutical capsules despite religious and vegetarian substitution pressures.
EFSA purity standards, FDA food additive regulations, and China's SAMR national food safety standards collectively shape formulation choices and import access across major supply corridors. REACH compliance in Europe and evolving GB standards in China add testing and documentation burdens that favor suppliers with established regulatory affairs infrastructure. Stakeholders must monitor divergence between regional clean-label definitions as formulation decisions increasingly lock in multi-year supply commitments.
Market Dynamics
Clean-label formulation mandates are compressing synthetic hydrocolloid demand as food manufacturers reformulate around EFSA purity thresholds and consumer ingredient transparency expectations. This regulatory-consumer convergence is redrawing supplier qualification criteria and procurement specifications across processed food value chains.
Growth Catalysts
- Plant-based dairy expansion:Carrageenan and pectin demand accelerates in oat milk and coconut yogurt applications where thermal stability and mouthfeel replication prove critical.
- EFSA novel food pathways:Streamlined approval processes for microbial polysaccharides reduce time-to-market for fermentation-derived gelling agents in EU formulations.
- China's processed food corridor:Shanghai-Guangzhou-Tianjin manufacturing clusters drive concentrated demand for texture-modified ready-meals and convenience foods.
Market Restraints
- Seaweed supply volatility:Carrageenan raw material costs fluctuate with Philippine and Indonesian farmgate pricing and monsoon harvesting disruptions.
- Gelatin substitution ceiling:Religious dietary restrictions and vegetarian formulation mandates cap growth in pharmaceutical capsule and confectionery segments.
- REACH documentation burdens:European hydrocolloid importers face extended substance registration timelines and testing cost escalation.
Strategic Opportunities
- Precision fermentation scale-up:Microbial gellan gum and curdlan production offers supply security independent of agricultural harvest cycles.
- SAMR clean-label alignment:China's national food safety standards evolution creates first-mover advantage for suppliers with established purity certification infrastructure.
- Pharmaceutical controlled-release matrices:Hydrogel applications in oral dosage forms and transdermal patches expand addressable market beyond food.
Industry Challenges
- Fermentation bioprocess engineering talent:Microbial polysaccharide production requires specialized metabolic pathway optimization expertise in short supply.
- Dual certification timelines:Simultaneous EFSA novel food and FDA GRAS approvals demand 18-36 month regulatory investment before commercial launch.
- Legacy equipment retrofit costs:Existing pectin extraction facilities require capital-intensive upgrades to meet tightened heavy metal and solvent residue specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gelling Agent Market |
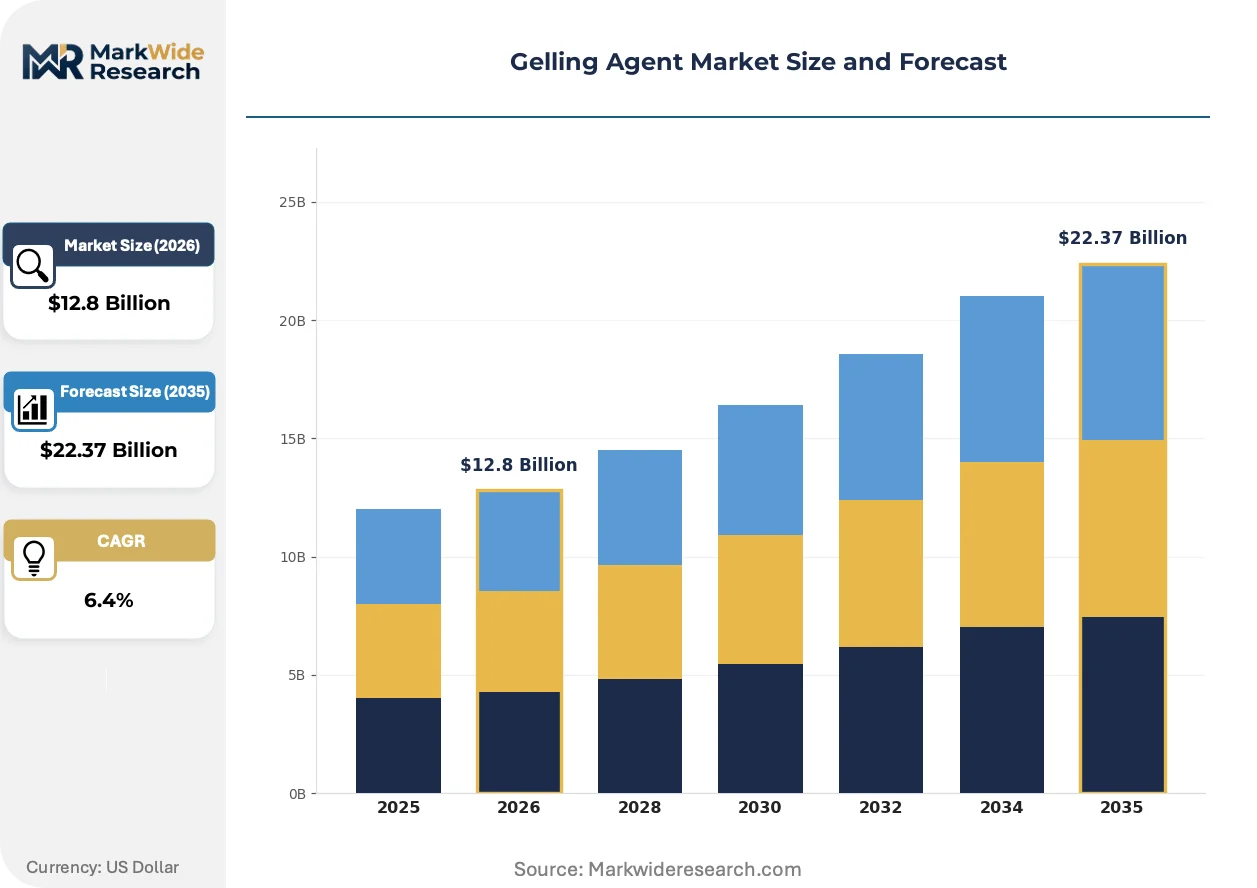
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Pectin, Gelatin, Carrageenan Application: Food & Beverages, Personal Care, Pharmaceutical, Industrial Form: Powder, Liquid, Granule, Sheet End User: Food Manufacturers, Cosmetic Firms, Healthcare Providers, Others |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Tate & Lyle, Ingredion Incorporated, E. I. DuPont de Nemours, CP Kelco, Kerry Group, Ashland Global Holdings, Nexira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gelling Agent Market Emerging Trajectories
Bioprocess engineering advances and regulatory purity convergence are compressing traditional extraction-based supply models while opening fermentation-derived alternatives. Formulation science is pivoting toward multi-hydrocolloid synergies that replicate texture profiles with reduced single-ingredient dependency.
Enzymatic pectin modification is collapsing the functional gap between high-methoxyl and low-methoxyl variants, enabling a single ingredient to perform across wider pH and calcium concentration ranges. Dairy alternative manufacturers in Germany and the Netherlands are adopting these unified pectin grades at accelerated qualification cycles. This technological consolidation is collapsing SKU complexity and raw material inventory requirements for mid-scale contract manufacturers.
REACH authorization requirements for certain seaweed processing aids are tightening impurity thresholds for carrageenan destined for infant nutrition applications. The industrial consequence is a bifurcation between food-grade and pharmaceutical-grade supply chains with diverging documentation and testing protocols. Infant formula manufacturers in Ireland and Denmark are responding by locking multi-year supply agreements with vertically integrated seaweed processors.
Ingredient specification unbundling is fragmenting traditional distributor relationships as large food manufacturers establish direct technical partnerships with hydrocolloid producers. Regional brokers in Southeast Asia are losing share to supplier-operated technical service laboratories that co-develop texture solutions with brand R&D teams. This channel compression is most visible in Thailand and Vietnam where local confectionery and beverage multinationals have terminated legacy distribution agreements in favor of direct procurement contracts.
Gelling Agent Market Segmentation
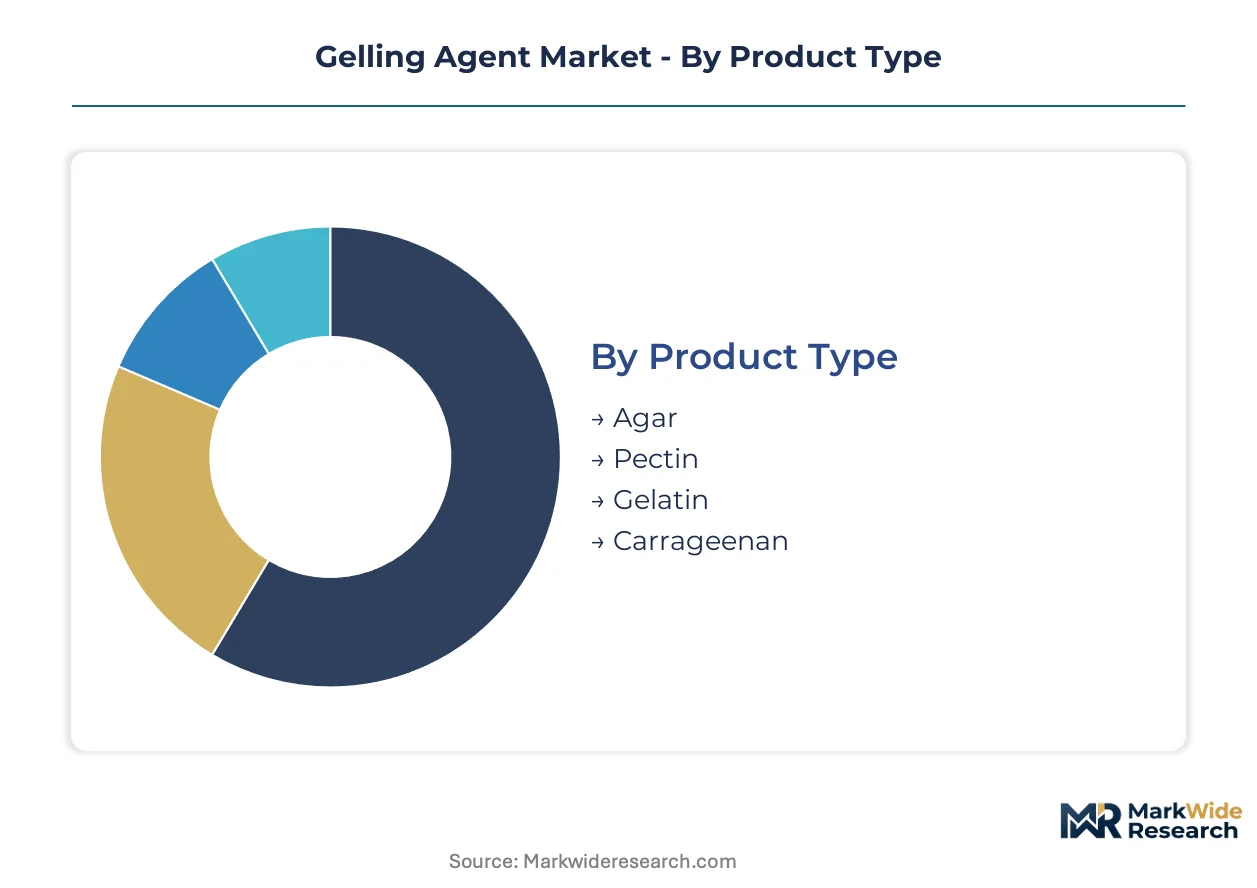
Gelling agent procurement decisions hinge on functional compatibility with processing conditions, regulatory clearance status, and supply security across volatile agricultural inputs. Segmentation reveals how hydrocolloid specifications diverge across temperature stability, ionic sensitivity, and gel strength requirements.
Product Type:
Use-case spectrum spans acid-set fruit systems, neutral pH dairy alternatives, thermo-reversible confectionery, and cold-set aspic applications.
- Pectin:High-methoxyl variants form gels in high-acid, high-sugar environments through hydrogen bonding and hydrophobic interactions. Jam and jelly manufacturers in Germany and France specify HM pectin for traditional preserves where rapid set and clean flavor release matter. Low-methoxyl grades respond to calcium cross-linking, enabling reduced-sugar formulations that EFSA clean-label guidelines favor.
- Carrageenan:Sulfated galactan extracted from red seaweed (Kappaphycus alvarezii, Eucheuma denticulatum) exists in kappa, iota, and lambda forms with distinct cation reactivity. Oat milk processors in the Netherlands and coconut yogurt facilities in Thailand specify kappa-iota blends for thermal stability during UHT treatment and shear-thinning recovery. Philippine farmgate pricing volatility and monsoon harvest disruptions create supply uncertainty that fermentation alternatives increasingly address.
- Gelatin:Collagen hydrolysate from bovine and porcine sources retains entrenched demand in pharmaceutical two-piece hard capsules and softgels. Religious dietary restrictions (halal, kosher) and vegetarian formulation mandates cap expansion in confectionery gummies and marshmallows.
- Agar:Polysaccharide from Gelidium and Gracilaria seaweed species delivers high gel strength at low concentrations with sharp melting-setting hysteresis. Microbiology laboratories and plant-based confectionery niche applications in Japan specify agar for its thermo-irreversible clarity.
The dominant share belongs to pectin, while carrageenan is closing the gap fastest.
Application:
Volume concentration tracks processed food manufacturing density and pharmaceutical formulation outsourcing patterns.
- Food & Beverages:Texture modification in ready-meals, dairy alternatives, and convenience foods drives bulk consumption. Shanghai-Guangzhou-Tianjin manufacturing clusters in China specify hydrocolloid blends for retort-stable sauces and instant dessert mixes.
- Pharmaceutical:Controlled-release matrix tablets, softgel capsules, and transdermal hydrogel patches demand documented purity grades. FDA GRAS and EMA excipient qualification requirements extend supplier onboarding timelines.
- Personal Care:Rheology modification in creams, lotions, and toothpaste requires cold-process compatibility and electrolyte tolerance. REACH authorization for certain seaweed-derived inputs tightens documentation burdens for EU-bound shipments.
- Industrial:Adhesives, coatings, and oilfield drilling fluids utilize gellan gum and xanthan for suspension stability. Specifications prioritize batch consistency over organoleptic purity.
Food and beverages command the volume base, with pharmaceutical applications climbing fastest on per-kilogram value premiums.
Form:
Processing equipment compatibility and dissolution efficiency determine format selection across manufacturing scales.
- Powder:Standard format for bulk dry blending operations offers extended shelf stability and precise dosing. Dust generation during handling requires containment infrastructure.
- Liquid:Pre-hydrated solutions eliminate dispersion lumps and reduce batch cycle times. Higher logistics costs limit geographic distribution radius.
- Granule:Agglomerated particles improve flowability and reduce dusting compared to fine powders. Instant beverage and soup mix manufacturers favor this format.
- Sheet:Traditional presentation for laboratory and culinary applications in East Asian markets. Limited industrial scale adoption outside specialized research settings.
Powder maintains the installed base, while liquid concentrates gain share in continuous processing lines.
End User:
Procurement sophistication varies from commodity spot purchasing to multi-year technical partnership agreements.
- Food Manufacturers:Multinational processed food corporations and regional contract manufacturers drive specification standardization. Clean-label mandates from retail chains cascade into hydrocolloid purity requirements.
- Cosmetic Firms:Formulation houses and brand owners prioritize sensory performance and regulatory dossier completeness. ECHA REACH compliance documentation extends supplier qualification cycles.
- Healthcare Providers:Pharmaceutical companies and compounding pharmacies require excipient-grade certifications with full traceability. USP-NF and Ph.Eur. monograph compliance is non-negotiable.
- Others:Research institutions, biotechnology startups, and niche industrial processors represent fragmented, specification-diverse demand.
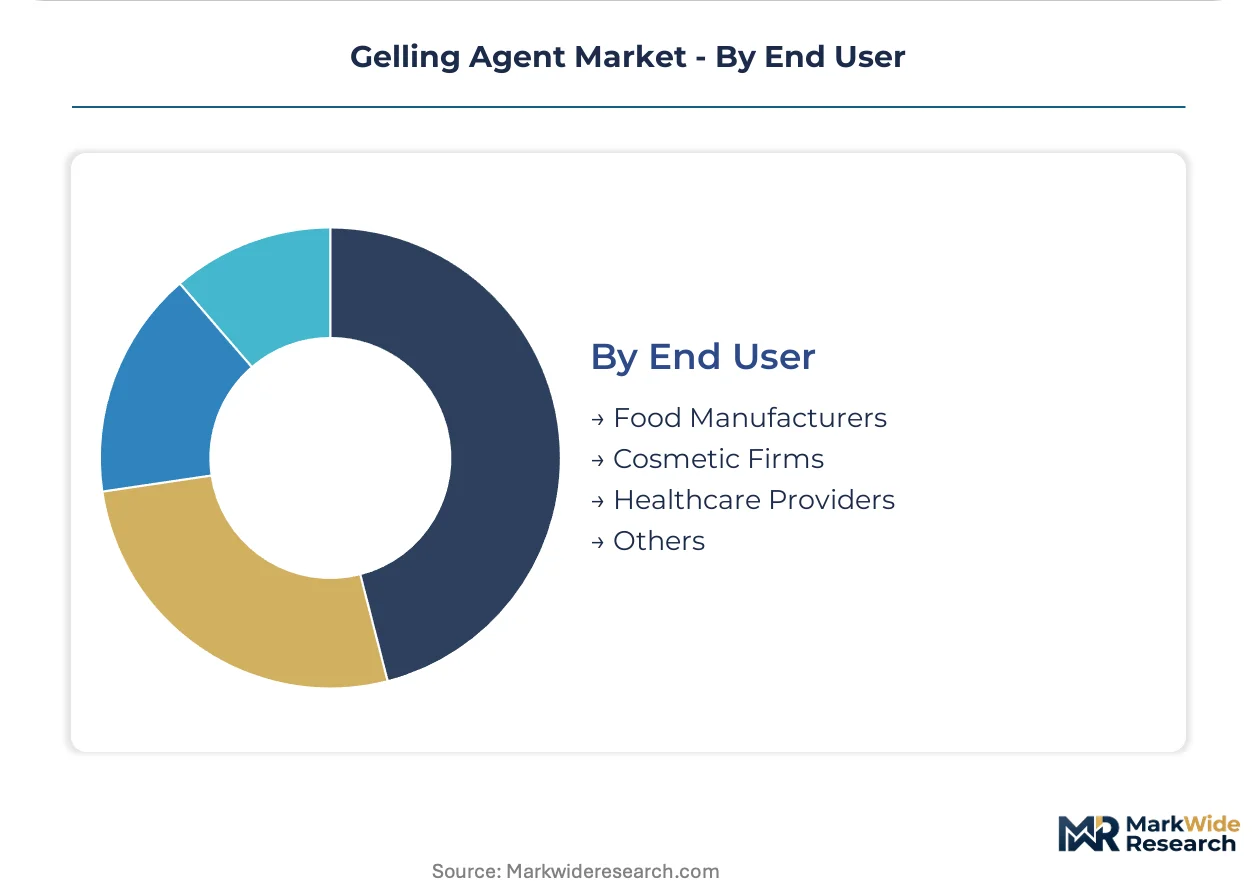
Food manufacturers anchor procurement volume, with cosmetic firms expanding specification influence through co-development partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's processed food corridor demonstrate the highest price elasticity, squeezing margins on commodity hydrocolloids, while pharmaceutical formulators in Germany and the United States absorb premium pricing for documented purity grades without volume contraction.
China
Shanghai-Guangzhou-Tianjin manufacturing clusters drive concentrated demand for retort-stable sauces and instant dessert mixes. SAMR national food safety standards evolution tightens purity certification requirements for plant-derived hydrocolloids. Tianjin's contract manufacturers are locking multi-year supply agreements to secure compliant pectin and carrageenan streams ahead of anticipated regulatory alignment with EFSA thresholds.
Germany
Jam and jelly manufacturers specify high-methoxyl pectin for traditional preserves where rapid set and clean flavor release matter. EFSA novel food regulations streamline approval processes for microbial polysaccharides, reducing time-to-market for fermentation-derived alternatives. Bavarian dairy alternative processors are accelerating qualification cycles for enzymatically modified unified pectin grades that collapse SKU complexity.
United States
FDA GRAS and excipient qualification requirements extend supplier onboarding timelines for pharmaceutical controlled-release matrices. Gelatin sustains entrenched demand in two-piece hard capsules and softgels despite religious and vegetarian substitution pressures. New Jersey and Pennsylvania formulation clusters prioritize documented traceability for hydrogel applications in oral dosage forms.
Netherlands
Oat milk processors specify kappa-iota carrageenan blends for thermal stability during UHT treatment and shear-thinning recovery. REACH authorization requirements tighten impurity thresholds for seaweed-derived inputs destined for infant nutrition applications. Rotterdam-area dairy alternative manufacturers are establishing direct technical partnerships with hydrocolloid producers, bypassing traditional distributor relationships.
Philippines
Farmgate pricing volatility and monsoon harvest disruptions create supply uncertainty for carrageenan raw materials extracted from Kappaphycus alvarezii and Eucheuma denticulatum. The country's national food safety regulator enforces evolving export certification standards for seaweed processing. Mindanao-based seaweed processors are responding to REACH documentation burdens by bifurcating food-grade and pharmaceutical-grade supply chains with diverging testing protocols.
Gelling Agent Market Vendor Landscape
Capability concentration sits with specialized fermentation operators; scale advantage sits with diversified agricultural processors. The market structures around three tiers: global ingredient conglomerates with integrated supply networks, mid-cap hydrocolloid specialists with technical service laboratories, and regional extraction-based suppliers dependent on volatile seaweed harvests. Dominant competitive moves include backward integration into raw material streams and direct technical partnerships that disintermediate traditional distribution channels.
Among diversified agricultural processors, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through global supply network leverage. CP Kelco occupies a specialist tier anchored by fermentation capabilities in microbial polysaccharides. Kerry Group represents the integrated solutions archetype, combining texture modification with adjacent formulation services. Tate & Lyle and Ingredion Incorporated sit within the commodity-processing tier, converting agricultural feedstocks into standardized hydrocolloid grades for high-volume food manufacturing contracts.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle |
| Ingredion Incorporated |
| E. I. DuPont de Nemours |
| CP Kelco |
| Kerry Group |
| Ashland Global Holdings |
| Nexira |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Philippine seaweed processing facilities is compressing farmgate carrageenan prices while simultaneously eroding supplier pricing power across Asian supply corridors. This utilization imbalance forces processors to absorb margin pressure rather than pass through costs, reshaping procurement negotiations for European and North American buyers.
Pricing Analysis
After-sales technical service contracts drive lifetime value for hydrocolloid suppliers, with formulation support and regulatory dossier maintenance commanding premium-mid-economy pricing differentiation based on certification depth. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade purity levels segments buyers by documentation burden tolerance. Cost compression in commodity pectin runs through Chinese contract manufacturers squeezing spot-market suppliers. Pharmaceutical formulators in Germany and the United States exhibit lowest price sensitivity, absorbing documented purity premiums without volume contraction.
Supply Chain Analysis
Tariff exposure between Southeast Asian seaweed processors and European Union importers dominates supply chain risk calculus for carrageenan-dependent dairy alternative manufacturers. Raw material extraction concentrates in the Philippines, Indonesia, and Vietnam, with Kappaphycus alvarezii and Eucheuma denticulatum biomass feeding regional processing hubs. Supply chains hinge on monsoon harvest cycles and farmgate pricing volatility that fermentation alternatives increasingly circumvent. Distribution runs through direct technical partnerships that disintermediate traditional Southeast Asian brokerage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable barriers: EFSA novel food approval timelines and FDA GRAS qualification cycles lock in incumbent advantages through 18-36 month switching costs.
For Market Incumbents: Insulate market position by deepening captive supply of Philippine and Indonesian seaweed streams through backward integration into farmgate procurement networks. Accelerate fermentation capacity buildout in microbial polysaccharides to neutralize agricultural harvest volatility. Lock multi-year technical partnership agreements with Shanghai-Guangzhou-Tianjin manufacturing clusters ahead of SAMR regulatory alignment with EFSA purity thresholds. For New Entrants and Emerging Players: Establish a beachhead in enzymatically modified unified pectin grades where SKU consolidation demand from mid-scale European contract manufacturers outpaces incumbent qualification cycles. Target pharmaceutical-grade gellan gum for controlled-release matrix applications, where USP-NF documentation gaps among existing suppliers create white-space entry. Lead with regulatory affairs infrastructure as primary go-to-market wedge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation-capable hydrocolloid specialists with established EFSA novel food dossiers and direct technical service laboratories. Long-term viability centers on bioprocess engineering talent scarcity and regulatory compliance infrastructure that compounds over decade horizons. Acquisition focus should center on microbial polysaccharide operators with SAMR pre-certification progress. The signal to watch is bifurcation between food-grade and pharmaceutical-grade supply chain certification depth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Cargill and CP Kelco secure Philippine farmgate supply chains against monsoon disruption and price volatility. |
| Fermentation Capacity Scale-Up | Microbial gellan gum production decouples supply security from Kappaphycus alvarezii harvest cycles. |
| EFSA Novel Food Dossier Expansion | Streamlined approval pathways for curdlan and microbial polysaccharides reduce EU market entry timelines. |
| Direct Technical Partnership Model | Kerry Group and regional specialists bypass Southeast Asian distributors to co-develop texture solutions with R&D teams. |
| Pharmaceutical-Grade Certification Investment | REACH-compliant heavy metal and solvent residue testing bifurcates supply chains for infant nutrition applications. |
Methodological Framework
A spread of perspectives from hydrocolloid procurement managers at multinational food manufacturers, fermentation bioprocess engineers, regulatory affairs directors, and seaweed processing facility operators converged on the working assumptions shaping this analysis. Primary field engagement combined with secondary validation from FDA GRAS notifications, EFSA novel food opinions, SAMR national food safety standard drafts, and SEC 10-K filings from diversified agricultural processors anchored the evidentiary base. Bottom-up volume modeling across pectin, carrageenan, gelatin, and microbial polysaccharide grades triangulated against top-down market sizing from trade flow data.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning product type, application, purity grade, and regional manufacturing cluster. CAGRs derived from weighted average growth contributions across enzymatic modification adoption curves, plant-based dairy expansion rates, and pharmaceutical excipient qualification timelines. Forecast inputs incorporated EFSA regulatory pathway velocity, Philippine farmgate price volatility indices, and SAMR-EFSA alignment probability assessments.
Macroeconomic conditions sit as an overlay; deviation in processed food consumer spending, EU-Asia trade policy, or fermentation feedstock energy costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory timeline convergence and bioprocess engineering talent availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Embossing Powder Market
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Template Preparation Kits Market