
 Solution Deposition Precursor Market | 2026-2036
Solution Deposition Precursor Market Size, Share, and Industry Trends Forecast 2026-2036
Solution Deposition Precursor Market Analytics
Modular precursor bundling is hardening as the dominant procurement pattern among semiconductor fabs. Merck KGaA leverages its integrated electronic materials portfolio to anchor long-term supply agreements with leading chipmakers. Entegris Corporation differentiates through contamination control expertise that extends from precursor synthesis to point-of-use delivery systems. JSR Corporation specializes in photoresist-adjacent precursor chemistries that compete directly in advanced node manufacturing.
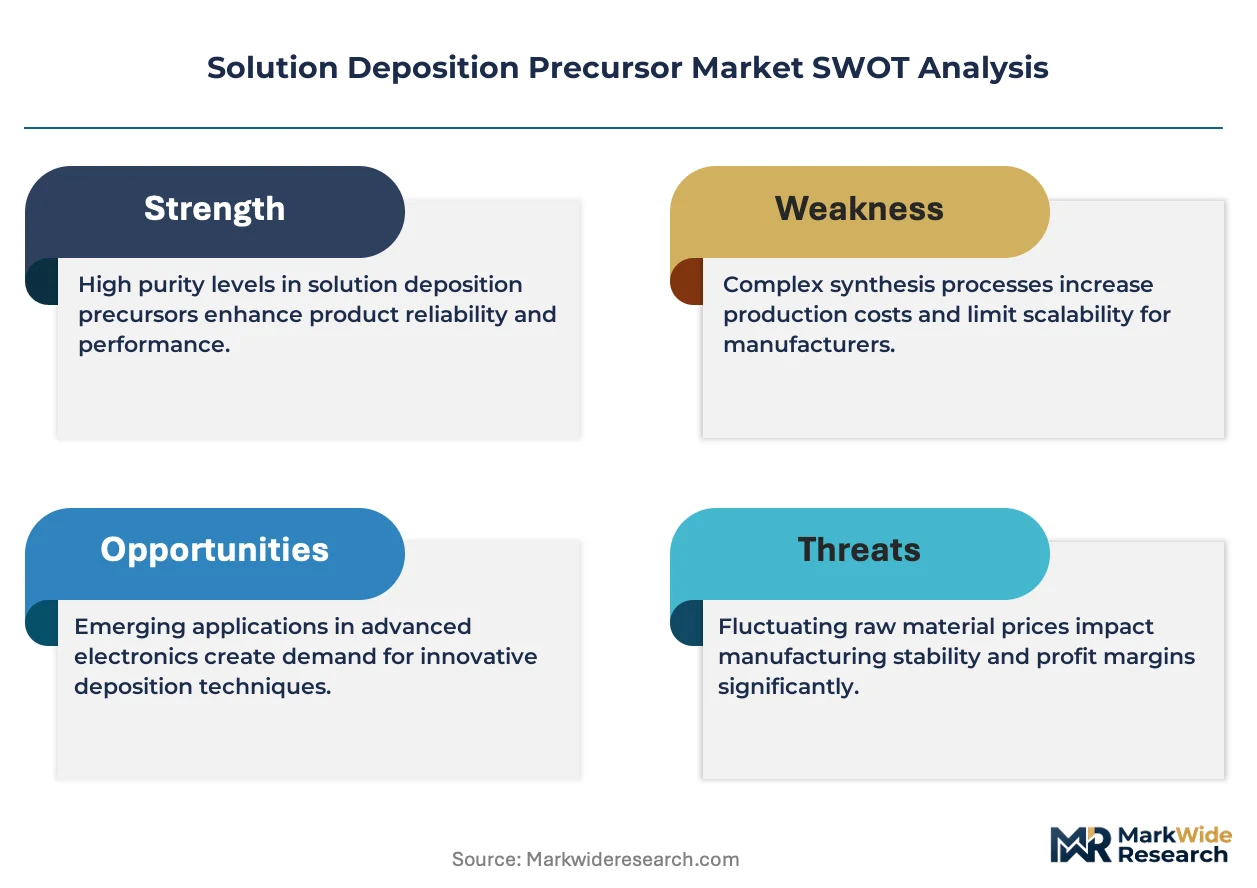
Solution deposition precursors are high-purity organometallic or inorganic compounds formulated for liquid-phase or vapor-phase thin-film deposition, typically requiring metal impurity levels below one part per billion to ensure electrical performance in nanoscale devices. These materials enable conformal coating of complex geometries in semiconductor interconnects, photovoltaic absorbers, and protective barrier layers through spin-coating, spray pyrolysis, or chemical bath deposition methods. Metal oxide precursors command the largest revenue share due to their irreplaceable role in high-k gate dielectrics and transparent conductive oxide fabrication. Thin film technology applications represent the fastest-expanding demand pool as perovskite solar cell manufacturers scale beyond pilot production. Liquid delivery systems dominate operational deployment because of their compatibility with existing chemical distribution infrastructure and precise flow control.
EPA oversight of hazardous chemical reporting shapes precursor handling protocols for US-based deposition facilities, while REACH registration requirements in Europe mandate exhaustive toxicity documentation that filters out smaller chemical suppliers. EMA and FDA frameworks indirectly influence demand through their jurisdiction over medical device coatings that rely on biocompatible thin films. South Korea's MFDS and K-Battery regulations are accelerating localization requirements for precursor supply chains serving domestic battery and memory chip sectors. Stakeholders must monitor evolving purity standards and regional content mandates to sustain qualification status with tier-one device manufacturers.
Market Dynamics
Semiconductor foundries are consolidating precursor procurement around atomic layer deposition compatibility, forcing suppliers to reconfigure synthesis and purification workflows around sub-ppb metal contamination thresholds.
Growth Catalysts
- Atomic layer deposition expansion:Memory chip manufacturers in South Korea are scaling ALD-capable precursor volumes for 3D NAND vertical stacking architectures.
- REACH purity mandates:ECHA registration requirements for electronic-grade chemicals are filtering out subscale suppliers and concentrating qualified vendor pools.
- Perovskite solar commercialization:Photovoltaic manufacturers are qualifying solution deposition precursors for absorber layer fabrication at pilot-to-production scale transitions.
Market Restraints
- Specialized metal feedstock volatility:Iridium and ruthenium organometallic precursors face price instability tied to South African and Russian mining concentration.
- Single-source synthesis dependencies:German and Japanese chemical specialists control critical high-purity solvent refining capacity for precursor formulation.
- RoHS substance restrictions:European directives on cadmium and lead content eliminate certain organometallic precursor chemistries from qualified material lists.
Strategic Opportunities
- India semiconductor fabrication:Tata Electronics and ISMC Digital are constructing fabrication facilities that will require localized precursor supply chain development under PLI scheme incentives.
- Biocompatible medical coatings:FDA-regulated device manufacturers are qualifying titanium and zirconium oxide precursors for implantable sensor encapsulation.
- Battery electrode functionalization:Solid-state battery developers are integrating solution deposition precursors for ceramic electrolyte thin-film deposition.
Industry Challenges
- Cleanroom-qualified chemical engineering talent:Deposition facilities face acute shortages of process engineers capable of managing point-of-use precursor delivery system integration.
- Multi-year fab qualification timelines:Precursor suppliers must sustain capital-intensive validation programs spanning 18-36 months for node-specific material approval.
- Cross-border hazardous material logistics:EPA and ECHA divergent reporting requirements for organometallic compounds create customs clearance friction and inventory positioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solution Deposition Precursor Market |
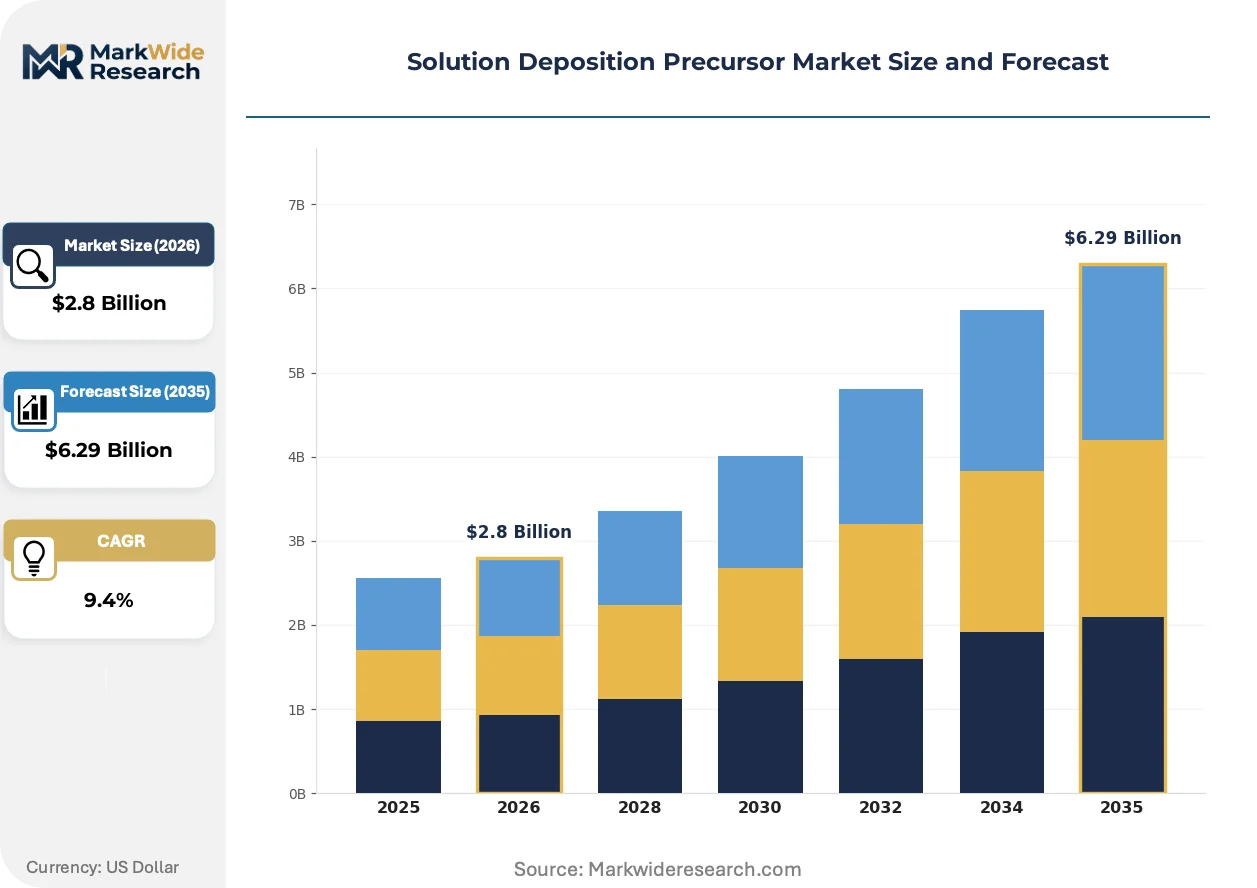
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Precursors, Metal Oxide Precursors, Organic Precursors, Hybrid Precursors Application: Semiconductor Manufacturing, Photovoltaics, Coatings, Thin Film Technology End User: Electronics Industry, Solar Energy Sector, Aerospace, Research Institutions Delivery Mode: Liquid Delivery, Gas Delivery, Solid Delivery, Vapor Delivery |
| Companies Covered | Air Liquide, Linde plc, Merck KGaA, Entegris Corporation, SK Materials, ADEKA Corporation, Dow Chemical Company, JSR Corporation, Mitsubishi Gas Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solution Deposition Precursor Market Evolving Landscape
Deposition technology roadmaps are converging on hybrid liquid-vapor delivery architectures that bridge legacy spin-coating infrastructure with advanced vapor-phase requirements.
Water-free organometallic precursor formulations are integrating silane and amide chemistries to eliminate hydrolysis-induced particle contamination in high-k dielectric deposition. Memory chip manufacturers in South Korea and Taiwan are adopting these moisture-stable chemistries for 3D NAND wordline fabrication. The shift is compressing qualification cycles for alternative precursor architectures that bypass traditional solvent-based stabilization.
REACH authorization procedures are tightening documentary requirements for organometallic substance toxicity profiles, extending registration timelines for new precursor introductions. ECHA's 2024 updates to substance evaluation protocols are forcing suppliers to commission extended mammalian toxicity studies before market entry. Photovoltaic precursor categories face the most severe compliance compression, as perovskite absorber chemistries fall under emerging nanomaterial classification scrutiny.
Long-term supply agreements are displacing spot-market precursor purchasing among tier-one semiconductor fabs, locking in volume commitments against price volatility. Merck KGaA and Entegris have secured multi-year contracts with Samsung and SK Hynix that bundle precursor supply with point-of-use filtration services. South Korean foundries are driving this contractualization most aggressively, using procurement consolidation to secure preferential allocation during supply constraints.
Solution Deposition Precursor Market Segmentation
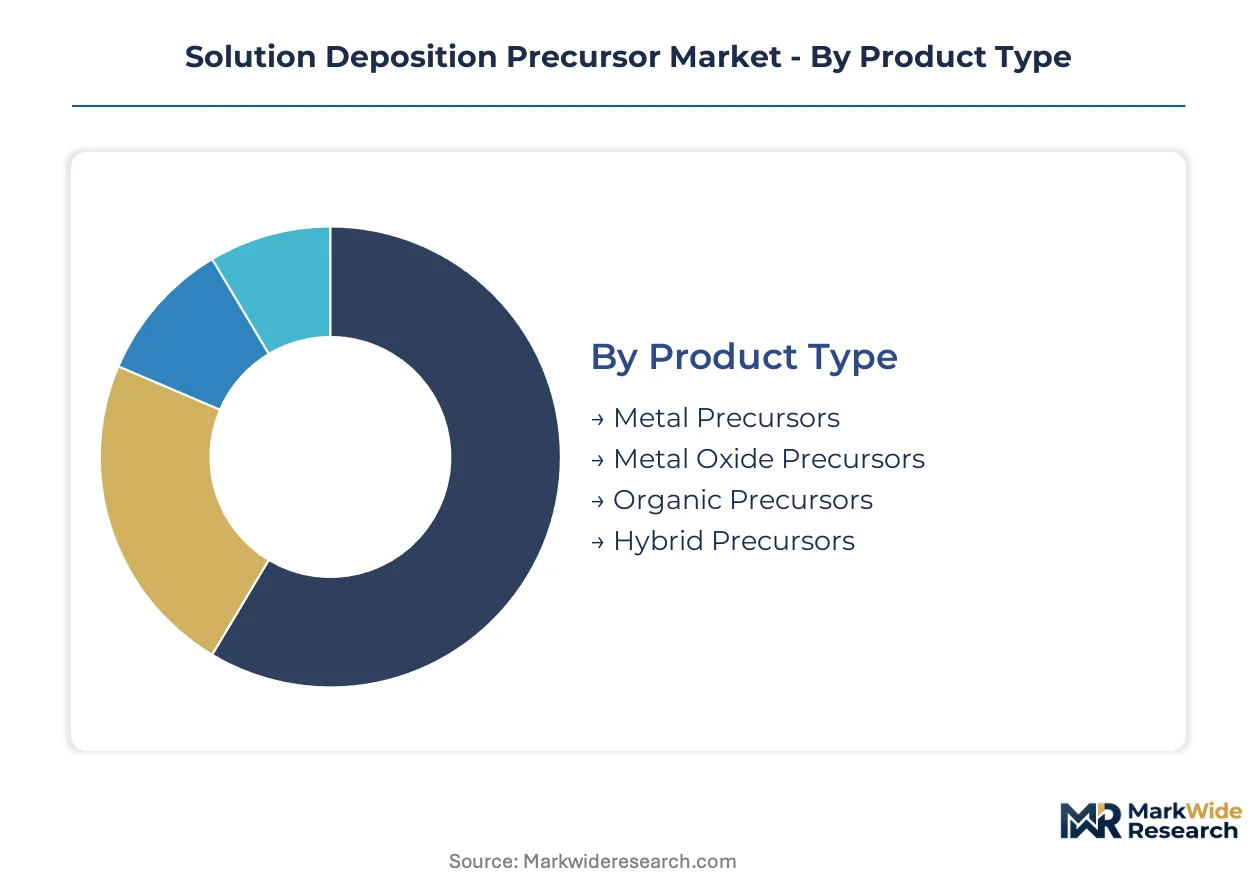
Precursor procurement patterns diverge sharply across deposition technologies and end-use specifications. Semiconductor fabs prioritize atomic layer deposition compatibility while photovoltaic manufacturers optimize for cost-effective coating coverage at scale.
Product Type:
Buyers differentiate primarily by metal impurity thresholds and thermal decomposition profiles required for their specific deposition chambers.
- Metal Oxide Precursors:High-purity organometallic compounds formulated for hafnium oxide and zirconium oxide deposition in gate dielectric stacks. Samsung and SK Hynix in South Korea consume the largest volumes for 3D NAND wordline fabrication, driven by vertical stacking architectures that demand conformal oxide coverage.
- Metal Precursors:Organometallic iridium and ruthenium compounds delivering atomic-scale nucleation control for interconnect barrier layers. Memory chip manufacturers in South Korea anchor procurement volumes here, though supply constraints around South African and Russian mining concentration create price volatility.
- Organic Precursors:Carbon-based coordination complexes for specialized dielectric and passivation applications.
- Hybrid Precursors:Mixed metal-organic formulations bridging vapor-phase and liquid-phase deposition requirements.
Volume sits with Metal Oxide Precursors; growth tilts toward Hybrid Precursors.
Application:
End-use specifications create tiered purity requirements that reshape supplier qualification timelines.
- Semiconductor Manufacturing:Sub-ppb metal contamination thresholds define qualification standards for atomic layer deposition in advanced node production. South Korean foundries drive procurement consolidation here, with multi-year supply agreements displacing spot-market purchasing.
- Thin Film Technology:Perovskite solar cell manufacturers are scaling beyond pilot production, creating demand for solution-processed absorber precursors that balance conversion efficiency with manufacturing throughput.
- Photovoltaics:Silicon and cadmium telluride deposition for conventional cell architectures.
- Coatings:Protective and functional layers for industrial and consumer applications.
Revenue concentrates in Semiconductor Manufacturing; expansion accelerates fastest in Thin Film Technology.
End User:
Customer technical capabilities determine whether procurement emphasizes bundled services or commodity chemical supply.
- Electronics Industry:Integrated device manufacturers and foundries requiring point-of-use filtration and contamination control alongside precursor supply. Merck KGaA and Entegris anchor long-term contracts here by bundling chemical delivery with cleanroom logistics.
- Solar Energy Sector:Photovoltaic manufacturers prioritizing cost-per-watt metrics over extreme purity, though perovskite developers are tightening specifications as cell efficiencies climb.
- Aerospace:Specialized coating applications for thermal protection and corrosion resistance.
- Research Institutions:Small-batch procurement for materials development and process characterization.
Procurement value concentrates with Electronics Industry; contract velocity is climbing fastest in Solar Energy Sector.
Delivery Mode:
Existing infrastructure compatibility shapes whether facilities retrofit or replace chemical distribution systems.
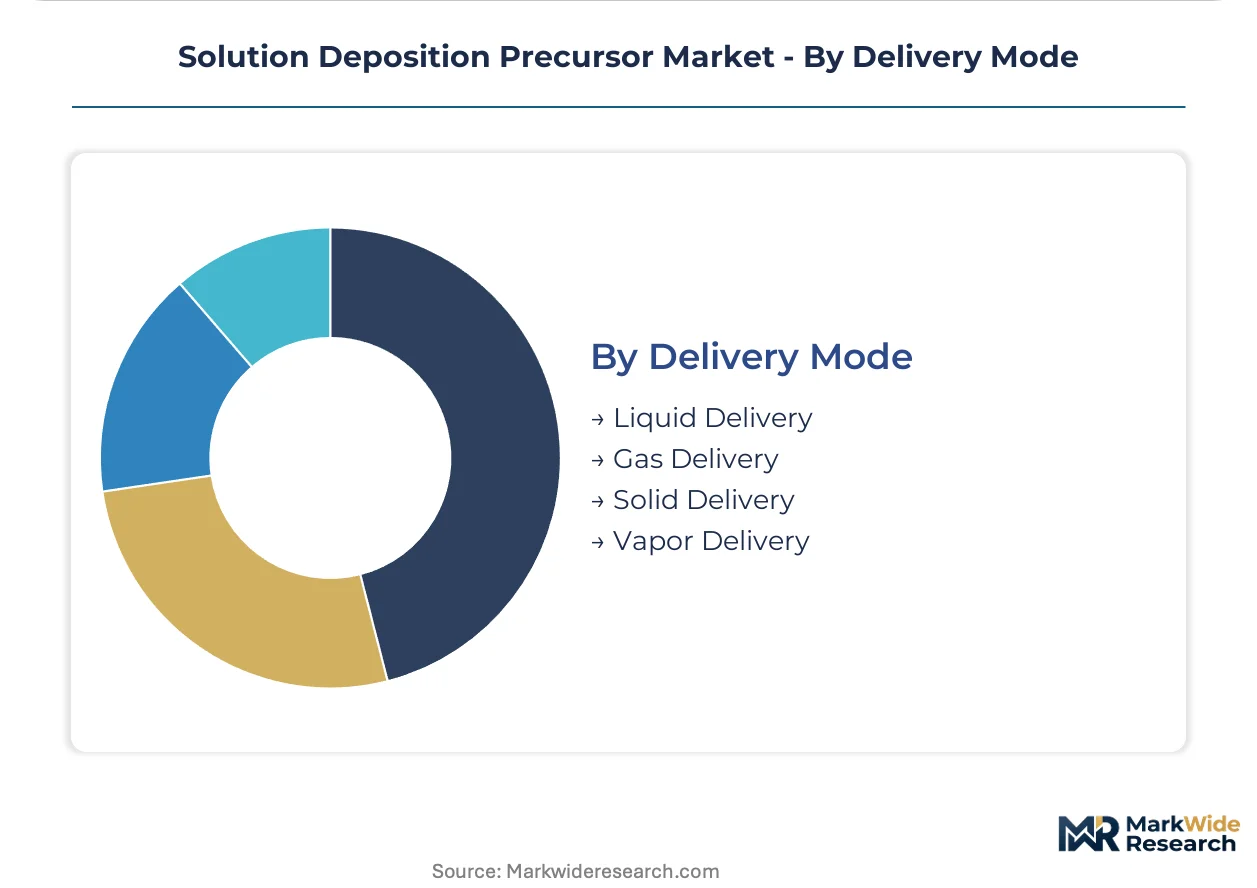
- Liquid Delivery:Dominates operational deployment through compatibility with established chemical distribution infrastructure and precise flow control systems. Entegris Corporation differentiates here with contamination control expertise extending from synthesis to point-of-use delivery.
- Vapor Delivery:Required for atomic layer deposition processes in advanced semiconductor nodes, forcing foundries to install specialized bubbler and direct liquid injection systems.
- Gas Delivery:Specialized applications for plasma-enhanced deposition processes.
- Solid Delivery:Niche applications for specific organometallic compounds with limited liquid-phase stability.
Installed base favors Liquid Delivery; capability investment is concentrating in Vapor Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan where high-purity solvent refining capabilities anchor precursor formulation, while consumption tilts toward South Korea and Taiwan where memory chip fabrication complexes drive procurement volumes. The geographic split forces suppliers to maintain dual-hemisphere manufacturing footprints to satisfy lead-time requirements.
United States
Domestic demand clusters around advanced logic foundries in Arizona and Texas expanding atomic layer deposition capacity for sub-3nm node production. EPA hazardous chemical reporting requirements under TSCA shape handling protocols for organometallic compounds at deposition facilities. The Pacific Northwest hosts specialized contamination control engineering firms supporting point-of-use delivery system integration.
South Korea
Samsung and SK Hynix fabrication complexes in Pyeongtaek and Icheon consume the largest global volumes of hafnium and zirconium oxide precursors for 3D NAND vertical stacking. MFDS chemical safety regulations and K-Battery localization mandates are accelerating domestic precursor supply chain development. The Seoul Capital Area concentration of packaging and testing facilities creates secondary demand for barrier layer deposition materials.
Japan
Japanese chemical specialists control critical high-purity solvent refining capacity that feeds precursor formulation workflows across Asia. METI industrial policy supports domestic production of electronic-grade organometallic compounds through designated critical material subsidies. The Osaka-Kobe industrial corridor hosts integrated electronic materials suppliers bundling precursor synthesis with contamination control services.
Germany
Merck KGaA anchors European precursor production through integrated electronic materials portfolios serving foundry customers. REACH authorization procedures and ECHA substance evaluation protocols filter supplier qualification, concentrating qualified vendor pools. The Rhine-Main manufacturing cluster combines specialty chemical synthesis with advanced purification infrastructure for sub-ppb metal contamination thresholds.
Taiwan
TSMC and UMC foundry operations in Hsinchu Science Park drive procurement of ALD-compatible precursors for advanced node manufacturing. The island's semiconductor ecosystem sources formulated precursors primarily from Japanese and Korean suppliers, creating import dependency. Taichung and Tainan fab expansions are qualifying additional precursor vendors to diversify supply risk.
Solution Deposition Precursor Market Competitive Landscape
The competitive structure tilts toward integrated electronic materials conglomerates with captive purification and contamination control capabilities. Market concentration is moderate, with a tiered vendor base separating qualified suppliers capable of sub-ppb metal thresholds from commodity chemical producers. Three archetypes dominate: diversified chemical conglomerates with electronic materials divisions, specialized contamination control firms extending into precursor delivery, and regional organometallic synthesis specialists. Capacity expansion and long-term supply agreement consolidation represent the dominant competitive moves, as foundries lock in volume commitments against feedstock volatility.
Within the integrated conglomerate tier, Merck KGaA and Entegris Corporation exemplify the bundling strategy combining precursor supply with point-of-use filtration and cleanroom logistics. SK Materials occupies a position representing Korean chemical specialists leveraging domestic fab proximity to anchor regional supply agreements. These three entities illustrate how geographic proximity to consumption clusters and vertical integration into contamination control services differentiate positioning against commodity chemical suppliers lacking qualification depth.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Merck KGaA |
| Entegris Corporation |
| SK Materials |
| ADEKA Corporation |
| Dow Chemical Company |
| JSR Corporation |
| Mitsubishi Gas Chemical |
| Others |
Value Network & Pricing Analysis
Cleanroom-qualified chemical engineering talent concentration in the Rhine-Main and Osaka-Kobe clusters creates labor-cost differentials that widen pricing-tier spreads between premium electronic-grade precursors and commodity formulations.
Pricing Analysis
Margin tightening in standard-grade precursor tiers reflects REACH registration cost absorption by mid-scale suppliers unable to achieve volume scale. Three-tier pricing structure across premium electronic-grade, standard industrial-grade, and economy reagent-grade levels separates qualification depth from basic chemical purity. Cost-down pressure on economy tiers accelerates because photovoltaic manufacturers prioritize cost-per-watt metrics over sub-ppb contamination thresholds. Solar Energy Sector buyers exhibit highest price sensitivity while Electronics Industry fabs accept premium pricing for bundled point-of-use filtration services.
Supply Chain Analysis
Cross-border hazardous material logistics costs for organometallic compounds compound landed pricing volatility for US and European deposition facilities. Supply concentrates in Germany and Japan where high-purity solvent refining capabilities anchor precursor formulation, with South Korea consuming the largest volumes. Raw material dependencies draw from South African iridium mining, Russian ruthenium concentrate, and Japanese high-purity solvent production. Single-source synthesis vulnerability around German and Japanese chemical specialists creates supply risk. Distribution runs through integrated electronic materials conglomerates bundling precursor supply with contamination control services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solution Deposition Precursor Market consolidation is accelerating as REACH and RoHS regulatory compliance costs force subscale suppliers without captive purification capabilities to exit qualification pools.
For Market Incumbents: Hedge against feedstock volatility by securing long-term offtake agreements with South African and Russian mining concentrate suppliers before price instability disrupts iridium and ruthenium organometallic precursor margins. Deepen backward integration into high-purity solvent refining capacity to reduce dependency on German and Japanese chemical specialists. Anchor regional supply agreements with Samsung and SK Hynix through bundled point-of-use filtration services that lock in volume commitments.
For New Entrants and Emerging Players: Perovskite solar cell manufacturers scaling beyond pilot production represent the most penetrable buyer archetype because their specifications remain less stringent than semiconductor sub-ppb thresholds. Target India's emerging fabrication ecosystem under PLI scheme incentives where localized precursor supply chains remain undeveloped. Qualify water-free organometallic formulations that bypass traditional solvent-based stabilization to compress entry timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with contamination control specialists possessing point-of-use delivery system integration capabilities given foundry procurement consolidation around bundled chemical services. Long-term viability favors vendors with dual-hemisphere manufacturing footprints satisfying lead-time requirements for South Korean and Taiwanese memory chip complexes. Watch for ECHA substance evaluation protocol updates as inflection indicators that filter qualified vendor pools and concentrate market share.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Solvent Refining | Reduces dependency on German and Japanese chemical specialists for precursor formulation feedstock. |
| Long-term Supply Agreement with Memory Chip Foundries | Locks in volume commitments with Samsung and SK Hynix against organometallic feedstock price volatility. |
| REACH Registration and ECHA Authorization Investment | Filters out subscale competitors unable to sustain extended mammalian toxicity study costs. |
| Geographic Manufacturing Footprint Expansion | Establishes dual-hemisphere production to satisfy lead-time requirements for South Korean and Taiwanese fabs. |
| Water-Free Organometallic Formulation Development | Enables moisture-stable chemistries that compress qualification cycles for 3D NAND wordline fabrication. |
Research Methodology
Document review covered SEC 10-K filings from electronic materials suppliers, ECHA registration databases, and Korean customs trade data, complemented by interviews with fab procurement managers, contamination control engineers, and organometallic synthesis specialists. Primary fieldwork engaged deposition process engineers at semiconductor foundries, point-of-use delivery system integrators, and REACH compliance consultants. Secondary validation drew from ACC specialty chemical reports, MFDS chemical safety guidance, and perovskite solar cell manufacturer technical disclosures. Bottom-up precursor volume estimates triangulated against top-down electronic materials market sizing.
Historical shipment data cross-referenced against panel input from precursor suppliers and foundry procurement leads informed the analytical framework across the analysis window. Segmentation dimensions modeled include deposition technology compatibility, metal impurity grade tier, delivery mode infrastructure, and regional fabrication hub concentration. CAGRs derived from regression analysis of precursor procurement volumes against memory chip capacity expansion and perovskite solar cell manufacturing scale-up trajectories. Forecast inputs incorporated ALD process adoption curves and REACH authorization timeline compression.
Revisions become necessary when ECHA substance evaluation protocols extend registration timelines, South African or Russian mining concentrate supply disruptions materialize, or foundry node transition schedules accelerate beyond current roadmaps. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Embossing Powder Market
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Foundry Binders Market