
 Forchlorfenuron Market | 2026-2036
Forchlorfenuron Market Size, Share, and Industry Trends Forecast 2026-2036
Forchlorfenuron Market Analysis
EU REACH registration requirements for plant growth regulators is rebalancing procurement priorities across European import channels. AlzChem leverages its German manufacturing base to sustain supply continuity for regulated markets, while Anyang Quanfeng Biological anchors volume production from Henan Province. Zhengzhou Zhuoyue competes through specialized technical-grade output, and Yinhai Chemical differentiates via integrated intermediates-to-active-ingredient production.
Forchlorfenuron functions as a synthetic cytokinin plant growth regulator, specifically N-(2-chloro-4-pyridyl)-N'-phenylurea, applied at concentrations typically ranging from 1 to 10 ppm to stimulate cell division and fruit enlargement in table grapes and kiwifruit. The compound operates by disrupting auxin-cytokinin ratios to promote parthenocarpic fruit set without fertilization. Fruit Trees applications dominate value capture due to premium grape and kiwi cultivation economics, while Liquid formulations represent the fastest-expanding format driven by precision agriculture spraying systems. Direct Sales channels occupy margin-rich positions through agronomist-led technical advisory relationships with commercial growers.
EPA tolerance assessments under the Federal Insecticide, Fungicide, and Rodenticide Act shape United States import acceptance thresholds, while China's Ministry of Agriculture and Rural Affairs governs domestic registration and maximum residue limits for food safety compliance. EFSA peer reviews under EU 1107/2009 determine renewal eligibility for active substance approvals, directly conditioning market access duration. Stakeholders must monitor evolving residue detection methodologies and import parity shifts between Brazilian and Chinese supply origins.
Market Dynamics
Tightening residue limits under EU REACH and EPA tolerance recalibrations are compressing formulation margins while accelerating technical-grade purification investments across Chinese and European manufacturing bases.
Growth Catalysts
- Precision agriculture spraying systems:Automated vineyard management in California's Central Valley and Australia's Murray-Darling Basin is expanding calibrated forchlorfenuron application rates.
- EU 1107/2009 active substance renewals:EFSA peer review timelines are creating registration data package demand for legacy cytokinin producers seeking renewal eligibility.
- Table grape cultivation economics:Premium varietal expansion in Chile's Atacama Region and Peru's Ica Valley is pulling cytokinin inputs for uniform berry sizing.
Market Restraints
- 2-chloro-4-aminopyridine feedstock volatility:Pyridine derivative supply concentration in Shandong Province creates input cost instability for technical-grade manufacturers.
- Maximum residue limit divergence:Codex Alimentarius thresholds, EU MRLs, and EPA tolerances lack harmonization, forcing multi-standard formulation portfolios.
- Biostimulant substitution:Protein hydrolysate and seaweed extract alternatives are displacing synthetic cytokinins in organic-certified vineyard segments.
Strategic Opportunities
- Brazilian table grape export zones:São Francisco Valley expansion offers underpenetrated acreage for cytokinin adoption as export-oriented cultivation intensifies.
- Drone-based variable-rate application:UAV spraying systems are integrating with GIS-mapped vineyard zones to enable sub-block cytokinin dosing precision.
- China's dual carbon goals:MEE emission standards are incentivizing closed-loop technical synthesis investments with carbon intensity documentation.
Industry Challenges
- Residue detection methodology evolution:LC-MS/MS sensitivity improvements are compressing the gap between application timing and harvest windows.
- Good Agricultural Practice documentation:EUREP GAP and GLOBALG.A.P. certification timelines are extending grower onboarding for regulated export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forchlorfenuron Market |
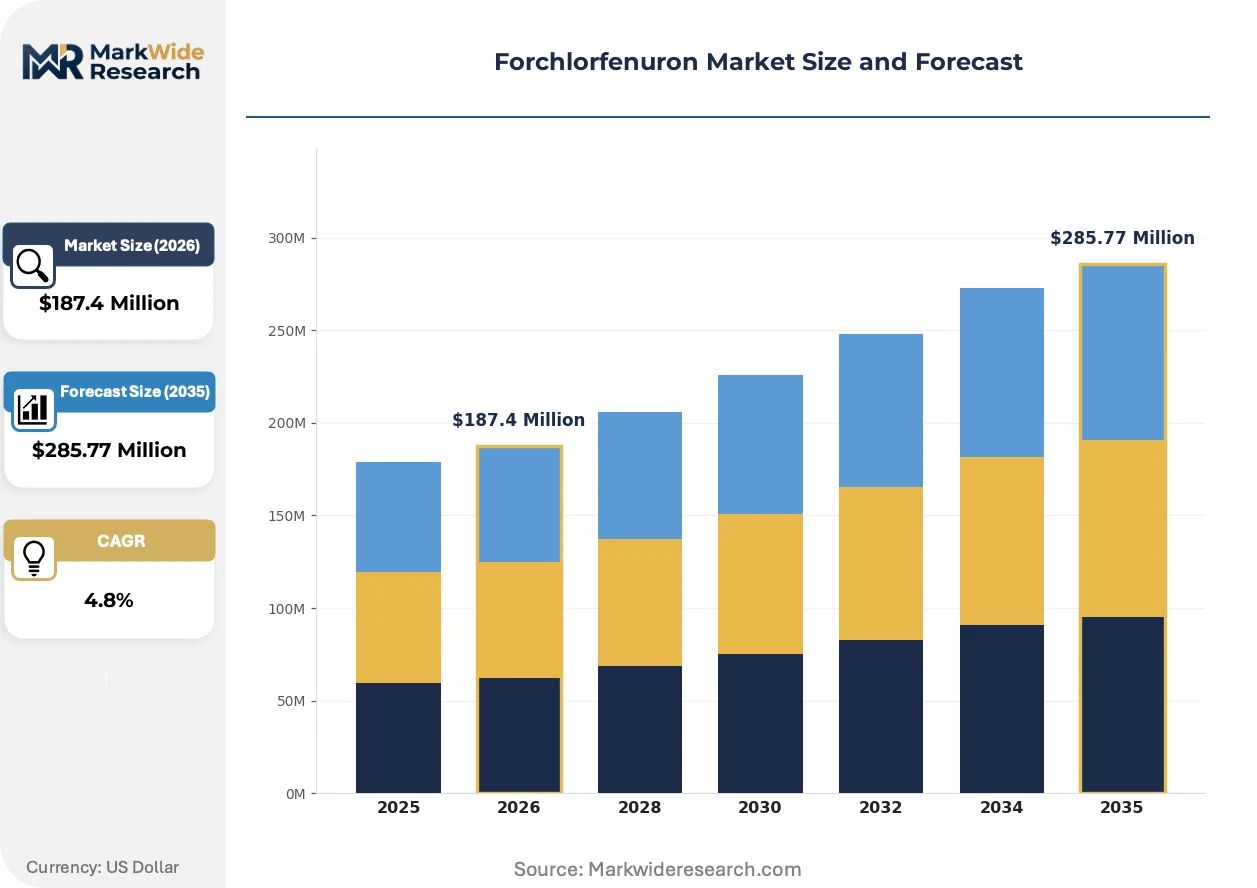
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fruit Trees, Vegetables, Cotton, Ornamentals Formulation Type: Liquid, Granular, Powder, Emulsifiable Concentrate Distribution Channel: Direct Sales, Online Retail, Distributors, Agricultural Stores End User: Farmers, Agronomists, Nursery Owners, Commercial Growers |
| Companies Covered | AlzChem, Anyang Quanfeng Biological, Zhengzhou Zhuoyue, Yinhai Chemical, Zhongke Chemical, Cheng Ming, Yinhe Chemical, Xinglian, Henan Door Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forchlorfenuron Market Emerging Trajectories
Formulation chemistry and application precision are converging to reshape cytokinin deployment economics across high-value fruit cultivation clusters.
Nano-emulsion delivery systems are integrating surfactant-stabilized active ingredient particles below 200 nanometers to enhance cuticular penetration in waxy grape varieties. California vineyard management firms are adopting these formulations for reduced-volume aerial applications. The technology is integrating with prescription agriculture platforms to enable real-time dose adjustment based on canopy density sensors.
EU REACH substance evaluation dossier requirements are forcing technical-grade producers to submit extended one-generation reproductive toxicity studies for renewal eligibility. Manufacturing facilities in Germany and China are restructuring purification trains to meet contaminant profile specifications. Table grape import channels into Rotterdam and Hamburg are prioritizing suppliers with complete Annex XV dossier submissions.
Direct-to-grower technical advisory channels are displacing traditional distributor networks in high-acreage vineyard operations. Agronomist-led subscription services in Australia's Riverina and California's Central Valley are bundling cytokinin protocols with phenological monitoring. This reconfiguration is most visible in 500+ hectare operations seeking integrated crop management accountability.
Forchlorfenuron Market Segmentation
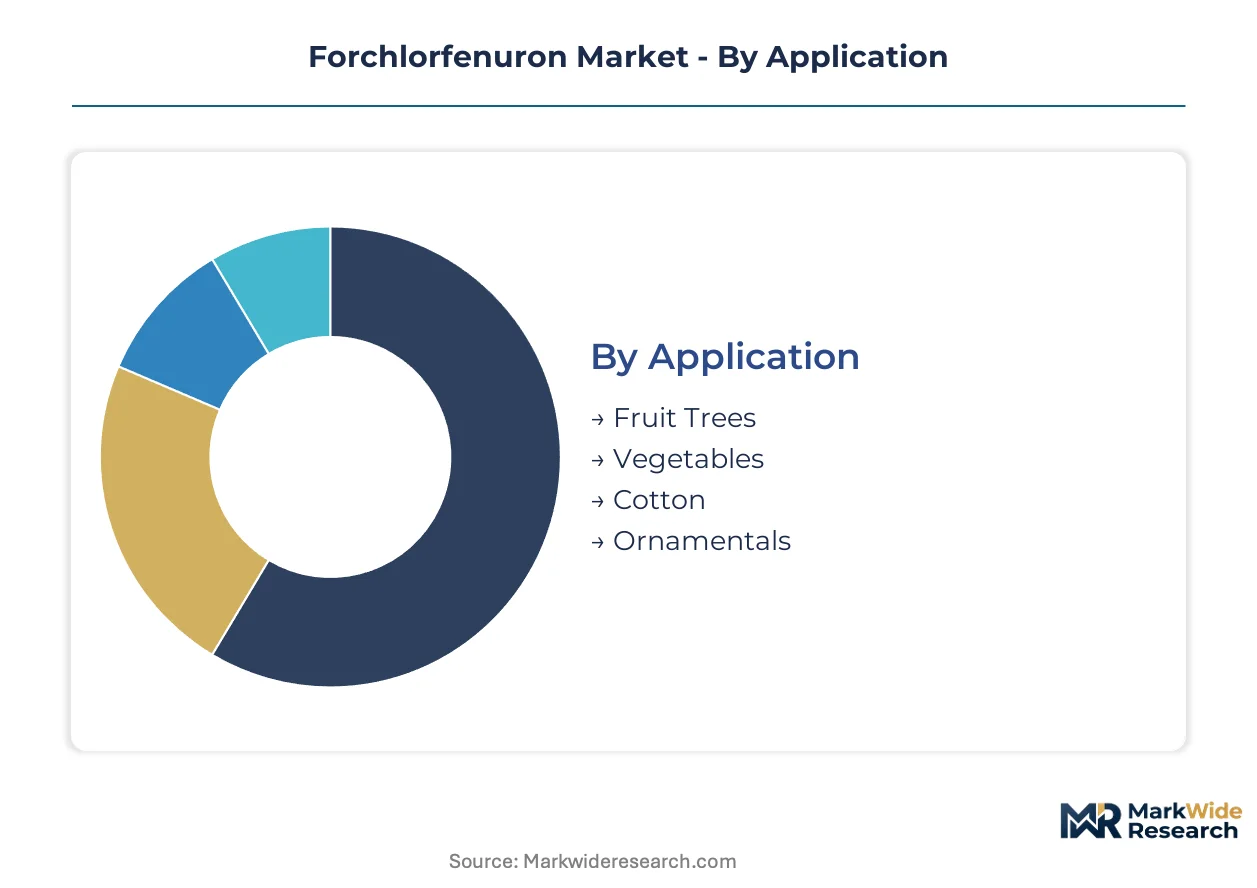
Forchlorfenuron procurement decisions hinge on residue compliance pathways and application precision requirements. Each segment carries distinct regulatory documentation burdens and technical advisory needs that reshape supplier selection criteria across cultivation clusters.
Application:
Fruit Trees applications require EFSA peer review alignment under EU 1107/2009 for renewal eligibility, while Vegetables and Cotton segments face divergent EPA tolerance thresholds and Codex Alimentarius MRL harmonization pressures.
- Fruit Trees:Dominant value concentration in table grape and kiwifruit cultivation, where cytokinin-induced cell division drives uniform berry sizing. Premium varietal expansion in Chile's Atacama Region and Peru's Ica Valley pulls technical-grade demand with strict harvest interval documentation.
- Vegetables:Cucumber and melon applications in China's Shandong Province leverage lower concentration protocols, though residue detection sensitivity improvements compress application-to-harvest windows under evolving GB standards.
- Cotton:Boll development applications concentrate in Xinjiang cultivation zones with boll retention protocols requiring SAMR registration compliance.
- Ornamentals:Nursery stock and cut flower applications in Netherlands' Westland cluster emphasize aesthetic uniformity with lower regulatory scrutiny than food crop segments.
Leading the category by volume: Fruit Trees. Growing fastest: Vegetables.
Formulation Type:
Margin structures diverge sharply between precision-spray-ready liquids and commodity powder formats, with nano-emulsion R&D investments concentrating in liquid and emulsifiable concentrate tiers.
- Liquid:Fastest-expanding format integrating with automated vineyard management systems in California's Central Valley. Surfactant-stabilized aqueous solutions enable calibrated 1-10 ppm dosing through precision agriculture spraying infrastructure.
- Emulsifiable Concentrate:Oil-in-water systems penetrating waxy grape cuticles in Australia's Murray-Darling Basin, where reduced-volume aerial applications demand enhanced penetration chemistry.
- Granular:Slow-release matrices for soil incorporation in cotton basins with labor-constrained application windows.
- Powder:Technical-grade bulk format dominating Chinese domestic procurement with cost-driven formulation flexibility.
Highest margin capture: Liquid. Steepest expansion trajectory: Emulsifiable Concentrate.
Distribution Channel:
Channel selection determines grower advisory depth and residue documentation support, with direct relationships commanding premium positioning in large-acreage operations.
- Direct Sales:Agronomist-led technical advisory bundles dominate 500+ hectare vineyard operations in Australia's Riverina, integrating cytokinin protocols with phenological monitoring subscriptions.
- Distributors:Traditional networks retain cotton and vegetable segments in China's Henan Province with volume-based procurement and limited technical support.
- Agricultural Stores:Local retail access for smallholder nursery owners and ornamental growers with standardized product portfolios.
- Online Retail:Emerging channel for documented product sourcing with batch traceability, particularly for export-oriented growers seeking GLOBALG.A.P. compliance records.
Deepest advisory integration: Direct Sales. Fastest channel shift: Online Retail.
End User:
User sophistication determines formulation specification tolerance and regulatory documentation requirements, segmenting the market by operational scale and export orientation.
- Commercial Growers:Export-oriented table grape operations in São Francisco Valley demand complete EU REACH Annex XV dossier alignment with residue testing protocols.
- Agronomists:Technical decision-makers prescribing precision application rates across managed vineyard portfolios with subscription-based accountability models.
- Farmers:Price-sensitive domestic market participants in China's Xinjiang Province prioritizing SAMR-registered formulations over export-grade documentation.
- Nursery Owners:Ornamental-focused users with lower residue compliance burdens and higher sensitivity to application labor costs.
Strictest compliance requirements: Commercial Growers. Fastest advisory service adoption: Agronomists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province anchors technical-grade forchlorfenuron manufacturing through pyridine derivative supply chains concentrated in Weifang and Binzhou chemical corridors.
China
Table grape cultivation in Xinjiang's Turpan Basin and Shandong's Yantai cluster consumes cytokinin inputs for uniform berry sizing under SAMR registration protocols. MEE emission standards under dual carbon goals are restructuring synthesis facilities toward closed-loop production with carbon intensity documentation. Henan Province's Anyang corridor houses volume manufacturers serving domestic fruit tree applications.
United States
California's Central Valley vineyard operations deploy precision agriculture spraying systems for calibrated cytokinin application in premium table grape blocks. EPA tolerance assessments under FIFRA shape import acceptance thresholds for technical-grade material. Automated vineyard management firms in Napa and Sonoma counties integrate liquid formulations with canopy density sensors.
Germany
EU REACH registration requirements condition import channel access through Rotterdam and Hamburg port gateways. EFSA peer reviews under EU 1107/2009 determine active substance renewal eligibility for legacy cytokinin producers. AlzChem leverages its Trostberg manufacturing base to sustain supply continuity for regulated European markets with complete Annex XV dossier alignment.
Chile
Atacama Region table grape export zones pull cytokinin inputs for premium varietal expansion targeting North American and Asian markets. Codex Alimentarius MRL harmonization pressures force harvest interval documentation for GLOBALG.A.P. certification. Iquique and Arica logistics corridors handle formulation imports for vineyard operations in Copiapó and Vallenar valleys.
Brazil
São Francisco Valley table grape intensification offers underpenetrated acreage for cytokinin adoption as export-oriented cultivation expands. ANVISA registration requirements govern plant growth regulator import protocols for fruit tree applications. Juazeiro and Petrolina clusters represent emerging demand centers with limited legacy synthetic cytokinin exposure.
Forchlorfenuron Market Vendor Landscape
The competitive structure tilts toward integrated chemical manufacturers with captive pyridine derivative supply. Technical-grade production concentrates among Chinese provincial specialists and European regulatory-compliant producers. Three archetypes dominate: upstream-integrated feedstock controllers, purification-focused technical specialists, and formulation-ready distributors. Capacity expansion and registration data package investments represent the dominant competitive vectors as renewal deadlines approach.
Among Henan-based biological specialists, Anyang Quanfeng Biological and Henan Door Chemical occupy positions within the volume-production tier. Zhengzhou Zhuoyue exemplifies the technical-grade purification specialist archetype. European regulatory compliance is anchored by AlzChem, a German GmbH-structured manufacturer. Yinhai Chemical represents the integrated intermediates-to-active-ingredient production model. These four entities collectively span the geographic and functional segmentation of supply-side capability.
| Leading Market Players |
|---|
| AlzChem |
| Anyang Quanfeng Biological |
| Zhengzhou Zhuoyue |
| Yinhai Chemical |
| Zhongke Chemical |
| Cheng Ming |
| Yinhe Chemical |
| Xinglian |
| Henan Door Chemical |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EU REACH-compliant technical purity and commodity-grade domestic formulations splits procurement economics across export and captive supply channels. This bifurcation concentrates margin capture with German and select Chinese manufacturers possessing complete Annex XV dossiers while compressing returns for undifferentiated powder suppliers serving price-sensitive domestic vegetable applications.
Pricing Analysis
Yield-per-hectare outcomes anchor value-based pricing for liquid cytokinin formulations in premium table grape operations. Three-tier pricing structure across export-certified, domestic food-grade, and industrial-grade purity levels reflects EFSA renewal status and residue documentation completeness. Pricing pressure stems from 2-chloro-4-aminopyridine feedstock volatility concentrated in Shandong Province. Commercial growers in export-oriented Chilean and Peruvian vineyard clusters exhibit lowest price sensitivity due to bundled agronomist advisory contracts.
Supply Chain Analysis
Direct-to-grower technical advisory channels handle large-acreage vineyard demand in Australia's Riverina and California's Central Valley. Technical-grade production concentrates in China's Shandong and Henan provinces alongside Germany's Trostberg manufacturing corridor. Pyridine derivative feedstocks, surfactant stabilizers, and nano-emulsion processing equipment constitute critical input dependencies. Single-source vulnerability in Shandong's chemical corridor threatens synthesis continuity for non-integrated manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Registration data package investments under EU 1107/2009 are consolidating supply-side capability around dossier-complete manufacturers, forcing technical-grade purification specialists without renewal resources toward exit or acquisition.
For Market Incumbents: Anchor supply continuity through captive pyridine derivative production or long-term offtake agreements with Shandong feedstock controllers. EFSA peer review timelines demand accelerated one-generation reproductive toxicity study submissions to defend renewal eligibility against emerging biostimulant substitutes. Backward integration into 2-chloro-4-aminopyridine synthesis mitigates input cost volatility threatening formulation margins. For New Entrants and Emerging Players: Mid-scale ornamental nursery operations in Netherlands' Westland cluster represent an underserved buyer archetype with lower regulatory documentation burdens and faster procurement cycles than export-oriented fruit tree segments. São Francisco Valley table grape intensification offers geographic white-space with limited legacy cytokinin exposure and rising GLOBALG.A.P. certification demand. Direct agronomist partnership models bypass entrenched distributor relationships in Australia's Riverina. For Investors and Strategic Acquirers: Re-rating potential sits with integrated intermediates-to-active-ingredient producers given tightening EU REACH contaminant profile specifications and carbon intensity documentation requirements under China's MEE standards. Long-term viability hinges on registration portfolio durability across multiple regulatory jurisdictions. Watch for EFSA non-renewal decisions on legacy cytokinin actives as inflection indicators for substitution technology acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyridine Feedstocks | Shandong Province supply concentration creates vulnerability for non-captive technical-grade manufacturers. |
| EU REACH Annex XV Dossier Completion | EFSA peer reviews under EU 1107/2009 determine renewal eligibility for active substance approvals. |
| Nano-Emulsion Formulation R&D | California vineyard management firms adopt sub-200 nanometer particles for waxy grape cuticle penetration. |
| Direct Agronomist Advisory Channel Buildout | 500+ hectare operations in Australia's Riverina seek bundled cytokinin protocols with phenological monitoring. |
| Closed-Loop Synthesis Investment | China's MEE emission standards incentivize carbon intensity documentation for technical-grade production. |
Methodological Framework
Multi-period observation of EFSA renewal timelines, EPA tolerance recalibrations, and SAMR registration protocols anchored the trend analysis, supplemented by interviews with plant growth regulator formulation chemists, technical-grade manufacturing plant managers, export-oriented table grape agronomists, and agricultural chemical procurement leads at European import distributors. Secondary validation drew from customs trade data, EU 1107/2009 regulatory filings, SEC 10-K disclosures by listed agrochemical firms, and GB standards evolution documentation. Bottom-up volume modeling triangulated against top-down value estimates across purification tiers.
Segment-weighting applied differential CAGR assumptions to liquid versus powder formulation trajectories, fruit tree versus vegetable application growth rates, and direct sales versus distributor channel expansion patterns across the projection horizon. Modeled dimensions included formulation type, application crop category, distribution channel structure, and regional regulatory cluster. CAGRs derived from regression analysis of historical technical-grade pricing and volume correlations with table grape cultivation economics. Forecast inputs incorporated precision agriculture spraying system adoption curves and drone-based variable-rate application penetration timelines.
Revisions become necessary when EFSA non-renewal decisions, abrupt EPA tolerance modifications, or feedstock supply disruptions in Shandong Province materialize. Forecasts reflect base-case assumptions regarding regulatory continuity and cultivation economics stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Embossing Powder Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Anti-Gelling Agent Market