
 Template Preparation Kits Market | 2026-2036
Template Preparation Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Template Preparation Kits Market Analytics
A shift from single-source to multi-source procurement is recalibrating how laboratories secure template preparation consumables. Thermo Fisher Scientific leverages its integrated supply chain to sustain pricing leverage across academic and clinical accounts. QIAGEN anchors its position through specialized silica-membrane chemistries that dominate nucleic acid extraction workflows. Illumina competes by bundling preparation modules with sequencing platforms, tightening vendor lock-in across high-throughput installations.
Template preparation kits encompass standardized reagent assemblies designed to isolate, purify, and qualify nucleic acid templates prior to downstream amplification or sequencing, typically incorporating buffer systems, binding matrices, and elution solutions calibrated to specific input types and yield thresholds. Their primary purpose centers on ensuring reproducible template quality across quantitative PCR, next-generation sequencing, and hybridization-based diagnostic applications. Standard kits occupy the mature volume tier where economies of scale compress per-reaction costs for high-frequency users, while custom kits capture expanding margin pools as pharmaceutical sponsors demand formulation modifications for proprietary assay pipelines. Contract research organizations represent the fastest-growing end-user channel as outsourced discovery and validation workflows multiply kit consumption per project.
FDA oversight of laboratory-developed tests and EPA guidelines for chemical waste disposal from extraction protocols jointly elevate compliance costs for kit manufacturers serving the United States market. ISO 13485 quality management standards and CE marking requirements under the EU In Vitro Diagnostic Regulation shape product design and market access trajectories for international suppliers. Stakeholders must monitor how harmonization pressures between FDA and EMA guidance documents reshape validation documentation burdens and regional kit registration timelines.
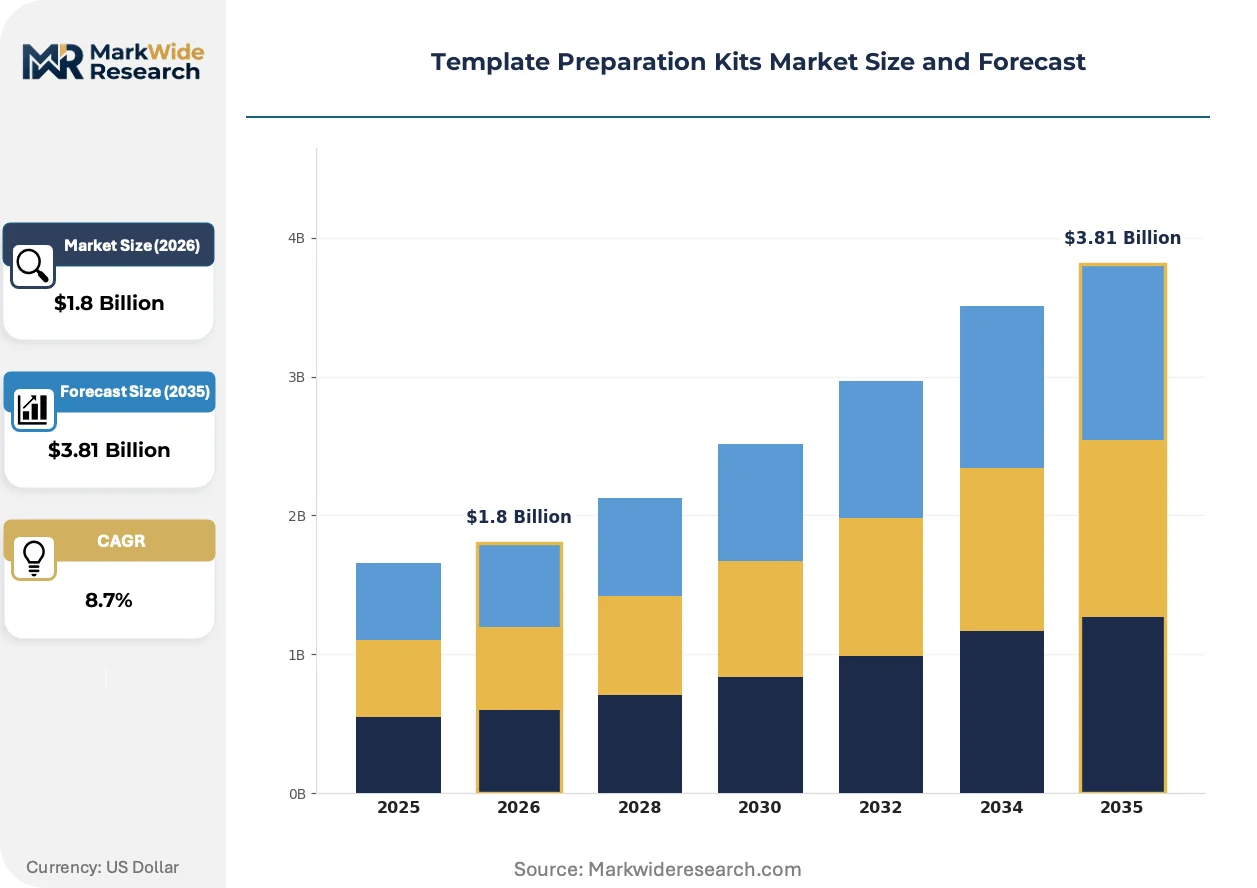
Market Dynamics
The Template Preparation Kits Market pivots on a structural tension between platform-integrated consumable bundles and open-architecture reagent sourcing, as sequencing instrument vendors tighten proprietary workflows while independent kit suppliers fight for standardization.
Growth Catalysts
- NIH funding expansion:Sustained federal research budgets in the United States accelerate sequencing throughput at academic medical centers, amplifying standardized kit procurement volumes.
- Silica-membrane chemistry maturation:Automated extraction platforms now process higher input volumes with reduced manual intervention, compressing per-sample labor costs for high-throughput clinical laboratories.
- Laboratory-developed test proliferation:FDA's evolving oversight framework for LDTs elevates kit validation documentation requirements, favoring suppliers with pre-validated, regulatory-ready reagent assemblies.
Market Restraints
- Platform lock-in economics:Sequencing instrument vendors bundle preparation modules at subsidized pricing, eroding standalone kit margins for third-party suppliers.
- Specialty enzyme cost volatility:Thermostable polymerase and modified reverse transcriptase inputs face supply concentration among contract fermentation providers.
- EPA chemical waste protocols:Extraction buffer disposal requirements elevate operational compliance burdens for United States-based laboratories.
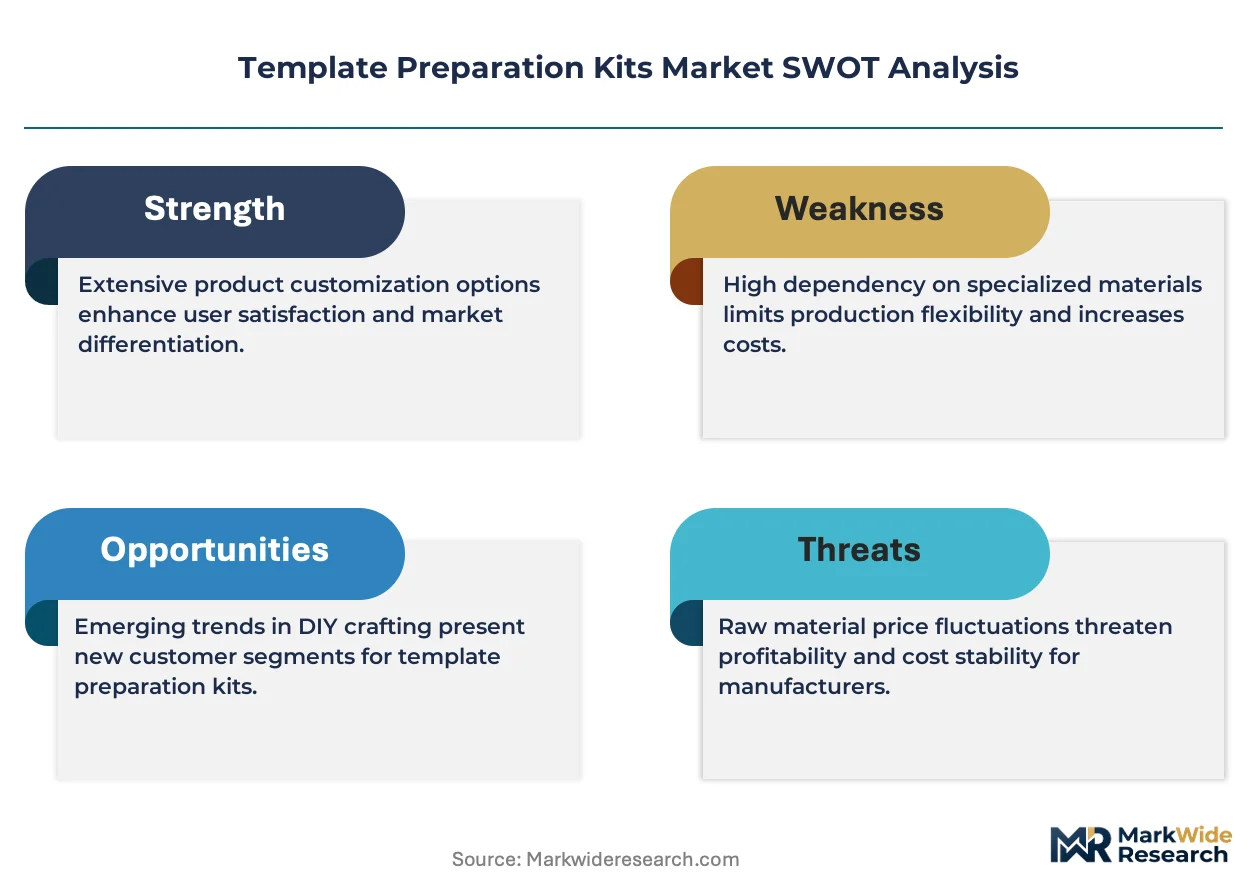
Strategic Opportunities
- Point-of-care molecular diagnostics:Miniaturized lyophilized preparation formats address unmet workflow needs in decentralized clinical settings.
- ISO 13485 certification arbitrage:Suppliers achieving quality management certification capture procurement preference from IVD manufacturers seeking upstream integration.
- Cloud-connected reagent tracking:RFID-enabled kit consumption monitoring aligns with laboratory information system integration mandates.
Industry Challenges
- Bioinformatics integration complexity:Template preparation outputs must align with downstream pipeline software, requiring cross-functional coordination between wet-lab and computational teams.
- CE-IVD marking timeline compression:EU In Vitro Diagnostic Regulation transition deadlines compress certification windows for legacy product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Template Preparation Kits Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Kits, Custom Kits, Bulk Kits, Reagent Kits End User: Pharmaceutical Companies, Academic Institutions, Contract Research Organizations, Biotechnology Firms Application: Clinical Research, Diagnostic Testing, Drug Development, Educational Purposes Packaging Type: Boxed Kits, Vial Kits, Pouch Kits, Tube Kits |
| Companies Covered | Thermo Fisher Scientific, Illumina, QIAGEN, Agilent Technologies, Bio-Rad Laboratories, Danaher Corporation, PerkinElmer, F. Hoffmann-La Roche, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Template Preparation Kits Market Evolving Landscape
Workflow automation and regulatory data integrity requirements are recalibrating how template preparation kits are designed, validated, and procured across clinical and research environments.
Magnetic bead-based nucleic acid purification is rewriting extraction throughput economics. Contract research organizations deploy these systems at scale to compress sample-to-sequence timelines. The shift is displacing column-based methods in high-volume installations where hands-free processing outweighs per-reagent cost premiums.
EU In Vitro Diagnostic Regulation performance evaluation requirements are elevating clinical evidence burdens for kit manufacturers. Suppliers must now generate systematic analytical and clinical validation data that was previously self-certified. Medium-sized reagent houses face capital allocation decisions between EU market retention and geographic portfolio rebalancing.
Consolidated procurement through group purchasing organizations is concentrating buyer leverage at integrated health systems. Independent laboratories lose price transparency as contract tiers stratify by committed volume. The pattern is most pronounced in United States hospital networks where supply chain centralization mandates single-source or dual-source reagent agreements.
Template Preparation Kits Market Segmentation
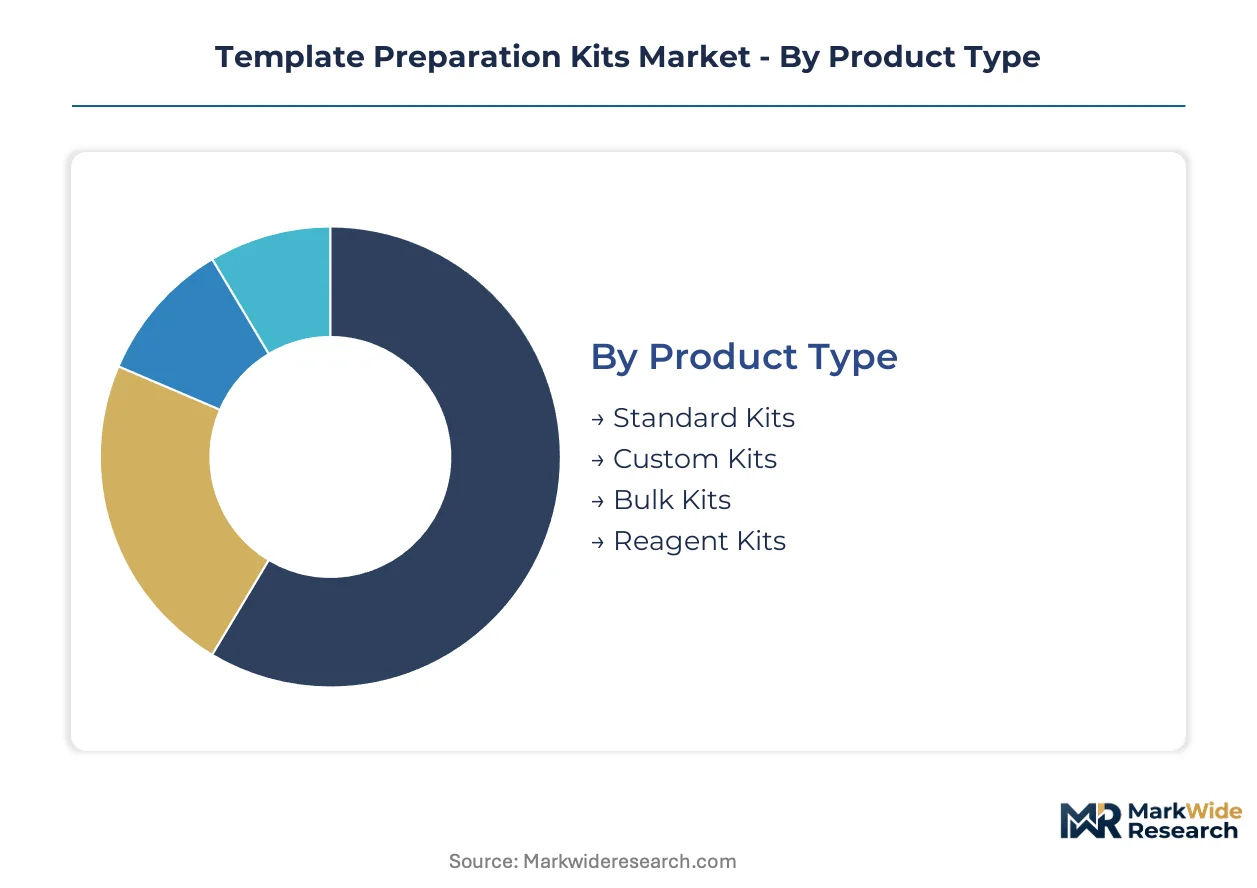
Template preparation kits fragment across four distinct axes that shape procurement patterns and margin structures. Product specifications determine workflow compatibility, while end-user scale dictates volume economics and regulatory documentation intensity.
Product Type:
Specifications range from off-the-shelf formulations to proprietary modifications calibrated for specialized input matrices.
- Standard Kits:Pre-validated reagent assemblies with fixed buffer compositions and binding matrices. Academic medical centers in the United States anchor procurement volumes through NIH-funded sequencing workflows, though per-reaction margins compress at high throughput.
- Custom Kits:Formulation modifications tailored to proprietary assay pipelines, including altered elution chemistries or stabilizer concentrations. Pharmaceutical sponsors in Boston and San Francisco biotech corridors drive demand as they internalize validation documentation for FDA-submitted companion diagnostics.
- Bulk Kits:Industrial-scale packaging configurations for centralized preparation facilities.
- Reagent Kits:Component-level assemblies permitting user-defined protocol assembly.
Standard kits lead on scale; custom kits lead on momentum.
End User:
Customer scale and regulatory sophistication stratify pricing tolerance and certification requirements.
- Contract Research Organizations:Outsourced discovery and validation workflows multiply kit consumption per project. CROs in Research Triangle Park and San Diego cluster sites prioritize ISO 13485-certified suppliers to streamline sponsor technology transfer.
- Academic Institutions:Federally funded research centers with standardized extraction protocols. NIH budget cycles directly correlate with procurement timing at major university medical centers.
- Pharmaceutical Companies:Internal R&D and regulated quality control operations.
- Biotechnology Firms:Venture-backed development shops with platform-specific preparation needs.
Academic institutions dominate absolute volume; contract research organizations show the steepest expansion trajectory.
Application:
Downstream use case determines regulatory classification and validation evidence burden.
- Diagnostic Testing:Patient sample processing for clinical decision-making. FDA oversight of laboratory-developed tests elevates kit traceability requirements, favoring suppliers with pre-submitted master files.
- Drug Development:Biomarker qualification and pharmacogenomic screening. Toxicology studies at contract research organizations demand lot-to-lot consistency documentation.
- Clinical Research:Investigator-sponsored trials with institutional review board protocols.
- Educational Purposes:Training laboratories with simplified workflow requirements.
Diagnostic testing commands premium positioning; drug development shows the fastest volume climb.
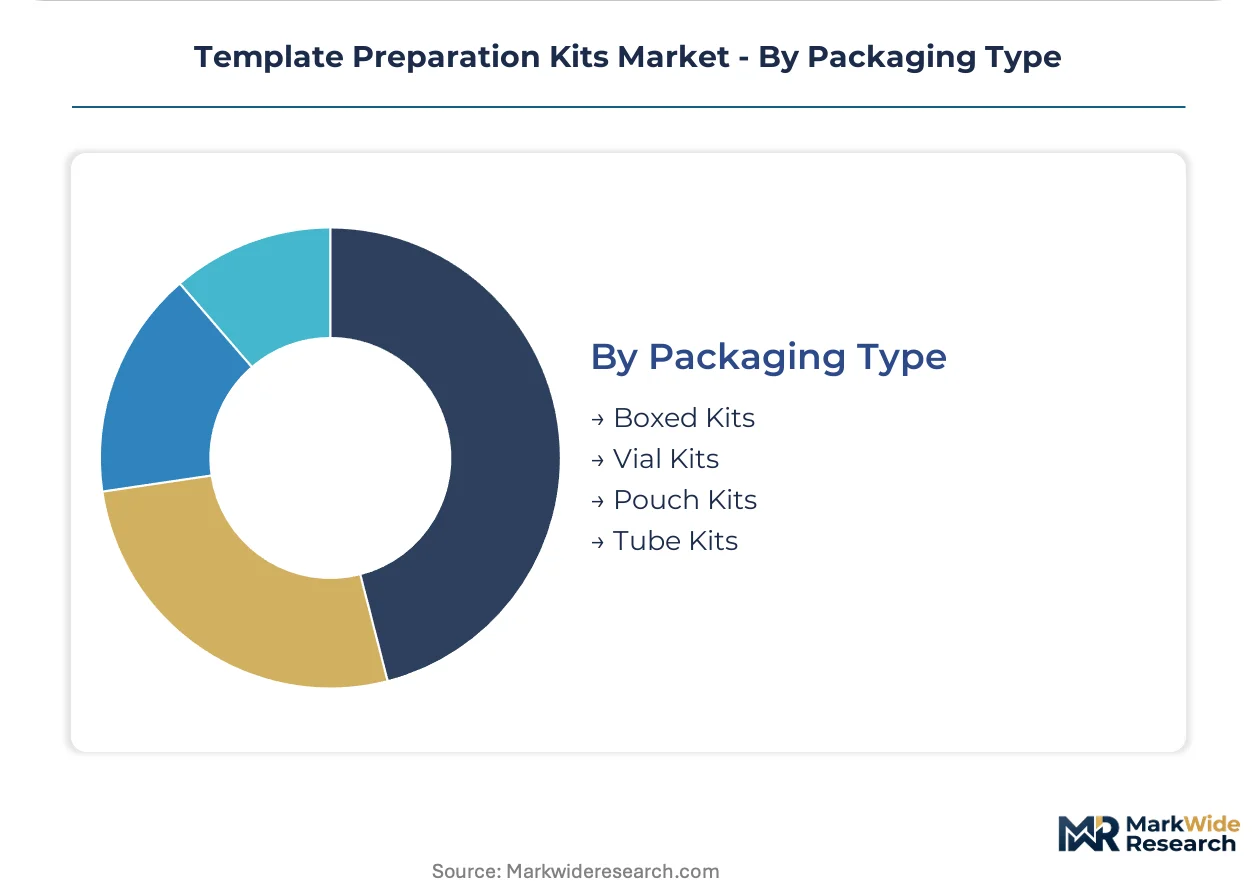
Packaging Type:
Physical configuration aligns with automation compatibility and cold-chain requirements.
- Boxed Kits:Comprehensive assemblies with printed protocols and accessory components. High-throughput clinical laboratories in the United States favor these for workflow standardization across shift changes.
- Tube Kits:Pre-aliquoted single-use configurations for lyophilized reagent stability. Point-of-care molecular diagnostic developers prefer tube formats for miniaturized instrument integration.
- Vial Kits:Concentrated stock solutions requiring user dilution.
- Pouch Kits:Flexible packaging for field-deployable applications.
Boxed kits retain volume leadership; tube kits gain share fastest in decentralized settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston-Cambridge biotech corridor anchors procurement volumes through concentrated pharmaceutical R&D and NIH-funded academic sequencing workflows. Kit manufacturers prioritize FDA-compliant documentation for laboratory-developed tests here. Geographic expansion targets secondary clusters where automated extraction platforms displace manual protocols.
United States
NIH budget cycles at Bethesda directly correlate with procurement timing at university medical centers nationwide. FDA oversight of laboratory-developed tests elevates validation documentation requirements for kit suppliers. San Diego and Research Triangle Park clusters drive specialized demand for ISO 13485-certified reagent assemblies in outsourced discovery workflows.
Germany
Baden-Württemberg precision medicine initiatives accelerate adoption of automated nucleic acid extraction systems. EMA guidance on companion diagnostic validation shapes kit registration timelines for EU market access. Munich biotech cluster concentrates demand for CE-IVD marked preparation modules in clinical research settings.
China
NMPA regulatory pathway acceleration for innovative diagnostics expands addressable market for standardized preparation kits. Domestic biopharma R&D expansion in Shanghai and Suzhou industrial parks multiplies kit consumption per drug development project. Yangtze River Delta manufacturing bases supply cost-competitive silica-membrane chemistries regionally.
United Kingdom
Genomics England population sequencing programs sustain high-throughput kit procurement at scale. MHRA post-Brexit regulatory autonomy creates divergence from EU CE marking requirements for IVD manufacturers. London-Oxford-Cambridge golden triangle concentrates demand for custom kit formulations in cell therapy development.
Japan
PMDA streamlined review pathways for nucleic acid detection kits accelerate product registration for international suppliers. METI biotechnology sector subsidies stimulate domestic sequencing infrastructure expansion. Kanto region pharmaceutical headquarters anchor demand for GMP-grade preparation reagents in regulated quality control operations.
Template Preparation Kits Market Competitive Landscape
Global majors compete with regional champions across platform integration and open-architecture sourcing dimensions. Market structure tilts toward consolidated procurement through integrated health system contracts, though independent laboratories retain fragmented purchasing patterns. Three archetypes dominate: sequencing instrument vendors bundling preparation modules, specialized reagent houses with proprietary chemistries, and diversified life science conglomerates leveraging supply chain scale. Competitive moves center on strategic partnerships for automated platform compatibility and geographic expansion into emerging biotech clusters.
Within the platform-integrated tier, Thermo Fisher Scientific and Illumina exemplify contrasting approaches to consumable lock-in. QIAGEN occupies a distinct position as a specialized reagent house with chemistry-focused differentiation. These three anchors represent the spectrum from diversified conglomerate to platform bundler to niche specialist, each commanding procurement preference through different validation and workflow integration pathways.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| QIAGEN |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Danaher Corporation |
| PerkinElmer |
| F. Hoffmann-La Roche |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
EPA chemical waste protocols for extraction buffer disposal gate qualified supply and premium-tier pricing access for kit manufacturers serving United States laboratories. Compliance with these environmental mandates requires specialized formulation engineering and documented disposal chain of custody, capabilities that concentrate among established suppliers with dedicated regulatory affairs infrastructure.
Pricing Analysis
Specialty enzyme cost pass-through from contract fermentation providers shapes margin structures across the reagent tier. Pricing stratifies across ISO 13485-certified premium tiers, standard research-grade formulations, and economy bulk configurations for high-throughput academic centers. Cost compression in standard kits intensifies as sequencing instrument vendors subsidize bundled preparation modules. Academic institutions exhibit highest price sensitivity; pharmaceutical sponsors developing companion diagnostics show lowest sensitivity due to validation documentation requirements.
Supply Chain Analysis
China's NMPA domestic-content mandates for innovative diagnostics are reshaping sourcing patterns for silica-membrane chemistries and magnetic bead substrates. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta bases supplying cost-competitive binding matrices. Supply chain risk centers on single-source vulnerability for thermostable polymerase inputs from concentrated fermentation providers. Distribution runs through group purchasing organizations at integrated health systems and direct procurement at independent research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Template Preparation Kits Market functions as a stable compounder anchored by sustained NIH funding cycles that perpetuate sequencing infrastructure investment across academic medical centers.
For Market Incumbents: Deepen ISO 13485 certification coverage to defend against emerging regional champions capturing sponsor technology transfer workflows. Expand captive supply of modified reverse transcriptase inputs to offset specialty enzyme cost volatility from contract fermentation providers. Strengthen automated platform compatibility partnerships to counter sequencing instrument vendor bundling strategies. For New Entrants and Emerging Players: Mid-sized contract research organizations in secondary biotech clusters represent an underserved buyer archetype with unmet demand for regulatory-ready reagent assemblies. Penetrate Research Triangle Park and San Diego CRO sites through ISO 13485-certified custom kit offerings with accelerated lot-to-lot documentation. Pursue sponsor-direct relationships to bypass incumbent distributor lock-in at consolidated health systems. For Investors and Strategic Acquirers: Roll-up economics work for specialized reagent houses with proprietary silica-membrane chemistries because platform-integrated bundling has not fully displaced open-architecture sourcing in outsourced discovery workflows. Target acquisition candidates with CE-IVD marking momentum and automated extraction platform compatibility. Monitor FDA laboratory-developed test guidance evolution as the critical inflection signal for validation documentation intensity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Captures procurement preference from IVD manufacturers seeking upstream integration partners. |
| Automated Platform Compatibility Partnership | Aligns with magnetic bead-based purification displacement of manual column methods. |
| CE-IVD Marking Pathway Acceleration | Addresses EU In Vitro Diagnostic Regulation performance evaluation timeline compression. |
| Cloud-Connected Reagent Tracking Development | Supports RFID-enabled consumption monitoring for laboratory information system integration. |
| Point-of-Care Miniaturization Launch | Addresses unmet workflow needs in decentralized clinical settings with lyophilized formats. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with laboratory directors, GPO contracts managers, regulatory affairs leads at kit manufacturers, and procurement officers at contract research organizations. Secondary validation draws from FDA 510(k) filings, EMA companion diagnostic guidance documents, NIH budget appropriations records, and ISO certification databases. Bottom-up segment sizing triangulates against top-down market envelope checks.
Granularity-level modeling disaggregates volume and value across product type, end user, application, and packaging configuration dimensions, with additional stratification by regional regulatory cluster and automation compatibility tier. CAGRs derive from fitted growth curves calibrated to NIH funding trajectories, sequencing platform installation bases, and laboratory-developed test proliferation patterns. Forecast inputs incorporate silica-membrane chemistry maturation curves and magnetic bead adoption elasticities.
Underlying measurement precision varies by segment; standard kits and academic end users carry tighter precision than custom formulations and pharmaceutical sponsor channels due to procurement transparency differences. Forecasts reflect assumptions about regulatory harmonization pressures and EPA enforcement consistency that could shift materially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Embossing Powder Market