
 Embossing Powder Market | 2026-2036
Embossing Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Embossing Powder Market Foresight
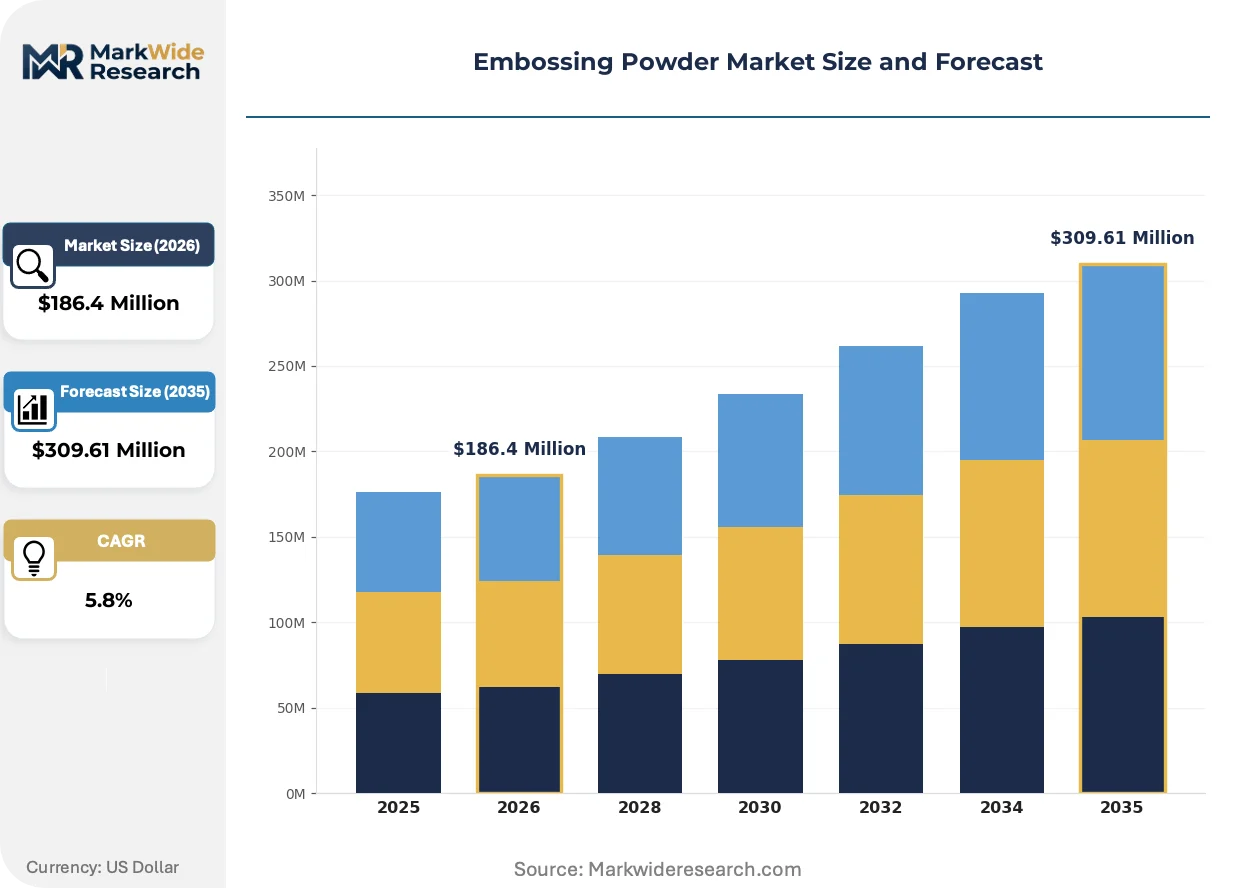
Multi-source pigment procurement is realigning how embossing powder formulators manage cost volatility and color consistency across batches. Ranger Industries leverages captive resin blending capabilities to secure margin stability in metallic formulations. WOW Embossing Powder anchors its position through direct-to-crafter digital channels that bypass traditional wholesale markups. Stampendous specializes in seasonal color palettes that dominate hobby retail shelf space during peak crafting periods.
Embossing powder consists of finely ground thermoplastic resin particles, typically 50–200 microns in diameter, that melt and fuse when exposed to controlled heat to create raised, textured surface effects on paper, cardstock, and mixed-media substrates. The material composition combines polymer or acrylic base resins with powdered pigments and flow-control additives to ensure uniform melting and adhesion at temperatures between 275°F and 350°F. Metallic and glossy product types command premium positioning due to higher pigment loading and specialized mica or pearl additive requirements. Crafting and card making applications absorb the majority of volume, though scrapbooking retains stronger per-unit pricing power through archival-grade certification demands. Powdered pigment and polymer material segments face divergent margin pressures as titanium dioxide and specialty resin feedstock costs fluctuate on commodity markets.
EPA oversight of volatile organic compound emissions from powder coating and decorative finishing processes shapes formulation chemistry decisions for U.S.-based manufacturers. REACH registration requirements in Europe restrict certain phthalate plasticizers and heavy-metal pigments, compelling reformulation of legacy embossing powder lines. BIS quality certification for imported craft materials affects market access for Asian suppliers serving Indian specialty retailers. Stakeholders must monitor evolving polymer resin classification under emerging chemical hazard frameworks and calibrate R&D budgets toward compliant pigment alternatives before regulatory deadlines compress formulation timelines.
Market Dynamics
REACH compliance deadlines across Europe are forcing wholesale reformulation of legacy embossing powder lines, compressing R&D timelines and raising barrier costs for smaller compounders who lack captive resin synthesis capabilities.
Growth Catalysts
- Card making hobbyist expansion:Small-scale manufacturers and DIY crafters are scaling embossing powder consumption through direct digital channels, bypassing traditional wholesale distribution markups.
- REACH-driven pigment substitution:European manufacturers accelerating compliant pigment alternatives ahead of registration deadlines are capturing shelf space from legacy suppliers.
- Archival-grade certification pull:Scrapbooking segments demanding acid-free, lignin-free formulations command sustained per-unit premiums and repeat purchase loyalty.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin stability for metallic and opaque white formulations, forcing frequent pricing adjustments.
- Asian supply concentration:Specialty polymer resin production clusters in China create single-source vulnerability for North American and European compounders.
- Digital printing substitution:Inkjet and toner-based dimensional effects are displacing heat-embossed finishes in commercial stationery and packaging prototypes.
Strategic Opportunities
- Indian specialty retail penetration:BIS certification-compliant suppliers can access underserved urban craft markets where organized retail infrastructure is expanding.
- Seasonal color palette pre-positioning:Direct-to-crafter digital channels enable just-in-time color drops aligned with holiday crafting cycles.
- Biobased resin convergence:Formulators combining polylactic acid thermoplastics with mineral pigments are unlocking compostable embossing powder categories.
Industry Challenges
- Reformulation timeline compression:Regulatory deadlines for phthalate-free plasticizers are squeezing product development cycles without guaranteed raw material availability.
- Color-matching skill scarcity:Batch-to-batch consistency demands specialized technicians with cross-training in polymer rheology and pigment dispersion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embossing Powder Market |
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $309.61 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glossy, Matte, Metallic, Clear Application: Crafting, Scrapbooking, Card Making, Decorative Arts Material: Polymer, Acrylic, Resin, Powdered Pigment Distribution Channel: Online Retailers, Specialty Stores, Wholesale Distributors, Others |
| Companies Covered | Ranger Industries, WOW Embossing Powder, Stampendous, Hero Arts, Tsukineko, Stewart Superior, Fine Glitter Powder, Percolour Polymer, Clearsnap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embossing Powder Market Shifts & Advancements
Formulation chemistry, regulatory compliance architecture, and distribution channel structure are simultaneously transforming how embossing powder reaches end-users and what performance specifications define commercial viability.
Low-temperature melting resin systems are overtaking conventional thermoplastic formulations in mixed-media applications. Crafters working with heat-sensitive substrates like vellum and acetate are adopting sub-250°F powders that fuse without warping delicate materials. This temperature threshold compression is overtaking traditional 275-350°F product lines in specialty retail assortments.
ECHA's evolving SVHC candidate list is tightening acceptable pigment chemistries across European embossing powder imports. Manufacturers are phasing out legacy cadmium and lead-based colorants ahead of formal authorization deadlines. Metallic finish suppliers serving German and French craft distributors are most affected, accelerating mica and synthetic pearl additive substitution programs.
Subscription box curation is consolidating craft supply purchasing into predictable monthly commitments. Card making enthusiasts receive pre-selected embossing powder assortments through dedicated hobby platforms, displacing individual SKU selection at brick-and-mortar retailers. This bundling behavior is most visible in United States coastal metropolitan markets where craft subscription penetration exceeds national averages.
Embossing Powder Market Segmentation
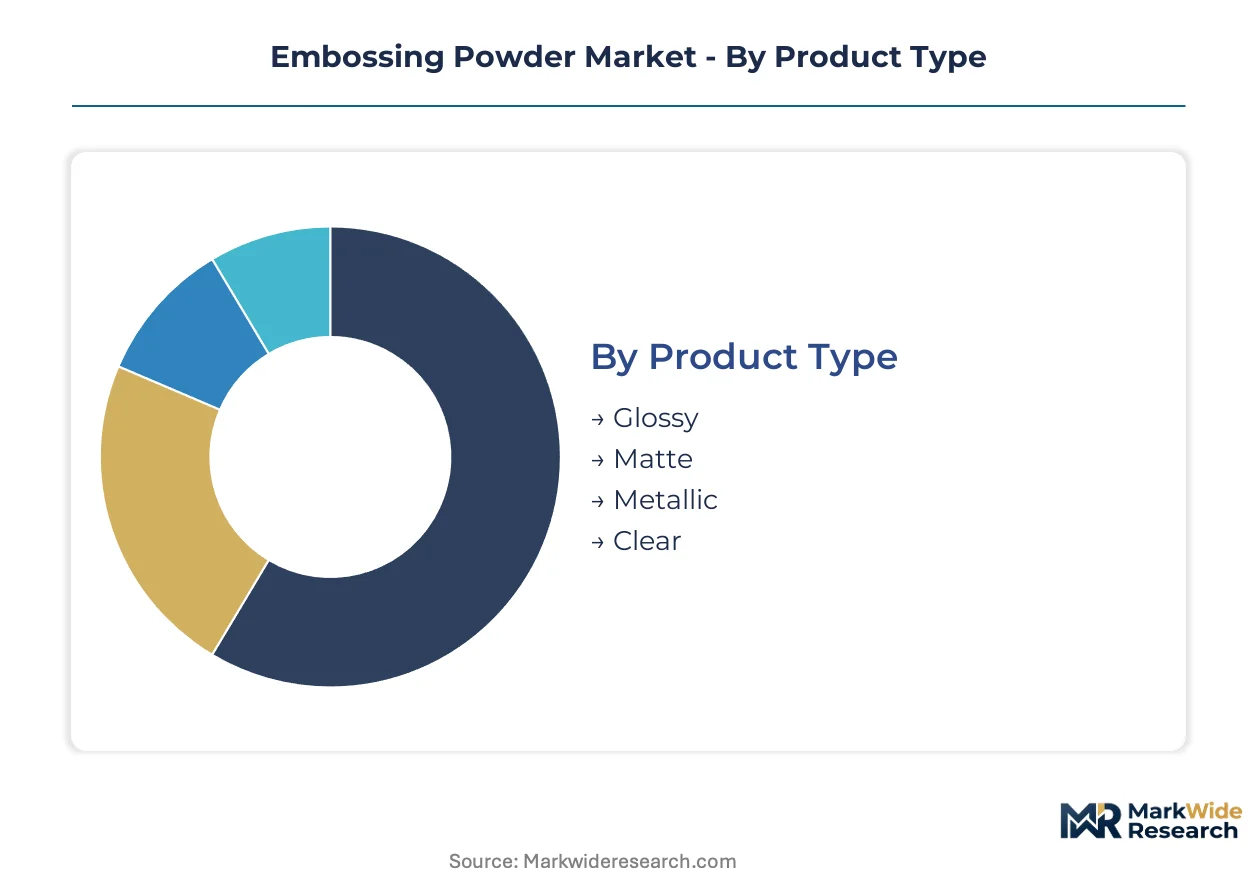
Embossing powder formulators configure product portfolios across four intersecting dimensions that determine margin capture and channel access. Technical specifications in resin chemistry and pigment loading separate premium positioning from commodity competition, while application-specific performance requirements reshape R&D allocation across customer segments.
Product Type:
Upgrade cycles in craft supply purchasing favor specialized finishes that command shelf space renewal and repeat engagement from hobbyist collectors.
- Metallic:Mica and synthetic pearl additives create reflective surface effects requiring higher pigment loading and controlled particle size distribution. Card making specialists in the United States absorb the majority of metallic volume through direct-to-crafter digital channels that emphasize limited-edition color drops. REACH-driven substitution of legacy metal-based colorants is compressing formulation timelines for European metallic suppliers.
- Glossy:High-clarity thermoplastic resins with optimized flow-control additives produce mirror-like raised finishes on cardstock and mixed-media substrates. Scrapbooking applications demanding archival-grade certification sustain per-unit premiums for glossy formulations that guarantee acid-free, lignin-free performance. Titanium dioxide feedstock volatility in opaque white glossy bases forces frequent pricing recalibration.
- Matte:Diffused surface finishes appeal to minimalist aesthetic trends in contemporary paper crafting, utilizing modified resin systems that scatter rather than reflect incident light.
- Clear:Transparent thermoplastic bases enable substrate-texture preservation and custom pigment blending by advanced crafters, serving niche professional segments.
Metallic sits at the top of the volume ranking, with Glossy climbing the fastest.
Application:
Volume concentration patterns track hobbyist engagement intensity and project complexity requirements across distinct creative disciplines.
- Card Making:Heat-embossed greeting cards and stationery drive the steepest expansion trajectory as small-scale manufacturers and DIY enthusiasts scale consumption through subscription box curation and social media tutorial influence. United States coastal metropolitan markets exhibit penetration rates exceeding national averages. Low-temperature melting resin systems are displacing conventional formulations for heat-sensitive vellum and acetate applications.
- Scrapbooking:Archival preservation standards demand acid-free, lignin-free, and photo-safe embossing powder certifications that sustain repeat purchase loyalty and per-unit pricing power. German and French craft distributors enforce stringent ECHA SVHC compliance for scrapbooking lines serving European memory-keeping enthusiasts. Seasonal color palette pre-positioning dominates hobby retail shelf space during peak crafting periods.
- Crafting:General mixed-media applications span home décor, altered art, and jewelry making with diverse substrate compatibility requirements.
- Decorative Arts:Professional artists and designers utilize embossing powder for dimensional effects in fine art and commercial display applications.
Card Making generates the highest absolute volume, with Scrapbooking retaining the strongest pricing discipline.
Material:
Feedstock cost volatility and regulatory classification pressures are fragmenting procurement strategies across base resin chemistries.
- Polymer:Thermoplastic resin systems dominate commercial embossing powder production, offering tunable melting points between 275°F and 350°F for controlled fusion behavior. Specialty polymer resin production clusters in China create single-source vulnerability for North American and European compounders seeking supply security. Captive resin blending capabilities at major formulators insulate margin stability from commodity price swings.
- Powdered Pigment:Titanium dioxide, mineral colorants, and specialty additives determine optical properties and regulatory compliance profiles across all product lines. REACH registration requirements restrict certain heavy-metal pigments, compelling reformulation investment before authorization deadlines. Multi-source pigment procurement is realigning how formulators manage cost volatility and batch-to-batch color consistency.
- Acrylic:Alternative thermoplastic bases offer distinct adhesion characteristics and substrate compatibility for specialized applications.
- Resin:Captive synthesis capabilities differentiate integrated manufacturers from compounders dependent on merchant resin supply.
Polymer commands the largest material share, with Powdered Pigment experiencing the most acute margin pressure.
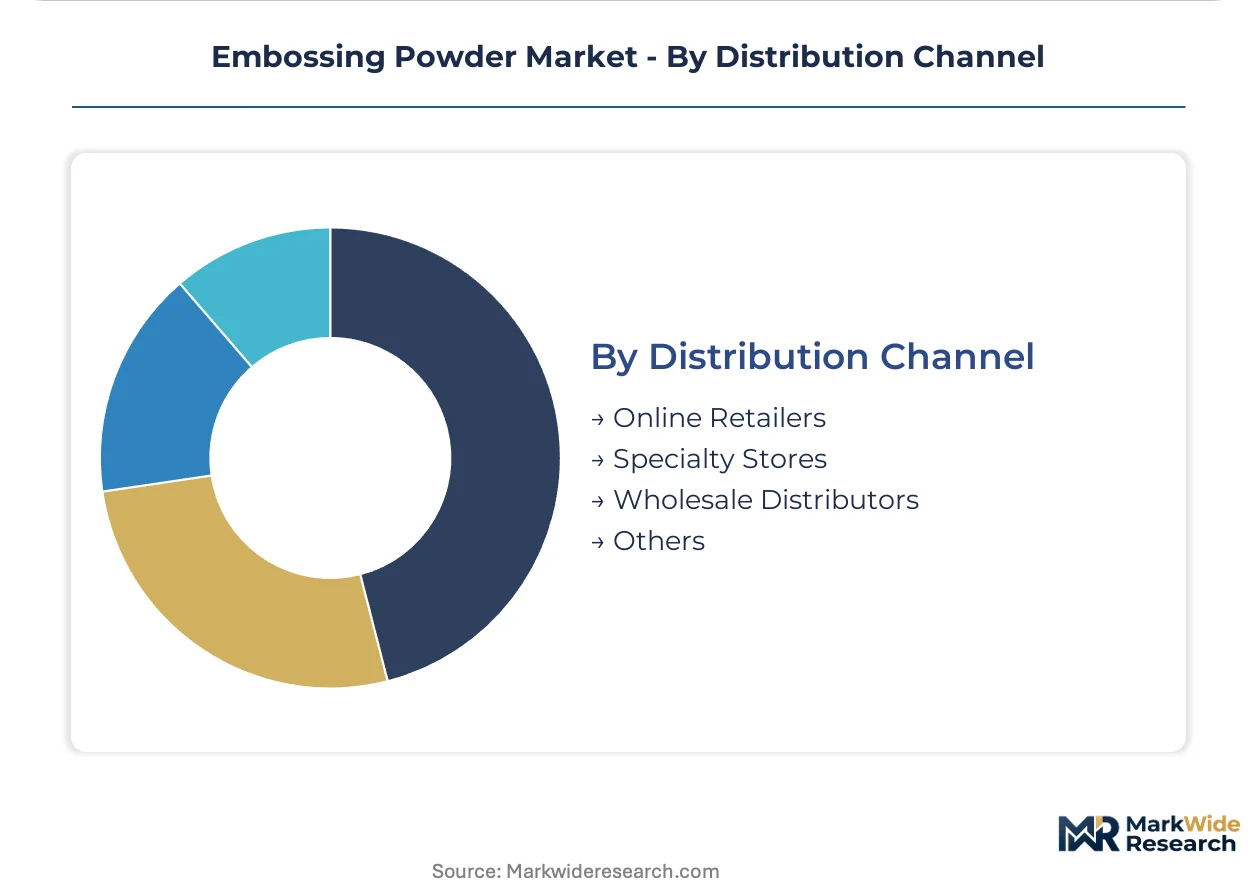
Distribution Channel:
Channel structure determines pricing transparency, customer acquisition economics, and inventory velocity for embossing powder suppliers.
- Online Retailers:Direct-to-crafter digital platforms bypass traditional wholesale markups and enable just-in-time color drops aligned with holiday crafting cycles. Subscription box curation consolidates purchasing into predictable monthly commitments, displacing individual SKU selection at physical retail. United States craft retail infrastructure sustains above-average uptake through online specialty channels.
- Specialty Stores:Hobby retail chains and independent craft shops provide tactile product evaluation and immediate availability for impulse purchasing. BIS quality certification for imported craft materials affects market access for Asian suppliers serving Indian specialty retailers expanding organized retail infrastructure.
- Wholesale Distributors:Traditional bulk supply relationships serve commercial stationery producers and educational institutional purchasing.
- Others:Direct sales, craft fair vending, and maker space consignment fill residual channel coverage.
Online Retailers anchor volume leadership, with Specialty Stores defending the highest per-transaction values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping embossing powder production geography as formulators relocate manufacturing to jurisdictions with lower compliance costs while maintaining market access through distributed warehousing.
United States
Card making hobbyists in coastal metropolitan markets drive consumption through subscription box curation and social media tutorial influence. EPA oversight of volatile organic compound emissions shapes formulation chemistry decisions for domestic manufacturers. Ranger Industries maintains captive resin blending capabilities in California to insulate margin stability from commodity price swings.
Germany
Scrapbooking enthusiasts demanding archival-grade certifications sustain per-unit premiums for acid-free, lignin-free formulations. ECHA's evolving SVHC candidate list tightens acceptable pigment chemistries, compelling metallic finish suppliers to accelerate mica substitution programs. Stuttgart-based craft distributors enforce stringent REACH compliance for memory-keeping product lines.
China
Specialty polymer resin production clusters create single-source vulnerability for North American and European compounders seeking supply security. MIIT standards and dual carbon goals pressure domestic formulators toward cleaner thermoplastic synthesis. Guangdong Province hosts concentrated thermoplastic resin manufacturing serving global embossing powder compounders.
India
Urban craft markets in expanding organized retail infrastructure present penetration opportunities for BIS certification-compliant suppliers. BIS quality certification for imported craft materials affects market access for Asian suppliers serving specialty retailers. Maharashtra's Mumbai-Pune corridor anchors emerging hobby retail distribution networks.
United Kingdom
DIY crafters scaling consumption through direct digital channels bypass traditional wholesale markups. REACH registration requirements inherited post-Brexit restrict certain phthalate plasticizers in legacy product lines. London's craft retail infrastructure sustains above-average uptake through online specialty channels.
Embossing Powder Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biobased resin convergence and low-temperature formulation niches. The vendor base concentrates around integrated compounders with captive resin capabilities and specialist finish houses with direct-to-crafter distribution. Two strategic archetypes dominate: vertically integrated manufacturers controlling upstream polymer synthesis, and digital-native brands leveraging subscription curation. Competitive moves center on REACH-compliant pigment pre-positioning and seasonal color palette drops through owned channels.
Among North American specialists, Ranger Industries exemplifies the integrated compounder archetype through captive resin operations. WOW Embossing Powder anchors the direct-to-crafter digital channel position. Stampendous occupies the seasonal color specialization tier. These three represent distinct competitive vectors: backward integration, channel disintermediation, and calendar-driven product velocity.
| Leading Market Players |
|---|
| Ranger Industries |
| WOW Embossing Powder |
| Stampendous |
| Hero Arts |
| Tsukineko |
| Stewart Superior |
| Fine Glitter Powder |
| Percolour Polymer |
| Clearsnap |
| Others |
Supply & Pricing Matrix
Specialized color-matching technicians concentrated in Guangdong Province and Stuttgart anchor labor-cost differentials that widen pricing-tier spreads between archival-grade scrapbooking formulations and commodity card-making powders. REACH-driven reformulation timelines in Europe compress R&D efficiency premiums, while captive resin capabilities at integrated North American compounders insulate margin stability against titanium dioxide feedstock swings.
Pricing Analysis
Distributor markups in traditional wholesale channels absorb 35-50 point spreads before specialty retail pricing, compressing compounder margins unless direct-to-crafter digital routes bypass intermediaries entirely. Three-tier pricing structure across premium metallic, standard glossy, and economy matte levels differentiates by pigment loading and certification grade, with archival acid-free tiers commanding sustained premiums. Pricing pressure stems from titanium dioxide cost volatility forcing frequent recalibration in opaque white bases. Subscription-curated hobbyists exhibit lowest price sensitivity; small-scale manufacturers purchasing through wholesale distributors face highest elasticity.
Supply Chain Analysis
Thermoplastic resin feedstock rests on specialty polymer production clusters in China, South Korea, and Germany that supply North American and European compounders with limited geographic diversification. Titanium dioxide from mineral processors, mica additives from Indian and Brazilian extractors, and phthalate-free plasticizers from German specialty chemical houses constitute critical input dependencies. Single-source vulnerability concentrates around Guangdong Province thermoplastic synthesis, exposing formulators to logistics chokepoint risk. Distribution runs through direct-to-crafter digital platforms, hobby retail chains, and wholesale distributors serving institutional and commercial stationery producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hobbyist demand shifts toward archival-grade, acid-free, lignin-free specifications that sustain per-unit premiums and repeat purchase loyalty despite volume commoditization elsewhere.
For Market Incumbents: Deploy captive resin blending capabilities to secure margin stability against titanium dioxide feedstock volatility and Asian supply concentration. Accelerate REACH-compliant pigment substitution programs ahead of ECHA authorization deadlines to capture shelf space from legacy suppliers facing reformulation timeline compression. Channel control through direct-to-crafter digital platforms insulates pricing power from wholesale distributor margin extraction.
For New Entrants and Emerging Players: Launch via subscription box curation targeting United States coastal metropolitan markets where craft subscription penetration exceeds national averages and customer acquisition economics favor bundled assortments over individual SKU competition. Biobased resin convergence using polylactic acid thermoplastics unlocks compostable positioning in underserved sustainability-focused segments. Indian specialty retail penetration through BIS certification compliance accesses urban craft markets with expanding organized retail infrastructure.
For Investors and Strategic Acquirers: Valuations sit cheapest among compounders lacking captive resin synthesis capabilities and facing REACH-driven reformulation cost spikes without guaranteed raw material availability. Long-term viability favors vertically integrated manufacturers controlling upstream polymer production or digital-native brands with owned channel access and recurring subscription revenue. Watch for ECHA SVHC candidate list expansion triggering accelerated mica and synthetic pearl substitution programs as inflection indicator for metallic finish supplier restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Pigment Pre-Positioning | ECHA authorization deadlines compress legacy supplier timelines, creating shelf space capture opportunity for prepared compounders. |
| Direct-to-Crafter Digital Channel Buildout | Subscription box curation consolidates purchasing into predictable commitments, displacing individual SKU selection at brick-and-mortar retail. |
| Captive Resin Blending Capability Expansion | Specialty polymer production concentration in China creates margin vulnerability that backward integration insulates against commodity swings. |
| Biobased Resin Convergence R&D | Polylactic acid thermoplastic formulations unlock compostable embossing powder categories in sustainability-focused hobby segments. |
| Indian BIS Certification Compliance Investment | Urban craft market expansion through organized retail infrastructure in Maharashtra and Delhi-NCR rewards early certification positioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with embossing powder formulators, craft supply procurement managers at specialty retailers, hobby distributor channel heads, and polymer resin procurement leads at downstream compounders with secondary validation. Trade data from customs records, chemical industry association reports, and SEC filings from listed specialty chemical producers anchored supply-side sizing. Bottom-up volume modeling across product type, application, material, and distribution channel dimensions triangulated against top-down value estimates from retail audit data and subscription platform disclosures.
Historical reference periods spanning five years anchored the projection horizon, with growth trajectories calibrated to segment-specific demand drivers rather than aggregate macroeconomic assumptions. Segmentation modeling spanned product finish tier, end-use application intensity, base resin chemistry, and channel structure. CAGRs derived from elasticity-adjusted volume projections and pricing power assessments across metallic, glossy, matte, and clear formulations. Industry-specific inputs included REACH registration timeline impacts on European formulation costs and subscription box penetration rates in United States coastal metropolitan markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated digital printing substitution or ECHA SVHC list expansion beyond current pigment substitution planning horizons. Forecasts reflect documented assumptions regarding hobbyist engagement sustainability and resin feedstock cost trajectories. Regulatory deadline compression, titanium dioxide supply disruption, and biobased resin performance validation constitute specific revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Gelling Agent Market