
 Drug Formulation Market | 2026-2036
Drug Formulation Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Formulation Market Foresight
Lyophilized protein formulations is pivoting toward aqueous-based alternatives as manufacturers seek to reduce cold-chain dependency and cost per dose. Pfizer leverages its integrated biologics network to control fill-finish capacity for mRNA and monoclonal antibody products. Roche sustains leadership in oncology formulation through proprietary nanoparticle delivery platforms. AbbVie differentiates its immunology portfolio with subcutaneous auto-injector presentations that reduce hospital administration burden.
Drug formulation encompasses the scientific and engineering discipline of combining active pharmaceutical ingredients with excipients, stabilizers, and delivery vehicles to achieve specified bioavailability, shelf-life stability, and patient-administration profiles; processes span wet granulation, hot-melt extrusion, spray drying, and aseptic filling under validated environmental conditions. Injectable biologics commands the deepest margin pools as cold-chain complexity and sterility assurance requirements limit qualified manufacturing sites. Oral immediate-release formulations remain the highest-volume category but face pricing pressure from generic substitution. Extended-release delivery methods are gaining share in neurology and cardiovascular therapeutic areas where patient adherence directly determines clinical outcomes.
FDA enforces Current Good Manufacturing Practice regulations through facility inspections and process validation requirements that determine market access for all US-bound products. EMA's Medical Device Regulation and revised Annex 1 sterile manufacturing standards impose contamination-control upgrades across European production networks. WHO prequalification programs shape procurement eligibility for emerging-market supply contracts. Stakeholders must monitor regulatory divergence between FDA's emerging guidance on continuous manufacturing and EMA's batch-release traditions when siting new capacity investments.
Market Dynamics
Biologics manufacturing is pulling capital away from oral solid dose infrastructure toward single-use bioreactor systems, creating a bifurcation where fill-finish capacity for complex parenterals commands scarcity premiums while commodity oral generics face margin compression.
Growth Catalysts
- FDA Quality by Design:The initiative tightens process analytical technology requirements, forcing manufacturers to invest in real-time release testing capabilities that improve batch consistency and reduce regulatory review timelines.
- Subcutaneous auto-injector formats:Immunology and oncology therapeutic areas are driving demand for self-administration devices that shift administration burden from hospitals to patients.
- Cold-chain expansion:mRNA and cell therapy products require validated temperature-controlled distribution networks, creating pull-through demand for specialized packaging and logistics infrastructure.
Market Restraints
- Stainless steel equipment lock-in:Legacy facilities face stranded asset risk as single-use technologies displace traditional clean-in-place systems, requiring full production line replacement rather than incremental upgrades.
- EMA Annex 1 compliance costs:Revised sterile manufacturing standards mandate contamination-control upgrades across European production networks, compressing returns on existing capacity investments.
- Plastics and resin supply concentration:Single-use bioreactor film supply concentrates among specialized polymer converters, creating input cost volatility and qualification bottlenecks for new material sources.
Strategic Opportunities
- WHO prequalification pathways:Emerging market procurement eligibility hinges on WHO certification, creating first-mover advantage for manufacturers that validate formulations against international standards ahead of local competitors.
- Continuous manufacturing adoption:FDA emerging guidance on real-time release enables process intensification that reduces facility footprint and accelerates scale-up timelines for high-value biologics.
- Aqueous protein stabilization:Lyophilized formats face displacement from liquid-stable formulations that eliminate reconstitution steps and reduce cold-chain dependency for biosimilar distribution.
Industry Challenges
- Aseptic processing technician scarcity:Sterile fill-finish operations require specialized cleanroom behavior training that outpaces vocational pipeline output, constraining qualified manufacturing site expansion.
- Process validation timeline compression:Concurrent release paradigms demand statistical process control datasets that extend development timelines while accelerating commercial pressure.
- Legacy batch record system integration:Electronic batch record implementation faces friction from paper-based quality systems that resist digitization without extensive workflow reengineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Formulation Market |
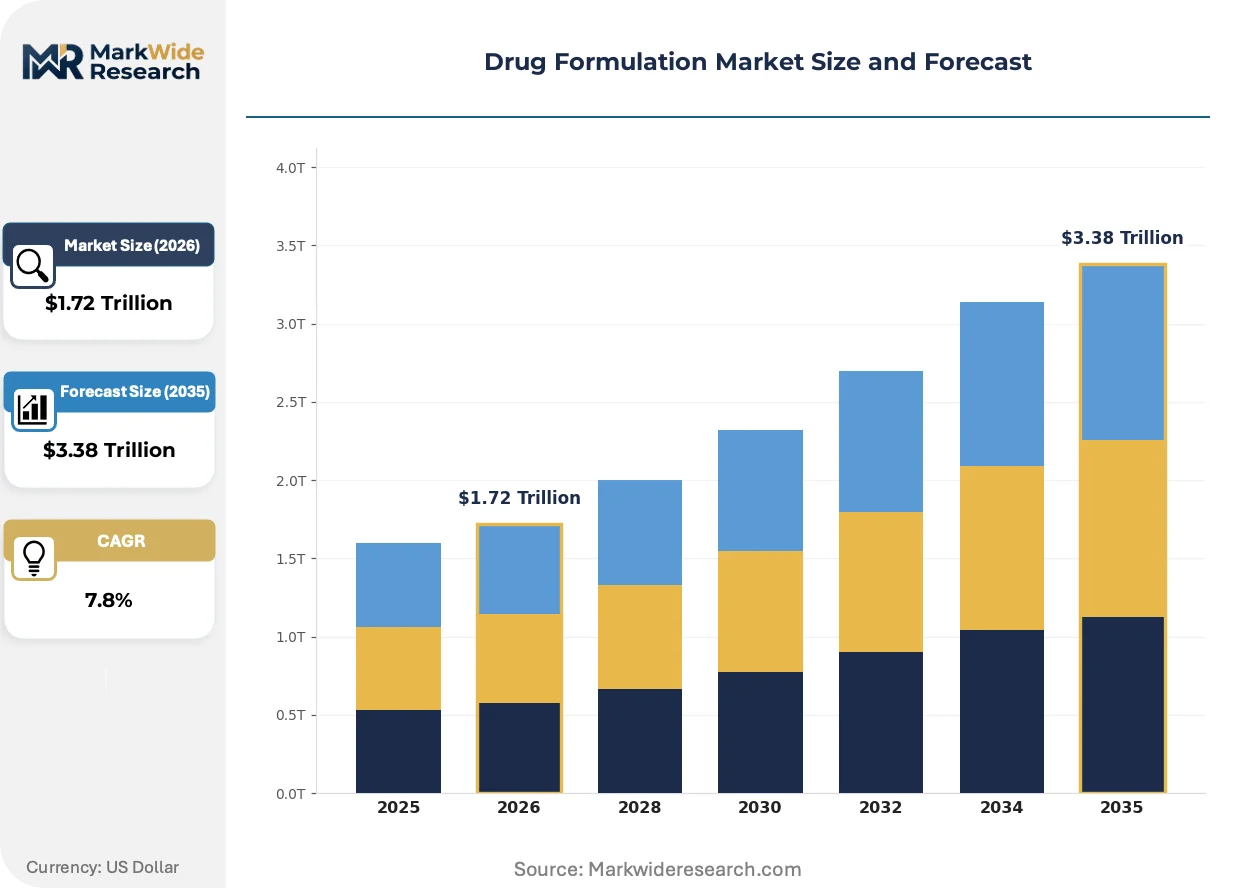
| Market Size in 2026 | $1.72 Trillion |
| Market Size in 2035 | $3.38 Trillion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
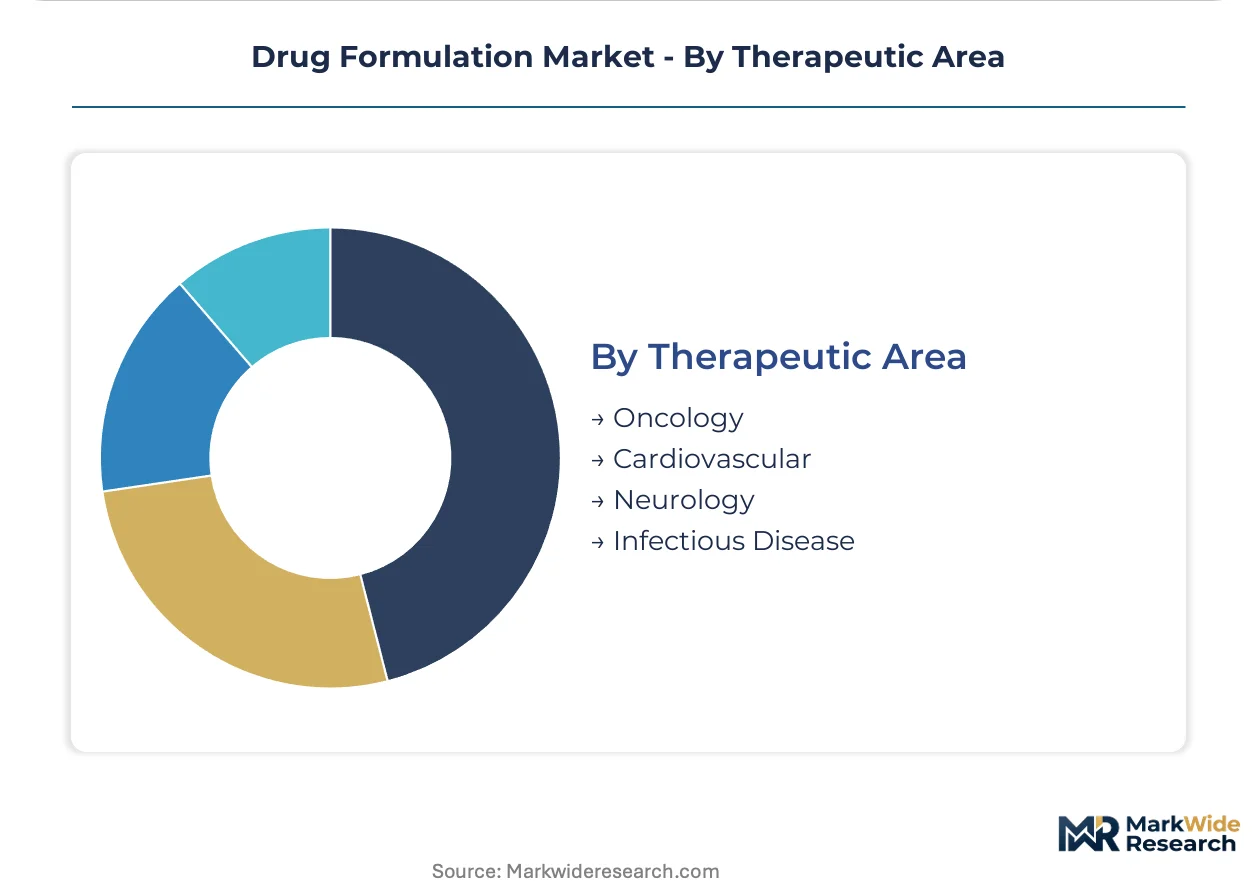
| Segmentation | Formulation Type: Oral, Injectable, Topical, Inhalable Active Ingredient: API, Biologics, Biosimilars, Small Molecules Delivery Method: Extended Release, Sustained Release, Immediate Release, Controlled Release Therapeutic Area: Oncology, Cardiovascular, Neurology, Infectious Disease |
| Companies Covered | Johnson & Johnson, Pfizer, Roche, Merck & Co., AbbVie, Novartis, Bristol-Myers Squibb, Sanofi, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Formulation Market Shifts & Advancements
Formulation science is pivoting toward patient-centric delivery formats that reduce administration burden while process technology shifts from batch to continuous paradigms that compress manufacturing timelines.
Continuous direct compression is decentralizing oral solid dose production from centralized high-volume facilities toward modular, right-sized units that co-locate with clinical supply chains. Regional hospital networks and specialized CDMOs are adopting these skid-mounted systems to reduce inventory carrying costs and accelerate stability-limited product release. The technology is decentralizing geographic production patterns, enabling distributed manufacturing that reduces cross-border shipment dependencies and customs delay exposure.
EMA's revised Annex 1 sterile manufacturing standards impose barrier technology mandates that upgrade isolator and restricted access barrier system requirements across European aseptic filling operations. Manufacturers must validate automated decontamination cycles and environmental monitoring systems that replace manual intervention protocols. Complex parenteral formulations including liposomal and nanoparticle suspensions face the steepest compliance burden, driving consolidation toward facilities with capital reserves for full cleanroom reconstruction.
Hospital procurement coalitions are consolidating purchasing authority for high-cost biologics, shifting negotiation leverage from individual institutions toward regional buying groups that extract volume-based price concessions. Specialty pharmacy distribution channels are displacing traditional wholesale relationships for self-administered injectables, capturing patient adherence data that informs formulary positioning. Germany and Japan exhibit the most advanced buyer concentration, where statutory pricing frameworks accelerate procurement centralization for reimbursed biologic therapies.
Drug Formulation Market Segmentation
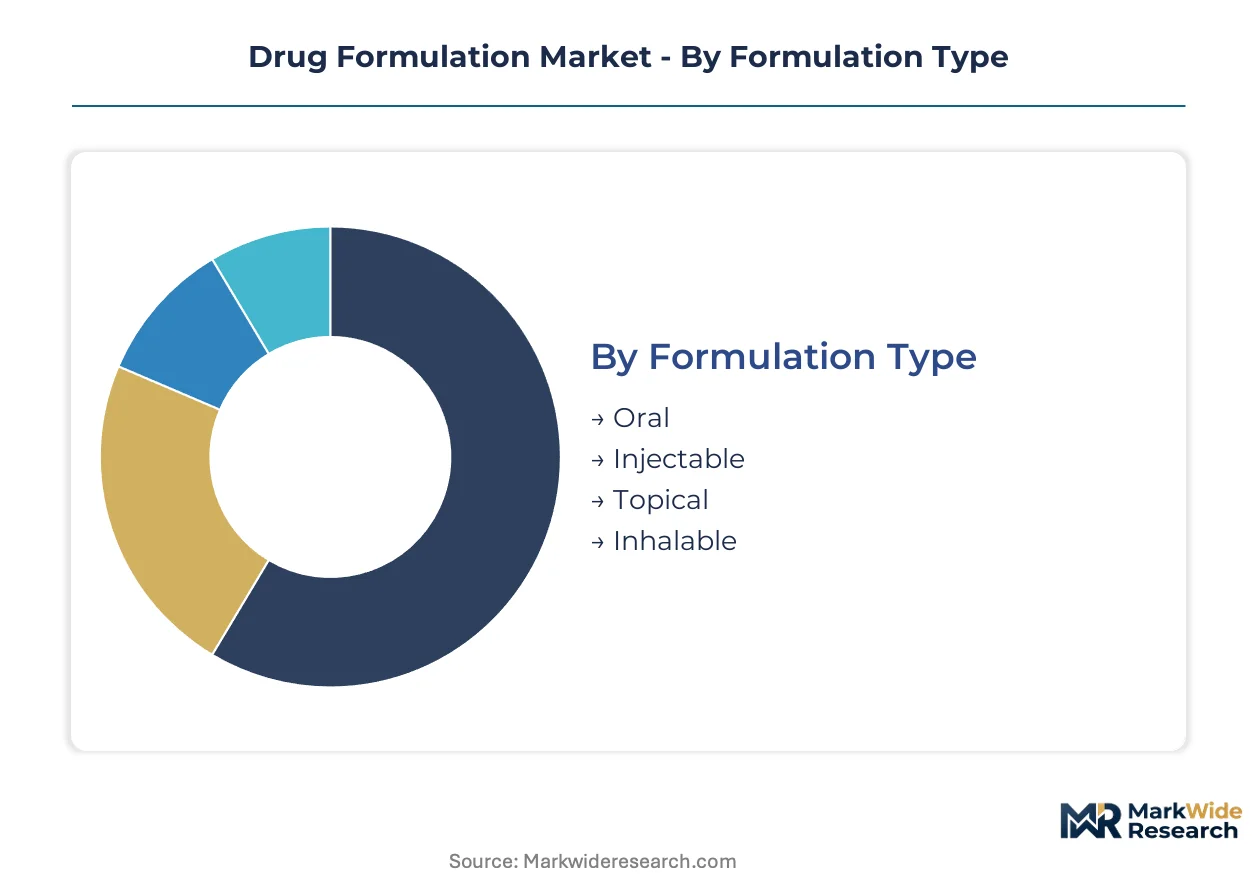
Drug formulation segmentation reveals divergent capital requirements across technology platforms, with biologics infrastructure commanding investment multiples that dwarf traditional small-molecule facilities. Manufacturers allocate capacity based on margin profiles, regulatory barriers, and patient-administration trends that reshape demand concentration across therapeutic categories.
Formulation Type:
Injectable formats demand the heaviest upfront capital outlays, driven by aseptic filling infrastructure, isolator technology, and cold-chain validation requirements that exclude marginal operators.
- Oral:Tablet and capsule manufacturing leverages mature high-speed compression and coating equipment with established process analytical technology integration. Demand concentrates in emerging markets where WHO prequalification pathways determine procurement eligibility for essential medicines.
- Injectable:Vial, syringe, and cartridge filling requires barrier isolator systems, automated visual inspection, and validated sterile processing environments that limit qualified manufacturing sites. United States and German markets absorb the deepest investment in fill-finish capacity for monoclonal antibodies and mRNA products.
- Topical:Cream, gel, and transdermal patch production utilizes semi-solid compounding and lamination equipment with lower regulatory entry barriers than parenteral formats.
- Inhalable:Dry powder and metered-dose inhaler manufacturing demands specialized particle engineering and device-assembly integration that concentrates among respiratory-focused CDMOs.
Injectable absorbs the bulk of installed capacity; Inhalable is expanding most quickly as device-integrated delivery gains traction in respiratory and systemic applications.
Active Ingredient:
Biologics manufacturing pulls capital away from chemical synthesis infrastructure toward single-use bioreactor systems and specialized downstream purification trains.
- API:Synthetic active pharmaceutical intermediate production spans batch and continuous chemical processing with established supplier networks across India and China.
- Biologics:Recombinant proteins, monoclonal antibodies, and cell therapies require mammalian or microbial expression systems, protein A chromatography, and viral clearance validation that stratifies manufacturing capabilities. Japanese and German facilities lead in biosimilar biologics capacity expansion.
- Biosimilars:Follow-on biologic formulations face abbreviated development pathways but require analytical biosimilarity packages and immunogenicity assessment that extend timelines versus small-molecule generics.
- Small Molecules:Traditional organic synthesis and crystallization processes dominate volume production with compressed margins in commoditized therapeutic categories.
Biologics commands the steepest capital allocation; Biosimilars is climbing the fastest as patent cliffs open reference product opportunities.
Delivery Method:
Extended-release technologies command premium pricing through formulation complexity that extends patent protection and improves clinical outcomes in chronic disease management.
- Extended Release:Matrix and reservoir systems modulate drug dissolution through polymer excipient engineering that requires specialized extrusion and coating equipment. Neurology and cardiovascular therapeutic areas in the United States drive demand for adherence-improving formulations.
- Sustained Release:Depot injections and implantable devices achieve multi-week plasma concentration profiles through biodegradable polymer matrices that concentrate manufacturing among parenteral specialists.
- Immediate Release:Conventional dissolution profiles dominate generic substitution markets with lowest formulation barriers and deepest price competition.
- Controlled Release:Osmotic pump and pulsatile systems enable zero-order kinetics and chronotherapeutic delivery that commands specialty pricing in narrow therapeutic index compounds.
Immediate Release holds the greatest volume share; Extended Release is gaining share fastest as payers prioritize adherence-linked outcomes.
Therapeutic Area:
Oncology formulations concentrate investment toward targeted delivery systems that minimize systemic toxicity while maximizing tumor penetration.
- Oncology:Liposomal, nanoparticle, and antibody-drug conjugate formulations require complex excipient engineering and aseptic processing that limits qualified suppliers. United States and Japanese markets absorb the majority of novel oncology formulation development.
- Cardiovascular:Extended-release antihypertensives and anticoagulants drive demand for adherence-optimized delivery as payers link reimbursement to reduced hospitalization rates.
- Neurology:CNS-penetrant formulations and long-acting injectable antipsychotics address adherence challenges in schizophrenia and bipolar disorder management.
- Infectious Disease:Antibiotic and antiviral formulations face pricing pressure from generic substitution while novel modalities like mRNA vaccines reshape manufacturing requirements.
Oncology captures the dominant R&D investment; Cardiovascular is expanding most quickly as population aging accelerates chronic disease burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where specialized CDMO capacity for complex parenterals remains constrained. FDA's Quality by Design initiative and EMA's revised Annex 1 guidelines are tightening process analytical technology requirements across these markets. Manufacturers allocate capacity based on margin profiles, regulatory barriers, and patient-administration trends that reshape demand concentration.
United States
Monoclonal antibody and mRNA fill-finish capacity absorbs the deepest investment as Pfizer and Bristol-Myers Squibb secure captive production networks. FDA enforces Current Good Manufacturing Practice regulations through facility inspections that determine market access. The Greater Boston and San Francisco Bay Area clusters concentrate biologics formulation development, with specialized CDMOs expanding isolator technology to meet sterility assurance requirements.
Germany
Biosimilar biologics capacity expansion leads European investment as statutory pricing frameworks accelerate procurement centralization. EMA's revised Annex 1 sterile manufacturing standards mandate contamination-control upgrades across production networks. The Rhine-Main and Bavarian industrial corridors host the densest concentration of barrier isolator installations, with facilities validating automated decontamination cycles to replace manual intervention protocols.
Japan
Oncology formulation development concentrates investment toward liposomal and nanoparticle delivery systems. PMDA guidelines align with international standards while maintaining batch-release traditions that influence siting decisions. The Kanto region around Tokyo anchors biologics manufacturing, with Osaka-based specialists expanding subcutaneous auto-injector assembly for immunology portfolios.
India
WHO prequalification pathways determine procurement eligibility for essential medicines across emerging markets. CDSCO regulates domestic manufacturing while export-oriented facilities pursue international certification ahead of local competitors. The Hyderabad and Ahmedabad clusters specialize in oral solid dose and injectable generics, with Maharashtra-based producers upgrading continuous direct compression capabilities.
Switzerland
Specialized parenteral formulation capacity commands scarcity premiums as complex excipient engineering requirements limit qualified suppliers. Swissmedic maintains alignment with EMA standards while offering streamlined pathways for innovative delivery technologies. The Basel region concentrates nanoparticle and antibody-drug conjugate development, with facilities investing in protein stabilization platforms that reduce cold-chain dependency.
Drug Formulation Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers redirect capital from oral solid dose infrastructure toward single-use bioreactor systems. The market stratifies between integrated pharmaceutical conglomerates with captive biologics networks and specialized CDMOs that monetize fill-finish scarcity. Three archetypes define competitive positioning: diversified innovators with proprietary delivery platforms, scale-driven generic formulators, and boutique parenteral specialists. M&A activity and strategic partnerships concentrate among biologics-focused assets, while technology licensing agreements proliferate for continuous manufacturing and aqueous protein stabilization.
Within the diversified innovator tier, Johnson & Johnson and Roche exemplify integrated control over formulation development and commercial production. Pfizer occupies a position representing network-scale biologics manufacturing, with AbbVie anchoring the subcutaneous delivery specialization segment. These entities sit within distinct competitive vectors: diversified innovators leverage proprietary platforms, while scale operators monetize capacity scarcity in qualified sterile processing environments.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer |
| Roche |
| Merck & Co. |
| AbbVie |
| Novartis |
| Bristol-Myers Squibb |
| Sanofi |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Single-use bioreactor adoption simultaneously compresses facility construction costs and concentrates qualified film supply among German and Japanese polymer converters. This technology shift stratifies pricing power between legacy stainless steel operators facing stranded asset risk and agile CDMOs monetizing fill-finish scarcity.
Pricing Analysis
Volume-margin bifurcation defines the market structure: immediate-release oral generics trade at commodity spot levels while complex parenterals command contract-based long-term offtake premiums. Pricing stratifies across premium, standard, and economy tiers based on sterility assurance certification and cold-chain validation depth. Price erosion runs through commodity oral segments as Indian and Chinese manufacturers expand WHO-prequalified capacity. Hospital procurement coalitions exhibit highest price sensitivity for reimbursed biologics, whereas oncology innovators face lowest sensitivity due to clinical outcome linkages.
Supply Chain Analysis
Cold-chain freight costs now represent a decisive factor in biologics distribution economics, reshaping siting decisions toward patient-proximate fill-finish locations. Active pharmaceutical ingredient supply concentrates in India and China, while specialized parenteral manufacturing clusters in the United States, Germany, and Switzerland. Single-use bioreactor film and resin inputs draw from concentrated polymer converter networks, creating single-source vulnerability for new material qualification. Distribution runs through specialty pharmacy channels for self-administered injectables and direct-to-hospital networks for infused biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA Annex 1 compliance costs and FDA Quality by Design mandates are forcing consolidation as marginal operators lack capital reserves for barrier technology upgrades.
For Market Incumbents: Lock in fill-finish capacity scarcity through captive network expansion in the Greater Boston and San Francisco Bay Area clusters. Prioritize isolator technology investment ahead of EMA's sterile manufacturing enforcement wave. Defensive backward integration into single-use bioreactor film supply reduces input cost volatility from German and Japanese polymer converters. For New Entrants and Emerging Players: Launch via continuous direct compression partnerships with regional hospital networks seeking inventory cost reduction. Target aqueous protein stabilization white space where lyophilized formats face displacement from liquid-stable alternatives. Penetrate through WHO prequalification pathways ahead of local competitors in emerging market procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in boutique parenteral specialists with validated nanoparticle and liposomal formulation capabilities. Long-term viability hinges on barrier isolator installation depth and biosimilar biologics pipeline positioning. Watch FDA emerging guidance on continuous manufacturing adoption as inflection signal for facility technology obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Isolator Installation | EMA Annex 1 compliance mandates automated decontamination cycles across European aseptic filling operations. |
| Continuous Manufacturing Adoption | FDA real-time release guidance enables process intensification that reduces facility footprint for high-value biologics. |
| Subcutaneous Auto-Injector Assembly | Osaka-based specialists expand device integration for immunology portfolios shifting administration to patients. |
| WHO Prequalification Pathway | Hyderabad and Ahmedabad clusters validate formulations to secure emerging market procurement eligibility ahead of rivals. |
| Aqueous Protein Stabilization Platform | Basel region facilities invest in liquid-stable formulations that eliminate reconstitution steps and reduce cold-chain dependency. |
Research Methodology
Multi-period observation of fill-finish capacity utilization rates and CDMO pricing trajectories anchored the trend analysis, supplemented by interviews with regulatory affairs leads, hospital procurement managers, and biologics manufacturing executives. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up facility capacity modeling and top-down therapeutic area demand projections were triangulated against disclosed capital expenditure patterns.
Segment-weighting across formulation type, active ingredient class, delivery method, and therapeutic area governed the analytical framework over the projection horizon. CAGRs were derived from installed capacity expansion schedules, patent expiration timelines, and regional regulatory cluster adoption curves. Forecast inputs incorporated sterility assurance technology upgrade cycles and single-use bioreactor film supply concentration metrics.
Regulatory guidance revision, raw material qualification bottlenecks, and procurement coalition pricing aggression are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Topical Applicators Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Embossing Powder Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Foundry Binders Market