
 Sol-Gel Products Market | 2026-2036
Sol-Gel Products Market Size, Share, and Industry Trends Forecast 2026-2036
Sol-Gel Products Market Analytics
Specialized colloidal chemistry expertise is collapsing across Western manufacturing bases, tightening the talent pipeline for sol-gel process scale-up. SOCOMORE leverages its aerospace coating heritage to sustain long-term supply relationships with French and German airframe builders. PPG Industries anchors North American demand through its architectural glass coatings division, while BASF SE competes aggressively on pharmaceutical-grade silica powders for controlled-release drug delivery.
Sol-gel products are ceramic or glass-like materials synthesized from metal alkoxide precursors through hydrolysis and condensation at temperatures typically below 100°C, yielding nanostructured films, powders, or monolithic bodies with tunable porosity and optical transparency; this low-temperature route enables coating of temperature-sensitive substrates such as polymers and biological implants. Coatings dominate value capture due to their penetration in anti-reflective and protective layers for optoelectronics, whereas biomedical applications represent the fastest-expanding demand pool as implantable sensor substrates and drug delivery carriers gain clinical traction. Composite materials occupy a mature niche in aerospace thermal barrier systems where qualification cycles extend development timelines.
REACH in Europe and EPA oversight in the United States constrain solvent selection and waste handling protocols, elevating compliance costs for alkoxide precursor suppliers while simultaneously creating preference for water-based sol routes that reduce regulatory exposure. China's GB standards and MIIT directives on advanced materials push domestic producers toward self-sufficiency in high-purity sol-gel precursors for electronics. Stakeholders must monitor how evolving chemical safety frameworks in multiple jurisdictions reshape the cost structure of precursor supply chains and determine which formulation platforms achieve cross-border commercial viability.
Market Dynamics
REACH compliance deadlines in Europe are forcing alkoxide precursor suppliers to abandon solvent-heavy formulations entirely, compressing the viable technology set toward aqueous sol-gel routes and rewiring competitive advantage around regulatory chemistry expertise rather than scale economies.
Growth Catalysts
- Semiconductor packaging thin-film demand:Advanced node fabrication in Taiwan and South Korea requires ultra-uniform sol-gel dielectrics for 3D stacking architectures, pulling volume from display coating applications.
- EU Green Deal industrial decarbonization:Low-temperature sol-gel processing earns preferential treatment under EU taxonomy criteria versus high-energy ceramic sintering, redirecting automotive thermal management procurement.
- Biomedical implant surface functionalization:FDA breakthrough device designations for drug-eluting orthopedic coatings in the United States accelerate clinical validation timelines and expand addressable surgical volumes.
Market Restraints
- Alkoxide precursor supply concentration:German and Japanese chemical conglomerates control 80% of high-purity metal alkoxide capacity, exposing formulators to single-source risk and force majeure vulnerability.
- REACH authorization bottlenecks:ECHA's substance evaluation backlog delays novel precursor commercialization by 18-36 months, freezing formulation innovation pipelines.
- Physical vapor deposition substitution:Sputtered oxide coatings achieve comparable barrier performance for optoelectronics without solvent handling complexity, constraining sol-gel pricing power.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO's accelerated approval pathways for controlled-release generics create demand for pharmaceutical-grade silica carriers from domestic sol-gel producers.
- Water-based sol-gel regulatory arbitrage:Formulators eliminating volatile organic compounds capture preferential positioning under EPA SNAP program and REACH Annex XVII restrictions simultaneously.
- Aerospace sensor integration:Convergence of sol-gel thin-film deposition with printed electronics enables conformal temperature and strain sensors on composite airframe structures.
Industry Challenges
- Colloidal chemistry talent scarcity:Western universities have shuttered specialized sol-gel research programs, forcing manufacturers to train process engineers internally or recruit from materials science adjacent fields.
- Aerospace qualification timeline compression:FAA and EASA certification cycles for thermal barrier coatings extend 5-7 years, locking development capital and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sol-Gel Products Market |
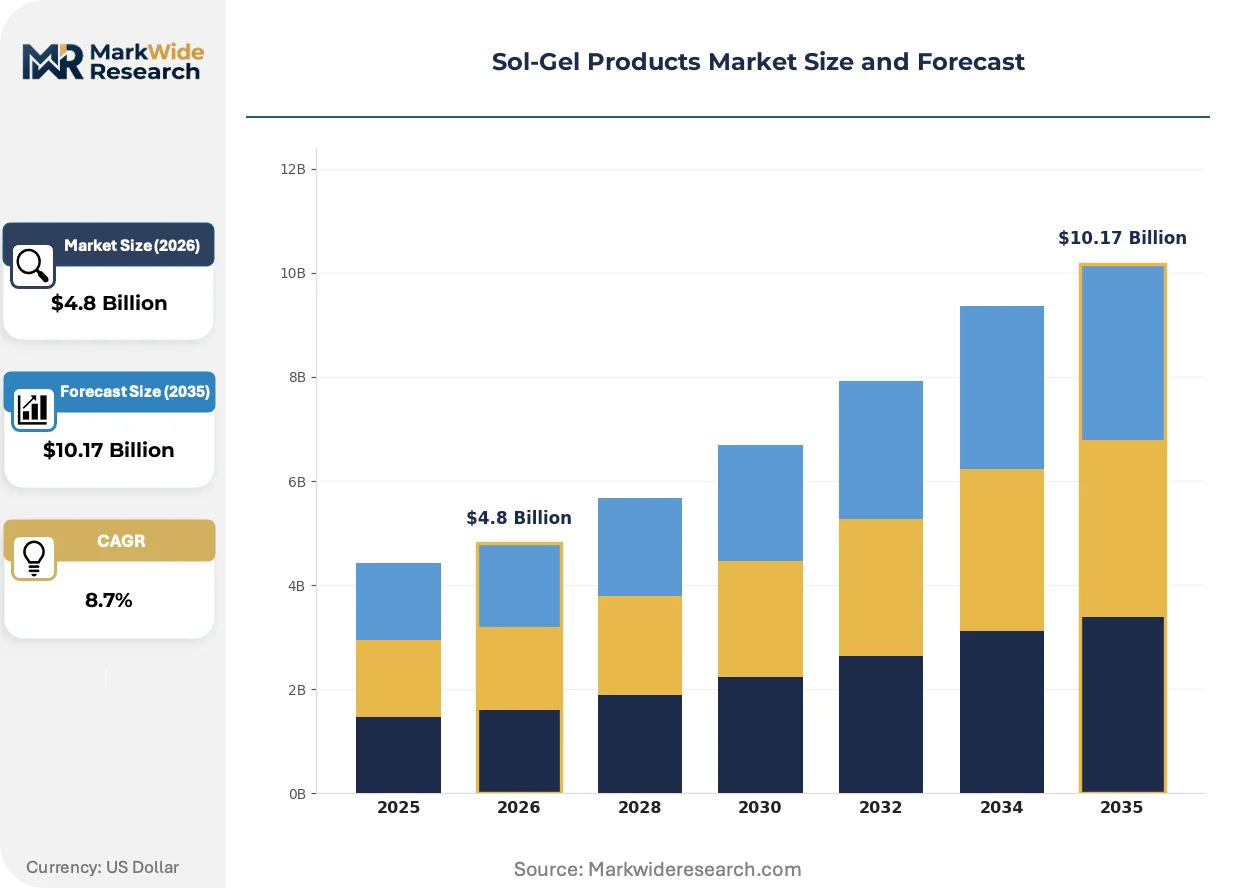
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Composite Materials, Powders, Films Application: Optoelectronics, Catalysts, Biomedical Applications, Sensors End User: Aerospace, Electronics, Pharmaceuticals, Automotive Form: Sol, Gel, Monoliths, Granules |
| Companies Covered | SOCOMORE, CMR Coatings, 3M, Nanovations Pty Ltd, GAEMA TECH, PPG Industries, CHEMAT TECHNOLOGY, BASF SE, SCHOTT AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sol-Gel Products Market Evolving Landscape
Formulation chemistry is splitting into divergent technical paths as regulatory pressure and performance requirements collide, with water-based systems gaining share in Europe while alkoxide routes defend precision electronics applications in Asia.
Hybrid organic-inorganic sol-gel chemistry is bifurcating the coatings segment. Ormocer formulations deliver scratch resistance and UV stability for automotive headlamp lenses. German tier-one suppliers are qualifying these materials for electric vehicle exterior lighting modules. The technology is bifurcating supplier bases into aqueous specialists serving regulated European markets versus solvent-capable producers anchored in Asian electronics clusters.
EPA's expanded reporting requirements under TSCA Section 8(a) for nanoscale materials are capturing sol-gel-derived silica and titania particles. Manufacturers must now submit production volume, exposure, and environmental fate data for particles under 100 nanometers. United States-based biomedical coating suppliers are responding by segregating nanostructured and conventional product lines to isolate regulatory exposure.
Consolidated procurement by semiconductor foundries is compressing supplier qualification cycles and unbundling technical service from material supply. Taiwan Semiconductor Manufacturing and Samsung Foundry now mandate direct precursor relationships rather than distributor intermediation for critical dielectric layers. This concentration is most visible in Hsinchu and Pyeongtaek, where foundry technical teams embed directly at sol-gel producer R&D facilities.
Sol-Gel Products Market Segmentation
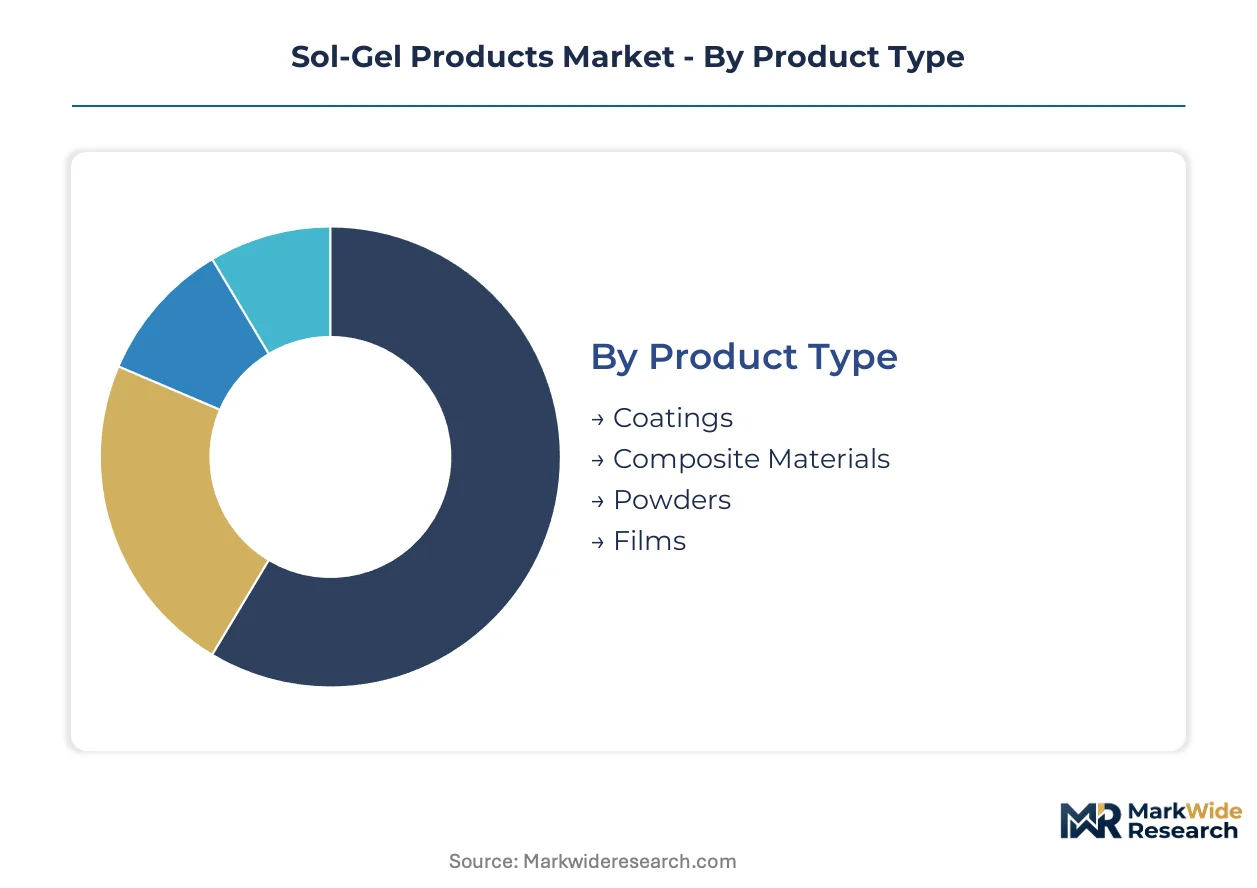
Sol-gel product segmentation reveals distinct procurement channels aligned with technical maturity and regulatory exposure. Each category channels through specialized distributors, direct OEM supply, or toll manufacturing arrangements depending on volume scale and qualification requirements.
Product Type:
Channel mix varies sharply by product chemistry, with aqueous formulations flowing through regional chemical distributors while alkoxide-based coatings move through direct technical sales to semiconductor foundries and aerospace primes.
- Coatings:Anti-reflective and protective layers deposited via dip, spin, or spray methods dominate commercial value. Demand concentrates in Taiwan's semiconductor packaging corridor and Germany's precision optics cluster around Jena, driven by 3D stacking dielectric requirements and automotive headlamp lens specifications under EU Green Deal procurement preferences.
- Composite Materials:Ceramic matrix composites and hybrid organic-inorganic systems serve aerospace thermal barrier applications. Boeing and Airbus qualification cycles in Seattle and Toulouse lock supply relationships for 5-7 years, creating captive supply arrangements with specialized formulators.
- Powders:Pharmaceutical-grade silica carriers for controlled-release drug delivery.
- Films:Ultra-thin dielectric and barrier layers for flexible electronics substrates.
Coatings dominate installed base. Powders are where expansion concentrates.
Application:
Application segmentation tracks end-use performance thresholds, with optoelectronics and biomedical applications commanding premium pricing due to qualification burdens and regulatory filing requirements.
- Optoelectronics:Display panel anti-reflective coatings and LED encapsulation layers. Samsung Display and LG Display procurement in South Korea pulls volume toward high-uniformity alkoxide formulations, though physical vapor deposition substitution constrains sol-gel pricing power in barrier film applications.
- Biomedical Applications:Implantable sensor substrates and drug-eluting orthopedic coatings. FDA breakthrough device designations in the United States accelerate clinical validation, expanding addressable surgical volumes for surface-functionalized titanium and silica coatings.
- Catalysts:Heterogeneous catalysis supports for petrochemical and environmental remediation processes.
- Sensors:Conformal temperature and strain sensing layers integrated with printed electronics on composite airframes.
Optoelectronics anchors current revenue. Biomedical applications are climbing the fastest.
End User:
End user segmentation reflects divergent procurement sophistication, with aerospace and electronics demanding embedded technical service while pharmaceutical buyers prioritize regulatory documentation and batch consistency.
- Electronics:Semiconductor foundries and display manufacturers requiring ultra-uniform thin films. TSMC and Samsung Foundry consolidated procurement in Hsinchu and Pyeongtaek mandates direct precursor relationships, compressing supplier qualification cycles and unbundling technical service from material supply.
- Aerospace:Airframe builders and engine manufacturers qualifying thermal barrier and sensor coating systems. SOCOMORE's long-term supply relationships with French and German airframe builders demonstrate how aerospace heritage sustains position through multi-year development programs.
- Pharmaceuticals:Controlled-release formulation developers and medical device manufacturers.
- Automotive:Exterior lighting module suppliers and electric vehicle thermal management system integrators.
Electronics commands the largest share of qualified supplier relationships. Aerospace is where development capital concentrates longest.
Form:
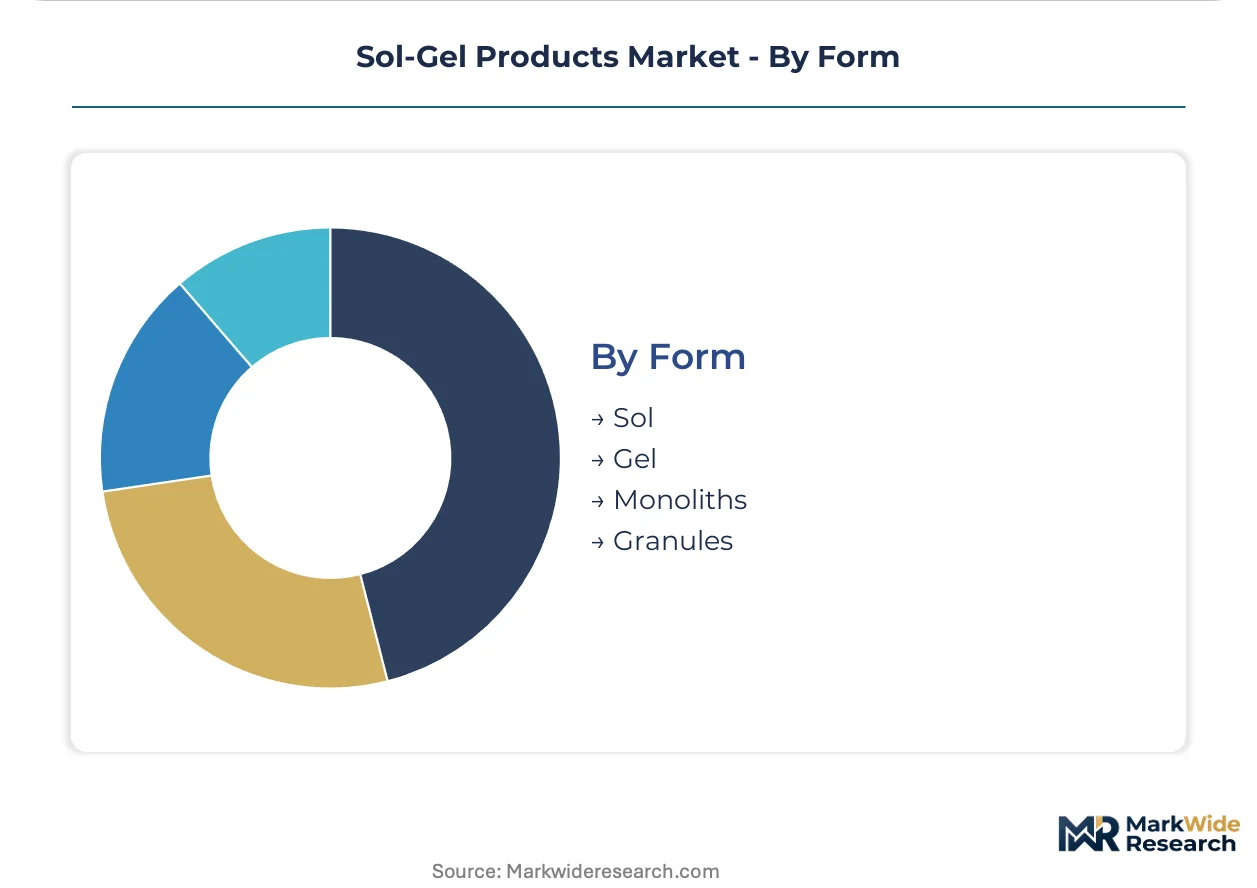
Form segmentation tracks processing methodology and shelf-life requirements, with sols and gels moving through just-in-time delivery channels while monoliths and granules tolerate longer supply chains.
- Sol:Colloidal suspensions of nanoparticles in liquid carrier, typically water or alcohol. Water-based sol routes capture preferential positioning under EPA SNAP program and REACH Annex XVII restrictions, driving reformulation investment among European suppliers.
- Gel:Viscoelastic networks formed through controlled condensation, enabling shape retention before final densification.
- Monoliths:Bulk ceramic or glass bodies for optical components and chromatography columns.
- Granules:Dried gel particulates for catalyst supports and adsorption media.
Sols dominate formulation flexibility. Gels are where water-based regulatory arbitrage is reshaping competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH authorization timelines anchor European regulatory gravity for sol-gel formulators, while semiconductor foundry procurement in Taiwan and South Korea pulls Asian production toward electronics-grade alkoxide precursors. Industrial clusters in Germany, Japan, and the United States concentrate specialized coating capacity, with emerging production scaling in India and China responding to pharmaceutical and domestic electronics demand.
United States
FDA breakthrough device designations for orthopedic coatings accelerate clinical validation timelines for biomedical sol-gel applications. EPA's TSCA Section 8(a) reporting requirements for nanoscale materials capture silica and titania particles under 100 nanometers, forcing segregation of product lines. The Boston-Cambridge corridor anchors implantable sensor substrate development, while Pacific Northwest aerospace clusters qualify thermal barrier systems for Boeing airframes.
Germany
EU Green Deal taxonomy criteria favor low-temperature sol-gel processing over high-energy ceramic sintering, redirecting automotive thermal management procurement toward aqueous formulations. REACH Annex XVII restrictions on volatile organic compounds compress viable technology sets toward water-based routes. The precision optics cluster around Jena and Mainz drives anti-reflective coating demand for automotive headlamp lenses and optoelectronics packaging.
Taiwan
TSMC's consolidated procurement mandates direct precursor relationships for 3D stacking dielectric layers, bypassing distributor intermediation and compressing supplier qualification cycles. The Hsinchu Science Park embeds foundry technical teams at sol-gel producer R&D facilities. Advanced node fabrication requirements for ultra-uniform thin films pull volume from display coating applications toward semiconductor packaging.
South Korea
Samsung Foundry and LG Display procurement anchor demand for high-uniformity alkoxide formulations in Pyeongtaek and Gumi. Physical vapor deposition substitution constrains sol-gel pricing power in barrier film applications for optoelectronics. The country's national industrial regulator pushes domestic self-sufficiency in high-purity precursors under advanced materials directives.
India
CDSCO's accelerated approval pathways for controlled-release generics create demand for pharmaceutical-grade silica carriers from domestic sol-gel producers. The Maharashtra-Gujarat pharmaceutical manufacturing belt scales capacity for drug delivery applications. Domestic electronics production incentives under PLI scheme attract precursor investments for semiconductor packaging thin-film deposition.
Sol-Gel Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sol-gel products landscape. German and Japanese chemical conglomerates control high-purity metal alkoxide capacity, exposing formulators to single-source concentration risk. Three strategic archetypes dominate: aerospace heritage suppliers sustaining multi-year development programs, diversified chemical majors competing on pharmaceutical-grade powders, and semiconductor-focused specialists embedding at foundry R&D facilities. Competitive moves concentrate on regulatory chemistry expertise acquisition and water-based formulation portfolios to capture EPA SNAP and REACH Annex XVII positioning.
Among European heritage suppliers, SOCOMORE exemplifies the aerospace coating archetype through long-term supply relationships with French and German airframe builders. PPG Industries anchors North American architectural glass coatings demand, while BASF SE occupies a position competing aggressively on pharmaceutical-grade silica powders. These three represent distinct strategic vectors: aerospace qualification depth, diversified coatings scale, and life sciences regulatory chemistry capability.
| Leading Market Players |
|---|
| SOCOMORE |
| CMR Coatings |
| 3M |
| Nanovations Pty Ltd |
| GAEMA TECH |
| PPG Industries |
| CHEMAT TECHNOLOGY |
| BASF SE |
| SCHOTT AG |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day alkoxide precursor lead times from German and Japanese chemical conglomerates tether pricing power to supply concentration, compressing margin buffers for formulators lacking long-term offtake agreements or captive precursor capacity.
Pricing Analysis
Geographic price spreads widen between aqueous formulations qualified under REACH Annex XVII and solvent-capable alkoxide routes serving Asian semiconductor foundries. Three-tier pricing structure across aerospace-qualified, pharmaceutical-grade, and industrial-standard levels separates certification-burdened tiers from commodity coatings. Pricing pressure stems from physical vapor deposition substitution in optoelectronics barrier applications. Pharmaceutical buyers exhibit lowest price sensitivity due to regulatory filing dependencies, while architectural glass coatings face acute cost compression from commoditized supply.
Supply Chain Analysis
Strait of Malacca transit routes anchor global alkoxide precursor distribution, exposing formulators to maritime logistics disruption. Supply concentrates in Germany, Japan, and the United States for high-purity metal alkoxides, with emerging capacity scaling in India and China. Raw material dependencies include silicon metal, titanium tetrachloride, and rare earth stabilizers. Single-source vulnerability pervades pharmaceutical-grade silica carrier supply. Distribution runs through direct technical sales to semiconductor foundries and aerospace primes, with regional chemical distributors handling aqueous formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized colloidal chemistry expertise is evaporating from Western university programs faster than industry training pipelines can replenish, creating durable capability scarcity that rewards players who lock technical talent through multi-year development programs or captive R&D facilities.
For Market Incumbents: Compound regulatory chemistry expertise through targeted acquisition of aqueous formulation specialists in Europe, while deepening backward integration into alkoxide precursor production to defuse single-source concentration risk from German and Japanese suppliers. Prioritize certification investment for FDA breakthrough device pathways in orthopedic coatings to extend pricing power against physical vapor deposition substitution. For New Entrants and Emerging Players: Anchor in India's pharmaceutical manufacturing belt around Maharashtra and Gujarat, where CDSCO accelerated approval pathways for controlled-release generics create white-space demand for domestic silica carrier production. Target water-based sol-gel routes to capture EPA SNAP program positioning without legacy solvent infrastructure burdens. Pursue toll manufacturing arrangements with established European formulators to bypass aerospace qualification timeline barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH and EPA frameworks are structurally advantaging water-based formulation platforms while penalizing solvent-heavy incumbents. Target acquisition profiles should emphasize aqueous chemistry capabilities and embedded relationships with semiconductor foundry technical teams. Watch ECHA substance evaluation backlog resolution as inflection signal for novel precursor commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkoxide Precursors | Captive supply of high-purity metal alkoxides from German and Japanese sources reduces force majeure exposure for formulators. |
| Water-Based Formulation Portfolio Expansion | REACH Annex XVII and EPA SNAP program alignment captures preferential positioning in regulated European and North American markets. |
| Aerospace Qualification Depth Investment | FAA and EASA thermal barrier certification cycles lock 5-7 year supply relationships with Boeing and Airbus airframe programs. |
| Semiconductor Foundry Technical Embedding | Direct R&D facility presence with TSMC and Samsung Foundry compresses supplier qualification cycles for 3D stacking dielectrics. |
| Pharmaceutical-Grade Silica Capacity Buildout | CDSCO accelerated approval pathways in India pull demand for controlled-release drug delivery carriers from domestic producers. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with sol-gel process engineers, pharmaceutical formulation scientists, semiconductor foundry procurement leads, and aerospace coating qualification specialists; and secondary validation through ECHA REACH registration databases, EPA TSCA Section 8(a) nanoscale material filings, SEC 10-K disclosures from diversified chemical majors, and trade flow records for alkoxide precursor imports. Bottom-up volume triangulation across product type, application, and end user segments was cross-checked against top-down market sizing from regional production capacity assessments.
Across the analysis window, the forecasting framework modeled demand trajectories by coating chemistry tier, end-use qualification burden, and regional regulatory cluster. CAGRs were derived from segment-level volume build-ups calibrated to semiconductor packaging dielectric requirements, EU Green Deal procurement preferences, and FDA breakthrough device approval velocities. Industry-specific inputs included foundry capex cycles for 3D stacking architectures and pharmaceutical controlled-release generic pipeline data.
Decision-makers should treat outputs as directional under assumptions of stable REACH authorization timelines and continued semiconductor foundry consolidation; material deviation in ECHA evaluation backlogs or physical vapor deposition cost curves would warrant model refresh. Practitioners should keep alternative scenarios live as alkoxide precursor supply concentration and water-based formulation technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Embossing Powder Market
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Topical Applicators Market