
 Topical Applicators Market | 2026-2036
Topical Applicators Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Applicators Market Analytics
The topical applicators market is rebalancing between premium precision-dosing systems and commodity squeeze-tube formats as reimbursement and regulatory scrutiny diverge. Johnson & Johnson leverages its dermatology franchise to sustain channel control across retail pharmacy networks. Galderma anchors the professional segment with specialized applicators calibrated for prescription topical therapies. Bayer AG competes across pain relief applicators through extended distribution into mass-market retail.
Topical applicators are mechanical or electromechanical devices engineered to meter, spread, or deposit semisolid or liquid formulations onto skin or mucosal surfaces with controlled dosage precision, typically incorporating polymer nozzles, piston pumps, or roller-ball mechanisms with dispensing tolerances measured in milligrams per actuation. Their primary commercial purpose is to ensure therapeutic efficacy, minimize waste, and reduce contamination risk in both clinical and consumer settings. The delivery mode dimension shows pump dispensers capturing margin pools in prescription dermatology where dose reproducibility commands premium positioning, while tube formats dominate volume in over-the-counter pain relief and cosmetic segments where manufacturing scale drives unit economics. Spray and roll-on applicators occupy faster-growing niches in veterinary and cosmetic end uses respectively.
FDA 21 CFR Part 3 combination product regulations and EU MDR classification rules for drug-device integrals shape design validation requirements and premarket submission pathways for manufacturers. ISO 13485 quality management standards and REACH substance restrictions further govern material selection and biocompatibility testing protocols for polymer components in direct skin contact. Stakeholders must monitor evolving regulator convergence between pharmaceutical and medical device frameworks to anticipate compliance cost shifts and competitive repositioning.
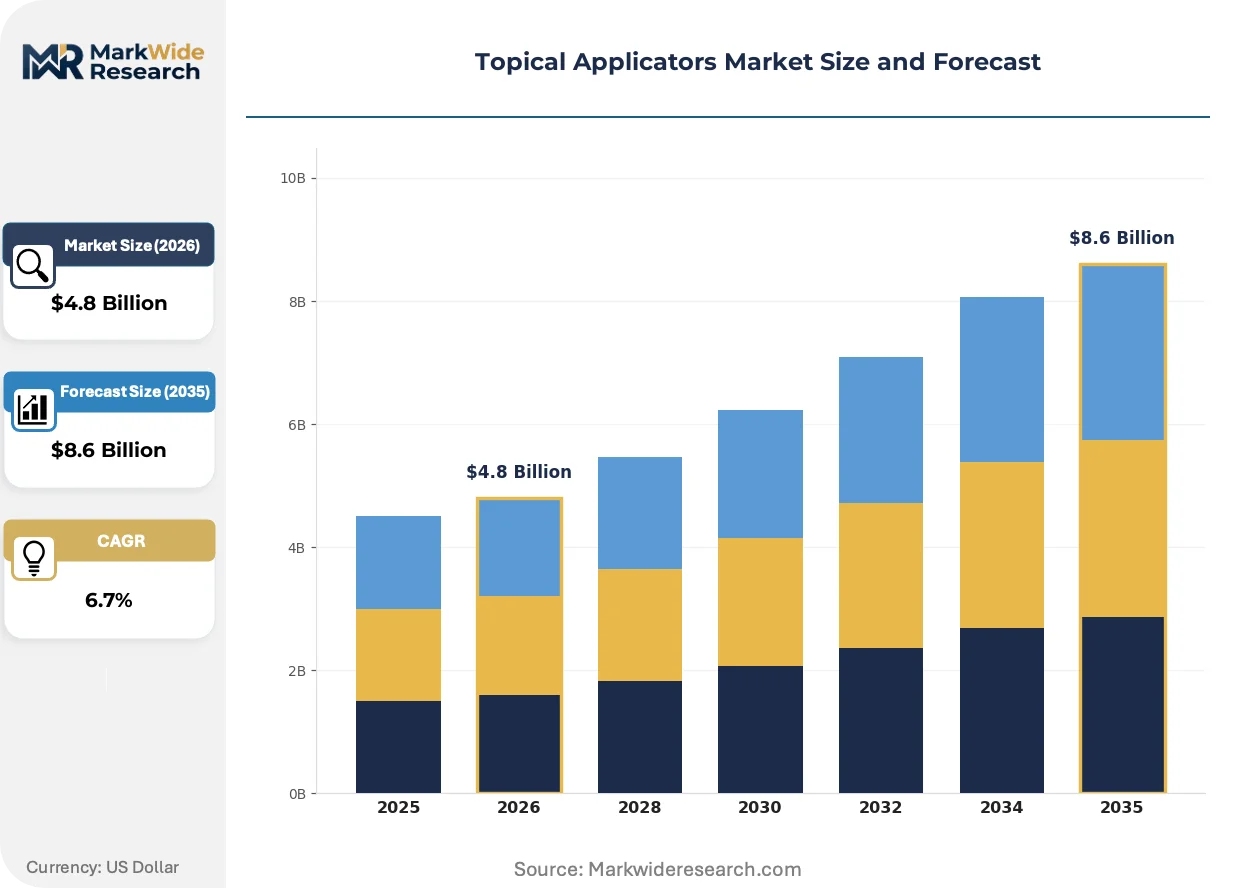
Market Dynamics
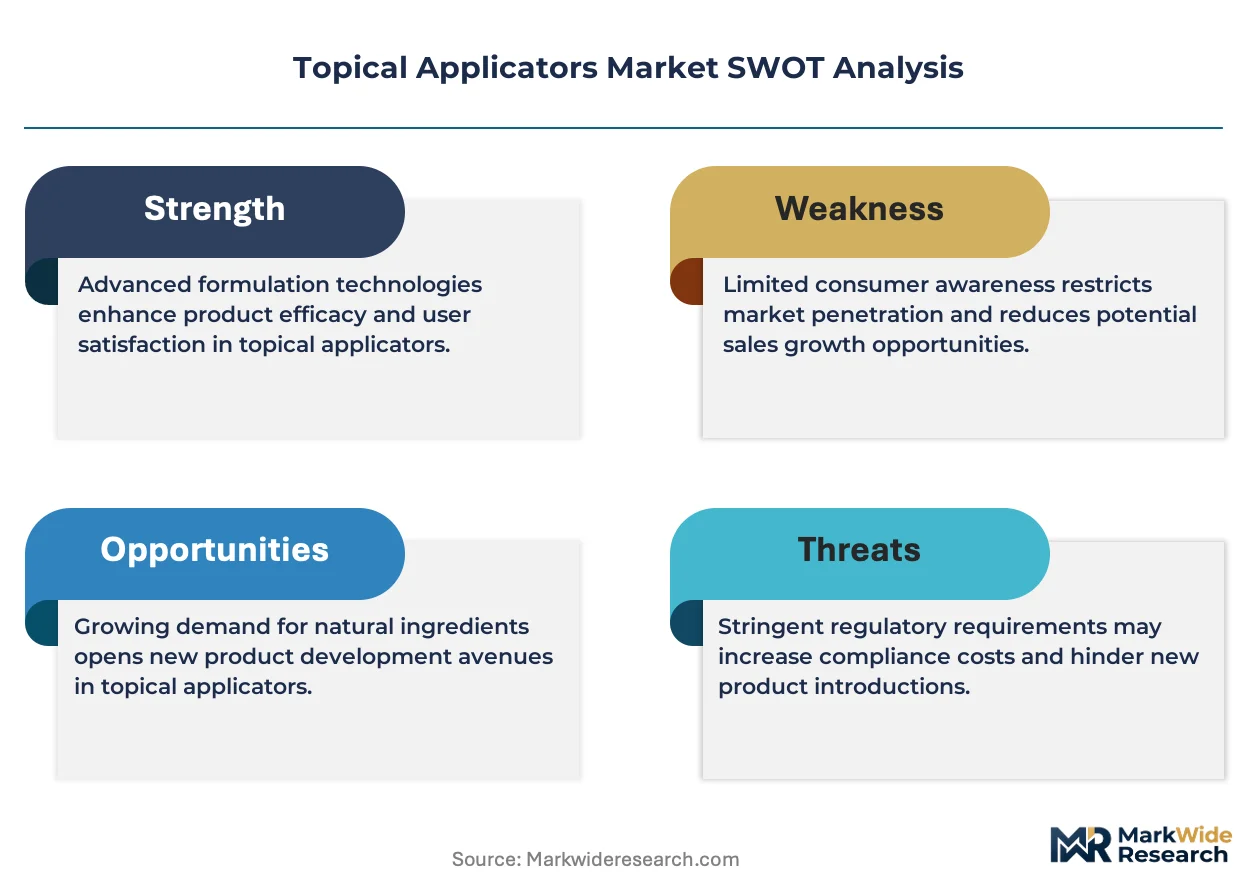
Precision dosing requirements under FDA combination product rules and EU MDR classification for drug-device integrals are forcing manufacturers to revalidate entire design control systems, compressing margins for commodity formats while expanding premium positioning for calibrated dispensing systems.
Growth Catalysts
- EU MDR Classification Rigor:Stricter device-drug boundary definitions in Brussels are accelerating demand for purpose-built applicators with documented biocompatibility testing, favoring suppliers with established quality management systems.
- Polymer Nozzle Microfabrication:Advances in injection molding tolerances now enable sub-milligram dosing reproducibility, opening prescription dermatology to pump formats previously limited to clinical settings.
- Dermatology Clinic Expansion:Outpatient procedural volume in the United States is concentrating purchasing power among clinic chains seeking standardized applicator fleets with traceable lot records.
Market Restraints
- Medical-Grade Polymer Cost Volatility:Cyclo-olefin polymer and thermoplastic elastomer feedstock prices swing with crude oil derivatives, squeezing gross margins on single-use disposable designs.
- Piston Pump Supply Concentration:Precision pump mechanism production clusters in southern Germany and northern Italy, creating geographic vulnerability for manufacturers dependent on just-in-time component flows.
- REACH Substance Restrictions:ECHA candidate list expansions for skin-contact polymers force reformulation cycles that delay product launches by 12-18 months.
Strategic Opportunities
- Veterinary Dermatology:Companion animal topical therapy protocols in the United States are adopting human-clinical precision standards, creating unmet demand for species-calibrated dosing applicators.
- Cosmetic Roll-On Convergence:Hybrid cosmetic-therapeutic positioning is opening pharmacy shelf space for applicators with dual cosmetic and mild dermatological claims.
- ISO 13485 Certification Arbitrage:Smaller manufacturers in India and South Korea are acquiring quality certifications to supply private-label precision applicators to European pharmaceutical firms seeking second-source validation.
Industry Challenges
- Combination Product Submission Expertise:FDA 21 CFR Part 3 premarket pathway navigation requires hybrid pharmaceutical-device regulatory talent that commands premium compensation and extended recruitment timelines.
- Legacy Tube Format Retooling:Converting commodity squeeze-tube production lines to pump or metered-dose formats demands capital equipment outlays that strain mid-tier contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Applicators Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Lotions, Ointments Application: Dermatological, Pain Relief, Cosmetic, Veterinary End User: Patients, Healthcare Professionals, Retail Customers, Veterinarians Delivery Mode: Pump Dispenser, Tube, Spray, Roll-on |
| Companies Covered | Reflex Medical, Doselogix, Tickerworks, Lucas Packaging, Simcro Ltd., Johnson & Johnson, Galderma, Bayer AG, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Applicators Market Evolving Landscape
Electromechanical dosing miniaturization and regulatory convergence between pharmaceutical and device frameworks are compressing development cycles while fragmenting competitive positioning between precision specialists and volume commodity suppliers.
Micro-pump actuation technology with piezoelectric or solenoid-driven piston mechanisms is decentralizing manufacturing scale requirements for milligram-accurate topical delivery. Mid-sized contract manufacturers in South Korea and Taiwan are adopting these platforms to serve regional pharmaceutical firms previously dependent on European OEM supply. The technology is decentralizing concentration of precision dosing capability away from incumbent dermatology device clusters.
EU MDR Annex XVI expansion to include substance-based medical devices is reclassifying numerous cosmetic-applicator formats as regulated devices, triggering conformity assessment obligations for manufacturers previously operating under cosmetic directive frameworks. German notified bodies are experiencing 14-month backlog queues for technical file reviews. Cosmetic brands with therapeutic positioning are most affected, accelerating partnerships with established medical device quality systems.
Clinic procurement departments are consolidating supplier relationships into single-source framework agreements with dose-traceability requirements, displacing fragmented spot purchasing of commodity formats. United States dermatology clinic chains are leading this consolidation, bundling applicator supply with pharmaceutical purchasing contracts. The shift is most visible in metropolitan markets with high clinic chain penetration.
Topical Applicators Market Segmentation
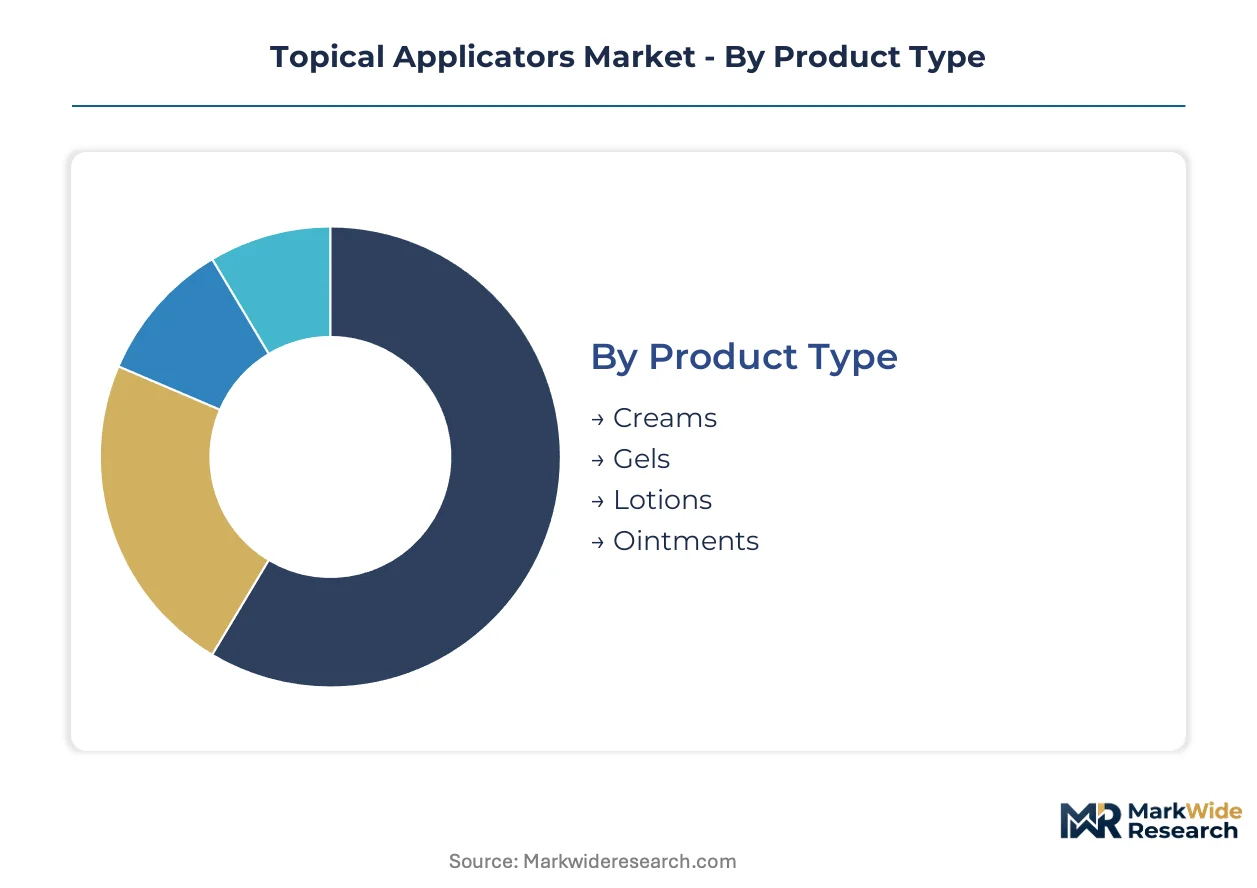
Segmentation in topical applicators reveals how regulatory pressure and dosing precision fragment manufacturing scale. Suppliers must choose between commodity tube volumes and calibrated pump margins, with each segment demanding distinct quality systems and channel relationships.
Product Type:
Supply concentration clusters around polymer formulation compatibility and fill-line sterilization requirements, with contract manufacturers specializing in specific rheological classes.
- Creams:Oil-in-water emulsions with intermediate viscosity require piston-pump compatibility and shear-stable thickeners. Demand concentrates in United States dermatology clinics where Medicaid reimbursement favors generic topical corticosteroids in metered formats.
- Gels:Hydrogel and organogel bases with thixotropic flow properties enable precise volumetric dosing through narrow-gauge nozzles. German pharmaceutical firms are expanding gel-applicator combination submissions under EU MDR accelerated pathways.
- Lotions:Low-viscosity fluid systems with pourable rheology dominate pediatric and cosmetic segments where spreadability overrides dosing precision.
- Ointments:Oleaginous bases with occlusive properties require heated fill processes and specialized tube sealing; compounding pharmacies in India drive spot demand.
Creams absorb the bulk of installed capacity; gels are expanding most quickly.
Application:
Cost tier stratification separates clinical-grade precision systems from consumer commodity formats, with reimbursement status determining applicator specification.
- Dermatological:Prescription topical therapies for psoriasis, eczema, and acne demand calibrated dosing with documented lot traceability. United States clinic chains are standardizing on pump dispensers with ISO 13485-certified manufacturing records.
- Pain Relief:Over-the-counter NSAID and counterirritant formulations prioritize manufacturing scale and shelf-ready packaging. Mass-market retail in Germany and France drives squeeze-tube volume.
- Cosmetic:Anti-aging and sun care applications occupy a regulatory gray zone where EU MDR Annex XVI reclassification is forcing conformity upgrades.
- Veterinary:Companion animal dermatology protocols in the United States are adopting human-clinical precision standards for otic and dermal formulations.
Dermatological applications command the highest unit margins; veterinary use is gaining share fastest.
End User:
Customer type determines procurement channel and quality documentation burden, with institutional buyers imposing framework agreements that commodity suppliers cannot satisfy.
- Healthcare Professionals:Dermatologists and clinic administrators require dose-traceable applicator fleets with supplier quality audits. Procurement consolidation in United States metropolitan markets favors single-source contracts.
- Patients:Self-administered prescription therapies drive demand for intuitive pump mechanisms with tactile dose confirmation.
- Retail Customers:Cosmetic and pain relief segments prioritize shelf aesthetics and price elasticity over dosing precision.
- Veterinarians:Specialist practices seek species-calibrated applicators with modified nozzle geometries for feline and canine anatomy.
Healthcare professionals absorb the bulk of precision-applicator procurement; veterinarians represent the steepest expansion trajectory.
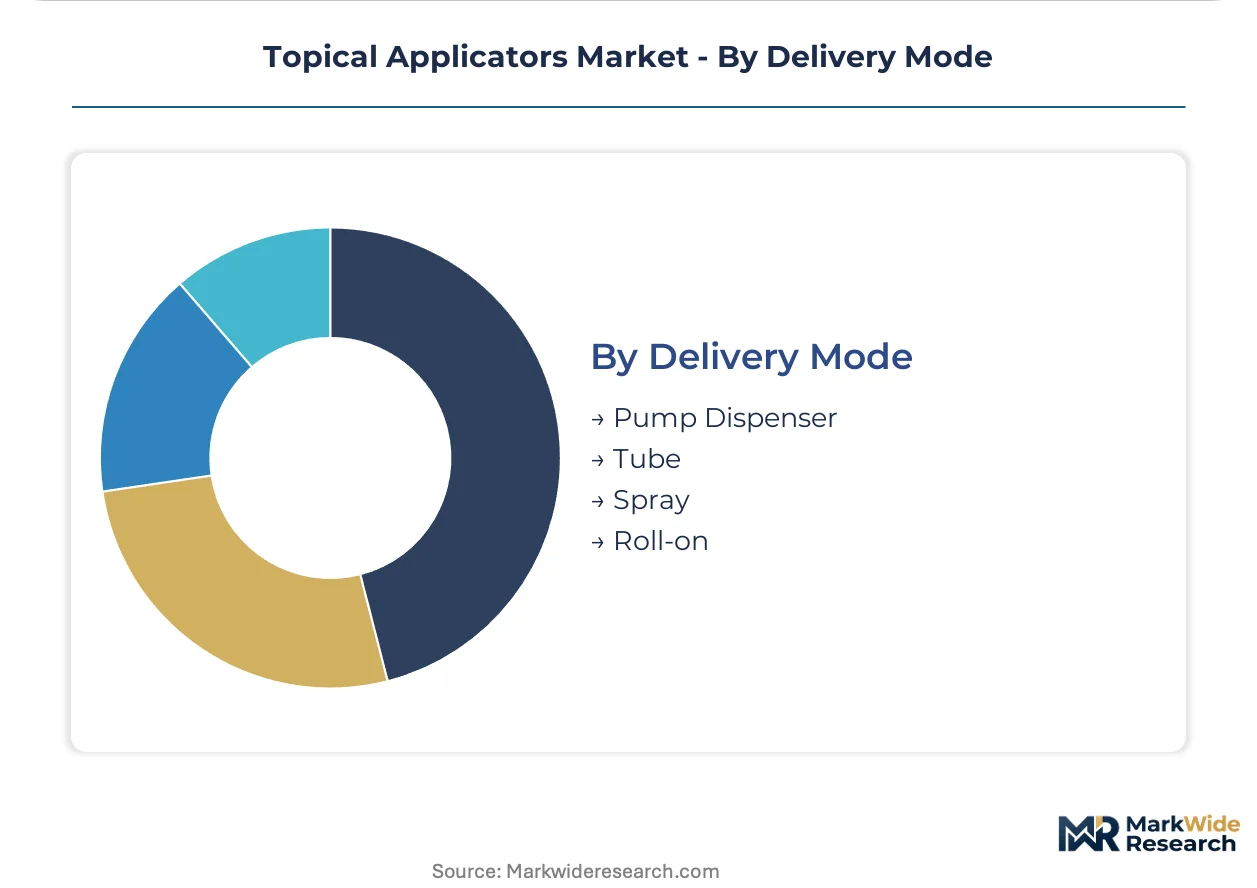
Delivery Mode:
Volume scale and margin structure diverge sharply across mechanism types, with electromechanical miniaturization disrupting traditional geographic supply patterns.
- Pump Dispenser:Piston or bellows mechanisms with milligram-accurate actuation and prime-recovery features. Production clusters in South Korea and Taiwan are challenging German and Italian incumbent suppliers.
- Tube:Laminated or extruded plastic squeeze formats with crimp or flip-cap closure dominate commodity segments where fill-speed economics override dosing precision.
- Spray:Aerosol or mechanical pump atomization for large-surface applications in veterinary and sun care segments.
- Roll-on:Ball-bearing applicators with reservoir-fed wick systems bridge cosmetic and mild therapeutic positioning in pharmacy channels.
Tubes absorb the bulk of unit volume; pump dispensers are climbing the fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European precision pump manufacturing for topical applicators, with German component suppliers feeding assembly operations across three continents. FDA premarket scrutiny in the United States and EU MDR classification rigor in Brussels are reshaping where manufacturers validate quality systems and locate final assembly capacity.
United States
Dermatology clinic chains in metropolitan markets concentrate procurement power through single-source framework agreements with dose-traceability requirements. FDA 21 CFR Part 3 combination product regulations force revalidation of design control systems for drug-device integrals. Greater Boston hosts contract manufacturers serving pharmaceutical firms seeking ISO 13485-certified precision pump supply.
Germany
Pharmaceutical firms in Baden-Württemberg expand gel-applicator combination submissions under EU MDR accelerated pathways. ECHA REACH substance restrictions for skin-contact polymers force 12-18 month reformulation cycles. Stuttgart and surrounding precision engineering clusters dominate piston pump mechanism production for European pharmaceutical OEMs.
China
Domestic pharmaceutical packaging demand drives adoption of metered-dose pump formats for topical corticosteroid generics. NMPA medical device classification rules for combination products align with international standards. Yangtze River Delta contract manufacturers are acquiring ISO 13485 certifications to supply European pharmaceutical second-source validation programs.
South Korea
Mid-sized contract manufacturers adopt micro-pump actuation platforms with piezoelectric mechanisms to serve regional pharmaceutical firms. MFDS medical device quality standards guide biocompatibility testing protocols for polymer components. Seoul Capital Area production clusters challenge German and Italian incumbents in precision dosing capability.
India
Compounding pharmacies in Maharashtra and Gujarat drive spot demand for ointment tube formats with heated fill processes. CDSCO medical device rules for drug-device combinations are tightening premarket documentation requirements. Mumbai-Pune industrial corridor contract manufacturers are upgrading quality systems to supply private-label precision applicators to European firms.
Topical Applicators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across dosing precision and regulatory certification tiers. The vendor base stratifies between ISO 13485-certified precision specialists serving prescription dermatology and commodity tube converters supplying over-the-counter segments. Three archetypes dominate: diversified healthcare conglomerates with dermatology franchises, specialized pharmaceutical packaging firms with device quality systems, and regional contract manufacturers pursuing certification arbitrage. Competitive moves concentrate on M&A to acquire combination product regulatory expertise and strategic partnerships to secure polymer supply chains.
Within the diversified healthcare tier, Johnson & Johnson and Bayer AG exemplify players leveraging extended distribution networks across retail pharmacy and mass-market channels. Among specialized pharmaceutical firms, Galderma occupies a position calibrated for prescription topical therapies with professional-grade applicator requirements. At the contract manufacturing end, Simcro Ltd. represents the veterinary precision segment where species-calibrated dosing standards are converging with human clinical protocols.
| Leading Market Players |
|---|
| Reflex Medical |
| Doselogix |
| Tickerworks |
| Lucas Packaging |
| Simcro Ltd. |
| Johnson & Johnson |
| Galderma |
| Bayer AG |
| GlaxoSmithKline |
| Others |
Value Network & Pricing Analysis
Micro-pump actuation miniaturization is compressing production scale thresholds while fragmenting cost economics between precision electromechanical assemblies and commodity polymer extrusions. This technology transition simultaneously enables South Korean contract manufacturers to challenge German incumbent pricing power while forcing commodity tube converters into thinner margin pools.
Pricing Analysis
Dose-traceability premiums anchor value-based pricing for ISO 13485-certified pump dispensers serving United States dermatology clinic chains. Three-tier pricing structure across premium, standard, and economy levels separates validated combination-product formats from cosmetic-grade tubes and veterinary spot purchases. Pricing pressure stems from REACH substance restriction compliance costs that compress margins on single-use polymer designs. Retail pharmacy buyers exhibit highest price sensitivity, while clinic procurement departments prioritize lot traceability over unit cost.
Supply Chain Analysis
Cyclo-olefin polymer and thermoplastic elastomer feedstock supply rests on petrochemical derivatives whose volatility swings with crude oil benchmarks. Production gravity centers on southern Germany and northern Italy for precision piston mechanisms, with South Korea and Taiwan emerging for micro-pump assembly. Single-source vulnerability concentrates in German notified body technical file reviews facing 14-month backlogs. Distribution runs through pharmaceutical OEM direct contracts, private-label arrangements, and spot purchasing from Indian compounding pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical dosing miniaturization is displacing legacy mechanical formats, creating asymmetric opportunity windows for stakeholders with quality system investments versus commodity-dependent incumbents.
For Market Incumbents: To counter South Korean contract manufacturer encroachment on precision pump supply, German and Italian incumbents must deepen backward integration into polymer nozzle microfabrication and accelerate EU MDR technical file pre-submission to notified bodies. Channel control through single-source framework agreements with United States dermatology clinic chains provides defensive moats against price erosion. For New Entrants and Emerging Players: Veterinary dermatology precision applicators represent the most penetrable white-space segment where human-clinical standards are newly adopted but incumbent supply remains thin. ISO 13485 certification arbitrage through Mumbai-Pune or Seoul Capital Area production enables private-label supply to European pharmaceutical firms seeking second-source validation. Direct partnerships with companion animal specialty practices bypass entrenched human-clinic procurement consolidation. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified healthcare conglomerates seeking combination product regulatory expertise and dermatology channel control. Mid-sized contract manufacturers with validated quality systems and regional pharmaceutical relationships offer strongest 5-10 year viability within electromechanical dosing transition. Watch FDA 21 CFR Part 3 premarket submission backlogs as inflection indicator for regulatory capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acquisition | Enables supply to European pharmaceutical firms under EU MDR accelerated pathways. |
| Micro-Pump Platform Integration | Decentralizes precision dosing capability from German-Italian incumbent clusters. |
| Veterinary Dermatology Partnership | Captures companion animal protocols adopting human-clinical precision standards. |
| Backward Integration into Polymer Feedstock | Insulates margins from cyclo-olefin and thermoplastic elastomer price volatility. |
| Clinic Chain Framework Agreement | Locks in dose-traceable supply relationships with United States metropolitan procurement. |
Research Methodology
FDA 510(k) filings, EMA combination product submissions, and EU MDR notified body technical file databases formed the secondary backbone, cross-referenced with primary interviews involving dermatology clinic procurement managers, pharmaceutical packaging engineers, contract manufacturer quality directors, and veterinary pharmaceutical formulators. Bottom-up and top-down triangulation validated segment-level volume estimates against customs records for polymer component trade flows.
Bottom-up modeling aggregated installed capacity by delivery mode and fill-line sterilization class, while top-down constraints checked aggregate output against pharmaceutical topical therapy prescription volumes across the analysis window. Segmentation dimensions included product rheology class, application therapeutic category, end-user procurement channel, and delivery mechanism precision tier. CAGRs derived from clinician procedure volume trajectories and regulatory submission pipeline velocities.
Several conditions sit outside the modeled scope, including speculative nanomaterial-based applicator formats and unapproved substance-based device reclassifications under EU MDR Annex XVI expansion. Forecasts reflect assumptions on notified body review timelines and polymer feedstock price stabilization. A small set of named triggers warrants ongoing watch: FDA combination product submission backlog durations, ECHA candidate list expansions for skin-contact polymers, and South Korean micro-pump patent litigation developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Formulation Chemicals
Anti-Gelling Agent Market
Formulation Chemicals
Forchlorfenuron Market
Formulation Chemicals
Global Benzaldehyde Derivatives Market
Formulation Chemicals
Slow and Controlled Release Pesticides Market
Formulation Chemicals
Solution Deposition Precursor Market
Formulation Chemicals
Global Formulation Development Outsourcing Market
Formulation Chemicals
Drug Formulation Market
Formulation Chemicals
Global Chemical Licensing Market
Formulation Chemicals
Sol-Gel Products Market
Formulation Chemicals
Ammonium Fluoride Solution Market
Formulation Chemicals
Gelling Agent Market
Formulation Chemicals
Template Preparation Kits Market
Formulation Chemicals
Foundry Binders Market
Formulation Chemicals
Embossing Powder Market