
 Prenatal Supplements Market | 2026-2036
Prenatal Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Prenatal Supplements Market Analytics
Expecting mothers seeking clean-label, plant-based formulations is redrawing demand patterns across the prenatal supplements category. Bayer AG leverages its pharmaceutical heritage to sustain credibility in clinical-grade prenatal vitamin lines. Garden of Life specializes in USDA Organic and Non-GMO Project Verified offerings that anchor its position in the natural channel. Abbott Laboratories competes through pediatrician-recommended prenatal portfolios tied to its broader maternal nutrition franchise.
Prenatal supplements are multi-nutrient formulations containing folic acid, iron, calcium, DHA, and iodine, designed to support fetal neural tube development, maternal hemoglobin maintenance, and gestational bone density requirements. The vitamins segment dominates volume, with folate and iron combinations forming the clinical backbone of most prescribed regimens. Gummies are the fastest-growing formulation, capturing consumers who experience tablet-related nausea during early pregnancy. Online stores are expanding fastest among distribution channels, though pharmacies retain the highest-margin positioning due to pharmacist consultation attachments.
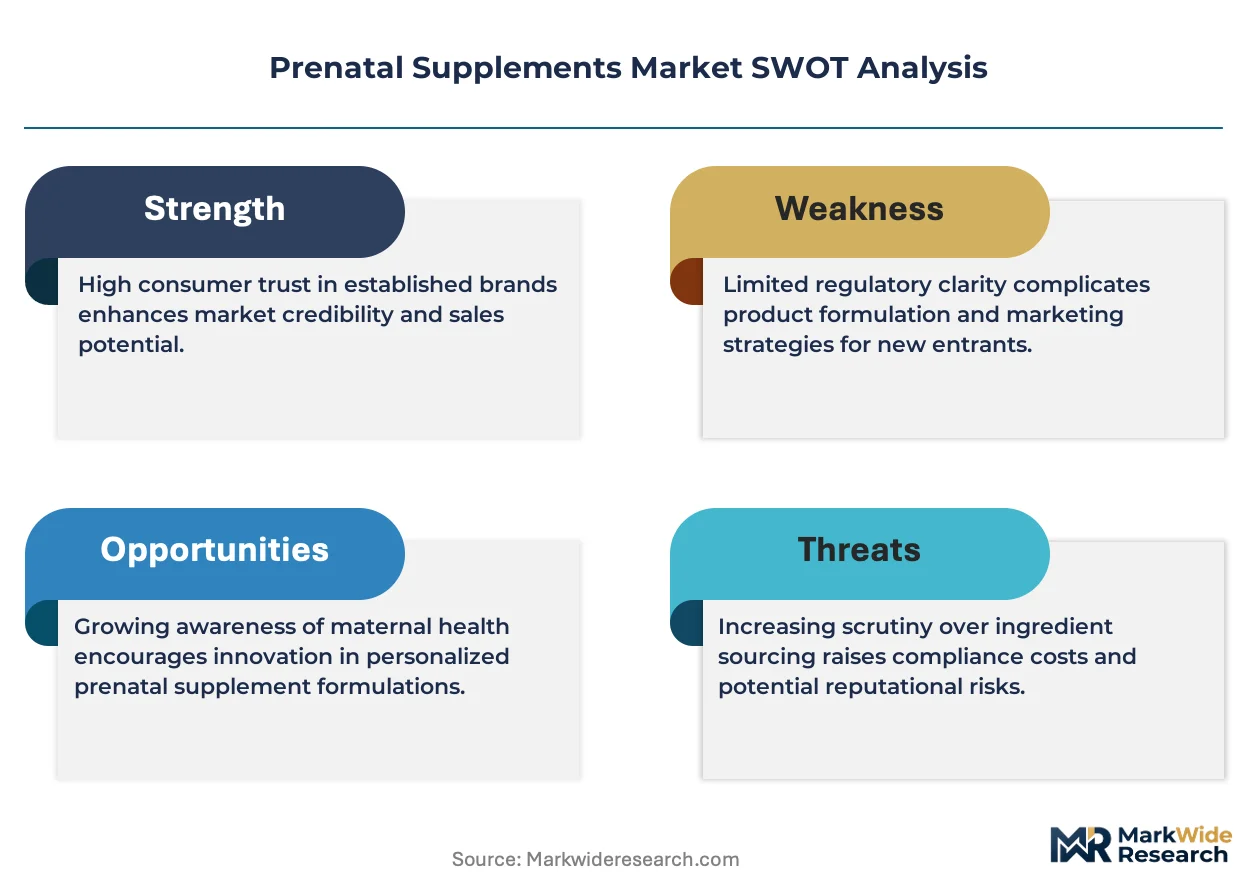
The FDA oversees prenatal supplement safety and labeling under DSHEA, while the USDA certifies organic claims and the EPA monitors fish-sourced omega-3 purity thresholds. These frameworks elevate compliance costs for new entrants but reinforce brand trust for established players with dedicated regulatory affairs teams. Stakeholders must monitor evolving state-level ingredient disclosure mandates and third-party certification requirements that increasingly influence retailer acceptance criteria.
Market Dynamics
The prenatal supplements sector is experiencing structural pressure from generational turnover in its core consumer base, as first-time mothers born after 1985 reject legacy tablet formats and demand alternative delivery systems that accommodate pregnancy-related sensitivities.
Growth Catalysts
- DSHEA Labeling Modernization:The FDA's updated dietary supplement labeling requirements are forcing manufacturers to disclose ingredient sourcing and potency verification, which elevates transparency standards and rewards brands with established quality infrastructure.
- Algae-Derived DHA:Plant-based omega-3 extraction technologies are displacing fish oil dependence, opening formulation pathways for vegan-certified product lines that capture environmentally conscious maternal consumers.
- Pharmacist Consultation Attachment:Pharmacy channel investments in prenatal counseling services are converting over-the-counter purchases into guided regimen selections, strengthening margin retention against pure-play e-commerce competitors.
Market Restraints
- Choline Raw Material Concentration:Over 70% of pharmaceutical-grade choline bitartrate originates from Chinese chemical manufacturers, exposing formulators to input cost volatility and geopolitical supply disruptions.
- Third-Party Certification Backlogs:NSF International and USP verification queues now extend 14-18 months for new entrants, creating a structural barrier to shelf placement at major retail pharmacy chains.
- Iron Bioavailability Trade-offs:Ferrous bisglycinate offers superior gastrointestinal tolerance but carries 3-4x the raw material cost of ferrous sulfate, compressing margin structures for mid-tier product lines.
Strategic Opportunities
- Postpartum Recovery Extensions:Lactation support formulations with galactagogues and tissue repair nutrients represent an adjacent white space with limited incumbent specialization.
- Subscription Direct-to-Consumer Models:Trimester-timed replenishment programs with dose personalization are capturing urban Millennial consumers who prioritize convenience over pharmacy pickup.
- State-Level Medicaid Inclusion:Expansion of prenatal vitamin coverage under state Medicaid formularies creates a reimbursement pathway for clinical-grade products in underserved maternal health populations.
Industry Challenges
- Regulatory Affairs Talent Scarcity:The intersection of DSHEA compliance, state-level disclosure mandates, and retailer-specific certification requirements demands specialized expertise that commands premium compensation in tight labor markets.
- Legacy ERP Integration:Batch record digitization and supply chain traceability systems require substantial capital deployment for mid-sized manufacturers operating on twentieth-century infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prenatal Supplements Market |
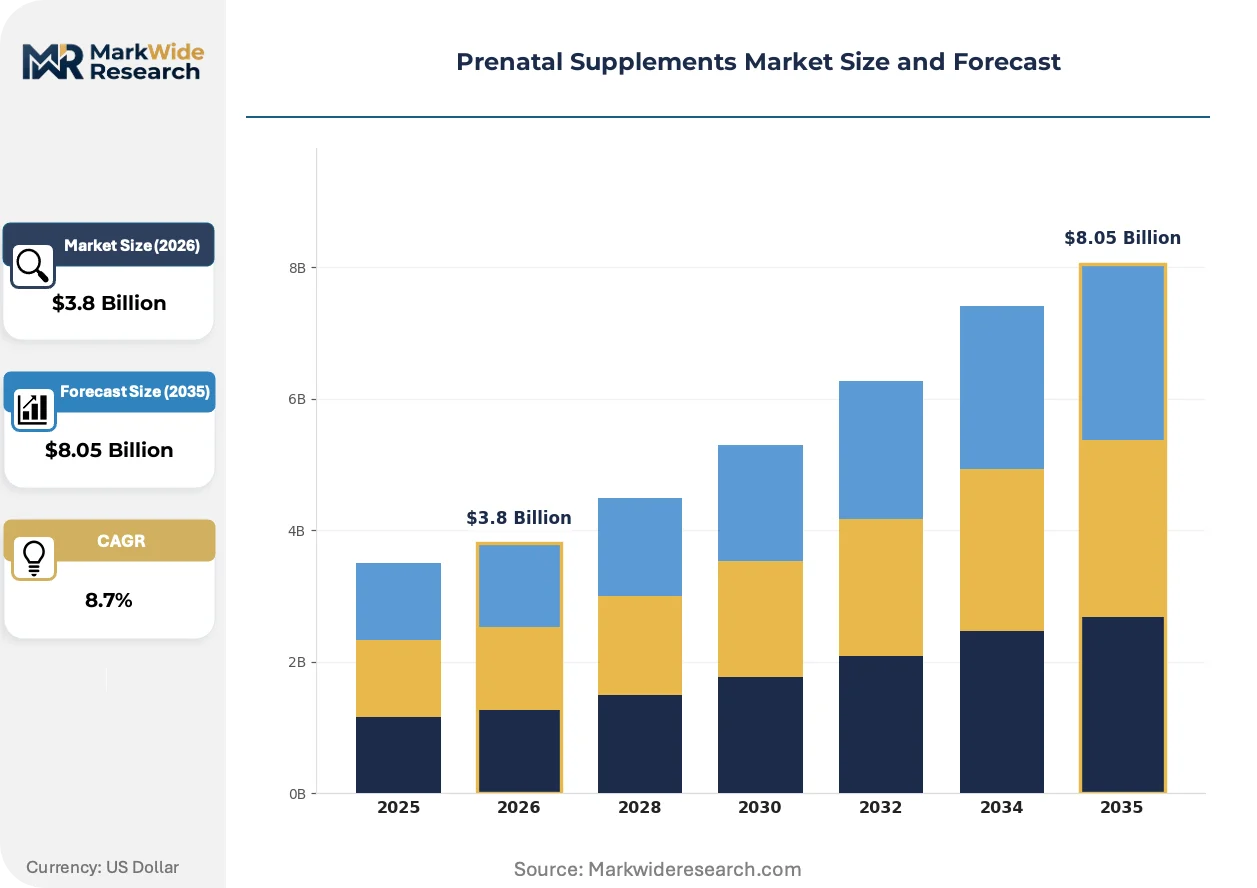
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal, Omega-3 Formulation: Tablets, Capsules, Gummies, Powders Distribution Channel: Pharmacies, Supermarkets, Online Stores, Health Food Shops Target Consumer: First-Time Mothers, Expecting Mothers, Healthcare Providers, Nutritional Consultants |
| Companies Covered | Nature Made, Bayer AG, Abbott Laboratories, Vitabiotics, Garden of Life, Church & Dwight Co., Inc., Nestlé, Procter & Gamble, MegaFood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prenatal Supplements Market Evolving Landscape
Formulation science and distribution architecture are undergoing parallel transformation as maternal nutrition moves from standardized multivitamins toward precision-targeted nutrient combinations delivered through novel consumption formats.
Liposomal encapsulation technology is bifurcating the bioavailability landscape for fat-soluble vitamins. High-absorption D3 and K2 complexes now command shelf space in specialty maternity retailers. Premium-positioned brands are capturing consumers who failed to achieve therapeutic serum levels with conventional oil-based softgels. This technology is compressing market share for standard emulsion formulations in the prenatal category.
REACH microplastic restrictions are reshaping European formulation standards for gummy and softgel products. The ECHA's proposed limitations on synthetic polymer additives are forcing manufacturers to reformulate texture agents and coating materials. German and French prenatal brands are accelerating shifts toward pectin-based gelling systems ahead of anticipated enforcement timelines.
Subscription commerce is displacing pharmacy-centric replenishment patterns among digitally native maternal consumers. Trimester-based auto-ship programs with dose escalation protocols are capturing urban professionals who prioritize convenience. This behavioral shift is most visible in coastal United States metropolitan markets where same-day delivery infrastructure supports just-in-time nutrition management.
Prenatal Supplements Market Segmentation
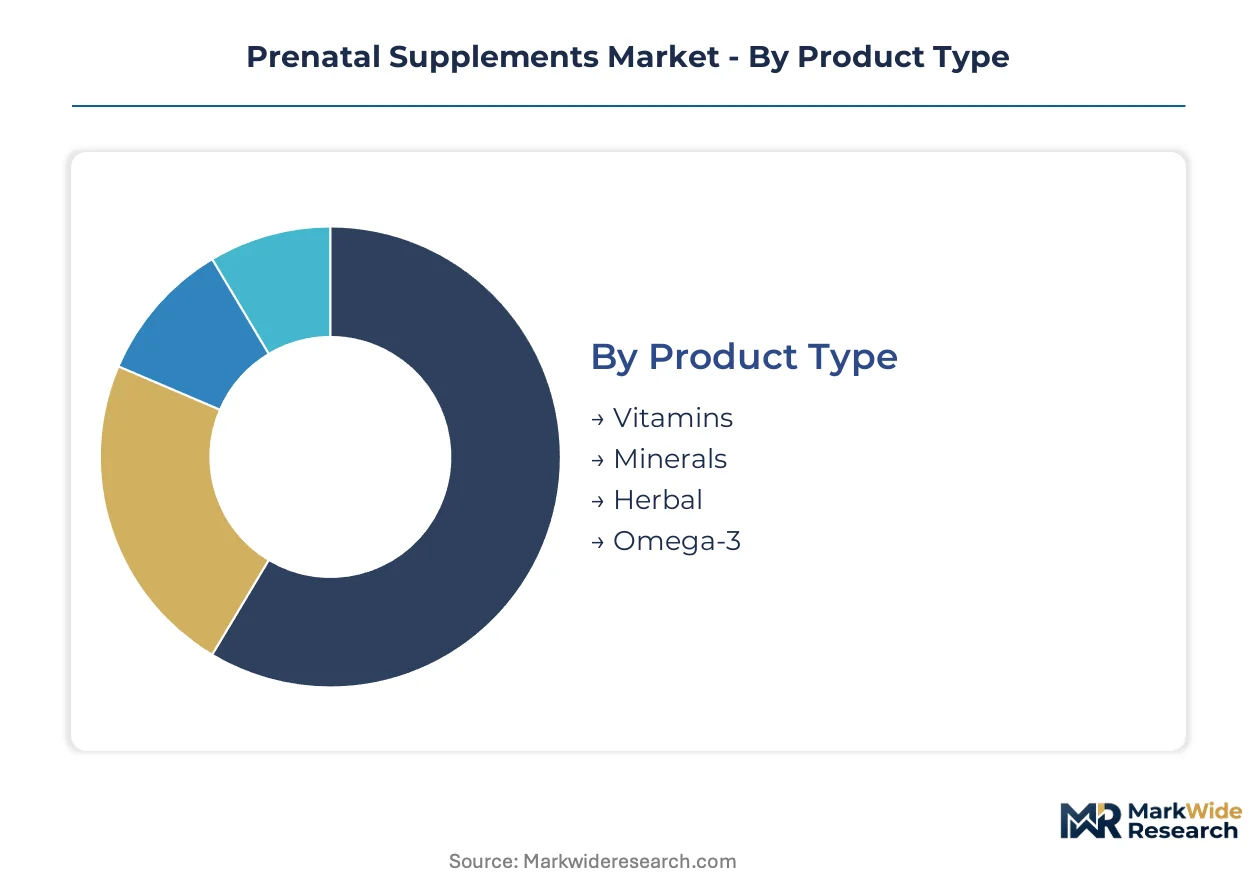
Prenatal supplement purchasing patterns fragment sharply across delivery format preferences and channel access points. Manufacturers must align formulation investments with generational consumption habits while navigating divergent margin structures across pharmacy and digital channels.
Product Type:
Vitamin and mineral combinations capture the deepest margin pools through prescription-adjacent positioning and clinical validation requirements.
- Vitamins:Folate-iron-D3 complexes form the clinical backbone of prescribed regimens. Demand concentrates in the United States and Germany where obstetrician endorsement drives pharmacy placement and reimbursement attachment.
- Minerals:Calcium-magnesium-iodine formulations address gestational bone density and thyroid support. China and India show concentrated uptake where dietary mineral gaps persist in maternal populations.
- Herbal:Ginger, red raspberry leaf, and chasteberry extracts target nausea and uterine tone. Natural channel specialists in Germany and Australia drive placement through midwife recommendation networks.
- Omega-3:Algae-derived DHA displaces fish oil in vegan-certified lines. Coastal United States metropolitan markets and Nordic countries show steepest adoption curves.
Vitamins hold installed capacity. Omega-3 is rotating up the share rankings.
Formulation:
Tablet and capsule formats retain volume leadership while gummy and powder alternatives capture experience-driven switching.
- Tablets:Compressed multivitamin matrices dominate prescription fulfillment and Medicaid formulary inclusion. Cost efficiency sustains penetration in price-sensitive United States Southern states and developing Asian markets.
- Capsules:Gelatin and vegetable-based shells enable delayed-release iron and sensitive nutrient protection. Germany and Switzerland show concentrated demand for enteric-coated variants.
- Gummies:Pectin-based chewables address first-trimester nausea and swallowing aversion. Millennial and Gen-Z consumers in United States coastal cities and United Kingdom urban centers drive fastest expansion.
- Powders:Single-serve sachets and tub formats suit smoothie integration and dose customization. Australia and Canada lead adoption among fitness-oriented maternal demographics.
Tablets hold installed capacity. Gummies are climbing the fastest.
Distribution Channel:
Pharmacy and supermarket channels defend margin through consultation attachment while online stores capture convenience-seeking switchers.
- Pharmacies:Pharmacist-guided prenatal counseling converts OTC purchases into regimen adherence. Germany, France, and Japan sustain highest per-transaction values through professional recommendation.
- Supermarkets:Mass-market placement captures unplanned purchases and price-comparison shoppers. United States big-box retailers and United Kingdom grocery chains dominate volume.
- Online Stores:Subscription auto-ship and trimester-timed replenishment capture urban professionals. United States coastal metros and Chinese tier-one cities show steepest digital adoption curves.
- Health Food Shops:Specialty retailers anchor organic and non-GMO certified positioning. Australia, Canada, and Netherlands sustain dedicated natural channel infrastructure.
Pharmacies hold installed capacity. Online stores are gaining share fastest.
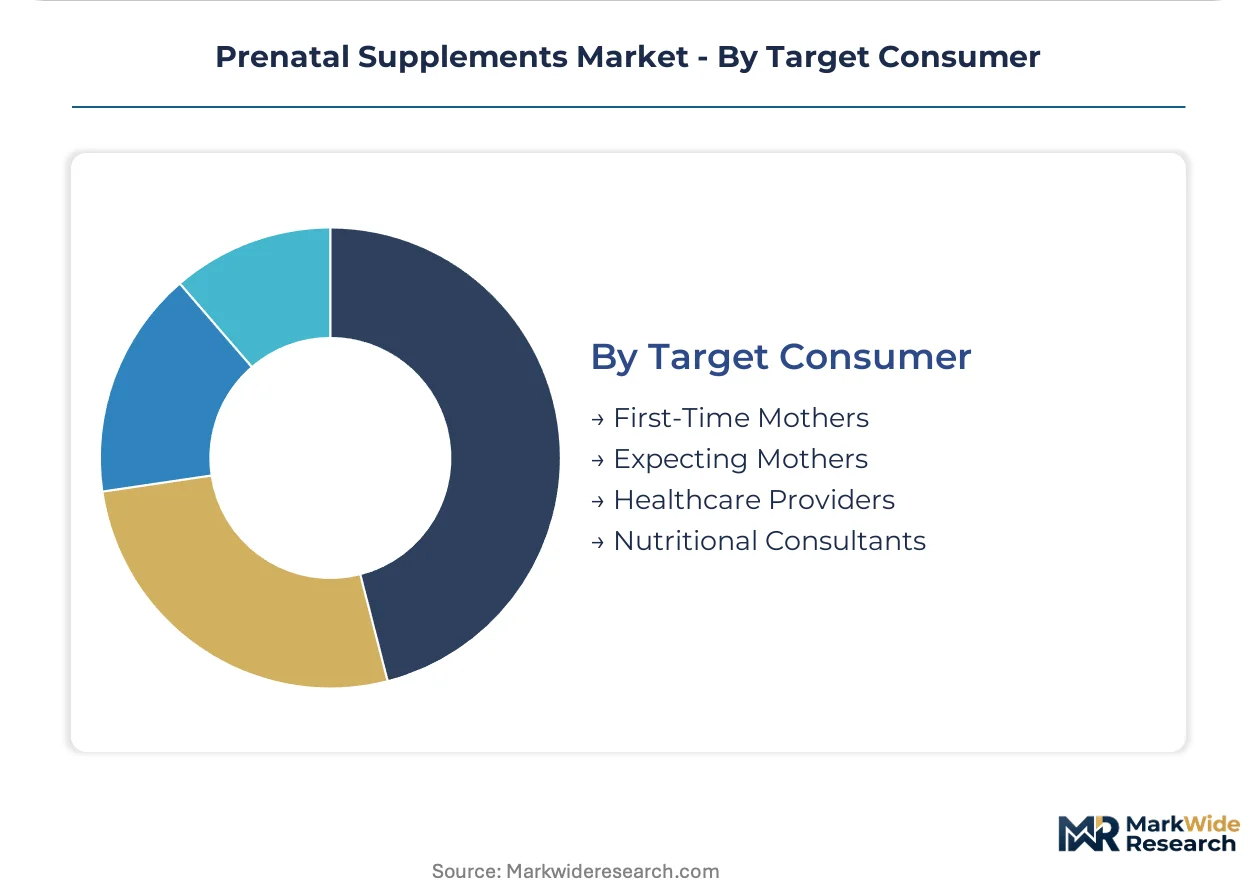
Target Consumer:
Expecting mothers drive absolute volume while healthcare providers gate prescription-adjacent segments.
- First-Time Mothers:Digital-native Millennials and Gen-Z entrants show highest formulation switching rates and premium willingness. United States and United Kingdom urban markets concentrate this demographic.
- Expecting Mothers:Repeat pregnancy experience drives brand loyalty and trimester-specific purchasing. China and India show concentrated multigenerational household influence on selection.
- Healthcare Providers:Obstetricians, midwives, and pharmacists control prescription and recommendation pathways. Germany, Japan, and France maintain strongest professional gatekeeper influence.
- Nutritional Consultants:Functional medicine practitioners and dietitians steer personalized regimen design. United States and Australia show expanding practitioner network density.
Expecting mothers hold installed capacity. First-time mothers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical-grade prenatal vitamin exports flow primarily to United States pharmacy chains and Chinese maternity clinics, establishing a transatlantic trade corridor that shapes formulation standards across both markets.
United States
Millennial first-time mothers in coastal metropolitan areas drive gummy and powder format switching, with New York and Los Angeles metro areas showing steepest adoption curves. FDA DSHEA labeling modernization elevates compliance costs but rewards established quality infrastructure. Subscription direct-to-consumer models concentrate in San Francisco and Seattle technology corridors.
Germany
Pharmacist consultation attachment sustains highest per-transaction values in Frankfurt and Munich pharmacy networks. ECHA REACH microplastic restrictions accelerate pectin-based gelling system transitions ahead of enforcement timelines. Bavaria and Baden-Württemberg anchor organic certification specialist manufacturing.
China
Tier-one city maternal health clinics in Shanghai and Beijing drive premium prenatal vitamin uptake among middle-class consumers. NMPA oversight of imported supplement registration creates structured entry pathways for clinical-grade foreign brands. Yangtze River Delta manufacturing clusters supply pharmaceutical-grade choline bitartrate to global formulators.
United Kingdom
Urban Millennial consumers in London and Manchester show fastest digital channel migration for trimester-timed replenishment programs. Midwife recommendation networks sustain natural channel placement for herbal prenatal formulations. Vitabiotics maintains domestic manufacturing presence with export orientation toward Commonwealth markets.
Australia
Fitness-oriented maternal demographics in Sydney and Melbourne drive powder format adoption for smoothie integration. TGA therapeutic goods administration maintains stringent ingredient disclosure requirements that elevate local quality benchmarks. Health food shop infrastructure in Queensland and Victoria sustains organic and non-GMO certified positioning.
Prenatal Supplements Market Competitive Landscape
Player mix skews toward multinational pharmaceutical heritage companies and natural channel specialists. Market structure shows moderate consolidation with tiered competition between clinical-grade prescription-adjacent portfolios and mass-market retail formulations. Strategic archetypes include pharmaceutical heritage players leveraging obstetrician endorsement networks, natural channel specialists commanding organic certification premiums, and consumer goods conglomerates exploiting mass-market distribution scale. Dominant competitive moves center on algae-derived DHA formulation transitions and subscription commerce infrastructure deployment.
Within the pharmaceutical heritage tier, Bayer AG and Abbott Laboratories occupy positions that exemplify clinical credibility anchoring, while Garden of Life represents the natural channel specialist archetype with USDA Organic and Non-GMO Project Verified portfolio concentration. Church & Dwight Co., Inc. sits within the consumer goods scale tier, and Vitabiotics exemplifies regional specialist positioning with Commonwealth market export orientation. These named entities serve as structural anchors for understanding competitive dynamics without asserting specific strategic actions or financial performance claims.
| Leading Market Players |
|---|
| Nature Made |
| Bayer AG |
| Abbott Laboratories |
| Vitabiotics |
| Garden of Life |
| Church & Dwight Co., Inc. |
| Nestlé |
| Procter & Gamble |
| MegaFood |
| Others |
Value Network & Pricing Analysis
Fourteen-month NSF International certification queues concentrate pricing power among incumbents with pre-existing quality infrastructure, while compressing margin structures for mid-tier entrants awaiting shelf placement at major United States pharmacy chains. This lead-time asymmetry between certified and uncertified suppliers reinforces a bifurcated market where established pharmaceutical heritage brands capture premium positioning and emerging players absorb compliance cost penalties.
Pricing Analysis
Conventional tablet formulations anchor economy pricing tiers, liposomal D3-K2 complexes command premium positioning, and algae-derived DHA variants occupy mid-tier expansion slots. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and bioavailability technology, with NSF-verified products sustaining 40-60% price elevation over unverified alternatives. Cost compression in standard-tier iron formulations is intensifying because ferrous bisglycinate raw material premiums compress margins against ferrous sulfate competitors. Medicaid-eligible consumers in United States Southern states exhibit highest price sensitivity, while coastal metropolitan first-time mothers show lowest elasticity for gummy and powder alternatives.
Supply Chain Analysis
Seventy-plus percent pharmaceutical-grade choline bitartrate inventories concentrate in Yangtze River Delta manufacturing clusters, creating 90-120 day exposure windows for formulators dependent on Chinese chemical manufacturers. Raw material procurement draws from algae cultivation facilities in United States coastal zones for vegan DHA, pectin suppliers in Brazil for gummy texture agents, and iodine extraction operations in Chile for thyroid-support minerals. Single-source vulnerability in choline inputs exposes global formulators to geopolitical disruption and input cost volatility. Distribution runs through pharmacist consultation networks in Germany and France, direct-to-consumer subscription platforms in United States coastal metros, and maternity clinic procurement systems in Chinese tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prenatal supplements sector functions as a regulatory entrenchment moat where NSF and USP verification backlogs create structural barriers that insulate incumbent quality infrastructure investments from rapid competitive replication.
For Market Incumbents: Secure algae-derived DHA supply agreements with United States coastal cultivation facilities before capacity constraints tighten, and accelerate pectin-based gummy line transitions ahead of ECHA REACH microplastic enforcement timelines. Emerging subscription commerce specialists threaten pharmacy channel margin retention, demanding counter-investment in trimester-timed auto-ship infrastructure. Certification investment in dual organic-FDA compliance maintains shelf positioning leverage against natural channel entrants.
For New Entrants and Emerging Players: Lead with postpartum recovery extensions targeting lactation support and tissue repair nutrient formulations, a white space with limited incumbent specialization and strong midwife recommendation network potential in Germany and Australia. The most penetrable segment comprises fitness-oriented maternal demographics in Australia and Canada seeking powder format smoothie integration. Go-to-market execution should anchor in health food shop channel partnerships with organic certification co-marketing.
For Investors and Strategic Acquirers: Carve-out targets emerge from consumer goods conglomerates seeking to divest non-core supplement portfolios lacking dedicated regulatory affairs capabilities. Long-term viability over a five-to-ten year horizon rests on subscription commerce infrastructure and algae-DHA formulation transition completion. Acquisition target archetype: mid-tier brands with established pharmacy distribution but underinvested in direct-to-consumer platforms. The signal to watch is state-level Medicaid formulary expansion velocity as reimbursement pathway indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Algae-DHA Formulation Transition | Plant-based omega-3 sourcing displaces fish oil dependence and captures vegan-certified consumer segments in coastal United States markets. |
| Subscription Commerce Infrastructure | Trimester-timed auto-ship programs convert pharmacy-centric replenishment patterns among Millennial first-time mothers. |
| NSF Verification Investment | Third-party certification accelerates shelf placement at major retail pharmacy chains and sustains premium pricing tiers. |
| Postpartum Recovery Line Extension | Lactation support formulations with galactagogues address adjacent white space with limited incumbent specialization. |
| Pectin-Based Gummy Reformulation | ECHA REACH microplastic compliance ahead of enforcement timelines protects European market access for German and French brands. |
Research Methodology
A standing panel of regulatory affairs directors, pharmacy procurement managers, maternal health clinicians, and supplement brand marketing executives provided ongoing calibration across primary interview cycles and secondary source validation. This practitioner input combined with FDA DSHEA guidance documents, ECHA REACH restriction proposals, NMPA registration filings, and retail pharmacy formulary databases enabled bottom-up demand segmentation and top-down market sizing triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework segmentation by product type, formulation, distribution channel, and target consumer archetype. CAGRs derived from historical trajectory analysis and forward-looking adoption curve modeling incorporated algae-DHA technology penetration rates, subscription commerce channel shift velocities, and state-level Medicaid inclusion expansion patterns as industry-specific forecast inputs.
Underlying assumptions cover sustained FDA DSHEA enforcement intensity and stable choline raw material trade flows, with deviation risk concentrated in geopolitical supply disruptions and accelerated ECHA microplastic restriction timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Global Liver Health Supplements Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Dietary Supplement Cultures Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market
Nutritional Supplements
US and Canada Beta Glucan Market