
 Airport Security Screening Systems Market | 2026-2036
Airport Security Screening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Security Screening Systems Market Outlook
A capital-intensity divergence between Tier-1 defense conglomerates and mid-tier specialists is rotating procurement leverage toward vertically integrated suppliers. Smiths Detection leverages its in-house explosive trace detection chemistry to sustain margin pools in European hub airports. L3Harris Technologies anchors North American demand through long-term service contracts with the country's national aviation regulator. Nuctech Company competes on manufacturing scale, dominating price-sensitive installations across emerging aviation markets.
Airport security screening systems encompass integrated hardware-software platforms that detect weapons, explosives, and contraband in passenger baggage and on person, typically employing X-ray attenuation coefficients of 0.1–10 MeV or millimeter-wave frequencies of 30–300 GHz to discriminate threat materials from benign objects. Computed tomography technology leads product-type value capture as airports replace legacy 2D baggage scanners with 3D reconstruction systems that reduce manual bag checks. Millimeter wave full-body scanners represent the fastest-growing technology segment, driven by privacy-compliant avatar-based imaging that eliminates human review of anatomical details. Fixed installations concentrate the majority of revenue, though portable systems gain share in temporary terminal expansions and event-driven aviation security deployments.
The FAA and TSA in the United States, EASA under EU framework regulations, and ICAO global standards collectively shape certification timelines, mandating specific detection probabilities for explosive simulants and operational availability thresholds. These requirements force continuous R&D reinvestment and create barriers for entrants lacking established regulator relationships. Stakeholders must monitor evolving checkpoint automation mandates and biometric integration standards that will determine next-generation procurement specifications and vendor qualification criteria.
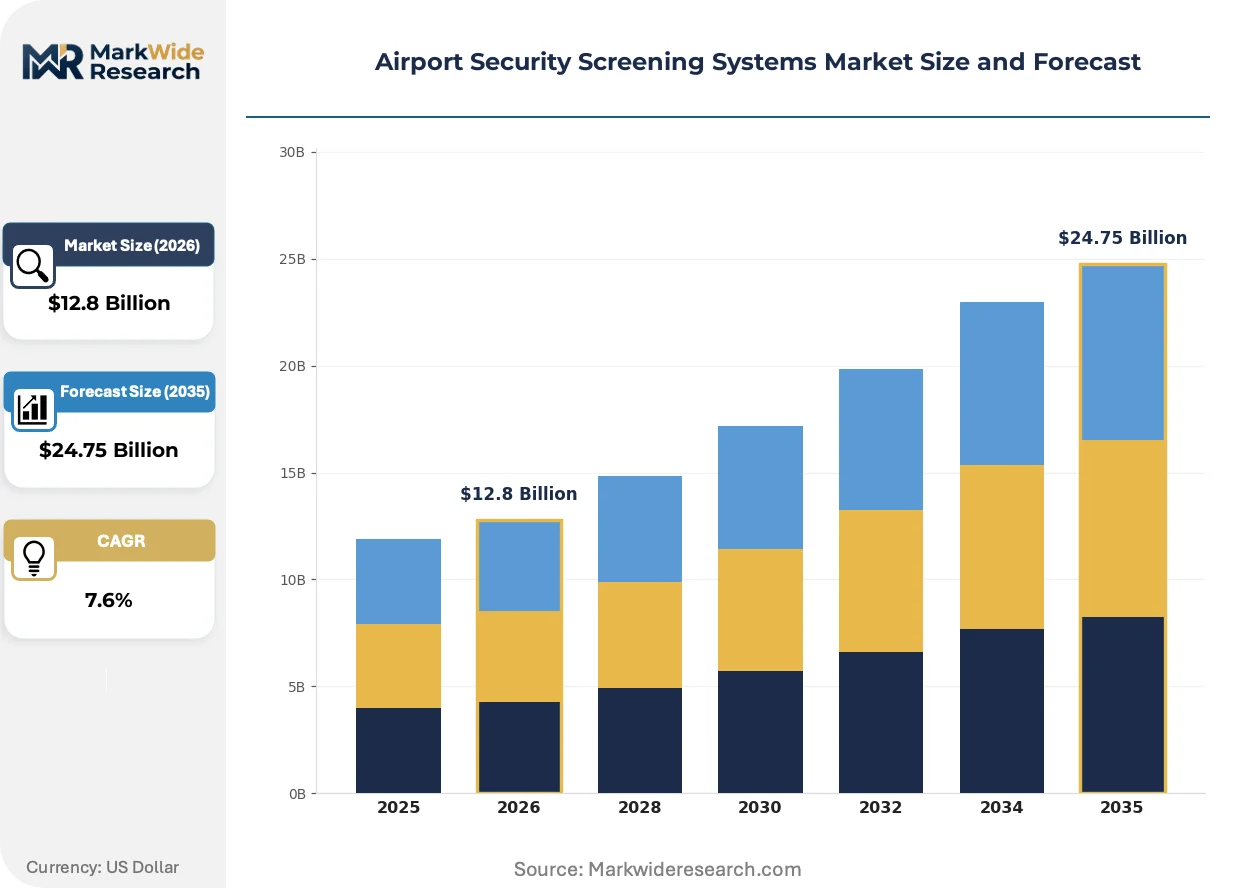
Market Dynamics
The global airport security screening systems market pivots on TSA's mandated transition to computed tomography baggage scanners, a regulatory compression forcing wholesale replacement of legacy 2D X-ray infrastructure across major hub airports.
Growth Catalysts
- ICAO Annex 17 Standards:Updated global aviation security protocols mandate enhanced explosive detection capabilities, compelling airports to upgrade screening infrastructure regardless of capital constraints.
- Checkpoint Automation:Automated screening lanes reduce passenger throughput time by integrating divestiture, conveyance, and collection functions into unified systems.
- Privacy-Compliant Body Scanning:Millimeter-wave scanners with generic avatar outputs satisfy GDPR and equivalent privacy frameworks, unlocking deployment in European and Asia-Pacific terminals previously blocked by civil liberties concerns.
Market Restraints
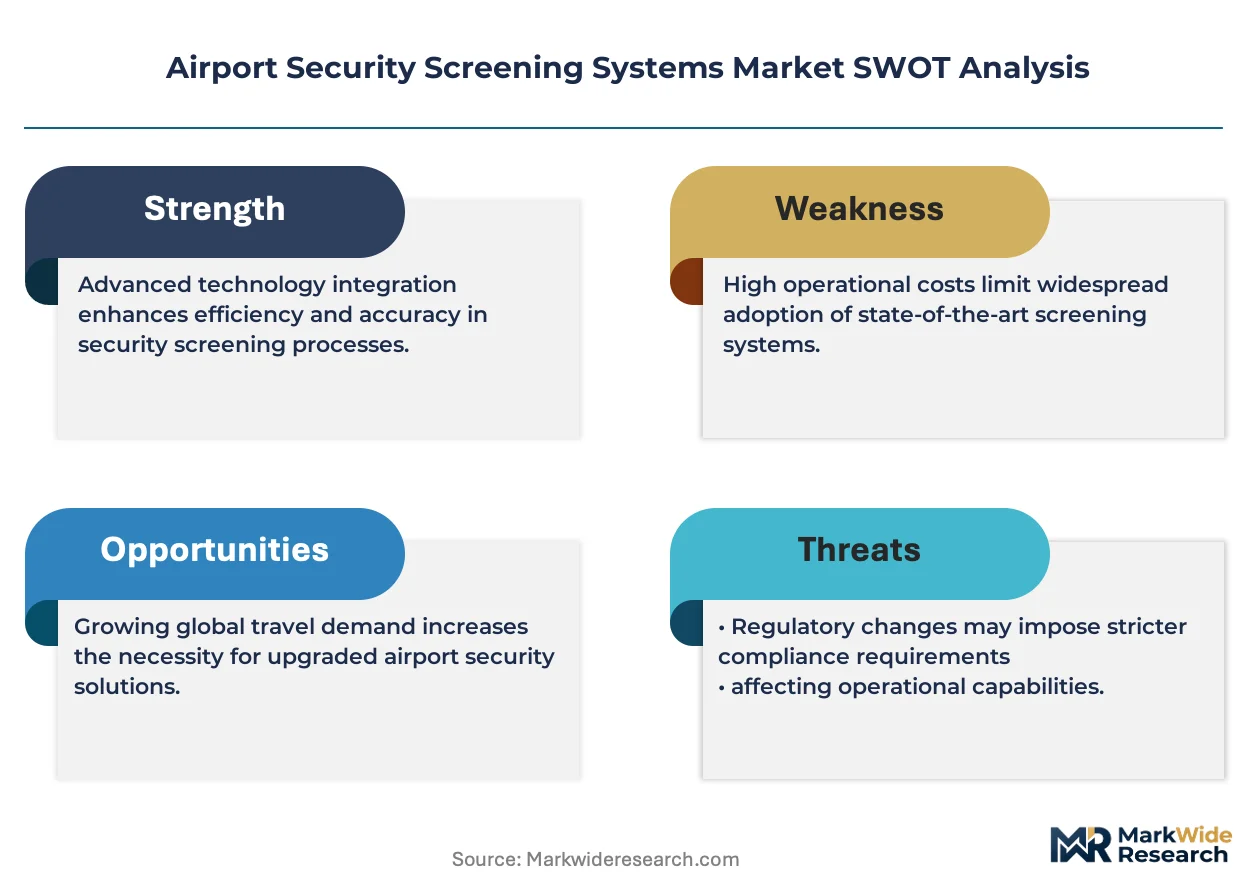
- Detector Crystal Supply Concentration:Cadmium zinc telluride semiconductor substrates for photon-counting CT detectors concentrate among three Asian suppliers, exposing OEMs to input volatility.
- Certification Timeline Friction:FAA and EASA explosive detection qualification protocols require 18-24 month validation cycles, freezing product iterations and extending R&D payback periods.
- Substitution by Passive Screening:Standoff chemical detection and behavioral analytics reduce reliance on physical checkpoint infrastructure in select high-security installations.
Strategic Opportunities
- India Airport Modernization:The country's PLI scheme for electronics manufacturing incentivizes domestic assembly of screening components, creating captive supply advantages for early entrants.
- Biometric-Checkpoint Convergence:Integration of facial recognition with screening lane access control enables seamless passenger flow from curb to gate.
- Temporary Event Deployments:Portable millimeter-wave and X-ray systems address surge capacity needs for international sporting events and political summits.
Industry Challenges
- Explosive Trace Detection Chemistry Talent:Specialized formulation expertise for ion mobility spectrometry sensors resides with a shrinking cohort of defense-sector chemists approaching retirement.
- Legacy System Integration Complexity:New CT scanners must interface with decade-old baggage handling systems and security operations center software architectures.
- Operational Availability Thresholds:TSA mandates 99.5% uptime for critical screening equipment, requiring predictive maintenance capabilities most vendors lack at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Security Screening Systems Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-Through Metal Detectors, X-Ray Screening Systems, Full-Body Scanners, Explosive Trace Detectors Technology: Millimeter Wave, Computed Tomography, 2D Image Processing, Explosive Detection Algorithms End User: Airports, Government Agencies, Private Security Firms, Airlines Installation Type: Fixed Systems, Portable Systems, Temporary Setups, Integrated Solutions |
| Companies Covered | Leidos, Analogic Corporation, Smiths Detection, Nuctech Company, L3Harris Technologies, OSI Systems, Thales Group, NEC Corporation, Rapiscan Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Security Screening Systems Market Strategic Shifts
Computed tomography reconstruction algorithms and artificial intelligence-assisted threat recognition are compressing false alarm rates while accelerating passenger throughput. These technical advances reshape competitive positioning around software differentiation rather than hardware specifications alone.
Deep learning-based automated threat detection is displacing human image analysts at primary inspection stations. Major European hub airports in Germany and the Netherlands now deploy neural networks trained on millions of bag scans, reducing secondary inspection rates from 15% to under 5%. This compression of labor dependency is reallocating security personnel to exception-handling roles.
EASA's updated common evaluation process for security equipment introduces streamlined certification pathways for CT-based hold baggage screening systems. The framework reduces duplicate national testing across EU member states, accelerating time-to-revenue for vendors. German and French regulators have already adopted the mutual recognition protocol, with Italian and Spanish aviation authorities preparing implementation.
Airport authorities increasingly unbundle hardware procurement from long-term service contracts, compressing vendor lock-in and enabling multi-source maintenance strategies. This fragmentation of the traditional single-source model pressures incumbents to compete on lifecycle cost transparency. The shift is most pronounced in Middle Eastern hub airports pursuing operational flexibility for mega-terminal expansions.
Airport Security Screening Systems Market Segmentation
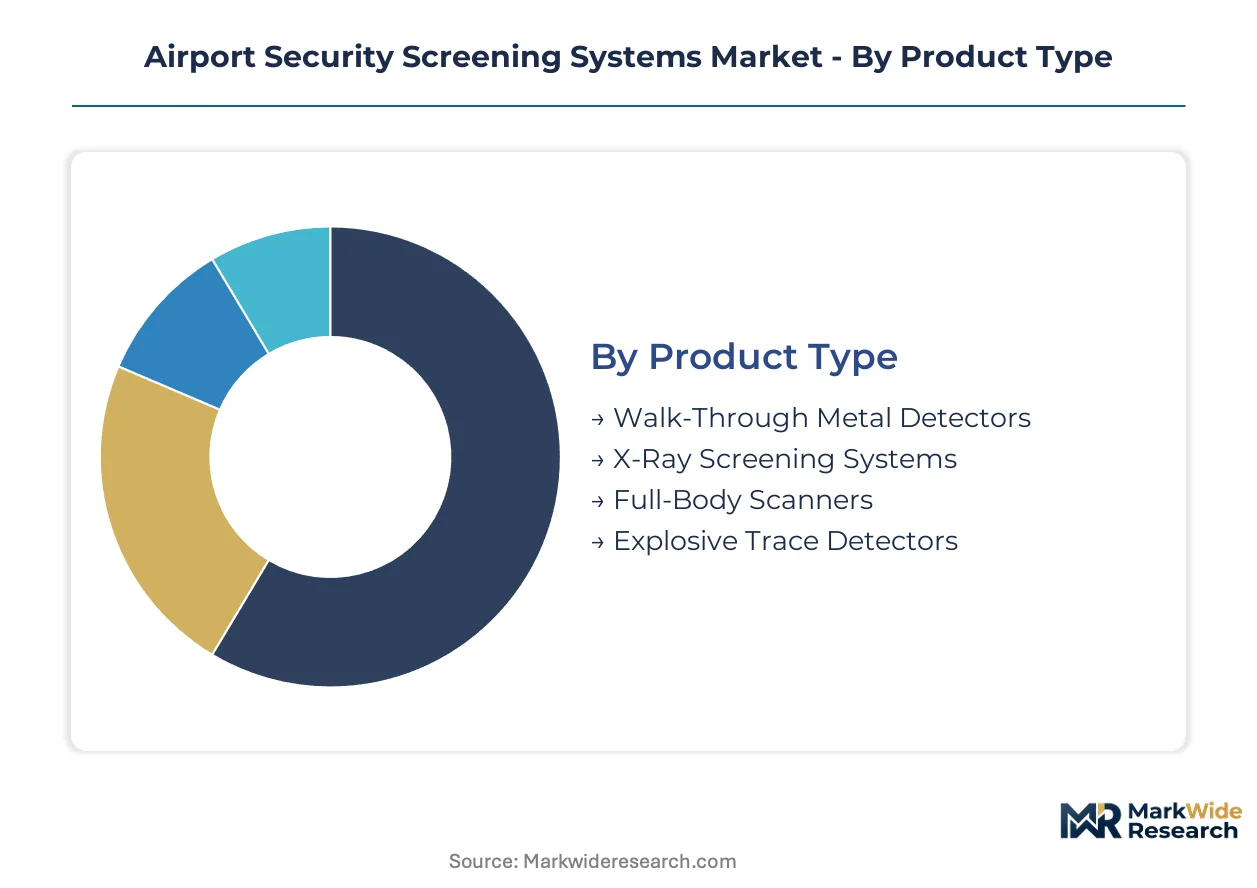
Segmentation reveals how procurement decisions fragment across threat-detection modalities and operational deployment models. Technology substitution pressures and regulatory compliance timelines create divergent growth trajectories across each dimension.
Product Type:
Substitution pressure from emerging passive screening technologies weighs most heavily on legacy metal detection platforms, while CT-based baggage systems face limited near-term replacement risk due to TSA mandate lock-in.
- X-Ray Screening Systems:Dual-view and multi-energy X-ray configurations process cabin baggage at 0.1–10 MeV attenuation ranges. Demand concentrates in United States hub airports replacing 2D legacy units under TSA checkpoint automation directives, constrained by 18-24 month FAA certification cycles.
- Full-Body Scanners:Millimeter-wave and backscatter architectures detect anomalies under clothing without physical pat-downs. European terminals in Germany and Netherlands drive volume as GDPR-compliant avatar outputs resolve prior civil liberties blockages, with Asia-Pacific airports now following.
- Walk-Through Metal Detectors:Induction-based portals for ferrous and non-ferrous threat detection remain ubiquitous at secondary checkpoints and staff entrances.
- Explosive Trace Detectors:Ion mobility spectrometry and chemiluminescence sensors sample swabs or ambient air for explosive residue traces.
X-Ray Screening Systems anchors the volume base while Full-Body Scanners gains share at the steepest rate.
Technology:
Cost tier stratification separates premium photon-counting CT detectors from commoditized 2D image processing stacks, with algorithmic differentiation emerging as a new margin lever.
- Computed Tomography:3D reconstruction algorithms generate volumetric baggage images from multiple X-ray projection angles. Major European hubs in Germany and Netherlands deploy neural-network threat classification trained on millions of scans, compressing secondary inspection rates from 15% to under 5%.
- Millimeter Wave:30–300 GHz frequency bands penetrate clothing to detect concealed objects. Privacy-compliant generic avatar outputs unlock deployment in France and Netherlands terminals previously blocked by data protection authorities, with EASA streamlined certification accelerating adoption.
- 2D Image Processing:Legacy single or dual-view X-ray projection with operator-dependent threat recognition dominates price-sensitive retrofits.
- Explosive Detection Algorithms:Machine learning classifiers trained on explosive simulant spectral signatures reduce false positive rates in trace and CT systems.
Computed Tomography commands the premium tier while Millimeter Wave expands most quickly across privacy-sensitive jurisdictions.
End User:
Application concentration varies sharply: airports bear capital intensity for passenger-facing infrastructure while government agencies fund R&D and certification pipelines.
- Airports:Terminal operators procure integrated checkpoint lanes combining divestiture, conveyance, and collection functions. Middle Eastern mega-hub expansions in UAE and Saudi Arabia unbundle hardware from service contracts, fragmenting traditional single-source vendor relationships.
- Government Agencies:National aviation regulators including TSA and EASA mandate detection standards and operate qualification testing facilities.
- Private Security Firms:Contracted checkpoint operators at secondary terminals and general aviation facilities drive portable system demand.
- Airlines:Carriers deploy proprietary screening at premium check-in zones and loyalty program access points.
Airports absorb the majority of capital expenditure while Government Agencies shape procurement specifications through mandate design.
Installation Type:
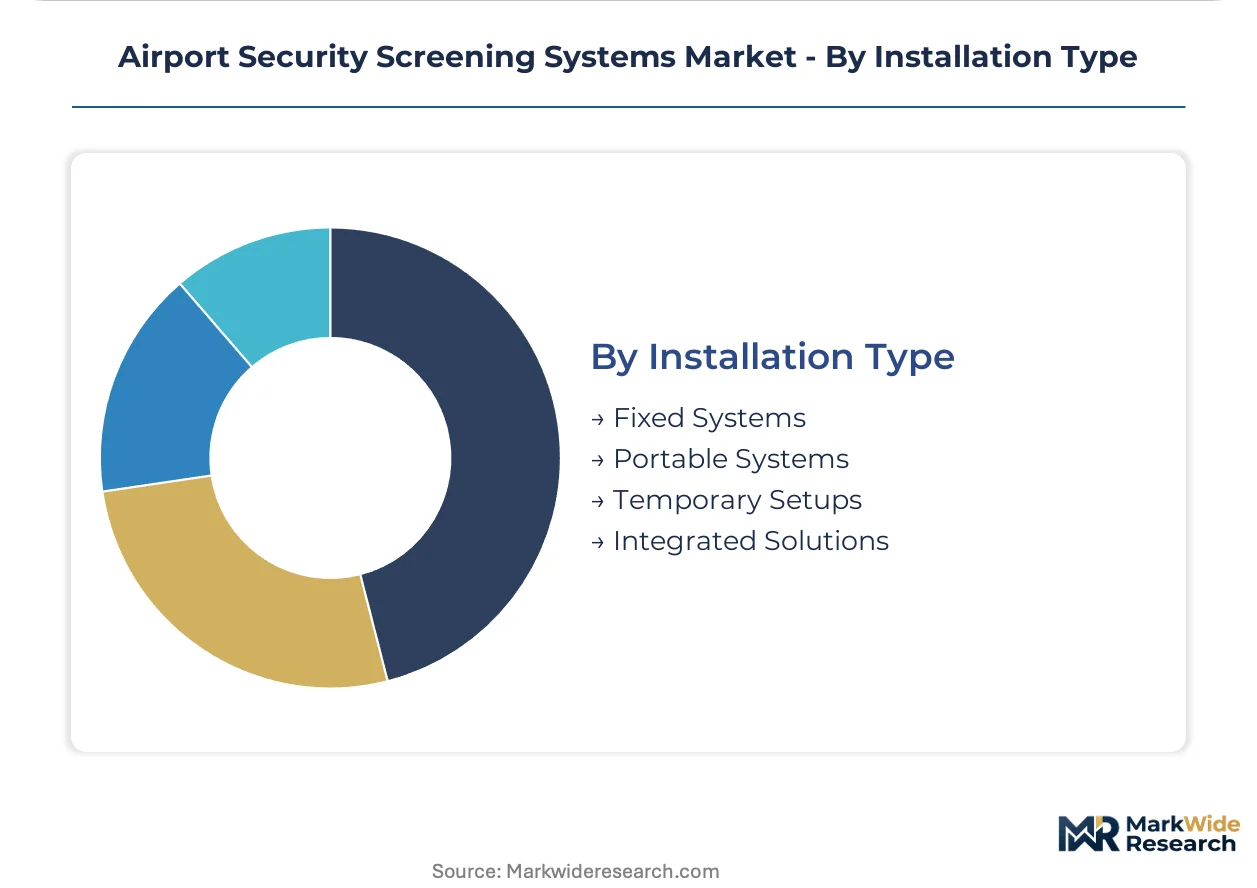
Customer type segmentation splits between permanent infrastructure commitments and operational flexibility requirements, with temporary deployments gaining traction in event-driven security planning.
- Fixed Systems:Hardwired CT baggage lines and millimeter-wave portals integrated with terminal architecture. United States hub airports anchor replacement demand as TSA mandates eliminate grandfathered 2D X-ray infrastructure.
- Portable Systems:Battery-powered or generator-fed units deployable within hours. International sporting events and political summits in Qatar and India drive rental market development for surge capacity.
- Temporary Setups:Semi-permanent installations for terminal expansions or seasonal capacity peaks.
- Integrated Solutions:Unified hardware-software-service contracts spanning multiple checkpoint technologies.
Fixed Systems dominate revenue concentration while Portable Systems climbs fastest as event-security budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement markets. Gulf state mega-hubs absorb premium-tier CT systems without capital constraint, while Indian and Southeast Asian airports prioritize manufacturing-scale suppliers under localization mandates.
United States
TSA checkpoint automation directives drive wholesale replacement of legacy 2D X-ray infrastructure at Atlanta, Chicago O'Hare, and Dallas-Fort Worth hubs. FAA certification cycles extend 18-24 months, freezing product iterations for vendors lacking established regulator relationships. Denver and Seattle-Tacoma terminals now deploy integrated screening lanes combining divestiture, conveyance, and collection functions.
Germany
Frankfurt and Munich airports anchor European demand for neural-network threat classification systems trained on millions of bag scans. EASA's streamlined common evaluation process reduces duplicate national testing, accelerating vendor time-to-revenue. Berlin-Brandenburg's terminal expansions unbundle hardware procurement from long-term service contracts, fragmenting traditional single-source vendor relationships.
China
Beijing Capital, Shanghai Pudong, and Guangzhou Baiyun drive volume for price-sensitive installations leveraging domestic manufacturing scale. MIIT standards for security equipment certification create preference for locally assembled components. Shenzhen and Chengdu terminals expand CT baggage screening capacity ahead of international route restoration.
India
Delhi Indira Gandhi and Mumbai Chhatrapati Shivaji Maharaj terminals modernize under the PLI scheme for electronics manufacturing, incentivizing domestic assembly of screening components. DGFT import substitution policies tilt procurement toward local joint ventures. Bangalore and Hyderabad airports pilot biometric-checkpoint convergence integrating facial recognition with screening lane access control.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International pursue operational flexibility for mega-terminal expansions, unbundling hardware from service contracts. MOHAP aviation security standards mandate 99.5% uptime thresholds for critical screening equipment. Sharjah and Ras Al Khaimah terminals deploy portable millimeter-wave systems for surge capacity during international events.
Airport Security Screening Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding regulator relationships and service contract lock-in while specialists compete on component innovation and price. The market structure concentrates procurement leverage among vertically positioned suppliers with in-house detector chemistry or manufacturing scale. Three archetypes dominate: defense conglomerates with long-term government relationships, mid-tier specialists with proprietary detection algorithms, and manufacturing-scale suppliers serving price-sensitive emerging markets. Competitive moves center on certification timeline acceleration and geographic footprint expansion through local assembly partnerships.
Within the integrated defense tier, Leidos and L3Harris Technologies occupy positions anchored by national aviation regulator relationships in North America. Smiths Detection exemplifies the European specialist archetype with concentrated presence at hub airports. Nuctech Company represents the manufacturing-scale vector, competing on production volume for emerging aviation markets. These three patterns illustrate how procurement leverage rotates toward suppliers combining certification access with captive supply advantages.
| Leading Market Players |
|---|
| Leidos |
| Analogic Corporation |
| Smiths Detection |
| Nuctech Company |
| L3Harris Technologies |
| OSI Systems |
| Thales Group |
| NEC Corporation |
| Rapiscan Systems |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four month FAA and EASA certification cycles concentrate pricing power among incumbent vendors with established regulator relationships, while cadmium zinc telluride detector substrate shortages extend lead times and compress margins for CT scanner OEMs lacking captive supply.
Pricing Analysis
After-sales service contracts spanning 10-15 year lifecycles generate 60-70% of lifetime value for screening system vendors. Contract-based long-term service agreements dominate, with price differentiation driven by certification tier (FAA/EASA qualified versus national-only) and geographic delivery cost to hub versus secondary airports. Pricing pressure stems from Middle Eastern mega-hubs unbundling hardware from service contracts, fragmenting traditional single-source lock-in. Emerging aviation markets in India and Southeast Asia exhibit highest price sensitivity, while Gulf state procurement shows lowest sensitivity due to operational flexibility priorities.
Supply Chain Analysis
China, Japan, and South Korea anchor production of cadmium zinc telluride semiconductor substrates, photon-counting detector arrays, and millimeter-wave transceiver modules. Raw material dependencies include rare earth elements for detector crystals, high-purity germanium for gamma spectroscopy, and specialized ceramics for X-ray tube housings. Single-source vulnerability concentrates in CZT substrate supply among three Asian suppliers. Distribution runs through direct OEM-to-airport procurement for fixed installations, with rental/leasing channels serving portable system demand for temporary event deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TSA's mandated CT baggage scanner transition creates a high-growth disruption window, with regulatory compression forcing wholesale infrastructure replacement across major hub airports regardless of capital constraints.
For Market Incumbents: Compound certification pipeline advantages by accelerating EASA streamlined evaluation process adoption and securing long-term service contract renewals before unbundling trends spread beyond Middle Eastern hubs. Threat substitution from passive standoff detection and behavioral analytics demands defensive R&D investment in AI-assisted threat recognition algorithms. Vertical integration into detector crystal supply buffers input volatility from Asian substrate suppliers.
For New Entrants and Emerging Players: EASA's streamlined common evaluation process for CT-based hold baggage screening creates entry pathway acceleration. White-space targets concentrate in India's PLI scheme electronics manufacturing incentives and portable system rentals for international sporting events. Go-to-market angle: domestic joint venture assembly partnerships with local component sourcing to satisfy DGFT import substitution mandates.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates divesting non-core checkpoint automation divisions amid portfolio rationalization. Long-term viability hinges on software differentiation moats rather than hardware commoditization, favoring vendors with neural-network threat classification capabilities. Signal to watch: biometric-checkpoint convergence integration milestones at Bangalore and Hyderabad pilot terminals as inflection indicator for next-generation procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Timeline Acceleration | EASA streamlined evaluation process reduces duplicate national testing across EU member states. |
| Detector Chemistry Backward Integration | In-house explosive trace detection formulation secures margin pools against retiring talent scarcity. |
| Biometric-Checkpoint Convergence | Facial recognition integration with screening lane access control enables seamless passenger flow. |
| Local Assembly Partnership | India PLI scheme joint ventures satisfy DGFT import substitution and capture price-sensitive volume. |
| Predictive Maintenance Capability Buildout | TSA-mandated 99.5% uptime thresholds require vendor scale most competitors currently lack. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with airport security directors, TSA procurement officers, EASA certification engineers, and CT scanner maintenance heads; and secondary validation through FAA certification databases, EASA common evaluation process documentation, ICAO Annex 17 standards filings, and customs trade data on detector component imports. Bottom-up installation counts across 40+ hub airports triangulated against top-down vendor revenue segmentation.
Across the projection horizon, the analytical framework modeled value trajectories by technology type, product category, installation configuration, and end-user archetype. CAGRs derived from regression analysis of historical procurement cycles against regulatory mandate timelines. Industry-specific forecast inputs included TSA checkpoint automation directive implementation pace and EASA mutual recognition protocol adoption rates across EU member states.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory mandate enforcement and stable detector substrate supply; material deviation in certification timeline friction or CZT supply concentration would warrant model refresh. Recalibration cycles align with material shifts in TSA automation procurement schedules and EASA streamlined evaluation process expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
Aviation Asset Management Market
Aerospace & Defense
Commercial Aircraft Health Monitoring Systems Market
Aerospace & Defense
Commercial Aircraft Carbon Brakes Market
Aerospace & Defense
Commercial Aerospace Market
Aerospace & Defense
UK Aviation Market
Aerospace & Defense
Missile Seekers Market
Aerospace & Defense
Deep Space Robotics Market
Aerospace & Defense
Commercial Aircraft Aerostructures Market
Aerospace & Defense
Global Composites in the Aerospace Interior Market
Aerospace & Defense
Civil Aerospace Simulation and Training Market
Aerospace & Defense
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Aerospace & Defense
Airborne ISR Market
Aerospace & Defense
Asia-Pacific Fighter Aircraft Market
Aerospace & Defense
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aerospace & Defense
Commercial Helicopter Market
Aerospace & Defense
Dismounted Soldier Systems Market