
 Artificial Intelligence Chatbots Market | 2026-2036
Artificial Intelligence Chatbots Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence Chatbots Market Insights
ISO/IEC 42001 certification for AI management systems is collapsing the barrier between experimental deployments and production-grade chatbot procurement, forcing vendors to demonstrate governance rigor. Anthropic leverages constitutional AI principles to differentiate its Claude systems in regulated industries. Google anchors its Gemini portfolio through deep integration with Workspace and Cloud infrastructure. Microsoft dominates enterprise distribution channels by embedding Copilot across Office 365 and Dynamics ecosystems.
Artificial intelligence chatbots constitute software agents that process natural language inputs through transformer-based neural architectures, generating contextual responses via autoregressive token prediction for automated human-computer dialogue. Natural language processing segments command the deepest technical moats as foundation models require billion-parameter training runs and curated instruction datasets. Cloud-based deployment models capture the fastest expansion trajectory by eliminating capital expenditure barriers for mid-market adopters. Customer support functionality retains the largest installed base, though sales assistance applications show the steepest growth curve as revenue operations teams pursue real-time lead qualification.
The EU AI Act and GDPR impose layered compliance obligations on chatbot providers operating in European jurisdictions, with high-risk system designations triggering conformity assessments and human oversight mandates. The US lacks unified federal AI legislation, leaving the FTC to pursue enforcement through consumer protection and deceptive practice statutes while sectoral regulators like the FDA govern medical chatbot claims. Stakeholders must monitor emerging state-level AI statutes in California and New York that may fragment compliance requirements ahead of any federal harmonization.
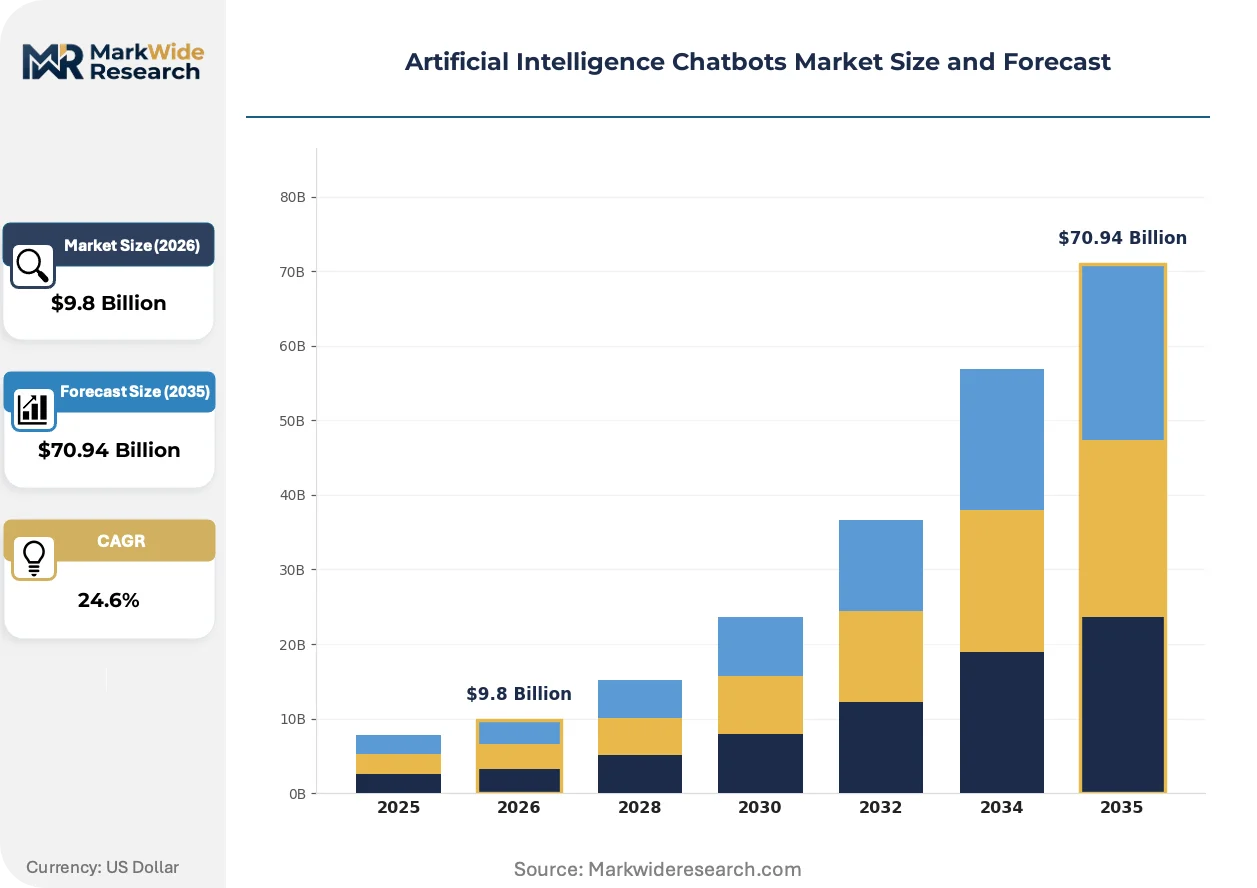
Market Dynamics
Transformer architectures trained on trillion-token corpora are compressing development cycles, forcing incumbents to release foundation model updates quarterly rather than annually to defend positioning. This velocity differential separates vendors with proprietary training infrastructure from those dependent on third-party APIs.
Growth Catalysts
- EU AI Act compliance mandates:High-risk system designations create procurement preference for certified vendors, accelerating enterprise adoption of governance-audited conversational agents in healthcare and financial services.
- Cloud API consumption models:Pay-per-token pricing eliminates capital expenditure barriers, enabling mid-market healthcare providers and retailers to deploy enterprise-grade chatbots without infrastructure investments.
- Workforce automation imperatives:Contact center labor shortages in the United States and Germany drive replacement demand for autonomous customer service agents capable of multi-turn resolution.
Market Restraints
- Compute cost volatility:NVIDIA GPU supply concentration and foundry capacity constraints in Taiwan create input cost instability for training and inference operations.
- Foundation model dependency:API access to leading large language models concentrates in three US-based providers, creating supplier power asymmetry for downstream application developers.
- GDPR data localization:Cross-border transfer restrictions for conversational data force redundant infrastructure deployment, raising operational complexity for multi-national deployments.
Strategic Opportunities
- India's digital public infrastructure:Unified Payments Interface integration and vernacular language support create white space for voice-first conversational banking agents in tier-two cities.
- Multimodal convergence:Synthesis of text, image, and audio processing enables diagnostic chatbots capable of analyzing patient-submitted visual symptoms alongside symptom descriptions.
- CSRD disclosure requirements:Mandatory sustainability reporting creates demand for automated ESG data collection agents that interface with supply chain partners.
Industry Challenges
- ISO/IEC 42001 certification timelines:Six-to-twelve-month audit cycles delay production deployments for vendors lacking pre-established AI management system documentation.
- Retrieval-augmented generation integration:Enterprise knowledge base fragmentation forces custom connector development for each deployment, compressing gross margins.
- Prompt engineering talent scarcity:Shortage of practitioners capable of optimizing context window utilization and chain-of-thought architectures limits model performance extraction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence Chatbots Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $70.94 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Deep Learning, Natural Language Processing, Machine Learning, Rule-Based Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Retail, Healthcare, BFSI, Telecommunications Functionality: Customer Support, Sales Assistance, Appointment Scheduling, Feedback Collection |
| Companies Covered | Anthropic (Claude AI), Kore.ai, OpenAI (ChatGPT), Cognigy, Yellow.ai, Google (Gemini), Perplexity AI, LeewayHertz, Microsoft (Copilot), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence Chatbots Market Trends and Innovations
Foundation model specialization is fragmenting the vendor landscape, with domain-specific fine-tuned systems outperforming general-purpose alternatives in regulated verticals. This technical divergence rewards organizations that invest in proprietary training data curation and reinforcement learning from human feedback pipelines.
Small language models optimized for edge deployment are displacing cloud-only architectures in manufacturing and healthcare settings where latency constraints and data sovereignty requirements prohibit round-trip API calls. Automotive suppliers and hospital networks are piloting on-premise inference engines for quality control and clinical documentation. This shift compresses addressable revenue per deployment while expanding total installable base.
The EU AI Act's risk classification framework imposes conformity assessment obligations on general-purpose AI systems deployed in high-stakes contexts. Medical device manufacturers face additional scrutiny from EMA and national competent authorities when integrating conversational interfaces into diagnostic workflows. German and French healthcare providers are front-loading compliance documentation to secure early-mover advantage in procurement processes.
Enterprise buyers are consolidating vendor relationships around platforms offering unified governance dashboards spanning multiple conversational use cases. Procurement committees now prioritize API standardization and audit logging capabilities over raw benchmark performance. This preference shift favors established cloud infrastructure providers with pre-existing security certifications across United States federal and European public sector procurement frameworks.
Artificial Intelligence Chatbots Market Segmentation
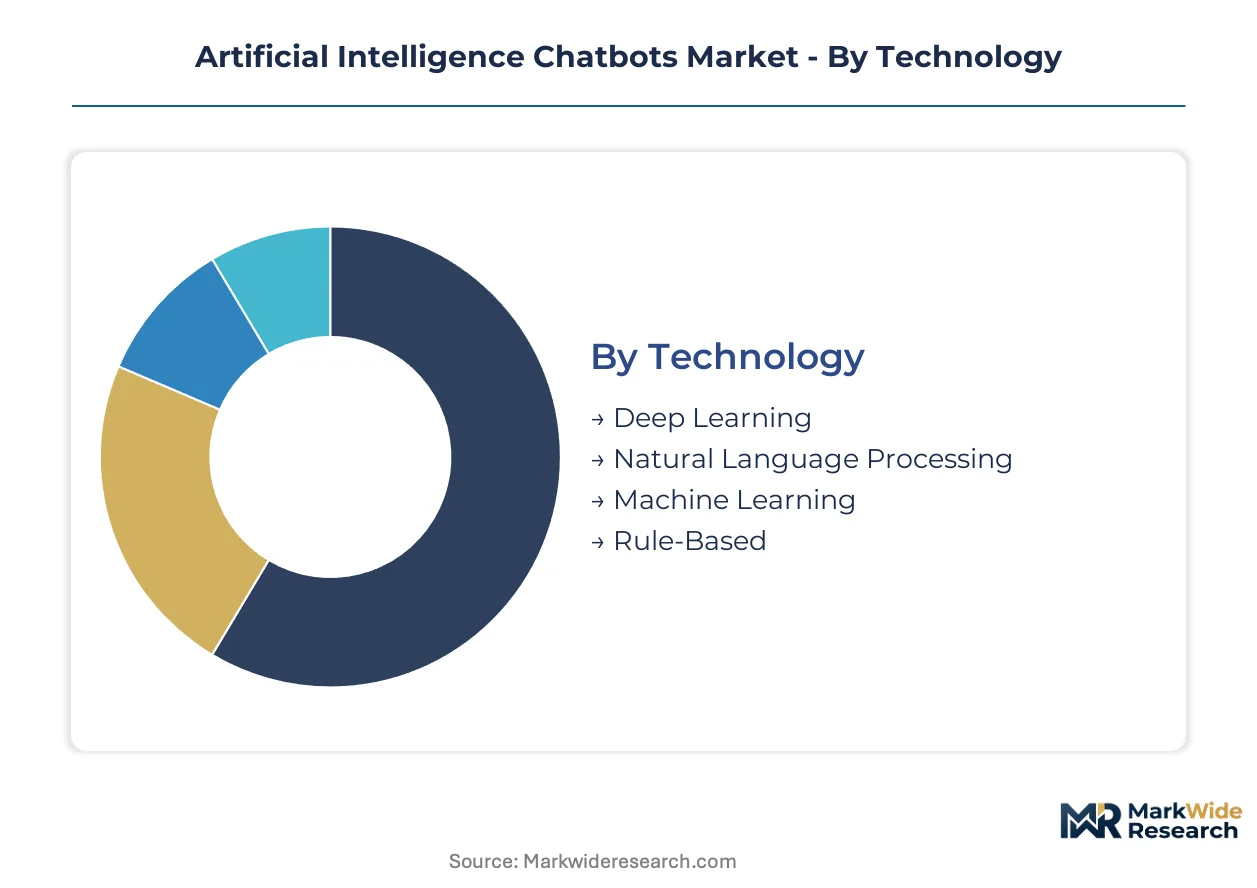
Segmentation in the artificial intelligence chatbots market reveals distinct competitive dynamics across technology architectures, deployment economics, and functional applications. Each dimension carries unique substitution pressures from adjacent automation technologies and legacy service models.
Technology:
Natural language processing faces the most acute substitution pressure from emerging multimodal systems that integrate vision and audio processing alongside text.
- Natural Language Processing:Transformer-based architectures process contextual embeddings through billion-parameter models trained on curated instruction datasets. Healthcare providers in the United States deploy these systems for clinical documentation, driven by HIPAA-compliant API availability from major cloud vendors.
- Deep Learning:Multi-layer neural networks enable intent classification and sentiment extraction through supervised fine-tuning on domain-specific corpora. German automotive suppliers leverage these capabilities for technical support bots handling complex diagnostic queries.
- Machine Learning:Traditional statistical methods support intent matching and response ranking in resource-constrained environments.
- Rule-Based:Deterministic decision trees persist in highly regulated financial compliance workflows requiring auditable logic paths.
Natural language processing retains volume leadership; deep learning holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates capital-intensive on-premise installations from consumption-based alternatives, with hybrid architectures capturing mid-market budget flexibility.
- Cloud-Based:API consumption eliminates infrastructure ownership, enabling pay-per-token scaling for mid-market retailers and healthcare clinics. India's Unified Payments Interface integration drives voice-first conversational banking deployments in tier-two cities without data center investments.
- SaaS:Pre-configured vertical templates accelerate time-to-value for customer support and sales use cases through standardized connectors.
- On-Premises:Air-gapped inference engines serve defense contractors and Swiss banking institutions with strict data sovereignty mandates.
- Hybrid:Split architectures process sensitive data locally while routing general queries to cloud endpoints, balancing latency with compliance.
Cloud-based deployments command the broadest adoption base; SaaS models are climbing the fastest as procurement committees prioritize standardized governance dashboards.
End User:
Application maturity varies sharply across verticals, with healthcare and financial services imposing the most stringent validation requirements.
- Healthcare:Conversational agents triage patient symptoms, schedule appointments, and surface clinical guidelines through EHR-integrated interfaces. FDA scrutiny of diagnostic claims and EMA conformity assessments under the EU AI Act create compliance barriers that favor established vendors with pre-existing certifications.
- BFSI:Retail banks deploy virtual assistants for account servicing and fraud alerts, with RBI guidelines in India and SEC disclosure requirements in the United States shaping procurement criteria.
- Retail:E-commerce platforms automate order tracking and returns processing through messaging channel integration.
- Telecommunications:Network operators use bots for technical troubleshooting and plan optimization, replacing tier-one contact center capacity.
Healthcare leads in revenue per deployment; BFSI is gaining share fastest as real-time transaction assistance expands.
Functionality:
Customer-facing automation concentrates in support and sales workflows, with back-office applications trailing in adoption velocity.
- Customer Support:Multi-turn resolution bots handle password resets, order status inquiries, and technical troubleshooting across messaging and voice channels. Contact center labor shortages in Germany and the United States drive replacement demand for autonomous agents capable of escalation handoffs.
- Sales Assistance:Real-time lead qualification and product recommendation engines integrate with CRM pipelines to accelerate revenue operations.
- Appointment Scheduling:Calendar-aware bots reduce no-show rates through automated reminders and rescheduling workflows.
- Feedback Collection:Post-interaction surveys and sentiment analysis feed continuous improvement loops for service quality monitoring.
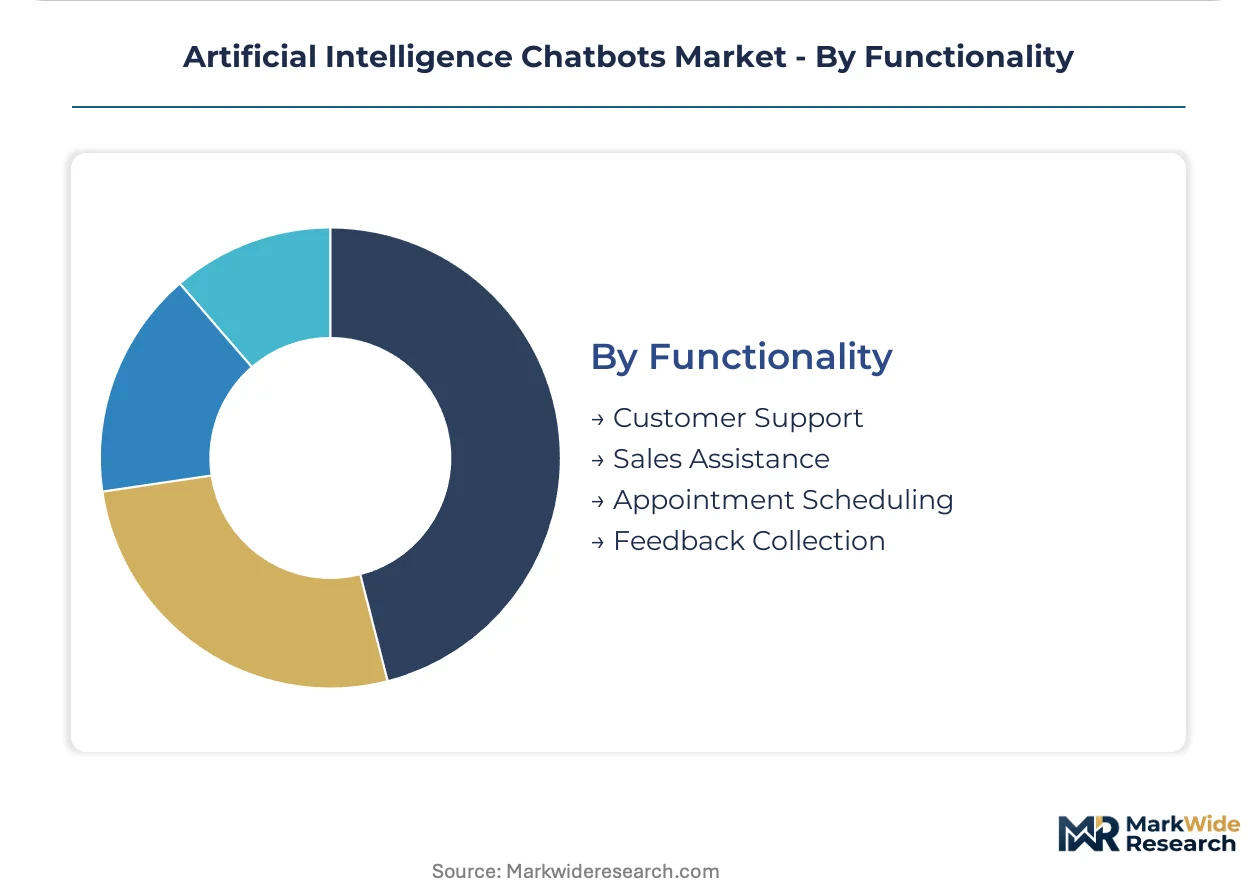
Customer support dominates installed base; sales assistance shows the most rapid uptake as revenue teams pursue real-time engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software procurement committees concentrate in the United States, Germany, and India, where cloud infrastructure budgets and digital transformation mandates create the strongest vendor pull. Regulatory fragmentation across jurisdictions forces multi-national adopters to maintain parallel compliance frameworks.
United States
Healthcare systems and financial institutions drive enterprise chatbot deployment, with Mayo Clinic and JPMorgan Chase operating at-scale implementations. FDA oversight of diagnostic claims and SEC disclosure requirements shape vendor selection criteria. Silicon Valley clusters host the dominant foundation model providers, while New York Metro anchors financial services adoption.
Germany
Automotive suppliers and industrial manufacturers deploy conversational agents for technical support and supply chain coordination. KBA standards and EU AI Act conformity assessments impose documentation burdens that favor established vendors. Stuttgart and Munich industrial corridors concentrate deployment activity among Mittelstand exporters.
India
Unified Payments Interface integration and vernacular language support accelerate voice-first banking bot adoption in tier-two cities. RBI guidelines on digital payment security and data localization requirements shape procurement. Bangalore and Hyderabad technology hubs host domestic application developers serving regional banks.
United Kingdom
Financial services and public sector organizations pursue customer service automation amid contact center labor constraints. FCA conduct rules and GDPR enforcement through the Information Commissioner's Office create compliance complexity. London's fintech corridor drives real-time transaction assistance deployments.
Japan
Aging demographics and labor shortages push healthcare providers and retailers toward autonomous service agents. METI industrial policy and PMDA medical device classifications govern diagnostic chatbot claims. Tokyo-Osaka manufacturing belts pilot edge-deployed inference engines for quality control documentation.
Artificial Intelligence Chatbots Market Competitive Landscape
Player mix skews toward hyperscale cloud providers with proprietary training infrastructure, creating a tiered structure where API-dependent application developers occupy subordinate positions. Foundation model access concentrates among three US-based entities with captive silicon and data center capacity. Strategic archetypes include vertically integrated infrastructure owners, horizontal platform specialists, and vertical-specific solution assemblers. Competitive moves center on embedding conversational capabilities within existing productivity suites and pursuing healthcare compliance certifications.
Within the hyperscale infrastructure tier, Microsoft and Google exemplify platform consolidation strategies, embedding conversational agents across cloud productivity ecosystems. Anthropic occupies a distinct position emphasizing constitutional AI principles for regulated industry penetration. These three entities anchor the supplier power asymmetry that shapes pricing and access terms for downstream developers.
| Leading Market Players |
|---|
| Anthropic (Claude AI) |
| Kore.ai |
| OpenAI (ChatGPT) |
| Cognigy |
| Yellow.ai |
| Google (Gemini) |
| Perplexity AI |
| LeewayHertz |
| Microsoft (Copilot) |
| Others |
Pricing and Supply Chain Analysis
ISO/IEC 42001 certification requirements simultaneously gate supply qualification and stratify price tiers, forcing vendors to absorb six-to-twelve-month audit costs while buyers pay premiums for governance-audited deployments in healthcare and financial services.
Pricing Analysis
Cost-plus contracts with NVIDIA GPU indexation dominate training infrastructure procurement, while downstream application vendors operate on SaaS-tiered subscriptions pegged to token consumption volumes. Price differentiation hinges on ISO/IEC 42001 certification grade and vertical integration depth into proprietary training infrastructure. Cost compression in mid-market cloud API tiers is intensifying because hyperscale providers are absorbing inference margin erosion to capture enterprise distribution channels. Mid-market healthcare clinics exhibit highest price sensitivity; defense contractors with air-gapped mandates show lowest.
Supply Chain Analysis
Taiwan and South Korea anchor advanced semiconductor fabrication for AI accelerators, while the United States concentrates hyperscaler data center capacity and proprietary model development. Foundry output draws from TSMC's N3E process nodes and HBM3 memory stacks from SK Hynix. Single-source vulnerability around NVIDIA GPU supply creates procurement bottlenecks for training clusters. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams with embedded security certification frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
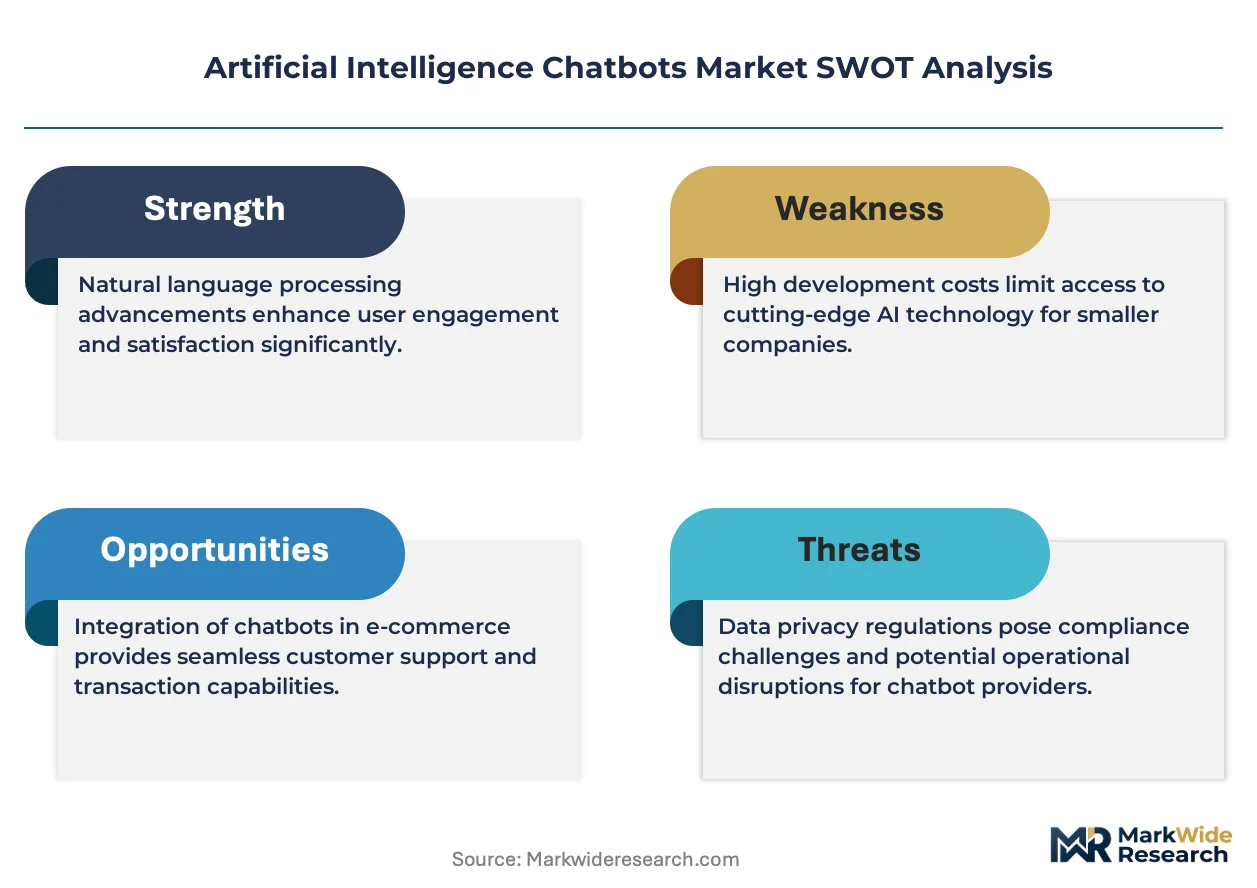
Foundation model commoditization threatens application-layer margins as enterprises consolidate around embedded productivity suite offerings, forcing specialized vendors to defend substitution risk from horizontal platform consolidation.
For Market Incumbents: Fortify proprietary training data moats through exclusive healthcare and financial services corpus licensing, while accelerating ISO/IEC 42001 certification pipelines to preempt procurement committee requirements. Vertical integration into captive silicon design—Google's TPU and Amazon's Trainium exemplars—reduces API dependency tax exposure. Channel control through pre-existing Workspace and Office 365 embedding remains the critical defensive lever against horizontal substitution.
For New Entrants and Emerging Players: Vernacular voice-first banking in India's tier-two cities represents an underserved service layer where UPI integration and Hindi-Tamil-Telugu language support outpace hyperscaler roadmap priorities. White-space targets include diagnostic chatbots with patient-submitted visual symptom analysis and automated ESG data collection agents for CSRD disclosure workflows. Go-to-market leverage rests on rapid connector development for fragmented enterprise knowledge bases rather than benchmark performance claims.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical specialists possessing pre-established FDA 510(k) pathways or EMA medical device classifications but lacking foundation model autonomy. Long-term viability favors platforms with embedded distribution through existing productivity suites rather than standalone application vendors facing API dependency asymmetry. Watch NVIDIA GPU supply allocation announcements as inflection signals for downstream margin compression severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Constitutional AI Certification | Anthropic's governance framework opens regulated healthcare procurement previously closed to general-purpose systems. |
| Edge Inference Engine Deployment | Automotive suppliers and hospital networks pilot on-premise quality control documentation bypassing cloud latency constraints. |
| Multimodal Diagnostic Integration | Synthesis of patient-submitted imagery with symptom descriptions creates reimbursement pathways for clinical decision support. |
| Vernacular Voice Banking | UPI-integrated Hindi and Tamil agents capture tier-two city deposits ahead of incumbent branch network expansion. |
| ESG Data Collection Automation | CSRD disclosure mandates drive supply chain partner interface demand for sustainability reporting chatbots. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with healthcare CIOs deploying EHR-integrated triage systems, financial services CTOs evaluating conversational banking architectures, cloud infrastructure procurement officers managing token consumption budgets, and regulatory affairs leads navigating EU AI Act conformity assessments. Secondary validation drew from SEC hyperscaler capex disclosures, FDA 510(k) submission databases, EMA medical device guidance documents, and RBI digital payment security circulars. Bottom-up deployment counts and top-down enterprise software spend estimates were triangulated to anchor market sizing.
Across the analysis window, projections model technology segmentation by architecture type, deployment economics by infrastructure ownership, functional application by workflow automation depth, and vertical penetration by regulatory complexity tier. CAGRs were derived from logistic diffusion curves fitted to historical cloud API consumption trajectories and workforce automation substitution elasticities. Forecast inputs include contact center labor shortage severity indices and EU AI Act enforcement timeline assumptions.
Material uncertainties—NVIDIA GPU supply allocation shocks, foundation model capability leapfrogging, and fragmented state-level AI legislation in California and New York—sit outside the modeled envelope. Forecasts reflect documented assumptions about enterprise consolidation velocity and hyperscaler embedding strategy execution. Recalibration cycles align with material shifts in regulatory enforcement intensity and training infrastructure cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
United States Conversational AI Market
Artificial Intelligence (AI)
Generative AI in Coding Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Global Conversational Systems Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
AI Code Assistant Market