
 Industrial AI Software Market | 2026-2036
Industrial AI Software Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial AI Software Market Insights
Multi-source procurement of AI inference hardware is hardening as manufacturers diversify beyond single chip vendors. NVIDIA Corporation dominates GPU supply for training workloads while SAP SE anchors enterprise software integration. IBM Corporation leverages hybrid cloud architectures to sustain competitive positioning in regulated industries.
Industrial AI software encompasses machine learning algorithms, computer vision systems, and predictive analytics platforms deployed to optimize physical production processes. These systems typically process sensor data at sub-second latency thresholds to enable automated decision-making on factory floors. Predictive maintenance commands the largest revenue pool as aging asset bases require failure forecasting, while edge computing deployments represent the fastest-expanding segment as latency constraints push inference closer to production lines. Process optimization retains mature margins in continuous manufacturing settings where throughput gains translate directly to energy savings.
The EU AI Act classifies industrial quality control systems as high-risk applications, mandating conformity assessments before market deployment. FDA oversight of AI-enabled medical device manufacturing imposes additional validation protocols on pharmaceutical producers adopting smart inspection systems. OSHA guidelines on human-robot collaboration shape automation interface requirements in US facilities. Stakeholders must monitor evolving liability frameworks governing autonomous decision-making in safety-critical industrial environments.
Market Dynamics
Machine learning inference at the edge is compressing decision latency from seconds to milliseconds, forcing software vendors to rearchitect deployment models and pricing structures around factory-floor hardware constraints rather than cloud-centric subscriptions.
Growth Catalysts
- EU AI Act compliance mandates:High-risk classification of quality control systems accelerates investment in validated, auditable software platforms across automotive and pharmaceutical manufacturing.
- Automotive defect detection:Stuttgart and Wolfsburg production clusters deploy computer vision systems to reduce warranty costs from paint and assembly anomalies.
- Predictive maintenance:Aging turbine and compressor fleets in process industries drive recurring software license demand for failure forecasting algorithms.
Market Restraints
- GPU supply concentration:Training workload dependence on single-vendor silicon creates procurement bottlenecks and price volatility for model development.
- Conformity assessment costs:EU AI Act mandatory third-party validation adds six-to-twelve month deployment delays and six-figure certification expenses per system.
- Edge hardware fragmentation:Proliferation of proprietary inference accelerators from Qualcomm, Intel, and ARM licensees complicates cross-platform software portability.
Strategic Opportunities
- India's PLI scheme:Electronics manufacturing incentives attract industrial AI software providers to Pune and Chennai industrial corridors for smartphone and component inspection.
- Digital twin convergence:Integration of physics simulation with real-time sensor analytics opens new subscription tiers for process optimization in chemical and steel production.
- OSHA human-robot collaboration guidelines:US facilities require new safety monitoring software for cobot deployments, creating compliance-driven demand for vision-based proximity detection.
Industry Challenges
- MLOps talent scarcity:Shortage of engineers capable of deploying production-grade model pipelines delays customer implementations and stretches professional services capacity.
- Legacy SCADA integration:Decades-old control systems in continuous manufacturing lack standardized data interfaces, requiring costly custom middleware development.
- Explainability requirements:EU AI Act mandated transparency for high-risk systems forces vendors to retrofit black-box deep learning models with interpretable output layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial AI Software Market |
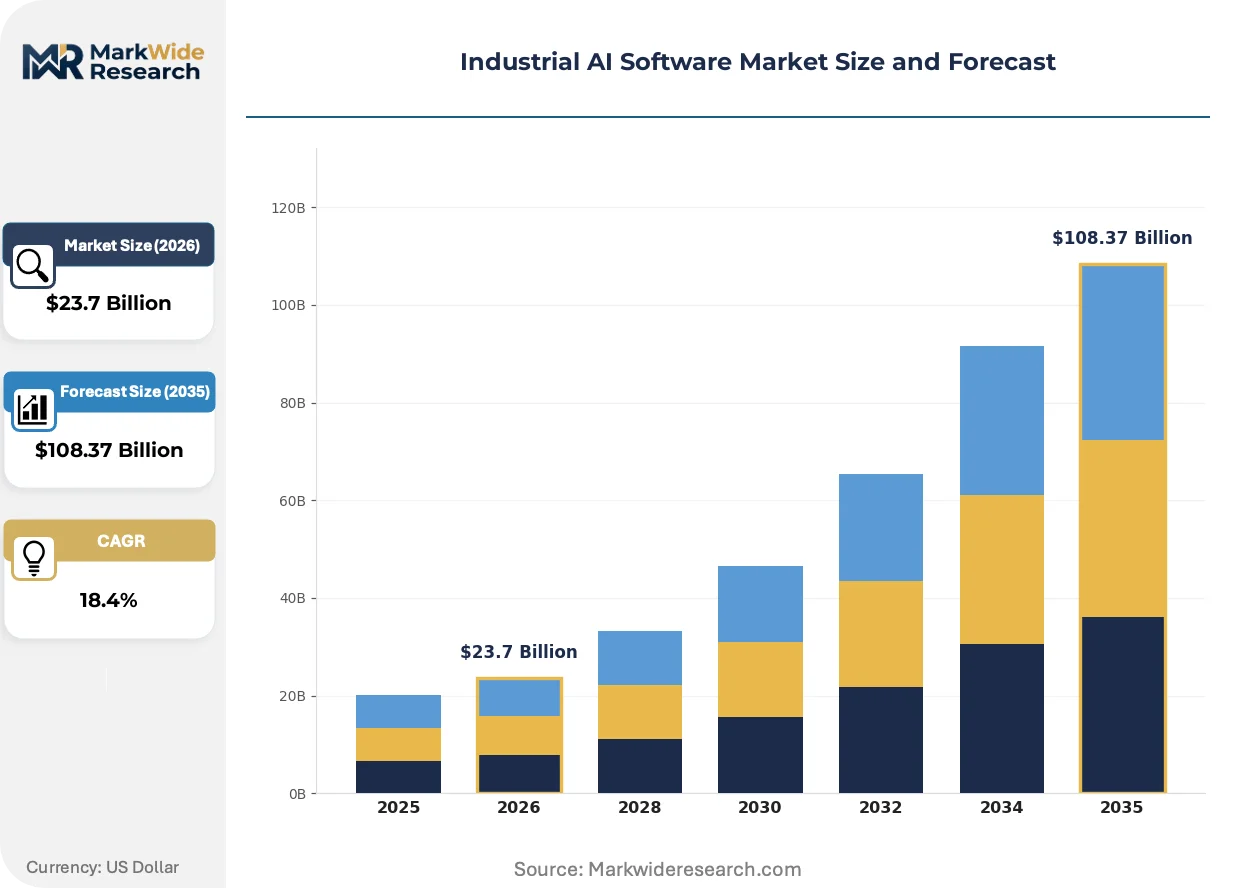
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $108.37 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Maintenance, Quality Control, Process Optimization, Supply Chain Management Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Edge Computing End User: Aerospace, Manufacturing, Oil & Gas, Automotive Functionality: Data Analysis, Machine Learning, Automation, Real-Time Monitoring |
| Companies Covered | IBM Corporation, Alphabet Inc., General Electric Company, Samsara, Amazon.com Inc., Rockwell Automation Inc., NVIDIA Corporation, Augury, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial AI Software Market Trends and Innovations
Federated learning architectures are redistributing model training across distributed factory sites, eliminating centralized data pooling while preserving proprietary process knowledge. This shift is compressing the traditional cloud-to-edge hierarchy that dominated industrial AI deployment through 2024.
Small language models optimized for industrial natural language processing are electrifying maintenance documentation analysis and operator query interfaces. Automotive manufacturers in Germany deploy these systems to parse multilingual equipment manuals and generate work orders without cloud connectivity. The technology is enabling real-time knowledge retrieval that previously required days of manual engineering review.
The EU AI Act's risk classification framework is mandating conformity assessments for quality control systems before market deployment. Pharmaceutical producers adopting smart inspection face additional FDA validation protocols for medical device manufacturing. High-risk system vendors are responding by building audit trails and human-in-the-loop overrides directly into software architecture.
Buyer procurement of industrial AI is consolidating around platform subscriptions that bundle edge runtime, model retraining, and regulatory documentation. System integrators and OEM channels are losing share to direct vendor relationships as manufacturers seek unified accountability for performance guarantees. This concentration is most visible in Germany's automotive supply chain, where procurement teams negotiate enterprise-wide licenses spanning Munich to Wolfsburg facilities.
Industrial AI Software Market Segmentation
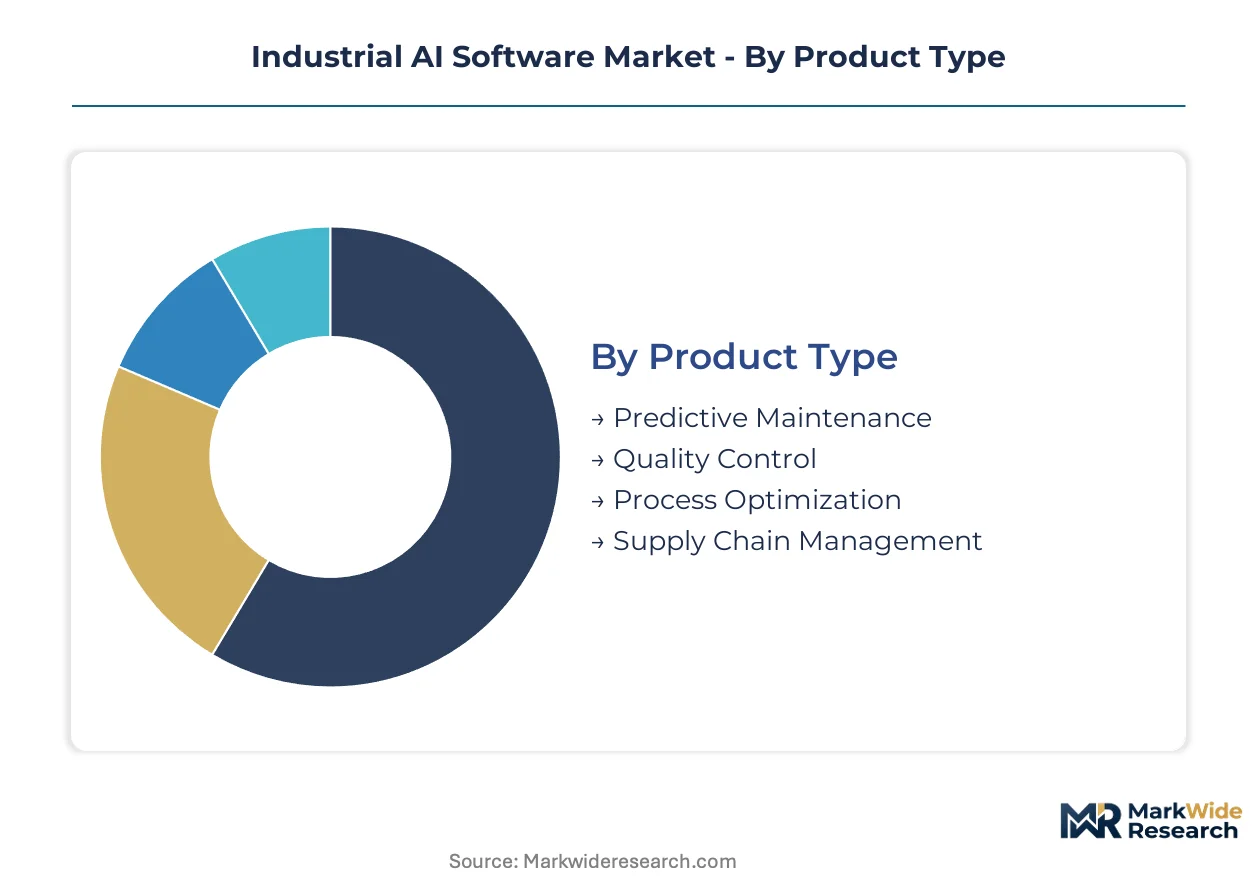
Industrial AI software purchasing decisions diverge sharply by operational context. Capital allocation patterns, latency requirements, and regulatory exposure reshape which segments command priority across automotive assembly lines, chemical plants, and aerospace facilities.
Product Type:
Capital intensity varies dramatically across software categories, with predictive maintenance platforms demanding the heaviest upfront investment in sensor infrastructure and historical failure data integration.
- Predictive Maintenance:Algorithms ingest vibration, thermal, and acoustic sensor streams to forecast equipment degradation before functional failure. German automotive clusters in Stuttgart and Wolfsburg deploy these systems across aging press lines and paint shops, driven by warranty cost containment and EU AI Act documentation requirements for high-risk asset monitoring.
- Quality Control:Computer vision systems inspect surface defects, dimensional tolerances, and assembly completeness at production-line speeds. Pharmaceutical manufacturers face combined EU AI Act and FDA validation protocols, stretching deployment timelines and inflating software architecture costs for audit trail integration.
- Process Optimization:Continuous manufacturing settings deploy physics-informed neural networks to balance throughput against energy consumption.
- Supply Chain Management:Demand forecasting and logistics optimization modules integrate ERP data with external market signals.
Most installed capacity flows through Predictive Maintenance. Expansion is steepest in Quality Control.
Deployment:
Deployment architecture selection hinges on latency tolerance, data sovereignty constraints, and existing infrastructure amortization schedules.
- Edge Computing:Inference accelerators collocated with production equipment compress decision latency from seconds to milliseconds. Automotive manufacturers in Wolfsburg deploy vision systems directly on paint line PLCs, eliminating cloud round-trips for defect classification while satisfying EU AI Act data localization preferences.
- Hybrid Solutions:Training pipelines execute in cloud environments while inference runs on factory floors, balancing computational intensity against real-time constraints. Oil and gas operators favor this architecture for offshore platforms with intermittent satellite connectivity.
- On-Premises:Fully captive infrastructure serves defense-aerospace contractors and nuclear facilities with air-gapped security requirements.
- Cloud-Based:Pure SaaS deployments dominate pilot programs and non-critical analytics workloads.
Edge Computing claims the steepest expansion trajectory as latency requirements harden. Hybrid Solutions retain the largest installed base.
End User:
End-user verticals exhibit divergent procurement sophistication, with automotive and aerospace buyers negotiating enterprise-wide platform licenses while oil and gas favors point solutions.
- Automotive:Stuttgart and Munich production clusters source unified AI platforms spanning quality control, predictive maintenance, and human-robot collaboration safety systems. EU AI Act conformity assessments for high-risk welding and inspection applications concentrate vendor selection around audit-capable providers.
- Manufacturing:Discrete and process manufacturers outside automotive deploy modular solutions with shorter implementation cycles.
- Oil & Gas:Turbine and compressor fleet monitoring drives recurring license demand, though procurement fragments across regional operating companies.
- Aerospace:Defense contractors impose stringent security and traceability requirements that limit vendor pools.
Automotive channels the highest absolute spending. Manufacturing delivers the broadest addressable base.
Functionality:
Functional module selection tracks organizational data maturity, with real-time monitoring preceding predictive analytics in typical adoption sequences.
- Real-Time Monitoring:Dashboard and alert systems processing sensor streams at sub-second intervals form the foundational layer for subsequent AI augmentation. German industrial corridors deploy these systems as compliance infrastructure under EU AI Act high-risk system documentation mandates.
- Machine Learning:Supervised and unsupervised model pipelines enable pattern recognition in unstructured operational data. MLOps talent scarcity constrains deployment velocity across all geographies.
- Data Analysis:Descriptive and diagnostic analytics modules support root-cause investigation without predictive capability.
- Automation:Closed-loop control systems integrating AI inference with actuation hardware.
Real-Time Monitoring saturates the installed base. Machine Learning is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping industrial AI deployment as manufacturers migrate development to jurisdictions with lighter compliance burdens. The EU AI Act's high-risk classification imposes six-figure certification costs that push pilot programs toward alternative locations. Germany's industrial corridor absorbs these costs for automotive quality control, while the United States and India capture edge computing experimentation.
United States
OSHA guidelines on human-robot collaboration drive safety monitoring software procurement for cobot deployments. FDA oversight of AI-enabled medical device manufacturing imposes validation protocols on pharmaceutical producers. Detroit and Austin production clusters deploy computer vision systems for automotive defect detection under lighter federal AI regulation than European counterparts.
Germany
Automotive defect detection systems reduce warranty costs from paint and assembly anomalies across Stuttgart and Wolfsburg production clusters. EU AI Act conformity assessments mandate third-party validation before market deployment, stretching timelines. Munich anchors enterprise software integration demand as SAP SE customers negotiate unified platform licenses spanning quality control and predictive maintenance.
China
MIIT standards for intelligent manufacturing accelerate domestic AI software adoption across Yangtze River Delta electronics producers. Dual carbon goals pressure steel and chemical plants to deploy process optimization for energy efficiency. Shenzhen and Shanghai industrial parks test federated learning architectures that preserve proprietary process knowledge without centralized data pooling.
India
PLI scheme electronics manufacturing incentives attract industrial AI providers to Pune and Chennai corridors for smartphone component inspection. CEA grid modernization mandates create demand for predictive maintenance on aging turbine infrastructure. Bangalore software development centers supply MLOps talent to global vendors facing implementation delays.
Japan
METI Society 5.0 initiatives fund digital twin convergence for chemical and steel production optimization. Aging asset bases in process industries drive recurring license demand for failure forecasting algorithms. Nagoya automotive suppliers deploy small language models for multilingual equipment manual parsing without cloud connectivity.
Industrial AI Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-native architectures and federated learning deployment models. The vendor base stratifies across cloud hyperscalers, industrial automation incumbents, and specialized AI chip designers. Strategic archetypes include training infrastructure providers, enterprise integration platforms, and vertical-specific predictive maintenance specialists. Competitive moves center on hybrid cloud partnerships and regulatory documentation bundling.
Within the enterprise integration tier, IBM Corporation and SAP SE exemplify hybrid cloud positioning for regulated industries. NVIDIA Corporation anchors training workload supply. Alphabet Inc. represents cloud-native AI service expansion. These three occupy positions that reflect divergent bets on centralized versus distributed computing architectures.
| Leading Market Players |
|---|
| IBM Corporation |
| Alphabet Inc. |
| General Electric Company |
| Samsara |
| Amazon.com Inc. |
| Rockwell Automation Inc. |
| NVIDIA Corporation |
| Augury |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM procurement teams in Germany's industrial corridor negotiate enterprise-wide platform licenses that bundle edge runtime, model retraining, and EU AI Act compliance documentation into unified subscription tiers.
Pricing Analysis
Distributor margins for industrial AI software compress as manufacturers shift toward direct vendor relationships. Three-tier pricing structure across premium, standard, and economy levels separates validated high-risk system vendors from pilot-stage entrants. Cost compression in the standard tier intensifies because GPU supply concentration forces training workload vendors to absorb silicon procurement volatility. Small and mid-sized discrete manufacturers exhibit the highest price sensitivity, while automotive OEMs prioritize audit-capable providers over unit cost.
Supply Chain Analysis
Regional distribution centers for AI inference hardware cluster near Stuttgart, Munich, and Wolfsburg to serve just-in-time automotive deployments. Supply concentrates in Taiwan for GPU fabrication, the United States for training infrastructure, and Germany for edge computing integration. Raw material dependencies span NVIDIA silicon, Qualcomm inference accelerators, and proprietary SAP enterprise connectors. Single-source vulnerability in GPU supply creates procurement bottlenecks for model development workloads. Distribution runs through system integrator channels that are losing share to direct OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial AI software market functions as a stable compounder, with EU AI Act compliance mandates locking in recurring platform subscriptions across automotive and pharmaceutical manufacturing.
For Market Incumbents: Deploy regulatory documentation bundling to deepen customer switching costs. SAP SE and IBM Corporation should expand hybrid cloud partnerships that unify edge runtime with cloud training pipelines. NVIDIA Corporation must secure multi-year foundry agreements to deflect emerging entrant challenges from AMD and Intel. Certification investment in EU AI Act conformity assessment capabilities separates sustainable vendors from pilot-stage competitors. For New Entrants and Emerging Players: Capture India's PLI scheme electronics manufacturing corridors in Pune and Chennai, where smartphone component inspection demand outstrips validated vendor supply. Target federated learning deployment models that preserve proprietary process knowledge without centralized data pooling. Partner with Bangalore MLOps talent pools to overcome implementation delays that stall incumbent professional services capacity. For Investors and Strategic Acquirers: Industrial automation incumbents are the most active acquirer in this space, seeking edge-native AI capabilities to complement legacy control systems. The market supports a 5-10 year compounder thesis driven by regulatory compliance recurring revenue and aging asset base predictive maintenance demand. Target acquisition archetypes include vertical-specific predictive maintenance specialists with proven FDA or EU AI Act validation track records. Watch for MLOps talent scarcity easing as a signal that implementation velocity constraints are lifting.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified edge-cloud runtime bundles satisfy EU AI Act audit trail requirements for automotive OEMs. |
| Regulatory Documentation Bundling | Pre-validated conformity assessment packages reduce six-to-twelve month deployment delays for pharmaceutical producers. |
| Backward Integration into Inference Silicon | In-house accelerator design insulates margins from NVIDIA supply concentration and price volatility. |
| Federated Learning Deployment | Distributed model training preserves proprietary process knowledge for chemical and steel manufacturers in Shenzhen and Shanghai. |
| Geographic Expansion to India PLI Corridors | Pune and Chennai electronics manufacturing incentives attract smartphone component inspection providers. |
Research Methodology
Direct dialogue with CTOs, plant engineers, OEM procurement teams, and MLOps specialists grounded the qualitative assessment, combined with secondary validation across SEC filings, hyperscaler capex disclosures, EU AI Act regulatory texts, and automotive production databases. Bottom-up and top-down triangulation reconciled vendor-reported deployment metrics with end-user procurement patterns across Germany's industrial corridor and US automotive clusters.
Segmentation outputs across deployment model, organization size, vertical application, and regional adoption pattern were modeled throughout the forecast period. CAGRs derived from historical license growth rates, edge computing hardware shipment trajectories, and regulatory compliance spending patterns across automotive and pharmaceutical manufacturing.
GPU supply disruption, EU AI Act enforcement variance, and MLOps talent availability are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
Edge AI Software Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Cognitive Collaboration Market
Artificial Intelligence (AI)
AI in Project Management Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market
Artificial Intelligence (AI)
North America Chatbot Market
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
AI Voice Cloning Market