
 Incense Sticks (Agarbatti) Market | 2026-2036
Incense Sticks (Agarbatti) Market Size, Share, and Industry Trends Forecast 2026-2036
Incense Sticks (Agarbatti) Market Foresight
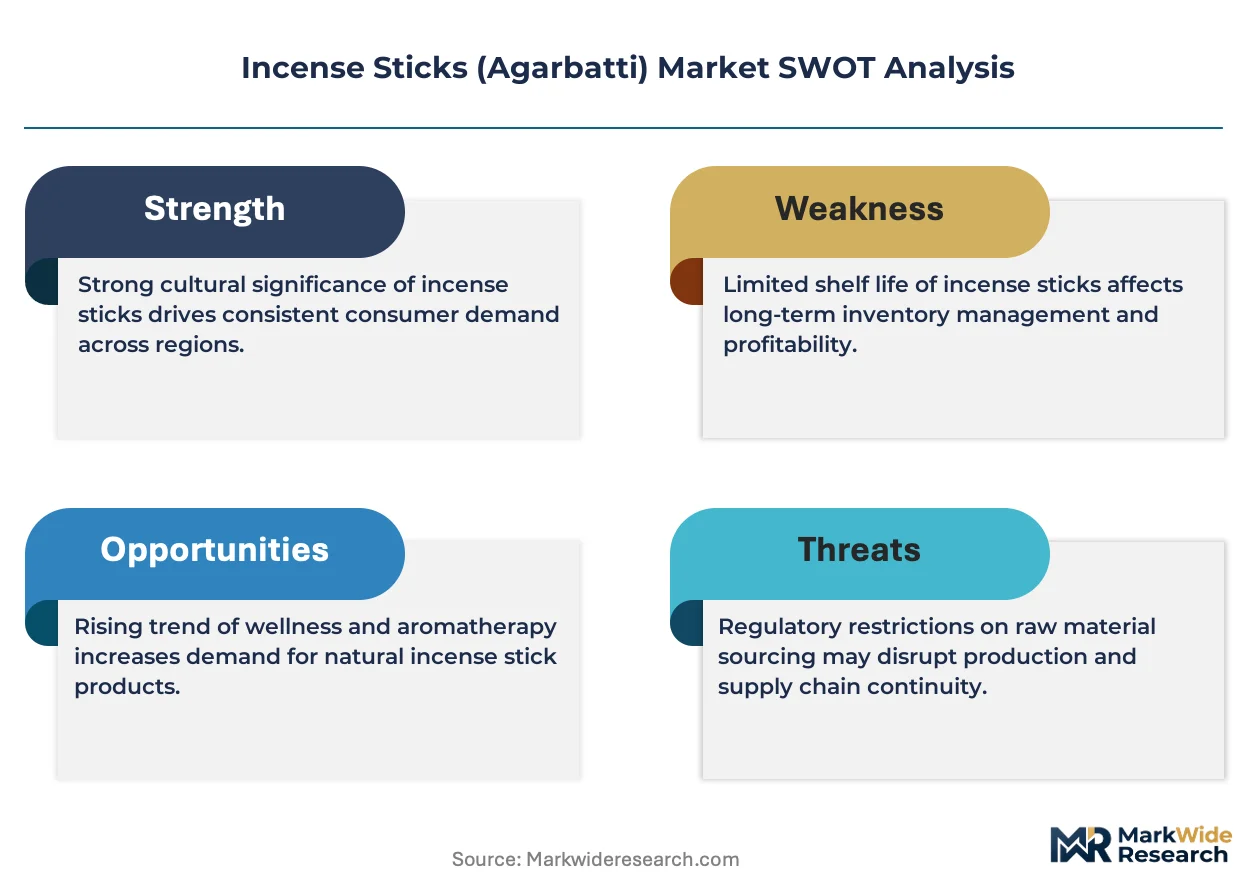
Natural bamboo charcoal is decoupling from traditional wood-powder cores across premium agarbatti lines, lowering particulate emissions while preserving burn consistency. ITC Limited (Mangaldeep) leverages its rural distribution network to sustain penetration in India's tier-three towns. N. Ranga Rao & Sons (Cycle) anchors South Indian brand loyalty through temple-channel exclusivity. Hem Agarbatti competes on price in North India's unorganized wholesale corridors.
Incense sticks (agarbatti) are thin cylindrical products comprising a combustible bamboo stick coated with aromatic paste of charcoal powder, binding gums, and fragrance oils, burned to release scented smoke for religious, meditative, or ambient purposes. The natural segment leads value contribution as consumers reject synthetic phenyl ethyl alcohol bases, while herbal variants containing tulsi and neem extracts represent the fastest-growing fringe due to wellness-center procurement. Household end users dominate volume, though religious institutions command superior per-unit margins through customized bulk packaging and ceremonial-grade formulations.
India's BIS mandates aromatic content disclosure under fragrance standards, while the EU REACH framework restricts synthetic musk imports into European wellness retail, shaping export compliance costs for Indian manufacturers. The US EPA regulates particulate emissions from combustible home products, creating testing barriers for charcoal-heavy formulations. Stakeholders must monitor evolving chemical disclosure regimes across their priority export corridors to preempt formulation redesign cycles.
Market Dynamics
India's BIS certification tightening for aromatic chemicals is compressing formulation margins while forcing supply chain consolidation among mid-tier manufacturers unable to absorb testing costs.
Growth Catalysts
- Temple economy expansion:Religious institutions across South Asia are scaling ceremonial-grade procurement volumes, with customized bulk packaging commanding premium unit economics.
- REACH framework adaptation:Indian exporters redesigning synthetic musk formulations to maintain European wellness retail access, creating compliance-driven product differentiation.
- Natural bamboo charcoal substitution:Premium agarbatti lines are decoupling from wood-powder cores, lowering particulate emissions while preserving burn consistency for wellness-center buyers.
Market Restraints
- Raw material cost volatility:Bamboo stick and natural gum prices fluctuate with monsoon-dependent harvest cycles across India's northeastern states.
- Supply concentration risk:Charcoal powder sourcing clusters in Karnataka and Tamil Nadu create geographic vulnerability to regional logistics disruptions.
- Substitution pressure:Electric aroma diffusers and ultrasonic oil vaporizers are capturing ambient scent demand in urban Indian households.
Strategic Opportunities
- Bangladesh volume penetration:Underdeveloped organized retail channels present first-mover advantages for branded agarbatti distribution networks.
- Herbal wellness convergence:Tulsi and neem extract formulations are capturing procurement contracts from yoga studios and ayurvedic centers.
- EU Green Deal alignment:Carbon-neutral certification pathways for natural-core products open premium positioning in European specialty retail.
Industry Challenges
- Skilled fragrance compounding shortage:Master perfumers with traditional attar knowledge are aging out without structured apprenticeship pipelines.
- BIS testing timeline compression:Aromatic content disclosure mandates require 12-18 month reformulation cycles that outpace seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incense Sticks (Agarbatti) Market |
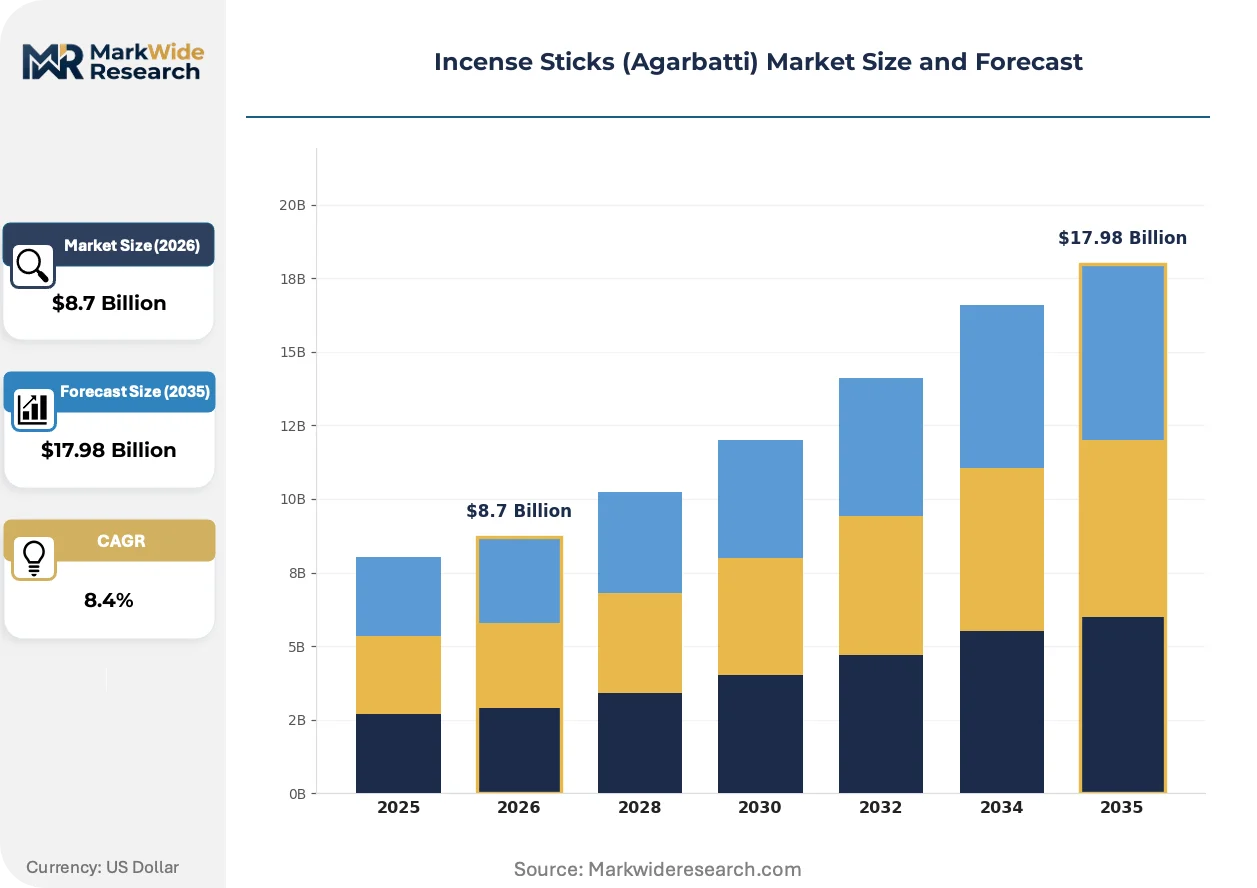
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Herbal, Charcoal End User: Household, Religious Institutions, Wellness Centers, Retail Shops Fragrance Type: Floral, Woody, Spicy, Fruity Packaging Type: Boxes, Bags, Tins, Bulk |
| Companies Covered | ITC Limited (Mangaldeep), Hem Agarbatti, Nippon Kodo Co., Ltd., N. Ranga Rao & Sons (Cycle), Hari Darshan Agarbatti, Baieido Co., Ltd., Satya (Shrinivas Sugandhalaya), Mysore Sandal (KSDL), Shoyeido Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incense Sticks (Agarbatti) Market Shifts & Advancements
Formulation transparency and combustion chemistry are displacing opaque ingredient lists across both religious and wellness consumption channels, reshaping how manufacturers communicate product credentials.
Automated bamboo stick sorting and coating lines are automating quality consistency across high-volume production facilities. Tier-one manufacturers deploying these systems achieve defect-rate reductions that manual inspection cannot match. The capital barrier is compressing competitive differentiation toward firms with balance-sheet capacity for continuous equipment refresh.
India's BIS fragrance standards mandate aromatic content disclosure on all packaged agarbatti products, eliminating proprietary formulation opacity. Manufacturers must now submit detailed chemical profiles for certification approval, extending product development timelines. Export-oriented firms are responding by establishing in-house analytical laboratories to preempt regulatory rejection cycles.
Wellness-center procurement officers are consolidating vendor relationships around certified herbal formulations, displacing fragmented household-brand purchasing. Single-source contracts with guaranteed tulsi and neem traceability are replacing opportunistic spot buying. This concentration is most visible in South Indian metropolitan clusters where ayurvedic service density supports dedicated supply agreements.
Incense Sticks (Agarbatti) Market Segmentation
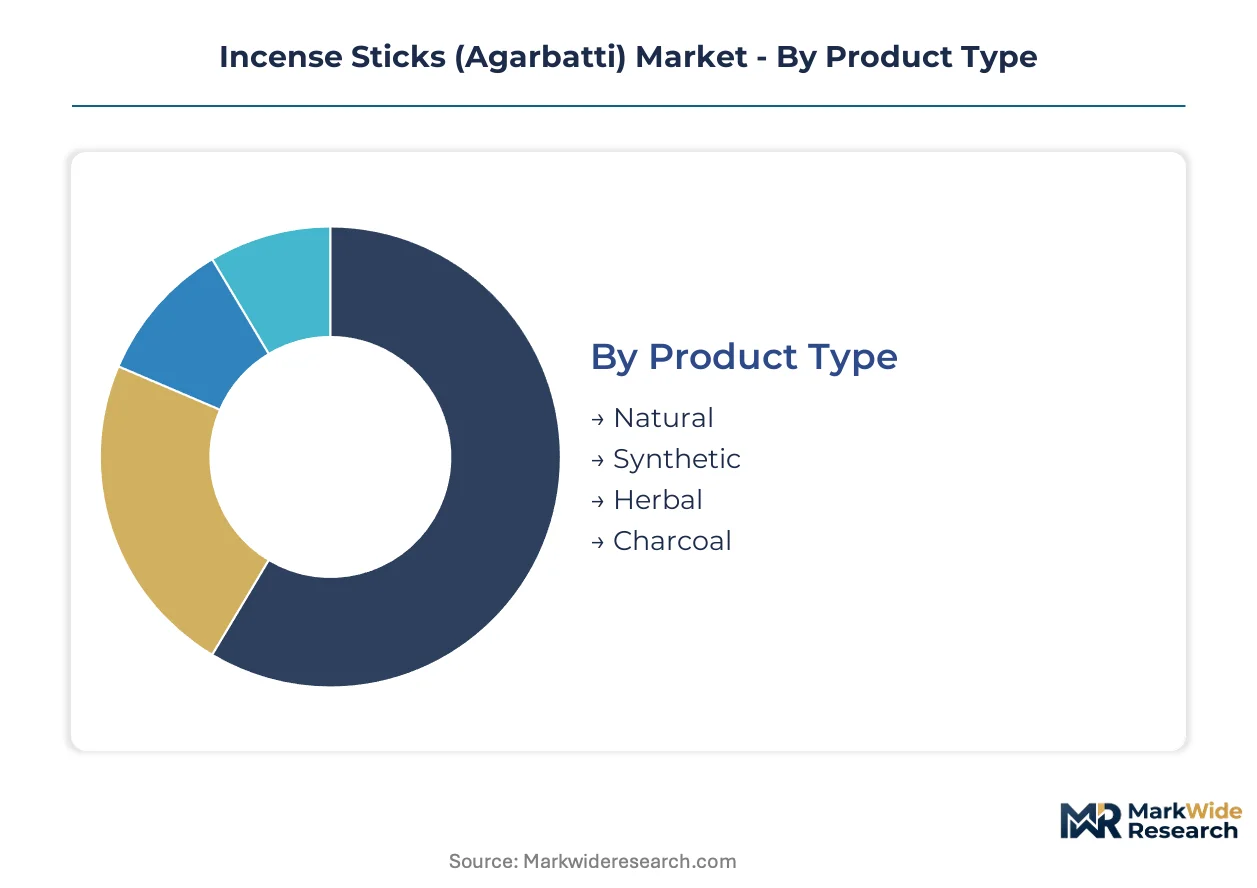
Segmentation in the agarbatti market determines pricing power, distribution channel selection, and regulatory compliance burden. Manufacturers must align production configurations with distinct demand profiles across ceremonial, wellness, and ambient scent applications.
Product Type:
Customization intensity varies sharply across this category, from commodity-grade synthetic formulations to precision-crafted natural cores requiring traceable supply chains.
- Natural:Bamboo charcoal cores coated with plant-derived binding gums and essential oil fragrances command premium positioning in temple and wellness channels. India's BIS aromatic content disclosure mandates have intensified scrutiny of natural claim authenticity, forcing manufacturers to maintain batch-level documentation.
- Synthetic:Phenyl ethyl alcohol and synthetic musk bases deliver cost-competitive burn performance for mass-market household consumption. REACH framework restrictions on synthetic musk imports into European wellness retail are compressing export viability for this segment.
- Herbal:Tulsi and neem extract formulations are gaining procurement traction from ayurvedic service providers.
- Charcoal:Traditional wood-powder cores face particulate emission scrutiny under US EPA combustible home product regulations.
Most installed capacity flows through Natural. Expansion is steepest in Herbal.
End User:
Volume concentration and margin extraction diverge dramatically across customer types, with ceremonial procurement commanding structural premiums over fragmented household purchasing.
- Household:Fragmented individual consumers purchasing through kirana stores, modern retail, and e-commerce platforms generate baseline volume throughput. Price sensitivity dominates, with brand loyalty concentrated around sensory familiarity rather than certification credentials.
- Religious Institutions:Temples, mosques, and gurudwaras across South Asia procure ceremonial-grade agarbatti in customized bulk packaging with guaranteed burn duration specifications. Per-unit margins exceed household channels significantly due to formulation precision requirements and dedicated supply relationships.
- Wellness Centers:Yoga studios and ayurvedic clinics are consolidating vendor relationships around certified herbal formulations with guaranteed ingredient traceability.
- Retail Shops:Kirana stores and specialty fragrance retailers serve as last-mile distribution infrastructure, with inventory decisions driven by turnover velocity and local preference patterns.
Volume concentrates in Household. Margin extraction peaks in Religious Institutions.
Fragrance Type:
Regional olfactory preference maps directly onto formulation specialization, with geographic clustering of master perfumers shaping competitive differentiation.
- Floral:Rose, jasmine, and mogra bases dominate South Indian temple procurement and festival retail cycles. Karnataka and Tamil Nadu fragrance compounding clusters maintain formulation expertise concentration for this category.
- Woody:Sandalwood and agarwood profiles command premium positioning in Middle Eastern export corridors and North Indian ceremonial consumption. Raw material scarcity is forcing substitution toward synthetic analogs in mass-market lines.
- Spicy:Cinnamon, clove, and cardamom formulations align with winter seasonality and specific religious observances.
- Fruity:Citrus and berry profiles are capturing younger demographic preference in urban ambient scent applications.
Production gravity centers on Floral. Steepest expansion trajectory belongs to Woody in premium wellness channels.
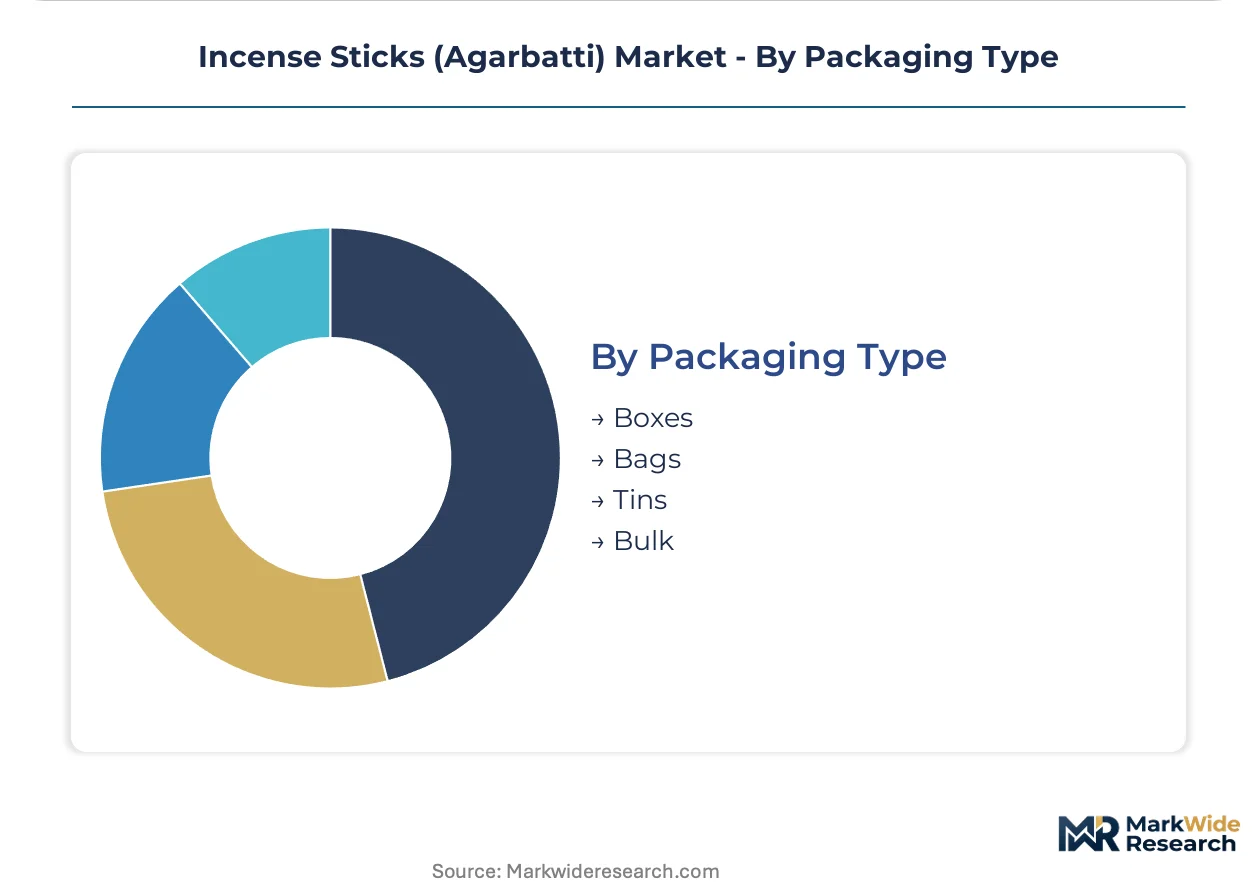
Packaging Type:
Unit economics and distribution reach are shaped by packaging format selection, with bulk ceremonial procurement operating on fundamentally different cost structures than branded retail presentation.
- Boxes:Rigid paperboard packaging with fragrance-retention laminations dominates modern retail and gift segment positioning. BIS labeling mandates for aromatic content disclosure have standardized box panel information architecture.
- Bags:Flexible polypropylene and paper pouches deliver cost-efficient containment for high-frequency household replenishment cycles.
- Tins:Metal containment provides moisture protection and premium shelf presence for specialty fragrance lines and export consignments.
- Bulk:Unpackaged or loosely bundled agarbatti serves temple economy procurement and wholesale redistribution, minimizing per-unit packaging cost to maximize material value capture.
Throughput concentrates in Bags. Value per unit peaks in Tins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mysuru anchors South India's agarbatti manufacturing concentration, with Karnataka's fragrance compounding clusters supplying ceremonial-grade formulations to temple economies across India, Bangladesh, and Sri Lanka. Regional demand patterns diverge sharply between religious institutional procurement and wellness-center contracting.
India
Temple economies in Tamil Nadu and Karnataka drive ceremonial-grade volume procurement with customized bulk packaging requirements. India's BIS mandates aromatic content disclosure under fragrance standards, compressing product development timelines for domestic manufacturers. Bangalore and Mysuru host the densest concentration of natural bamboo charcoal processing facilities serving premium agarbatti lines.
Bangladesh
Religious institutions in Dhaka and Chittagong are scaling agarbatti consumption for Islamic and Hindu ceremonial observances. The country's national standards body is evaluating alignment with Indian BIS disclosure requirements for cross-border trade facilitation. Underdeveloped organized retail channels in secondary cities present first-mover distribution opportunities for branded entrants.
Sri Lanka
Buddhist temple networks in Colombo and Kandy sustain steady ceremonial consumption with preference for sandalwood and jasmine fragrance profiles. Import regulations administered by the country's consumer affairs authority require chemical composition documentation for aromatic product categories. Coastal processing zones around Galle are emerging as packaging and redistribution nodes for Indian-manufactured products.
Japan
Wellness-center procurement in Tokyo and Osaka favors low-emission natural-core formulations for meditation and ambient scent applications. METI standards for indoor air quality influence combustible home product import criteria, creating testing barriers for charcoal-heavy agarbatti. Kyoto-based traditional fragrance houses maintain expertise in agarwood and sandalwood compounding for ceremonial incense categories.
United States
Ayurvedic service providers in California and New York are consolidating vendor relationships around certified herbal agarbatti with guaranteed ingredient traceability. The US EPA regulates particulate emissions from combustible home products, requiring reformulation of wood-powder core products for wellness retail compliance. Los Angeles and Miami host the largest concentrations of South Asian diaspora demand driving specialty fragrance retail.
Incense Sticks (Agarbatti) Market Competitive Landscape
Capacity expansion dominates the current landscape as tier-one manufacturers deploy automated bamboo stick sorting and coating lines to achieve defect-rate reductions. The vendor base fragments across three tiers: integrated conglomerates with rural distribution networks, family-owned specialists with temple-channel exclusivity, and price-competitive wholesalers serving unorganized retail corridors. Two strategic archetypes define competitive positioning: fragrance compounding specialists leveraging traditional attar knowledge, and scale-driven operators optimizing unit economics through process automation. Geographic expansion into Bangladesh and Sri Lanka, alongside portfolio diversification into herbal wellness formulations, represent the dominant competitive moves.
Among India-based integrated conglomerates, ITC Limited (Mangaldeep) exemplifies the rural distribution archetype, while N. Ranga Rao & Sons (Cycle) occupies a position within the temple-channel specialist tier. Hem Agarbatti represents the price-competitive wholesale archetype serving North India's unorganized retail corridors. These three anchors illustrate the structural segmentation between premium ceremonial positioning, mass-market penetration, and unorganized corridor supply.
| Leading Market Players |
|---|
| ITC Limited (Mangaldeep) |
| Hem Agarbatti |
| Nippon Kodo Co., Ltd. |
| N. Ranga Rao & Sons (Cycle) |
| Hari Darshan Agarbatti |
| Baieido Co., Ltd. |
| Satya (Shrinivas Sugandhalaya) |
| Mysore Sandal (KSDL) |
| Shoyeido Co., Ltd. |
| Others |
Supply & Pricing Matrix
Automated bamboo stick sorting and coating lines are compressing unit economics at tier-one facilities while concentrating production capacity among balance-sheet-strong manufacturers capable of continuous equipment refresh. This capital-intensity shift simultaneously raises quality consistency thresholds and widens cost-performance spreads between mechanized and manual production tiers.
Pricing Analysis
Input-cost pass-through from bamboo stick and natural gum harvest volatility in India's northeastern states runs through to finished-product pricing, with monsoon-dependent supply cycles creating predictable seasonal pressure points. Three-tier pricing structure across premium natural-core, standard synthetic-base, and economy charcoal-heavy tiers separates temple-economy ceremonial procurement from mass-market household replenishment. Cost compression in synthetic formulations is intensifying because REACH-compliant musk substitution raises European export compliance burdens. Household consumers through kirana channels exhibit highest price sensitivity, while religious institutions purchasing customized bulk ceremonial grades accept premium positioning.
Supply Chain Analysis
India's BIS aromatic content disclosure mandates are reshaping sourcing priorities toward batch-traceable natural gum and essential oil suppliers capable of documentation compliance. Geographic supply concentration clusters in Karnataka and Tamil Nadu for charcoal powder processing, with bamboo stick cultivation anchored in northeastern Indian states and Bangladesh border regions. Raw material dependencies rest on monsoon-sensitive bamboo harvests, Karnataka-Tamil Nadu charcoal processing capacity, and Kerala-Tamil Nadu fragrance compounding expertise. Single-source vulnerability around charcoal powder processing creates geographic concentration risk. Distribution runs through temple-channel exclusivity arrangements, modern retail box formats, and kirana store flexible pouch replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification timeline compression against Bangladesh's underdeveloped standards enforcement creates a regulatory arbitrage window for formulation-export positioning. Cost differentials between Indian analytical laboratory investment requirements and Bangladeshi cross-border trade facilitation favor phased geographic sequencing.
For Market Incumbents: Cement temple-channel exclusivity through multi-year ceremonial-grade supply contracts with guaranteed burn-duration specifications before synthetic substitution and electric diffuser penetration erode religious institutional volume. Defend margin position by captive supply of natural bamboo charcoal processing capacity in Karnataka clusters, insulating against raw material cost volatility that manual competitors cannot absorb. Prioritize in-house analytical laboratory certification to preempt BIS rejection cycles that delay seasonal product launches. For New Entrants and Emerging Players: Launch via direct wellness-center contracting in South Indian metropolitan clusters where ayurvedic service density supports single-source herbal formulation agreements with guaranteed tulsi and neem traceability. Target Bangladesh's underdeveloped organized retail channels in secondary cities before branded distribution networks consolidate shelf access. Exploit herbal wellness convergence through certified natural-core positioning that commands premium extraction unavailable in synthetic mass-market competition. For Investors and Strategic Acquirers: Valuations sit cheapest among family-owned fragrance compounding specialists with traditional attar knowledge but aging master perfumer benches and no structured apprenticeship pipelines. Long-term viability over the coming decade hinges on successful capability transfer to automated quality systems and regulatory compliance infrastructure. Acquisition target archetype: South Indian temple-channel specialists with established ceremonial-grade relationships and underutilized natural-core production capacity. Watch for BIS timeline compression forcing mid-tier manufacturer distressed exits as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bamboo Charcoal Processing | Karnataka facility ownership secures supply continuity against monsoon harvest volatility. |
| EU Green Deal Certification Pathway | Carbon-neutral natural-core positioning unlocks premium European specialty retail access. |
| Temple-Channel Multi-Year Supply Contracting | Ceremonial-grade exclusivity arrangements lock in structural margin premiums over household channels. |
| In-House Analytical Laboratory Investment | BIS aromatic content disclosure compliance accelerates product development timelines versus outsourced testing. |
| Herbal Wellness Formulation Extension | Tulsi and neem extract variants capture yoga studio and ayurvedic center procurement consolidation. |
Research Methodology
Direct dialogue with fragrance compounding masters, temple procurement officers, wellness-center contracting managers, and BIS certification auditors grounded qualitative assessment in operational reality. Secondary validation drew from customs trade records for aromatic chemical imports, BIS fragrance standard publications, Karnataka and Tamil Nadu state industrial development corporation filings, and EU REACH restriction updates. Bottom-up volume estimates from installed production capacity triangulated against top-down demand aggregation across household, religious institutional, and wellness-center end-use segments.
Bottom-up modeling tracked production capacity by manufacturing tier across Mysuru, Bangalore, and Tamil Nadu clusters, while top-down assessment aggregated end-use demand through festival retail cycle analysis and temple economy procurement patterns. Segmentation dimensions spanned product type, end user, fragrance profile, and packaging format across the projection horizon. CAGRs derived from elasticity-adjusted volume trajectories responding to regulatory compliance cost pass-through and substitution pressure from electric aroma diffusers. Industry-specific inputs included monsoon-indexed bamboo harvest forecasts and BIS certification pipeline timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended monsoon disruption scenarios or accelerated BIS disclosure mandate expansion. Forecasts reflect documented assumptions regarding regulatory timeline adherence, raw material harvest stability, and wellness-center procurement consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Savoury Seasoning Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Pepper Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
Asafoetida Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Sichuan Peppercorn Market