
 US Antimicrobial Plastics Market | 2026-2036
US Antimicrobial Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
US Antimicrobial Plastics Market Outlook
Direct distribution from compounders to medical device OEMs is tilting toward specification-driven partnerships. DuPont de Nemours leverages its materials science portfolio to anchor long-term supply contracts with sterilization-sensitive buyers. Microban International differentiates through embedded antimicrobial technology licensing rather than resin sales alone. RTP Company specializes in custom compounding formulations that meet FDA device master file requirements for healthcare applications.
Antimicrobial plastics are polymer matrices infused with biocidal agents such as silver ions, copper salts, or quaternary ammonium compounds, manufactured through melt compounding or surface coating processes to achieve sustained microbial inhibition on contact surfaces. These materials serve primarily to reduce pathogen transmission in high-touch environments and extend product hygiene lifespan in regulated industries. Polypropylene dominates medical device applications due to its sterilization compatibility and processability into thin-wall injection molded components. Silver nanoparticle technology commands premium positioning in healthcare and food packaging segments where EPA registration and FDA compliance create barrier-protected margin pools. Organic compound additives compete on cost in consumer goods and household segments where regulatory stringency remains lower.
FDA device regulations and EPA antimicrobial pesticide registrations under FIFRA govern product claims, testing protocols, and market access for antimicrobial plastics in healthcare and consumer applications. OSHA workplace safety standards and state-level California Proposition 65 disclosure requirements further constrain formulation choices and labeling obligations. Stakeholders must monitor pending EPA reassessments of silver-based additives and evolving FDA guidance on antimicrobial device coatings to anticipate compliance cost shifts and reformulation timelines.
Market Dynamics
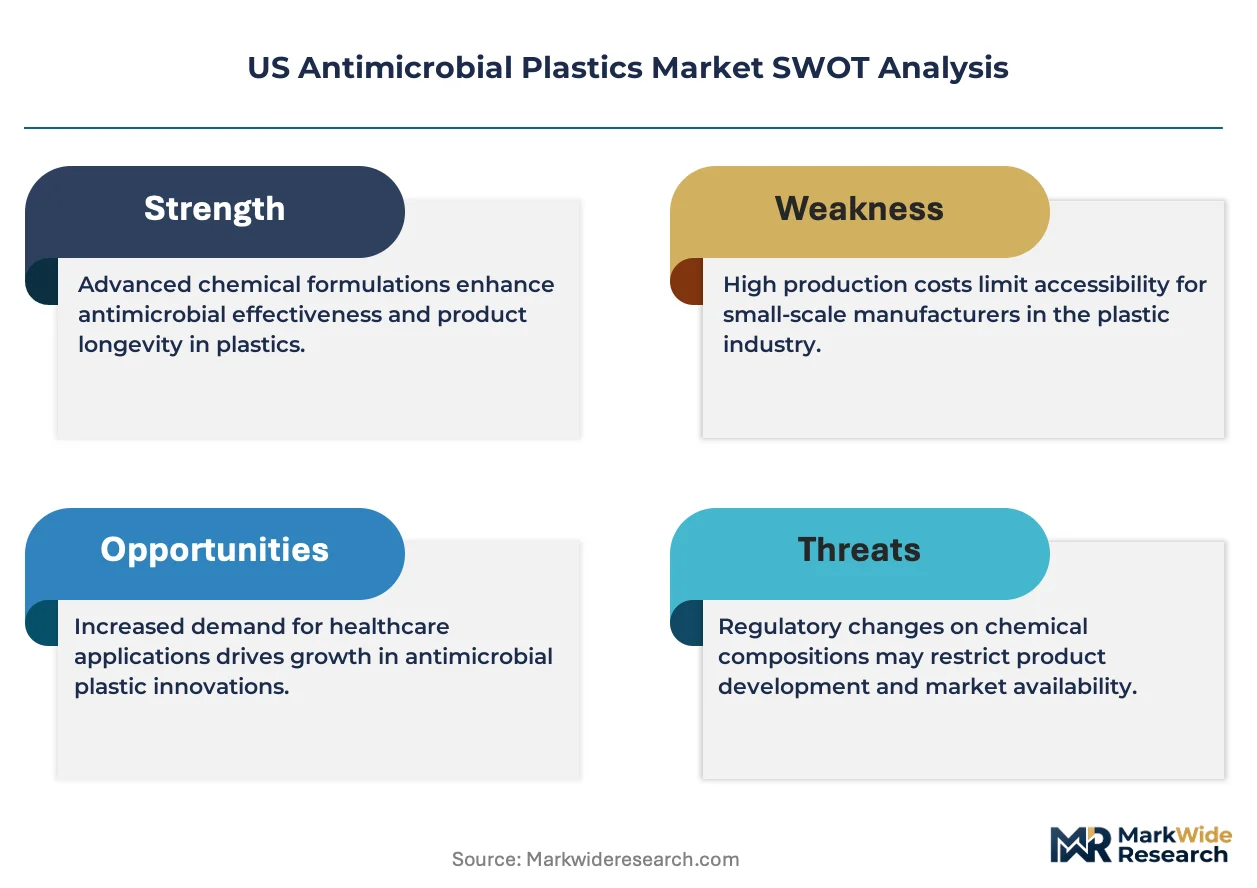
The EPA's reassessment of silver-based biocides under FIFRA is compressing formulation timelines and forcing compounders to validate alternative antimicrobial agents before registration pathways close.
Growth Catalysts
- Hospital-acquired infection prevention mandates:Joint Commission accreditation standards now explicitly reference antimicrobial surface performance in patient care zones, accelerating specification of silver-ion-infused polymers in bed rails, tray tables, and IV poles.
- Food Safety Modernization Act enforcement:FDA inspection protocols for food contact surfaces are driving meat and dairy processors toward copper-enhanced cutting boards, conveyor belts, and storage bins to reduce listeria and salmonella contamination vectors.
- California Proposition 65 disclosure alignment:Compounders reformulating to eliminate triclosan and certain quaternary ammonium compounds are capturing shelf space with compliant alternatives in West Coast medical device and consumer goods channels.
Market Restraints
- Silver price volatility:Nanoparticle silver feedstock costs fluctuate with Comex futures, squeezing margin pools for compounders locked into annual supply contracts with medical device OEMs.
- EPA registration concentration:Four registrants control the majority of approved polymer-integrated biocide masterbatches, creating supply chokepoints when formulation switches require new compatibility testing.
- Organic additive performance ceiling:Quaternary ammonium compounds degrade above 120°C processing temperatures, excluding them from high-heat injection molding applications where polypropylene dominates.
Strategic Opportunities
- Texas medical device corridor expansion:Austin and Dallas-Fort Worth clusters are attracting sterilization-sensitive manufacturers seeking localized compounding partnerships to reduce logistics lead times.
- Zinc oxide convergence with photonics:UV-activated antimicrobial polymers are opening dental equipment and diagnostic housing applications where silver-ion migration concerns limit traditional additive use.
- Direct-to-facility distribution:Compounders bypassing regional distributors to service hospital group purchasing organizations are capturing specification authority and multi-year contract structures.
Industry Challenges
- Biocide efficacy testing bottlenecks:ISO 22196 and ASTM E2149 protocol backlogs at third-party laboratories are extending product launch timelines by six to nine months for reformulated resins.
- Master file migration complexity:FDA Device Master File amendments for new antimicrobial additives require toxicological data packages that smaller compounders struggle to assemble without regulatory consulting partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Antimicrobial Plastics Market |
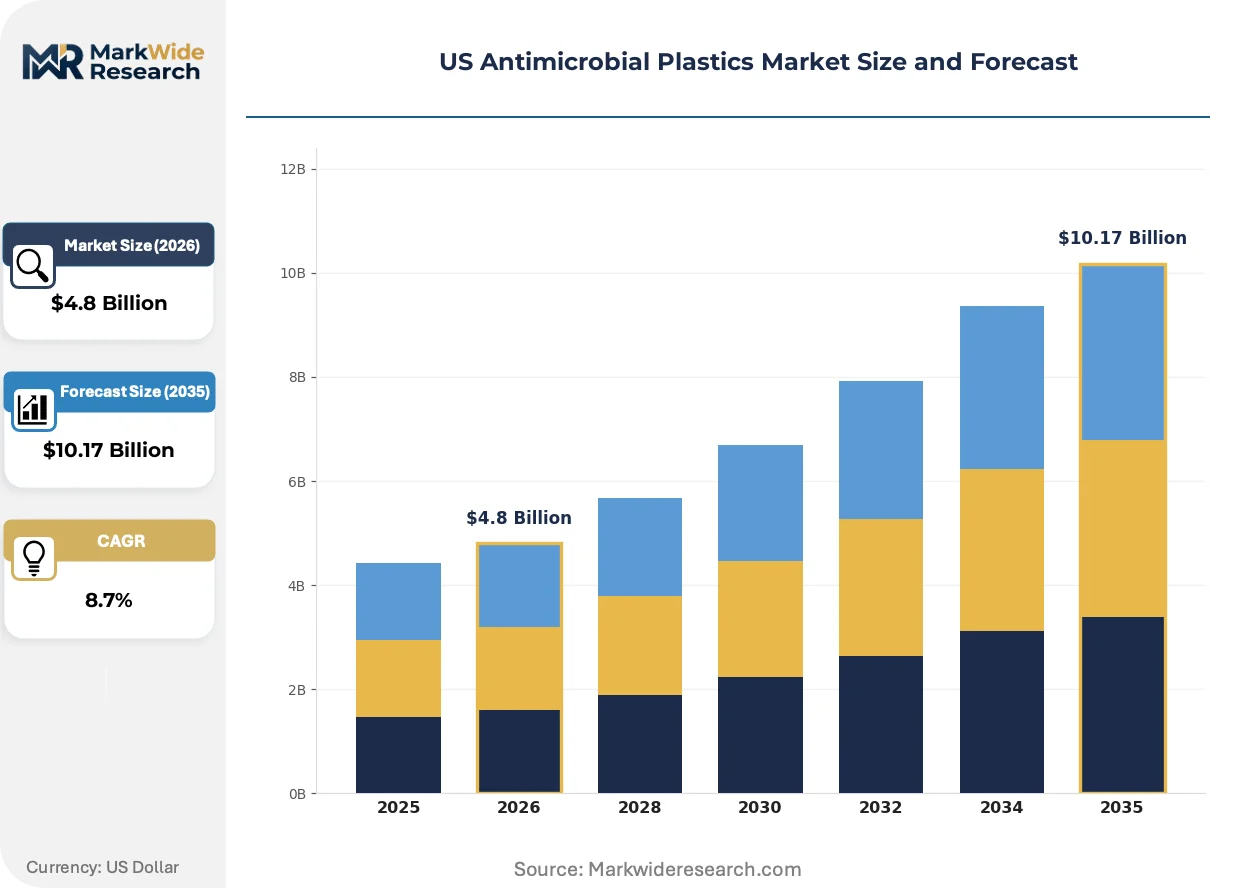
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polyvinyl Chloride, Polystyrene Application: Medical Devices, Packaging, Consumer Goods, Automotive Interiors End User: Healthcare Facilities, Food Industry, Building & Construction, Household Technology: Silver Nanoparticles, Copper Coatings, Organic Compounds, Others |
| Companies Covered | DuPont de Nemours, Inc, Avient Corporation, Microban International, RTP Company, Americhem Inc., King Plastic Corporation, American Polyfilm Inc., Ray Products Company Inc., Agion Technologies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Antimicrobial Plastics Market Strategic Shifts
Antimicrobial plastics manufacturing is pivoting from surface coatings toward bulk-integrated additives that survive multiple sterilization cycles without efficacy degradation.
Copper-salt masterbatch technology is rendering obsolete surface-applied silver coatings in HVAC ducting and filtration housing applications. Building automation contractors in Florida and Arizona are specifying bulk-infused polymers to eliminate delamination risks in high-humidity environments. This shift is compressing the addressable market for coating equipment suppliers while expanding compounding capacity requirements.
EPA's 2024 draft framework for nanoscale silver reassessment is forcing registrants to submit new environmental fate data. Compounders with existing FIFRA approvals are accelerating pipeline diversification toward zinc pyrithione and copper-based alternatives. Medical device manufacturers in Minnesota and Massachusetts are prioritizing suppliers with dual-registered additive portfolios to mitigate supply disruption risk.
Specification authority is migrating from procurement departments to infection control committees within hospital networks. Group purchasing organizations in the Upper Midwest are unbundling antimicrobial surface requirements from general polymer contracts, creating direct engagement opportunities for compounders with clinical efficacy data. This behavioral shift is most visible in Michigan and Ohio, where health system consolidation has concentrated buying power among three dominant networks.
US Antimicrobial Plastics Market Segmentation
Antimicrobial plastics exhibit divergent specification requirements across polymer chemistry, end-use exposure conditions, and regulatory compliance tiers. Understanding these segment boundaries enables compounders to align R&D investment with the highest-margin application clusters and anticipate reformulation triggers from EPA registration shifts.
Product Type:
After-sales service intensity varies sharply by resin chemistry, with medical-grade polypropylene requiring ongoing sterilization validation support while commodity polyethylene demands minimal technical assistance.
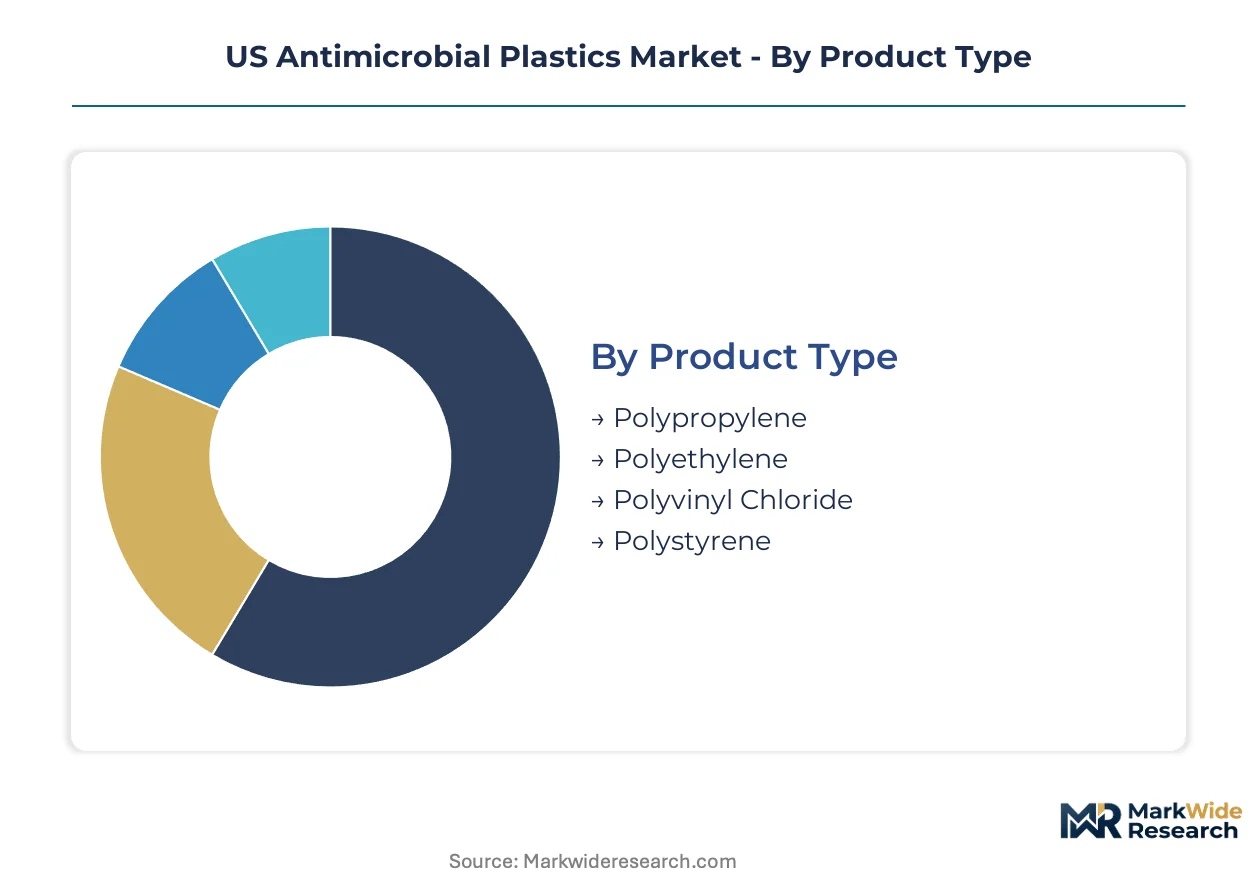
- Polypropylene:High crystallinity thermoplastic with excellent autoclave and gamma radiation sterilization resistance. Hospital bed rails, IV poles, and surgical instrument trays in Minnesota and Ohio health systems specify this resin for its thin-wall injection molding capability and FDA Device Master File compatibility.
- Polyethylene:Lower density polymer offering superior chemical resistance and flexibility in blow-molded containers. Food processing facilities in California and Texas procurement channels favor this material for cutting boards and storage bins subject to FSMA inspection protocols.
- Polyvinyl Chloride:Rigid formulation with inherent antimicrobial compatibility through plasticizer selection, serving drainage and tubing applications where copper salt additives integrate during extrusion.
- Polystyrene:Amorphous polymer limited to low-temperature applications; quaternary ammonium compound loading faces processing temperature constraints excluding high-heat medical sterilization cycles.
By volume, polyethylene leads. By growth pace, polypropylene is ahead.
Application:
Cost tier stratification separates premium specification-driven medical devices from price-sensitive consumer goods where organic additive loading minimizes unit economics impact.
- Medical Devices:Implantable and patient-contact equipment requiring FDA 510(k) submission and ISO 10993 biocompatibility testing. Silver nanoparticle masterbatches dominate this segment due to EPA FIFRA registration security and demonstrated efficacy against MRSA and C. difficile in Joint Commission-accredited facilities.
- Packaging:Food contact surfaces subject to FDA migration testing and state-level Proposition 65 disclosure requirements. Copper-enhanced films are displacing silver in meat and dairy processing lines where humidity accelerates ion migration concerns.
- Consumer Goods:Kitchen utensils, phone cases, and personal care items where lower regulatory burden permits cost-optimized organic antimicrobial loading.
- Automotive Interiors:HVAC ducting and touch surfaces where bulk-infused copper salts replace delamination-prone coatings in Florida and Arizona fleet specifications.
Medical devices command premium pricing. Packaging volumes are expanding most rapidly.
End User:
Customer type concentration determines distribution architecture, with healthcare facilities demanding direct compounding partnerships while household channels tolerate distributor intermediaries.
- Healthcare Facilities:Hospital networks and outpatient clinics where infection control committees now wield specification authority. Group purchasing organizations in Michigan and Ohio unbundle antimicrobial surface requirements from general polymer contracts, creating direct engagement opportunities for compounders with clinical efficacy data.
- Food Industry:Meat, dairy, and produce processors responding to FDA FSMA enforcement with copper-enhanced conveyor systems and storage infrastructure.
- Building & Construction:HVAC contractors and building automation specialists in high-humidity states specifying bulk-infused polymers to eliminate coating delamination risks.
- Household:Individual consumers purchasing antimicrobial-enhanced consumer goods through retail channels with minimal technical specification oversight.
Healthcare facilities drive margin capture. Food industry procurement is climbing the fastest.
Technology:
Supply concentration among EPA-registered biocide masterbatch suppliers creates chokepoints, with four registrants controlling polymer-integrated additive approvals and forcing compounders into compatibility testing bottlenecks.
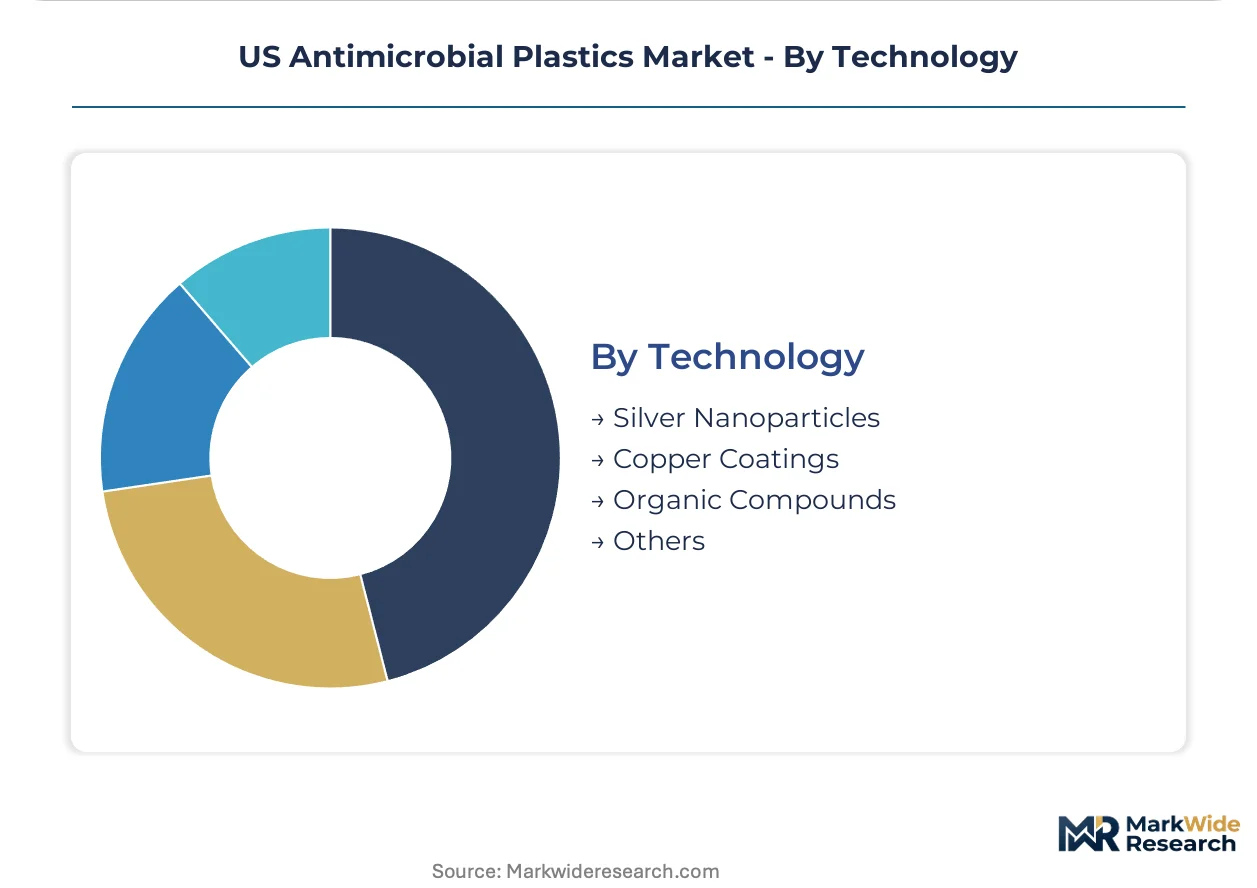
- Silver Nanoparticles:Inorganic additive with broad-spectrum efficacy and established EPA FIFRA registration pathways. Medical device manufacturers in Minnesota and Massachusetts prioritize suppliers with existing approvals to mitigate supply disruption risk from pending EPA nanoscale reassessment.
- Copper Coatings:Salt-based masterbatch technology rendering surface-applied silver obsolete in HVAC and filtration applications. Building contractors in Florida and Arizona specify these formulations for humidity-resistant performance.
- Organic Compounds:Quaternary ammonium and triclosan alternatives competing on cost in consumer goods where California Proposition 65 compliance pressures drive reformulation cycles.
- Others:Emerging zinc pyrithione and UV-activated zinc oxide technologies diversifying compounder pipelines ahead of potential silver registration pathway closures.
Silver nanoparticles dominate revenue. Copper coatings are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical corridor underwrites Texas's dominance in antimicrobial resin compounding, feeding medical device clusters along the Gulf Coast with polymer feedstock and specialized additive masterbatches.
California
Food processing facilities in the Central Valley and medical device manufacturers in Orange County drive procurement of Proposition 65-compliant formulations. The California Department of Public Health enforces disclosure requirements that compounders must satisfy to access West Coast distribution channels. San Diego's biotech corridor concentrates sterilization-sensitive device OEMs seeking localized compounding partnerships.
Texas
Austin and Dallas-Fort Worth medical device clusters attract antimicrobial compounders seeking reduced logistics lead times for gamma-sterilizable polypropylene. EPA Region 6 oversees FIFRA registration compliance for polymer-integrated biocides used in hospital equipment. The Houston Ship Channel's resin import infrastructure supports bulk masterbatch manufacturing for regional distribution.
Minnesota
Mayo Clinic-affiliated health systems and Medtronic's operational base generate specification authority for silver-ion-infused polymers in implantable device housings. The Minnesota Pollution Control Agency monitors industrial discharge from compounding operations near the Mississippi River. Minneapolis-St. Paul's medical technology corridor concentrates FDA Device Master File holders seeking dual-registered additive suppliers.
Massachusetts
Massachusetts General Hospital and Boston Scientific anchor demand for EPA-registered antimicrobial coatings in catheter and guidewire applications. The state's Toxics Use Reduction Act pressures compounders to validate alternative biocides ahead of potential silver registration pathway closures. Route 128's medical device corridor hosts sterilization validation laboratories that accelerate product qualification timelines.
Florida
Building automation contractors specify bulk-infused copper salt polymers for HVAC ducting in high-humidity coastal environments where coating delamination risks exclude surface-applied alternatives. The Florida Department of Environmental Protection regulates biocide discharge from compounding facilities near the Everglades. Miami-Dade's hospital construction pipeline concentrates procurement for antimicrobial surface specifications in new patient care facilities.
US Antimicrobial Plastics Market Competitive Environment
On the supply side, the industry is consolidating around specification-driven partnerships rather than transactional resin sales. Compounders with existing FDA Device Master Files and EPA FIFRA registrations command premium positioning in healthcare channels. Three archetypes dominate: diversified materials science conglomerates, embedded technology licensors, and custom compounding specialists. Capacity expansion and portfolio diversification toward zinc-based alternatives represent the primary competitive vectors as silver registration uncertainty intensifies.
Among diversified materials science conglomerates, DuPont de Nemours anchors long-term supply relationships through its sterilization-compatible polymer portfolio. Custom compounding specialists RTP Company and Americhem occupy positions serving FDA-regulated device manufacturers requiring master file documentation. Microban International exemplifies the technology licensing archetype, differentiating through embedded antimicrobial intellectual property rather than direct resin sales.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc |
| Avient Corporation |
| Microban International |
| RTP Company |
| Americhem Inc. |
| King Plastic Corporation |
| American Polyfilm Inc. |
| Ray Products Company Inc. |
| Agion Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
The Houston Ship Channel's resin import infrastructure anchors cost dynamics across the US antimicrobial plastics market, concentrating supply-side leverage among Gulf Coast compounders while forcing downstream price differentiation between sterilization-validated medical grades and commodity food-contact formulations.
Pricing Analysis
Volume-discount tiering separates FDA Device Master File holders from standard compounders, with silver-nanoparticle masterbatches commanding premium positioning against copper-salt alternatives. Price differentiation rests on EPA FIFRA registration security and ISO 10993 biocompatibility certification tiers. Cost compression in commodity polyethylene channels is intensifying as food processors negotiate multi-year FSMA-compliant supply agreements. Hospital group purchasing organizations exhibit lowest price sensitivity, while household consumer goods buyers drive aggressive unit economics negotiations.
Supply Chain Analysis
Extended payment terms from medical device OEMs now stretch 90-120 days, forcing compounders to leverage supply-chain finance facilities from regional banks. Geographic supply concentration centers on Texas, Minnesota, and Massachusetts, with resin feedstock drawing from Gulf Coast petrochemical corridors. Raw material dependencies include silver nanoparticle feedstocks, polypropylene base resins, and copper salt additives. Single-source vulnerability around EPA-registered biocide masterbatches creates chokepoints when formulation switches trigger compatibility testing. Distribution runs through direct partnerships with hospital GPOs and regional distributors serving food processing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US antimicrobial plastics market is entering a cyclical recovery phase as hospital capital expenditure budgets rebound from pandemic-era deferrals and FDA inspection protocols tighten food safety compliance spending.
For Market Incumbents: Harden EPA FIFRA registration portfolios through accelerated zinc pyrithione and copper-based additive diversification ahead of potential silver pathway closures. Deepen backward integration into specialized masterbatch manufacturing in Texas to capture margin from logistics-sensitive medical device clusters. Lock multi-year sterilization validation contracts with Minnesota and Ohio health systems to entrench specification authority against emerging compounders. For New Entrants and Emerging Players: Establish a beachhead in Proposition 65-compliant consumer goods channels where California disclosure requirements have displaced incumbent formulations containing legacy quaternary ammonium compounds. Target copper-enhanced food packaging segments in the Central Valley where FSMA enforcement is accelerating processor procurement cycles. Pursue white-label compounding partnerships with regional distributors lacking in-house antimicrobial formulation expertise. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core antimicrobial masterbatch operations amid portfolio rationalization pressures. Long-term viability hinges on dual-registered additive capabilities spanning silver alternatives and emerging photonic technologies. Watch EPA nanoscale silver reassessment timelines as the critical inflection signal for supply disruption risk and valuation compression in silver-dependent compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Registration Portfolio Buildout | Mitigates EPA silver reassessment risk for healthcare compounders serving Joint Commission-accredited facilities. |
| Direct GPO Partnership Structure | Bypasses distributor intermediaries to capture specification authority in Michigan and Ohio hospital networks. |
| Copper-Salt Masterbatch Scale-Up | Displaces surface coatings in Florida HVAC applications where humidity accelerates delamination failures. |
| Proposition 65 Compliance Reformulation | Unlocks California medical device and consumer goods shelf space previously blocked by triclosan-containing alternatives. |
| Sterilization Validation Laboratory Investment | Compresses ISO 22196 protocol backlogs that currently extend medical device launch timelines by six to nine months. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA FIFRA registration databases, FDA Device Master File records, and hospital procurement contract disclosures. Interviews with antimicrobial compounder technical directors, medical device OEM procurement leads, GPO contracts managers, and food processing facility engineers informed supply-side and demand-side dynamics. Secondary validation drew from customs trade data, American Chemistry Council resin production reports, and SEC filings from publicly traded materials science conglomerates. Bottom-up volume estimates triangulated against top-down market sizing across polymer chemistry and application segments.
Forecast inputs incorporate EPA registration pathway timelines, hospital capital expenditure cycle patterns, and food safety inspection enforcement intensity across the projection horizon. Segmentation dimensions modeled include polymer type, antimicrobial technology, application end-use, and geographic procurement cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion announcements. Industry-specific inputs include silver price volatility indices and third-party laboratory testing backlog durations.
Stress conditions across silver feedstock cost spikes, EPA registration denial scenarios, and hospital reimbursement compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory continuity and healthcare capital spending recovery. Macroeconomic contraction, accelerated EPA silver restrictions, or technological disruption in UV-activated alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Global Acrylic Processing Aid Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Gallic Acid Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Betulinic Acid Market
Specialty Chemicals
Ethylhexane Diol Market