
 Active Passive Trainer Market | 2026-2036
Active Passive Trainer Market Size, Share, and Industry Trends Forecast 2026-2036
Active Passive Trainer Market Insights
Modular platform configurations is rebalancing buyer choice across the Active Passive Trainer landscape as clinics seek interchangeable resistance modules and detachable limb attachments from single suppliers. Kinetec leverages its European manufacturing footprint to sustain rapid fulfillment of configurable lower-extremity systems. RECK-Technik anchors its competitive stance through specialized upper-body trainer architectures. Biodex Medical Systems differentiates via integrated software ecosystems that extend hardware utility across multiple therapy protocols.
An active passive trainer constitutes a motor-assisted rehabilitation device that delivers cyclical limb movement through electronically controlled resistance ranges, typically spanning 0–250 RPM with torque-adjustable drive mechanisms for neuromuscular re-education. The equipment serves primarily to restore range of motion, prevent joint contracture, and rebuild muscular endurance in post-surgical or neurologically impaired patients. Electronic trainers occupy the dominant margin pool given embedded biofeedback sensors and programmable session logging that command premium positioning. Rehabilitation centers represent the fastest-growing end-user channel as institutional procurement shifts toward outcome-documented equipment. Virtual reality integration remains nascent but captures disproportionate R&D allocation from vendors seeking software-based differentiation.
The FDA enforces 510(k) premarket notification for motorized therapy devices with software-controlled resistance, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for Class IIa active trainers distributed in member states. Japan's PMDA applies comparable electrical safety and electromagnetic compatibility standards that shape product development timelines for entrants targeting East Asian hospital networks. Stakeholders must monitor evolving software-as-medical-device classifications that could reclassify app-integrated trainers under stricter regulatory pathways.
Market Dynamics
EU Medical Device Regulation enforcement is compressing product development timelines as manufacturers revalidate software-controlled resistance algorithms for Class IIa reclassification.
Growth Catalysts
- Aging demographics in Japan:Metropolitan hospital districts in Tokyo and Osaka are accelerating physical therapy device deployment to address post-stroke rehabilitation demand.
- EU MDR clinical evidence mandates:Post-market surveillance requirements for motor-driven therapy equipment are institutionalizing outcome-documented procurement practices across German rehabilitation centers.
- Neuromuscular re-education protocols:Cyclical limb movement systems with torque-adjustable drive mechanisms are expanding into post-surgical recovery pathways.
Market Restraints
- Electronics supply concentration:Embedded biofeedback sensor sourcing depends on East Asian semiconductor fabrication capacity.
- Software validation costs:FDA 510(k) premarket notification timelines for programmable session logging extend commercialization cycles.
- Manual therapy substitution:Human-administered range-of-motion exercises retain preference in cost-constrained outpatient clinics.
Strategic Opportunities
- Virtual reality convergence:App-integrated trainers with immersive feedback environments capture disproportionate R&D allocation from established vendors.
- Interchangeable resistance modules:Modular platform configurations allow single-supplier relationships to cover multiple limb attachment requirements.
- Outcome-based reimbursement:Documentation capabilities in electronic trainers align with institutional procurement shifts toward measurable rehabilitation metrics.
Industry Challenges
- Electromagnetic compatibility certification:PMDA testing protocols for motor-assisted devices create bottlenecks in East Asian market entry.
- Legacy system integration:Hospital information system connectivity requirements complicate deployment of standalone rehabilitation equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Passive Trainer Market |
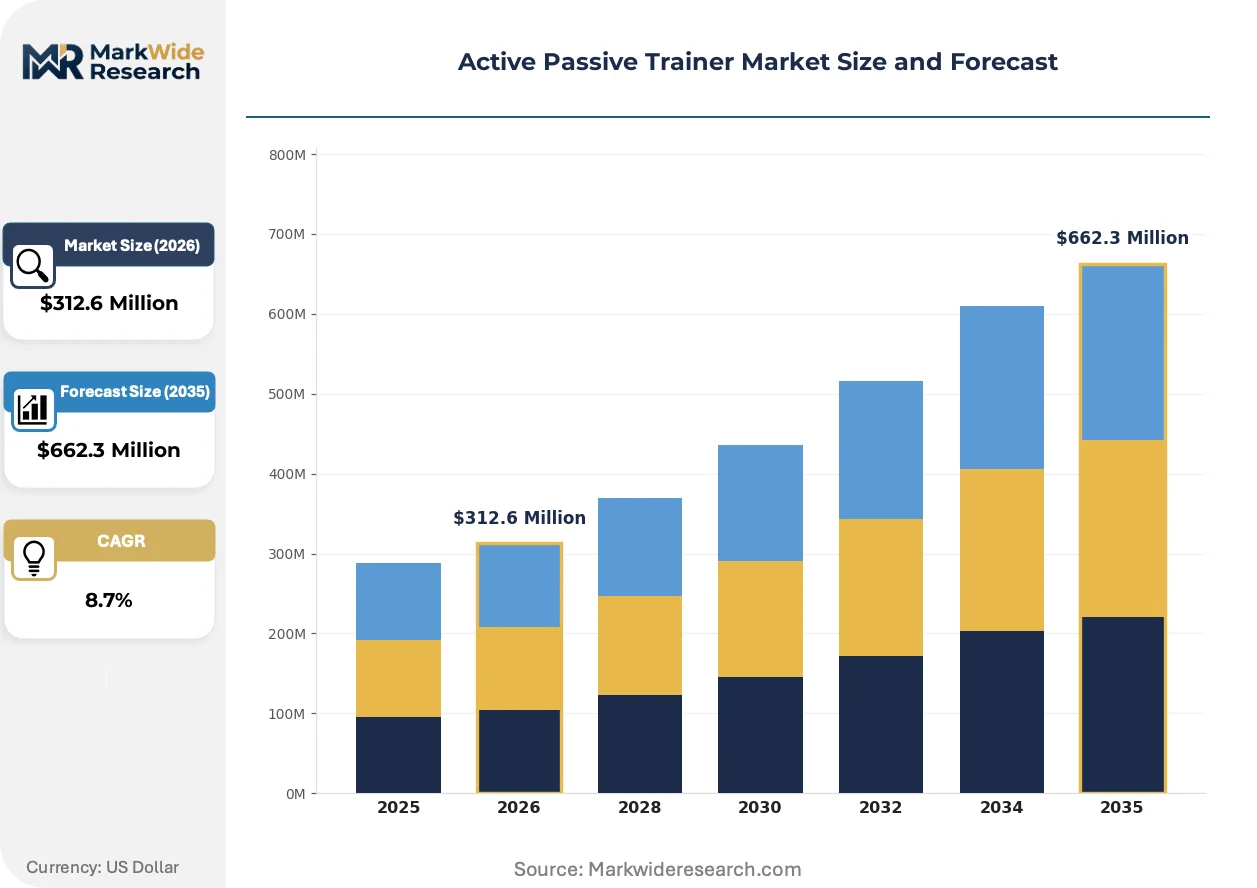
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Trainers, Manual Trainers, Automated Trainers, Smart Trainers End User: Rehabilitation Centers, Fitness Clubs, Home Users, Athletic Training Facilities Technology: Biofeedback Mechanisms, Resistance Training, Interactive Systems, Virtual Reality Integration Application: Physical Therapy, Sports Conditioning, Injury Prevention, General Fitness |
| Companies Covered | Mettler Electronics, Kinetec, RECK-Technik, Biodex Medical Systems, Chinesport, Healthcare International, Richmar, Nanjing Vishee Medical Technology, Sungdo MC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Passive Trainer Market Trends and Innovations
Software-based differentiation is displacing hardware specifications as the primary competitive axis in rehabilitation equipment procurement decisions.
Sensors measuring torque output and range-of-motion progression are integrating into unified biofeedback architectures. Rehabilitation centers in Germany are adopting these systems at accelerated pace to satisfy EU MDR documentation requirements. The technology is integrating session analytics directly into electronic medical record workflows, compressing the value proposition of standalone hardware-only trainers.
EU Medical Device Regulation Class IIa reclassification mandates are extending clinical evidence requirements to software-controlled resistance algorithms. Manufacturers must now submit post-market surveillance data for motor-driven therapy equipment distributed in member states. Japanese hospital networks are responding by demanding pre-validated electromagnetic compatibility documentation before procurement approval.
Institutional buyers are consolidating vendor relationships around suppliers offering configurable lower-extremity and upper-body attachments from single platforms. This pattern replaces fragmented procurement of dedicated devices for each limb type. Metropolitan hospital districts in Japan and rehabilitation centers in Germany exhibit the most concentrated adoption of unified-supplier contracts.
Active Passive Trainer Market Segmentation
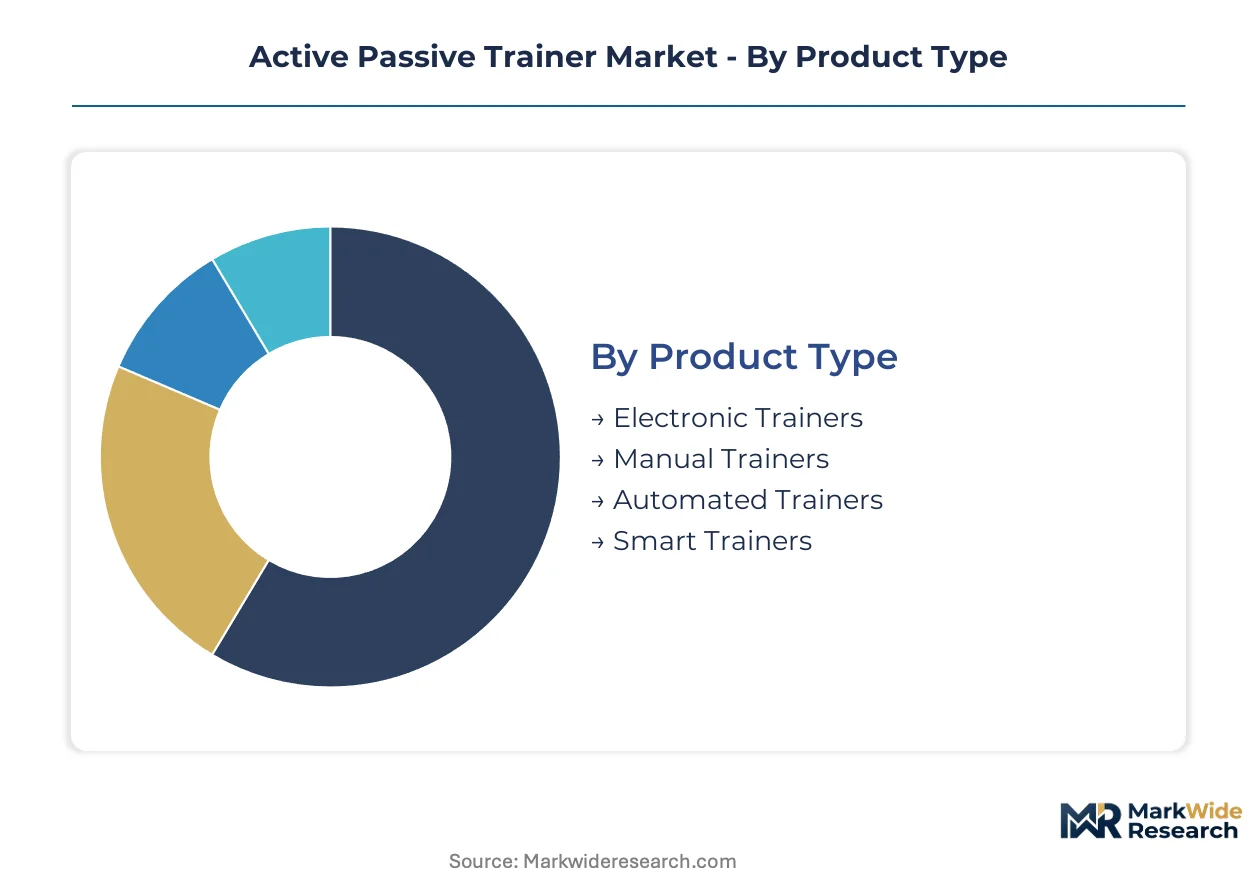
Segmentation in the Active Passive Trainer Market reveals distinct procurement patterns across institutional and consumer channels. Supply concentration varies sharply by product complexity, with electronic and automated systems commanding dedicated manufacturing footprints while manual trainers source from distributed metalworking networks.
Product Type:
Supply concentration clusters around electronically controlled systems, with semiconductor-dependent architectures requiring specialized assembly lines distinct from mechanical-only production.
- Electronic Trainers:Motor-assisted devices embed biofeedback sensors and programmable session logging for neuromuscular re-education. Rehabilitation centers in Germany prioritize these systems to satisfy EU MDR documentation mandates for outcome-tracked therapy.
- Automated Trainers:These systems deliver cyclical limb movement through torque-adjustable drive mechanisms with software-controlled resistance ranges. Metropolitan hospital districts in Japan accelerate procurement of automated configurations for post-stroke rehabilitation protocols.
- Manual Trainers:Human-powered resistance devices without electronic components serve cost-constrained outpatient clinics.
- Smart Trainers:App-integrated platforms with connectivity features face evolving software-as-medical-device classification risks.
Electronic trainers absorb the bulk of installed capacity; automated trainers are expanding most quickly.
End User:
Cost tier differentiation separates institutional procurement—with its compliance documentation requirements—from consumer channels where price sensitivity dominates.
- Rehabilitation Centers:Institutional buyers demand integrated software ecosystems that extend hardware utility across multiple therapy protocols. German rehabilitation centers lead procurement volume as EU MDR post-market surveillance requirements institutionalize outcome-documented equipment purchasing.
- Fitness Clubs:Commercial wellness facilities seek durable platforms with interchangeable resistance modules to serve diverse member needs.
- Athletic Training Facilities:Sports medicine departments prioritize torque measurement precision for injury recovery protocols.
- Home Users:Residential buyers favor compact units with simplified interfaces over clinical-grade feature sets.
Rehabilitation centers dominate current revenue concentration; fitness clubs show the steepest expansion trajectory among commercial channels.
Technology:
Application focus determines technology adoption, with clinical settings demanding validated measurement systems while wellness applications prioritize engagement interfaces.
- Biofeedback Mechanisms:Sensors measuring torque output and range-of-motion progression integrate into unified architectures for session analytics. These systems compress the value proposition of hardware-only alternatives by feeding electronic medical record workflows directly.
- Virtual Reality Integration:Immersive feedback environments capture disproportionate R&D allocation from vendors seeking software-based differentiation. The technology remains nascent in clinical deployment but attracts development investment from established equipment manufacturers.
- Resistance Training:Electronically controlled resistance algorithms require FDA 510(k) premarket notification, extending commercialization timelines.
- Interactive Systems:Touchscreen-guided protocols simplify operator training in high-turnover clinical staffing environments.
Biofeedback mechanisms anchor current technology investment; virtual reality integration is gaining share fastest among emerging capabilities.
Application:
Volume concentration in physical therapy reflects reimbursement structures, while sports conditioning follows discretionary spending patterns with different pricing elasticity.
- Physical Therapy:Post-surgical and neurologically impaired patient populations drive demand for cyclical limb movement systems. The application benefits from outcome-based reimbursement alignment with documentation capabilities in electronic trainers.
- Sports Conditioning:Athletic performance applications emphasize resistance adjustability for muscular endurance rebuilding. Professional training facilities in Japan's metropolitan districts deploy these systems for injury prevention protocols.
- Injury Prevention:Pre-habilitation protocols in athletic settings seek joint contracture prevention through regular range-of-motion maintenance.
- General Fitness:Wellness-oriented users apply active passive trainers for low-impact cardiovascular activity without clinical supervision.
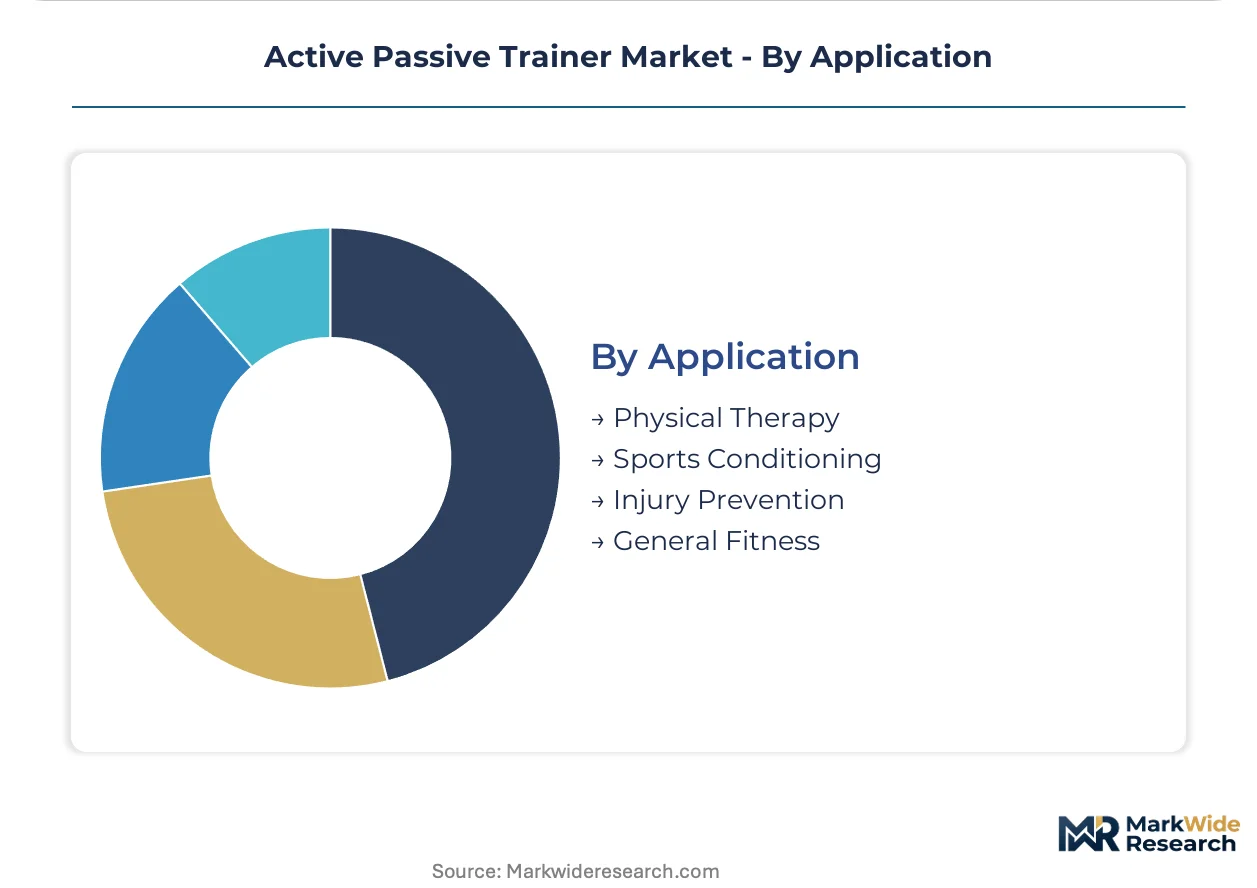
Physical therapy commands the largest installed base; sports conditioning is climbing the fastest among application categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of active passive trainers concentrates in European and East Asian industrial clusters, while demand acceleration spans aging populations in Japan, post-surgical rehabilitation expansion in Germany, and home-care adoption in North American metropolitan areas.
Japan
Metropolitan hospital districts in Tokyo and Osaka deploy automated trainer systems for post-stroke rehabilitation protocols. The PMDA enforces electromagnetic compatibility certification that shapes product development timelines for East Asian market entry. Kanto region medical device procurement is accelerating physical therapy device deployment to address demographic aging.
Germany
Rehabilitation centers across Bavaria and North Rhine-Westphalia are expanding procurement of outcome-documented equipment. The EU Medical Device Regulation mandates clinical evidence and post-market surveillance for Class IIa active trainers distributed in member states. Baden-Württemberg manufacturing clusters sustain rapid fulfillment of configurable lower-extremity systems.
United States
Institutional buyers in the Northeast Corridor and California demand integrated software ecosystems that extend hardware utility across multiple therapy protocols. The FDA enforces 510(k) premarket notification for motorized therapy devices with software-controlled resistance. Greater Boston hospital networks prioritize biofeedback sensor integration for electronic medical record connectivity.
South Korea
Seoul Capital Area rehabilitation facilities seek compact units with simplified interfaces for high-turnover clinical staffing environments. The MFDS applies electrical safety standards comparable to PMDA protocols that shape product localization requirements. Busan-Ulsan medical device distributors are consolidating vendor relationships around single-platform suppliers.
China
Yangtze River Delta manufacturing hubs source embedded biofeedback sensors from semiconductor fabrication networks for export-oriented production. The NMPA regulates motor-assisted rehabilitation devices under medical device classification schemes that align with international standards. Pearl River Delta assembly operations serve cost-constrained outpatient clinic segments with manual trainer alternatives.
Active Passive Trainer Market Competitive Landscape
The competitive structure tilts toward specialized rehabilitation equipment fabricators with regional manufacturing footprints. Vendor relationships consolidate around suppliers offering modular platform configurations covering multiple limb attachment requirements. Three archetypes dominate: European manufacturers with configurable lower-extremity systems, East Asian producers of compact upper-body architectures, and North American developers of software-integrated biofeedback ecosystems. Dominant competitive moves include backward integration into sensor component sourcing and strategic partnerships with hospital information system vendors.
Within the European manufacturing tier, Kinetec leverages its continental production footprint to sustain rapid fulfillment cycles, while RECK-Technik anchors specialized upper-body trainer architectures. Biodex Medical Systems occupies a position exemplifying software-based differentiation through integrated ecosystem approaches. These three entities represent distinct competitive vectors: geographic proximity to institutional buyers, anatomical specialization, and digital platform extension.
| Leading Market Players |
|---|
| Mettler Electronics |
| Kinetec |
| RECK-Technik |
| Biodex Medical Systems |
| Chinesport |
| Healthcare International |
| Richmar |
| Nanjing Vishee Medical Technology |
| Sungdo MC |
| Others |
Pricing and Supply Chain Analysis
EU MDR post-market surveillance mandates for Class IIa active trainers are compressing procurement timelines as rehabilitation centers demand pre-validated electromagnetic compatibility documentation, forcing manufacturers to absorb certification costs upstream and stratify pricing across CE-marked premium tiers versus non-certified economy alternatives.
Pricing Analysis
Margin tightening in electronic trainer tiers reflects embedded biofeedback sensor sourcing from East Asian semiconductor fabrication networks. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) certification status and software ecosystem integration depth. Cost compression accelerates in manual trainer segments as outpatient clinics substitute human-administered range-of-motion exercises. Rehabilitation centers exhibit lowest price sensitivity given outcome-based reimbursement alignment; home users face highest budget constraints.
Supply Chain Analysis
Japan's PMDA domestic-content preferences for hospital procurement are reshaping sourcing patterns toward local assembly partnerships. Manufacturing concentrates in Germany, Japan, and China, with Baden-Württemberg clusters feeding European demand and Yangtze River Delta hubs serving export markets. Embedded sensor modules, torque-adjustable drive mechanisms, and medical-grade aluminum framing constitute critical input dependencies. Single-source vulnerability in semiconductor fabrication creates bottlenecks for biofeedback-enabled systems. Distribution runs through specialized medical device distributors with hospital system integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over embedded sensor supply and software validation capabilities determines margin capture across EU MDR-compliant and FDA-regulated product tiers.
For Market Incumbents: To counter software-as-medical-device reclassification risks, Kinetec and RECK-Technik should deepen backward integration into torque sensor component sourcing and accelerate CE marking pathways for algorithm-controlled resistance modules. Captive supply of programmable session logging hardware preserves premium positioning against emerging Asian competitors. For New Entrants and Emerging Players: The price-point gap between FDA-validated premium electronic trainers and unregulated manual alternatives offers entry space for compact upper-body architectures targeting South Korea's Seoul Capital Area rehabilitation facilities. A white-label partnership strategy with Busan-Ulsan medical device distributors bypasses direct regulatory compliance investments. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with validated PMDA electromagnetic compatibility documentation and existing hospital information system connectivity. Long-term viability hinges on software ecosystem extension rather than hardware manufacturing scale. Watch for EU MDR Class IIa reclassification enforcement as inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa reclassification mandates clinical evidence submission for software-controlled resistance algorithms. |
| Hospital System Partnership | Integrated electronic medical record connectivity satisfies German rehabilitation center procurement requirements. |
| Backward Integration into Sensors | Captive biofeedback component supply mitigates East Asian semiconductor fabrication concentration risks. |
| Software Companion Development | App-integrated platforms with session analytics align with outcome-documented reimbursement structures. |
| Reimbursement Strategy | Outcome-based validation documentation accelerates adoption in Japan's metropolitan hospital districts. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, and PMDA electromagnetic compatibility test standards, complemented by interviews with rehabilitation center procurement managers, biomedical engineers at German hospital networks, medical device regulatory consultants, and distributors in the Busan-Ulsan corridor. Secondary sources included hospital procurement databases, GPO contracts, and customs trade records for rehabilitation equipment. Bottom-up unit demand estimates were cross-referenced against top-down market sizing through iterative triangulation.
Historical shipment data was cross-referenced against panel input from equipment manufacturers and institutional buyers across the analysis window. Segmentation modeling spanned product type, end-user channel, technology architecture, and application focus. CAGRs were derived from regression analysis of installed base expansion and replacement cycle dynamics. Forecast inputs incorporated demographic aging trajectories in Japan and EU MDR enforcement timelines.
Underlying measurement precision varies by segment; electronic and automated trainer categories carry tighter precision than manual alternatives given concentrated manufacturer reporting. Forecasts reflect assumptions around regulatory enforcement consistency and semiconductor supply normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Bowling Lane Panels Market
Sports & Fitness
Premium Bicycle Market
Sports & Fitness
Gymnastic Hoops Market
Sports & Fitness
Ski Vacation Market
Sports & Fitness
Branched Chain Amino Acid Supplements Market
Sports & Fitness
Knee Pads Market
Sports & Fitness
Europe Weight Management Supplement Market
Sports & Fitness
Home Fitness Market
Sports & Fitness
Wearable Patch Market
Sports & Fitness
UK Sports Management Software Market
Sports & Fitness
Golf Ball Market
Sports & Fitness
India Fitness Ring Market
Sports & Fitness
Bicycle Crankset Market
Sports & Fitness
United Kingdom Sports Drink Market
Sports & Fitness
Inflatable Sleds Market
Sports & Fitness
Shuffleboard Equipment Market