
 Home Fitness Market | 2026-2036
Home Fitness Market Size, Share, and Industry Trends Forecast 2026-2036
Home Fitness Market Analytics
Certified personal trainer availability is collapsing across suburban and rural markets, pushing households toward self-guided equipment purchases that replicate studio experiences. Peloton Interactive, Inc. sustains premium positioning through captive content ecosystems that lock in recurring revenue. Johnson Health Tech anchors mid-market volume through manufacturing scale across Taiwan and China production facilities. Technogym differentiates in the luxury residential segment with Italian-designed connected equipment for high-net-worth home installations.
Home fitness encompasses motorized and non-motorized exercise equipment designed for residential use, typically rated for lighter duty cycles than commercial-grade machinery with maximum user weight thresholds between 250 and 400 pounds. The category serves consumers seeking physical conditioning, weight management, and cardiovascular health maintenance without facility membership. Treadmills and exercise bikes within the Product Type segment command the largest installed base though resistance bands and adjustable dumbbells capture faster growth through lower price points and minimal space requirements. Connected Devices and Smart Equipment under the Technology dimension concentrate margin pools through subscription attach rates, while Wearable Trackers and Fitness Apps face commoditization from smartphone-native health platforms.
The Consumer Product Safety Commission enforces stability and electrical safety standards for motorized equipment, while the FCC regulates wireless connectivity protocols in smart-enabled machines. California's Proposition 65 chemical disclosure requirements add compliance costs for manufacturers using certain plastics and coatings. Stakeholders must monitor how evolving data privacy frameworks treat biometric collection from home fitness devices, as regulatory divergence between federal and state levels will shape product architecture decisions and market access requirements.
Market Dynamics
AI-powered personalization algorithms are compressing equipment replacement cycles while IoT interoperability mandates from the FCC reshape hardware architecture decisions across connected fitness platforms.
Growth Catalysts
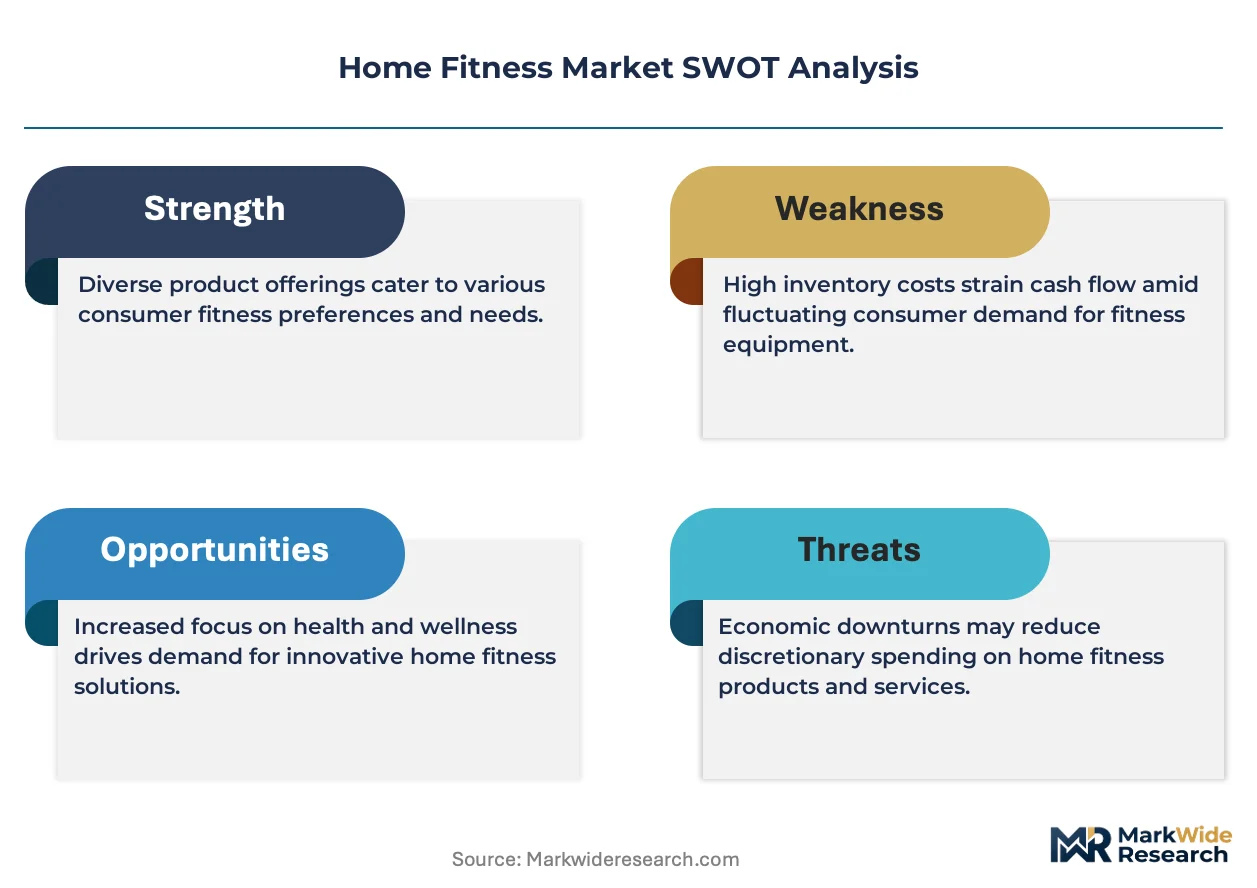
- Basement gym standardization:Residential builders in the United States now pre-wire dedicated workout spaces as standard amenity packages, embedding electrical and ventilation infrastructure that reduces consumer retrofit costs.
- REACH chemical compliance spillover:European manufacturers exporting to EU member states have already absorbed phthalate-free coating R&D costs, creating regulatory arbitrage for compliant products entering adjacent markets.
- Biometric data monetization:Subscription platforms leverage heart rate variability and recovery metrics to justify recurring fees, converting one-time equipment sales into annuity revenue streams.
Market Restraints
- Semiconductor allocation volatility:Motor controllers and Bluetooth modules face intermittent allocation constraints from Taiwan-based foundries, extending lead times for smart-enabled treadmills and bikes.
- California Proposition 65 disclosure burden:Warning label requirements for BPA and formaldehyde in plastics and adhesives add per-unit compliance costs that disproportionately impact low-margin resistance band manufacturers.
- Smartphone-native health platform substitution:Apple Health and Google Fit commoditize basic activity tracking, eroding standalone wearable tracker attach rates at the point of equipment sale.
Strategic Opportunities
- German-speaking Europe luxury retrofit:High-net-worth households in Austria and Switzerland exhibit underpenetrated demand for Italian-designed connected strength equipment matching residential interior specifications.
- India BIS certification pathway:Domestic manufacturing incentives under the PLI scheme create localized production opportunities for motorized equipment serving tier-2 urban markets.
- Generative AI coaching convergence:Large language models integrated with computer vision enable real-time form correction without human trainer overhead, opening premium positioning at mid-market price points.
Industry Challenges
- Embedded systems firmware talent scarcity:Real-time motion control algorithm development requires specialized skill sets concentrated in automotive and robotics sectors, driving compensation inflation for connected equipment R&D teams.
- HIPAA-aligned data architecture complexity:Biometric storage and third-party API sharing protocols demand legal-technical coordination that extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Fitness Market |
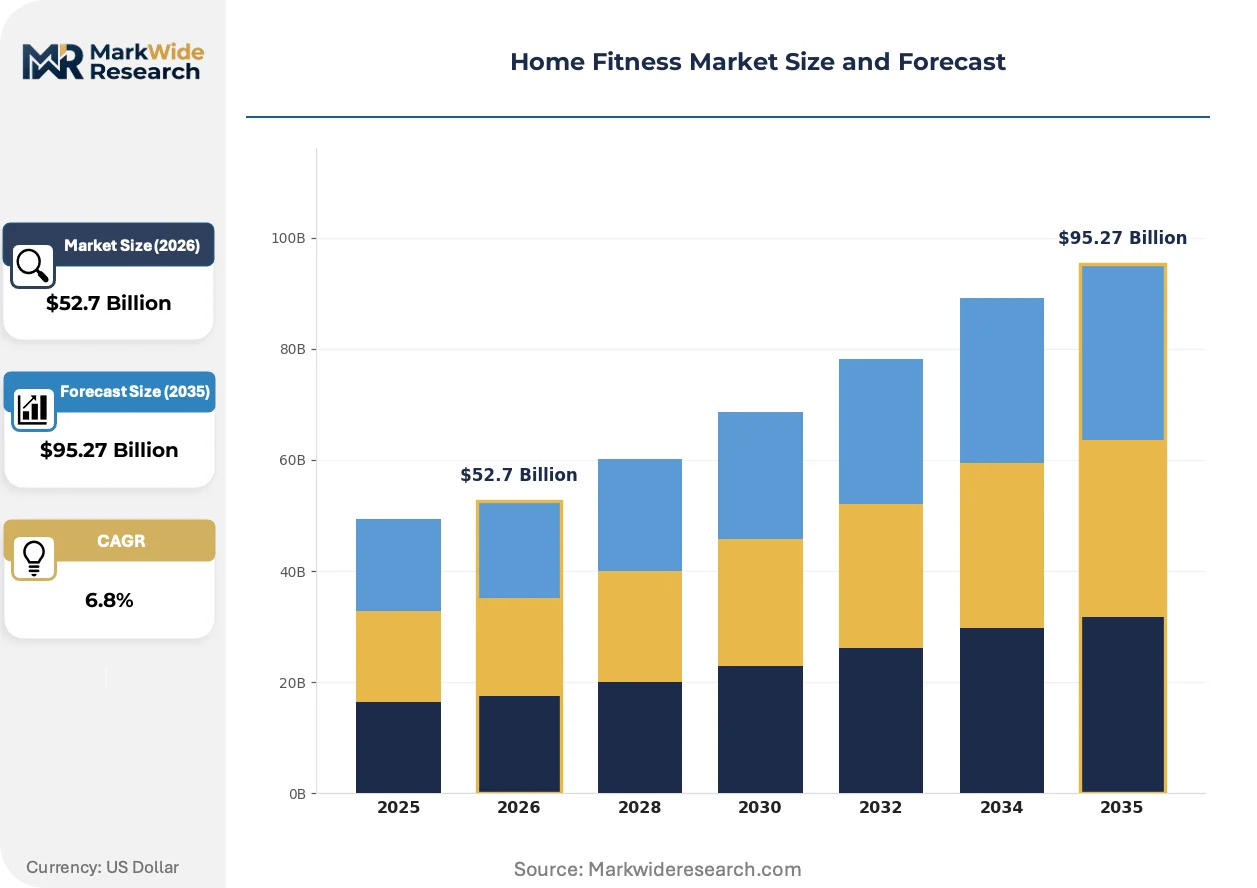
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmills, Exercise Bikes, Dumbbells, Resistance Bands End User: Individuals, Families, Fitness Enthusiasts, Seniors Technology: Connected Devices, Smart Equipment, Fitness Apps, Wearable Trackers Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Gyms |
| Companies Covered | Icon Health & Fitness, Johnson Health Tech, Technogym, Nautilus, Inc., Core Health & Fitness, Peloton Interactive, Inc., Life Fitness, Precor Incorporated, Torque Fitness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Fitness Market Evolving Landscape
Connected fitness platforms are pivoting from content volume toward predictive health integration, while hardware manufacturers face pressure to open proprietary data protocols for interoperability.
Computer vision form analysis is fragmenting the personal training value chain. Cameras embedded in mirrors and smartphones now count repetitions and flag range-of-motion deviations without wearable sensors. Boutique studio members and physical therapy patients adopt these tools for between-session consistency. The technology is fragmenting certification requirements across trainer credentialing bodies as automated feedback reduces perceived need for human supervision.
The EU AI Act's risk classification framework for biometric inference systems imposes conformity assessment obligations on European-market connected equipment. Manufacturers must document algorithmic decision-making processes for heart rate zone recommendations and injury risk predictions. Premium smart bike and treadmill lines destined for Germany, France, and Netherlands face 12-18 month certification timelines that compress first-mover advantages.
Direct-to-consumer subscription bundling is displacing retail equipment financing as the dominant acquisition model. Peloton and competitors now lead with monthly all-inclusive pricing that obscures hardware depreciation, shifting credit risk from consumer lenders to platform balance sheets. This pattern concentrates most visibly in United States urban markets where apartment dwellers prioritize flexibility over ownership equity.
Home Fitness Market Segmentation
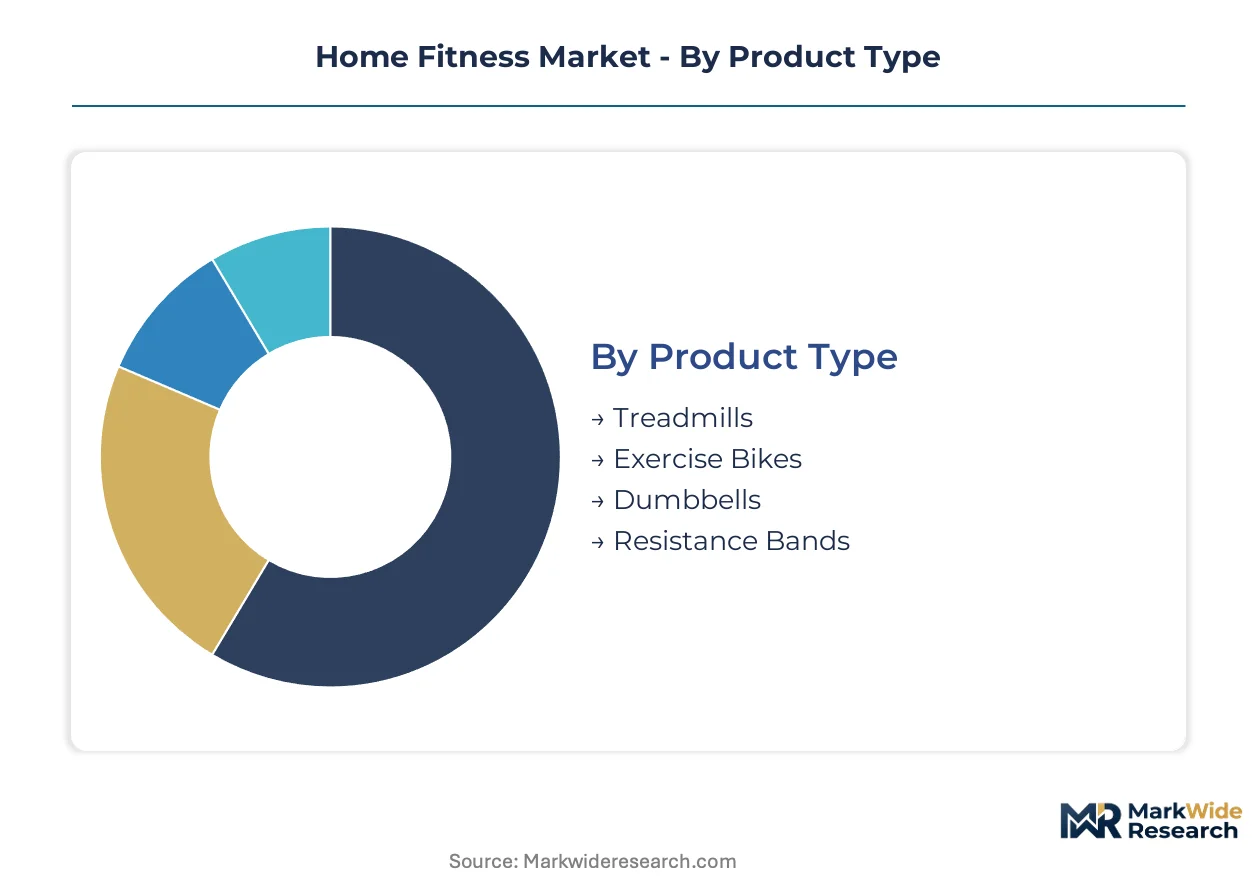
Segmentation in home fitness reveals divergent margin architectures across hardware, software, and service layers. Equipment categories carry divergent replacement cycles and subscription attach potential. Understanding where value concentrates within each dimension guides capital allocation and partnership strategy.
Product Type:
Motorized equipment commands premium pricing and recurring content revenue, while compact resistance tools dominate volume through impulse purchase accessibility.
- Treadmills:Motorized belt systems rated for residential duty cycles between 250-400 pound user thresholds anchor the premium hardware tier. Basement gym standardization in United States new construction sustains replacement demand as electrical pre-wiring reduces installation friction.
- Exercise Bikes:Stationary cycling platforms with magnetic resistance and integrated tablet mounts concentrate subscription attach rates. Connected bike demand clusters in urban professional households seeking studio-class output metrics without commute overhead.
- Dumbbells:Cast iron and adjustable weight systems serve strength training protocols with minimal space requirements. Adjustable configurations capture share from fixed sets through storage efficiency in apartment-dwelling segments.
- Resistance Bands:Elastic polymer loops and tubes enable portability-focused training at entry price points. Proposition 65 compliance costs for BPA disclosures compress margins for domestic manufacturers serving California distribution channels.
Treadmills hold installed capacity. Resistance bands are rotating up the share rankings.
End User:
Household composition and training intensity separate one-time equipment purchasers from recurring subscription subscribers.
- Individuals:Solo occupants prioritize compact footprint equipment and personalized content algorithms. This segment drives demand for AI-powered form correction and biometric-integrated coaching platforms.
- Families:Multi-user households require adjustable weight thresholds and user profile switching capabilities. Safety certifications from the Consumer Product Safety Commission influence purchase decisions for equipment accessed by children.
- Fitness Enthusiasts:High-frequency users demand commercial-grade durability specifications in residential form factors. This segment sustains premium pricing for connected equipment with live class libraries and competitive leaderboard features.
- Seniors:Older adults prioritize low-impact modalities and stability-assured design for fall prevention. Medicare Advantage supplemental benefit expansions in select United States markets are creating reimbursement-adjacent purchase channels.
Fitness enthusiasts hold installed capacity. Seniors are rotating up the share rankings.
Technology:
Data capture and subscription monetization potential separate margin-accretive technology tiers from hardware-commoditized alternatives.
- Connected Devices:Embedded screens with proprietary content ecosystems lock users into recurring payment streams. FCC wireless protocol compliance and HIPAA-aligned data architecture requirements extend development timelines for biometric-integrated systems.
- Smart Equipment:Sensor-embedded hardware capturing force, velocity, and range-of-motion metrics enables AI-driven coaching feedback. Real-time motion control firmware talent scarcity concentrates development capacity in automotive and robotics sector crossover hires.
- Fitness Apps:Smartphone-native training software faces commoditization pressure from Apple Health and Google Fit native integrations. Standalone app publishers pivot toward equipment-agnostic subscription models to escape platform dependency.
- Wearable Trackers:Wrist and chest-worn biometric sensors confront substitution from smartphone health platforms. Differentiation is shifting toward specialized recovery metrics and third-party equipment API integrations.
Connected devices hold installed capacity. Smart equipment is rotating up the share rankings.
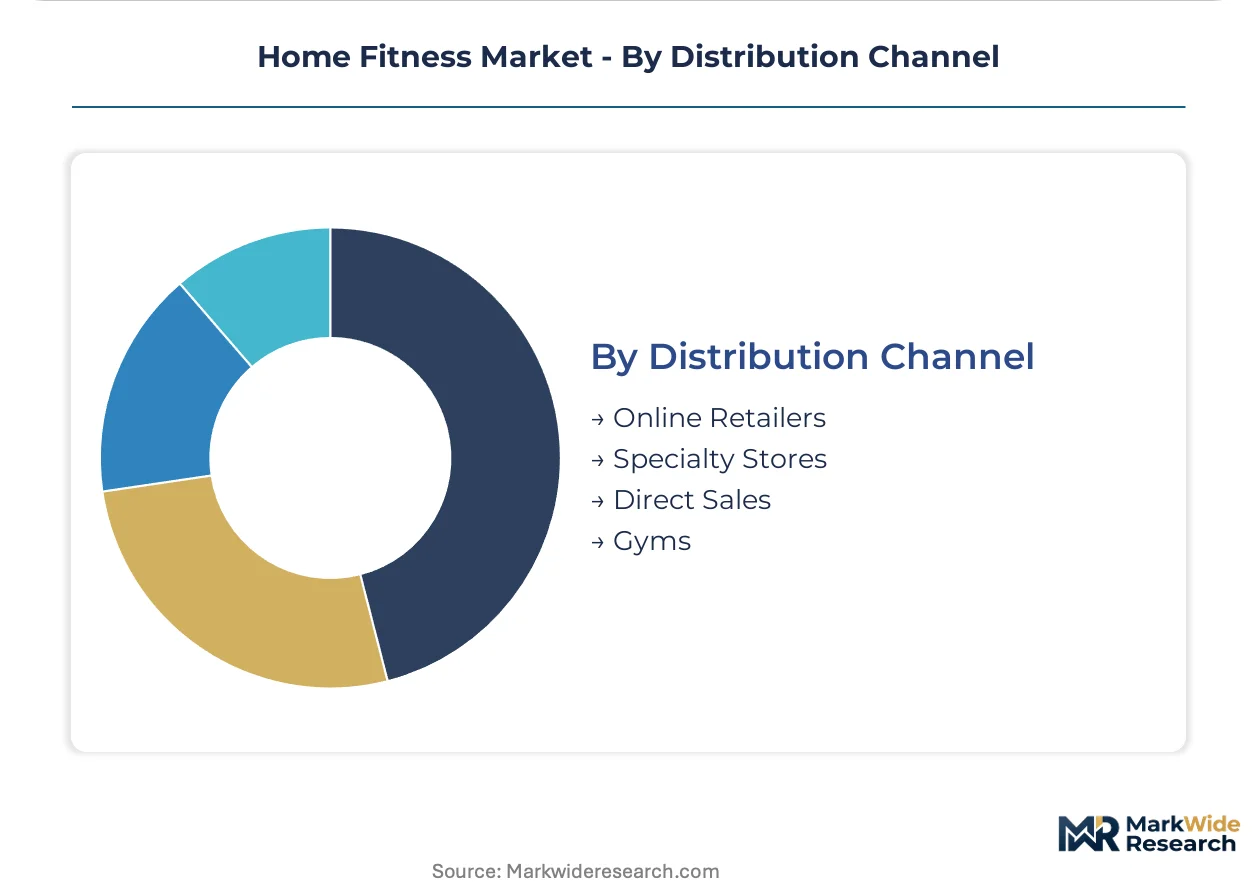
Distribution Channel:
Customer acquisition cost and subscription attach efficiency vary sharply across physical and digital touchpoints.
- Online Retailers:E-commerce platforms aggregate comparison shopping and enable financing integration at checkout. Amazon and specialty fitness marketplaces concentrate volume for compact, self-install equipment categories.
- Specialty Stores:Physical showrooms allow tactile evaluation of build quality and ergonomic fit. This channel sustains premium positioning for motorized equipment requiring delivery and assembly coordination.
- Direct Sales:Manufacturer-owned channels capture full margin and enable subscription bundling at point of purchase. Peloton's direct model concentrates credit risk on corporate balance sheets while obscuring hardware depreciation through all-inclusive monthly pricing.
- Gyms:Fitness facility partnerships enable equipment trial and brand exposure to pre-qualified active users. Boutique studio closures during pandemic periods accelerated direct-to-consumer channel migration.
Online retailers hold installed capacity. Direct sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC regulates wireless connectivity protocols for smart-enabled equipment in the United States, anchoring the largest concentration of connected fitness platform revenue and basement gym infrastructure investment.
United States
Residential builders in Texas and Florida pre-wire dedicated workout spaces as standard amenities, reducing consumer retrofit costs for motorized treadmills and exercise bikes. The Consumer Product Safety Commission enforces stability standards for equipment accessed by children in multi-user households. Greater Phoenix and Austin metropolitan clusters concentrate last-mile delivery fulfillment for direct-to-consumer connected bike platforms.
Germany
High-net-worth households in Bavaria and Baden-Württemberg drive demand for Italian-designed connected strength equipment matching residential interior specifications. The EU AI Act imposes conformity assessment obligations on biometric inference systems in smart bikes and treadmills destined for German, French, and Dutch markets. Berlin-Brandenburg hosts firmware development talent pools drawn from automotive and robotics sector crossover hiring.
China
Tier-2 urban markets in Sichuan-Chongqing and Shandong Peninsula exhibit rising demand for motorized equipment serving apartment-dwelling fitness enthusiasts. MIIT regulates wireless connectivity standards for IoT-enabled devices manufactured in Yangtze River Delta production clusters. Shenzhen and Dongguan concentrate electronics assembly capacity for motor controllers and Bluetooth modules facing intermittent semiconductor allocation constraints.
India
Domestic manufacturing incentives under the PLI scheme create localized production opportunities for motorized equipment serving Maharashtra and Karnataka urban markets. BIS certification requirements shape product architecture decisions for equipment entering formal retail channels. Delhi-NCR and Bengaluru clusters concentrate e-commerce platform distribution for compact resistance tools and adjustable dumbbells.
United Kingdom
London and Southeast England urban professionals prioritize subscription-based connected fitness platforms with live class libraries and competitive leaderboard features. GDPR compliance requirements extend product launch timelines for biometric-integrated coaching systems. Midlands manufacturing corridors supply cast iron and adjustable weight systems to European distribution networks.
Home Fitness Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with subscription bundling capabilities separating margin-accretive platforms from hardware-commoditized alternatives. Content ecosystem captivity and manufacturing scale represent the primary defensive moats. Three archetypes dominate: vertically integrated platform operators with captive content libraries, contract manufacturers serving white-label retail channels, and luxury residential specialists commanding interior-design-aligned pricing. Competitive moves concentrate on direct-to-consumer subscription bundling and geographic expansion through localized certification pathways.
Among North American platform operators, Peloton Interactive, Inc. and Nautilus, Inc. occupy positions exemplifying the subscription-anchored archetype, while Technogym S.p.A. represents the luxury residential specialist tier with Italian design credentials for high-net-worth home installations.
| Leading Market Players |
|---|
| Icon Health & Fitness |
| Johnson Health Tech |
| Technogym |
| Nautilus, Inc. |
| Core Health & Fitness |
| Peloton Interactive, Inc. |
| Life Fitness |
| Precor Incorporated |
| Torque Fitness |
| Others |
Value Network & Pricing Analysis
FCC wireless protocol certification gates both supplier qualification and price tier access for connected fitness equipment, compressing margins for manufacturers lacking pre-certified component sourcing while enabling premium capture by platforms with captive firmware development.
Pricing Analysis
United States urban markets command 40-60 percent premiums over equivalent equipment in India and Southeast Asian distribution channels, reflecting embedded subscription bundling and last-mile assembly costs. Three-tier pricing structure across premium, standard, and economy levels separates Peloton-style content-integrated platforms from Johnson Health Tech's mid-market volume plays and entry-level resistance tool manufacturers. Cost compression in the compact equipment tier is intensifying because Proposition 65 compliance burdens and polymer raw material volatility squeeze domestic manufacturers serving California. Individual apartment-dwelling buyers exhibit highest price sensitivity, while high-net-worth household renovations in German-speaking Europe show lowest elasticity.
Supply Chain Analysis
Inventory cycles for motor controllers and Bluetooth modules from Taiwan-based foundries have extended from standard 8-12 week baselines, forcing equipment manufacturers to pre-position semiconductor buffer stock. Manufacturing concentration centers on China, Taiwan, and Vietnam for electronics assembly and injection-molded polymer components, with Italy retaining captive capacity for luxury residential finishing. Raw material dependencies span rare earth magnets for resistance systems, phthalate-free polymer formulations for coatings, and aluminum extrusions for frame structures. Single-source vulnerability in Taiwan semiconductor allocation represents the dominant structural risk. Distribution runs through direct-to-consumer platforms for subscription-anchored equipment, while compact resistance tools flow through Amazon and specialty e-commerce aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home fitness incumbents face sustained substitution pressure from smartphone-native health platforms that commoditize basic activity tracking without hardware investment, demanding defensive repositioning around irreplaceable physical experience and biometric depth.
For Market Incumbents: Shield subscription revenue by deepening proprietary content ecosystem captivity through generative AI coaching integration that Apple Health cannot replicate without hardware partnerships. Lock in manufacturing scale advantages across Taiwan and China production facilities to outlast semiconductor allocation volatility that constrains smaller competitors. Prioritize HIPAA-aligned data architecture completion to preempt regulatory exclusion from Medicare Advantage reimbursement channels.
For New Entrants and Emerging Players: BIS certification fast-track under India's PLI scheme enables localized production cost advantages serving Maharashtra and Karnataka urban markets with motorized equipment priced below import parity. Target underpenetrated Austrian and Swiss luxury residential retrofit demand for Italian-designed connected strength equipment matching interior specifications. Pursue boutique studio partnership channels for equipment trial exposure to pre-qualified active users before direct-to-consumer scale investment.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape by imposing 12-18 month conformity assessment timelines that compress first-mover advantages for biometric-integrated platforms. Long-term viability favors vertically integrated platform operators with captive content libraries and manufacturing scale over hardware-commoditized contract manufacturers. Monitor firmware development talent migration from automotive and robotics sectors into connected fitness R&D as inflection indicator for platform capability deepening.
| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Coaching Integration | Large language models enable real-time form correction without human trainer overhead, opening premium positioning at mid-market price points. |
| HIPAA-Aligned Data Architecture Investment | Biometric storage compliance extends product launch timelines but unlocks Medicare Advantage reimbursement-adjacent purchase channels. |
| India PLI Scheme Localization | Domestic manufacturing incentives create cost-competitive production capacity for motorized equipment serving tier-2 urban markets. |
| EU AI Act Conformity Pathway | Algorithmic decision-making documentation requirements compress first-mover advantages for biometric inference systems in German, French, and Dutch markets. |
| Direct-to-Consumer Subscription Bundling | Monthly all-inclusive pricing obscures hardware depreciation while concentrating credit risk on platform balance sheets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with connected fitness platform executives, semiconductor procurement leads at equipment manufacturers, and Medicare Advantage benefits administrators; and secondary validation against FCC equipment authorization databases, EU AI Act implementation guidance, and SEC 10-K disclosures from publicly traded fitness equipment companies. Bottom-up triangulation across product category shipment estimates and top-down cross-checks against subscription revenue disclosures anchored volume and value assessments.
Across the analysis window, forecast outputs reflect modeled segmentation by product type, technology tier, end-user household composition, and distribution channel, with CAGRs derived from regression analysis of historical replacement cycles and subscription attach rate trajectories. Industry-specific inputs incorporated basement gym standardization penetration in United States new residential construction and BIS certification timeline assumptions for India market entry.
Underlying assumptions cover semiconductor allocation normalization, regulatory compliance cost absorption, and subscription retention stability, with deviation risk concentrated in EU AI Act enforcement timing and smartphone-native health platform capability expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Yoga and Pilates Mats Market
Fitness Equipment
Europe Home Fitness Equipment Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
Gym Fitness Accessories Market
Fitness Equipment
Asia-Pacific Fitness Equipment Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
North America Exercise Bike Market
Fitness Equipment
Gymnastic Springboard Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Treadmill Desks Market
Fitness Equipment
Treadmill Motors Market
Fitness Equipment
Middle East and Africa Fitness Equipment Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Pilates Equipment Market