
 Golf Ball Market | 2026-2036
Golf Ball Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Ball Market Analytics
Multi-layer urethane casting technology is narrowing the performance gap between tour-grade and recreational golf balls, compressing traditional price-performance tiers. Titleist leverages its Ball Plant manufacturing concentration to sustain quality consistency across professional and amateur channels. Bridgestone Golf competes through rubber compound R&D partnerships with its parent tire division, while Srixon anchors its position in the value-tier urethane segment through controlled Asian manufacturing scale.
A golf ball is a precision-engineered sphere typically measuring 42.67 mm in diameter and weighing no more than 45.93 grams, constructed from molded rubber cores wrapped in ionomer or urethane cover layers through compression or injection molding processes designed to deliver controlled spin, distance, and aerodynamic stability across varied swing speeds. Two-piece Surlyn-covered balls dominate unit volume in the amateur leisure application due to durability and lower price points, while four-piece urethane constructions command the tournament segment where spin control and feel differentiate professional-grade equipment. Polyurethane cover materials represent the fastest-growing material category as manufacturers reformulate for softer compression without sacrificing cut resistance.
The USGA equipment conformance standards and R&A ball specifications govern maximum initial velocity and overall distance standards, restricting product innovation to materials and aerodynamics rather than fundamental performance expansion. The EPA oversees rubber compounding and solvent emissions at US-based manufacturing facilities, adding compliance costs that favor larger producers with environmental management systems. Stakeholders must monitor evolving amateur participation demographics and material substitution economics as the industry navigates generational participation shifts and sustainable manufacturing mandates.
Market Dynamics
Multi-layer urethane casting technology is compressing traditional price-performance tiers, forcing manufacturers to differentiate through material science breakthroughs rather than fundamental design expansion under USGA and R&A constraints.
Growth Catalysts
- Resort-based amateur programs:Equipment refresh cycles accelerate as recreational leagues expand across destination golf clusters in the United States and Spain.
- REACH-compliant polyurethane reformulation:European manufacturers leverage softer compression urethane covers to capture migrating recreational players seeking tour-grade feel.
- Controlled Asian manufacturing scale:Value-tier urethane production concentrates in Thailand and Vietnam, lowering unit economics for mid-market penetration.
Market Restraints
- Petrochemical feedstock volatility:Synthetic rubber and ionomer resin prices fluctuate with crude oil indices, compressing margin stability for cover material suppliers.
- USGA velocity ceiling:Maximum initial velocity standards cap distance performance gains, restricting premium pricing justification for distance-focused innovations.
- Surlyn durability threshold:Two-piece constructions dominate unit volume at price points where urethane covers cannot achieve equivalent cut resistance.
Strategic Opportunities
- India course development:Greenfield resort construction in Karnataka and Maharashtra creates first-mover equipment partnerships with emerging club operators.
- Biodegradable core research:Corn-based rubber alternatives align with EU Green Deal mandates and attract sustainability-conscious municipal course procurement.
- Direct-to-consumer fitting platforms:Swing-speed-matched ball recommendation algorithms bypass traditional pro-shop markup structures.
Industry Challenges
- Compression molding technician scarcity:Specialized urethane casting expertise concentrates in legacy Japanese and Korean manufacturing bases, limiting facility expansion.
- Multi-year USGA conformance timelines:Novel dimple pattern submissions face 12-18 month approval windows, delaying product launch synchronization with tour seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Ball Market |
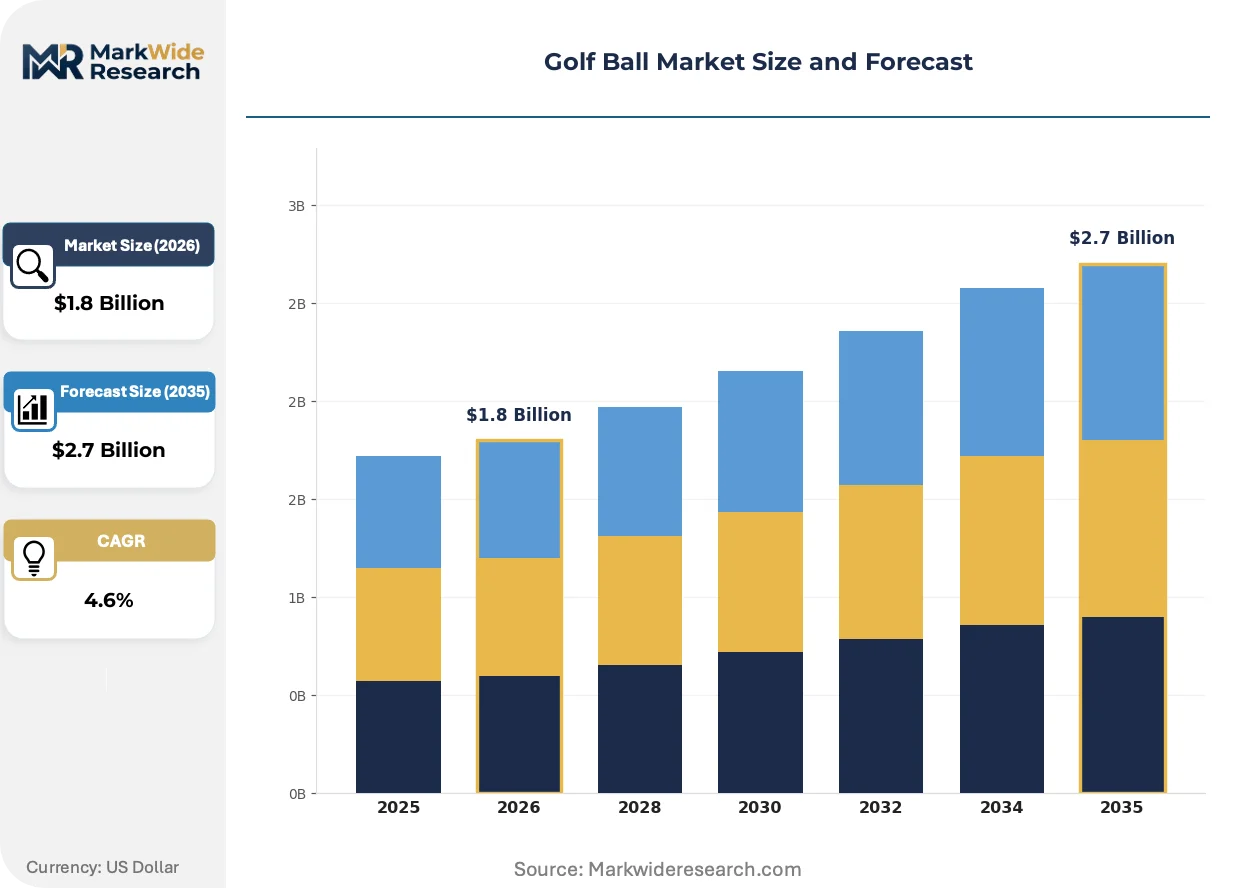
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Piece, Three-Piece, Four-Piece, Urethane End User: Amateurs, Professionals, Women, Juniors Material: Surlyn, Rubber, Polyurethane, Composite Application: Practice, Tournament, Leisure, Training |
| Companies Covered | TaylorMade, PXG, Titleist, Wilson Golf, Mizuno, Bridgestone Golf, Srixon, Maxfli, Callaway Golf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Ball Market Evolving Landscape
Digital swing analysis and material informatics are converging to personalize ball construction recommendations, while regulatory pressure on rubber compounding emissions accelerates sustainable chemistry investment.
Computational fluid dynamics simulation is virtualizing dimple pattern prototyping, allowing manufacturers to test aerodynamic stability across 10,000+ geometry permutations without physical mold fabrication. Tour equipment managers and high-volume amateur leagues adopt these digitally-optimized designs within single product cycles. The technology is virtualizing traditional wind-tunnel validation, compressing R&D timelines from 18 months to under 6 months for iterative cover texture refinements.
EPA rubber compounding emission standards tighten solvent recovery requirements at US-based manufacturing facilities, adding capital expenditure burdens that favor producers with existing environmental management infrastructure. The regulation drives consolidation toward larger Ball Plant-scale operations with captive chemical handling systems. Smaller domestic competitors face facility relocation decisions or contract manufacturing pivots to Mexican and Canadian toll producers.
Amateur buying patterns fragment across swing-speed-segmented SKUs rather than traditional handicap-based categorization. Retail channel inventory complexity rises as 85-95 mph and 95-105 mph compression variants displace generic "distance" and "control" shelf positioning. United States big-box sporting goods retailers respond with interactive launch-monitor stations that match ball construction to measured clubhead speed, shifting purchase authority from green grass pro shops to data-driven self-selection.
Golf Ball Market Segmentation
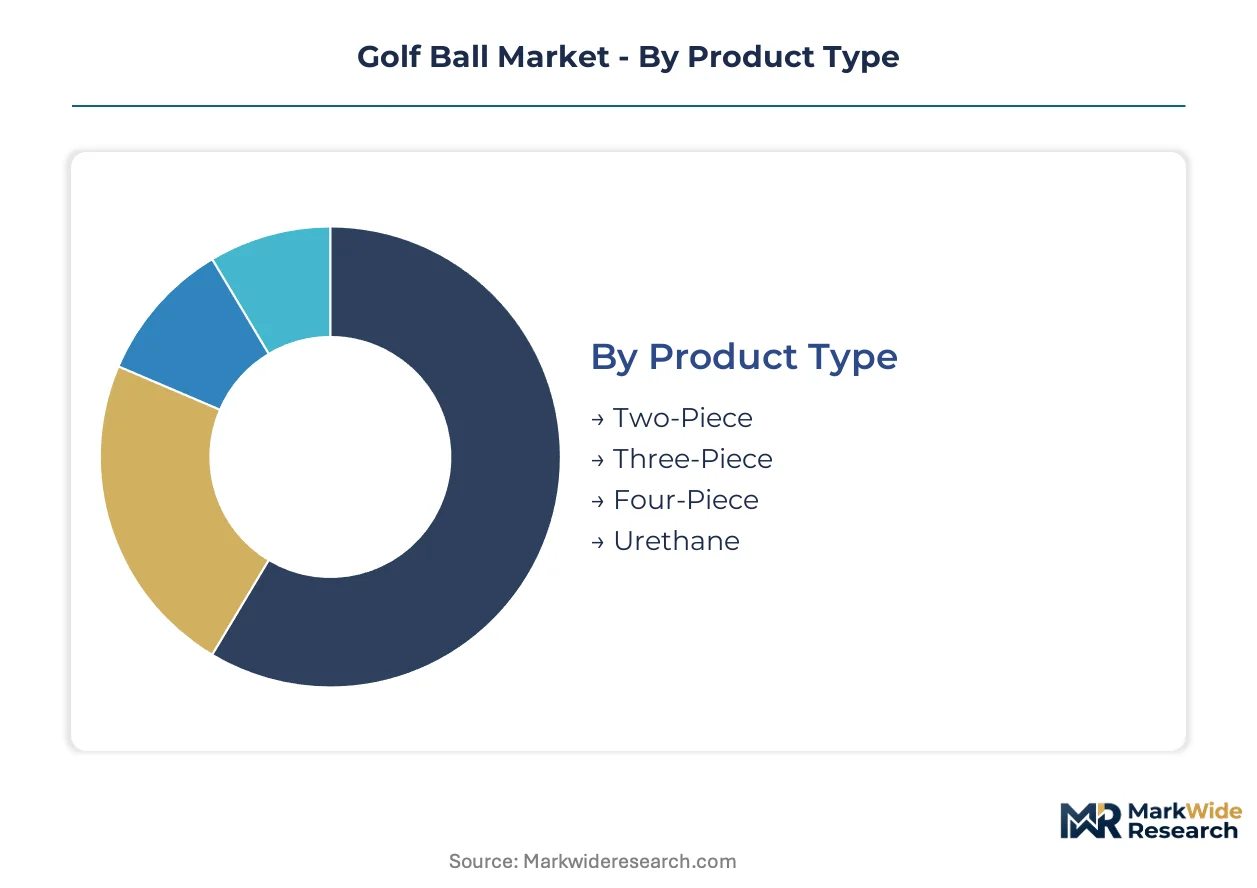
Golf ball segmentation reflects divergent performance requirements across swing speeds, competitive levels, and price sensitivity. Manufacturers align construction complexity and cover chemistry to specific usage contexts rather than pursuing universal designs.
Product Type:
Construction layers determine compression characteristics, spin generation, and cost tier positioning across the amateur-to-professional spectrum.
- Two-Piece:A molded solid core wrapped in Surlyn ionomer cover delivers maximum durability and distance for slower swing speeds. Demand concentrates in municipal course bulk purchases and driving range operations across the United States where replacement frequency drives procurement decisions.
- Four-Piece:Dual-core construction with mantle layers and soft urethane cover enables precise spin separation between long-game and short-game performance. Tournament players in Florida and Arizona destination circuits absorb premium pricing for trajectory control around firm greens.
- Three-Piece:Intermediate compression core with single mantle balances feel and distance for mid-handicap recreational players.
- Urethane:Cast thermoset polyurethane covers across multi-layer platforms deliver soft feel and greenside bite regardless of piece count.
Two-piece constructions command the established base in unit volume. The steepest expansion runs through four-piece urethane configurations as amateur swing speeds rise and fitting education penetrates club memberships.
End User:
Player category segmentation aligns compression matching, colorways, and marketing channels to distinct participation patterns and equipment refresh cycles.
- Amateurs:Handicap-indexed players from 5 to 25 drive replacement purchases through seasonal league play and resort-based equipment trials. United States club-fitting studios now match ball compression to measured driver swing speeds rather than handicap alone.
- Professionals:Tour card holders and elite amateurs require USGA-conforming balls with batch-to-batch consistency for competitive validation. Equipment contracts with Arizona and California-based tour vans dictate specification lock-in months before major championships.
- Women:Lower-compression constructions marketed through dedicated colorways and packaging address average swing speed differentials in women's leagues.
- Juniors:Reduced-compression, high-visibility designs support development programs at Texas and North Carolina junior academies.
Amateur channels absorb the majority of unit volume. The steepest expansion trajectory belongs to women and junior segments as participation initiatives target demographic gaps in traditional club membership.
Material:
Cover and core chemistry choices trade off durability, feel, and manufacturing cost in formulations governed by EPA and REACH compliance requirements.
- Polyurethane:Thermoset casting enables sub-90 compression covers with cut resistance approaching ionomer alternatives. European manufacturers leverage REACH-compliant reformulations to capture migrating recreational players seeking tour-grade feel without US import premiums.
- Surlyn:Ionomer resin covers dominate two-piece constructions with abrasion resistance exceeding 100 holes per ball in robotic testing. Thailand-based compounding facilities supply Asian value-tier producers with resin grades optimized for tropical storage conditions.
- Rubber:Synthetic polybutadiene cores across all construction types determine initial velocity and compression response.
- Composite:Experimental core formulations incorporating recycled rubber and bio-based binders address emerging sustainability procurement mandates.
Surlyn retains volume leadership in price-sensitive channels. Polyurethane climbs fastest as compression-matching education spreads through United States retail fitting installations.
Application:
Usage context dictates durability requirements, visibility specifications, and procurement economics across institutional and individual buyers.
- Leisure:Recreational rounds at resort and municipal courses in Spain and Portugal drive bulk purchasing of two-piece white and yellow options. Golf package operators specify ball inclusion in stay-and-play bundles, compressing brand switching costs.
- Tournament:Sanctioned competition requires USGA and R&A conformance list validation with lot number traceability. State golf associations in California, Texas, and Florida mandate list-checking for championship eligibility.
- Practice:Driving range and short-game facility operators prioritize durability over performance in high-volume retrieval environments.
- Training:Launch-monitor-optimized balls with embedded RFID or reflective markings support swing analysis at Korean and Japanese coaching centers.
Leisure applications anchor unit demand through resort partnerships. Tournament-specification balls gain share fastest as competitive participation rebounds and conformance verification technology penetrates regional qualifying events.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based resort operators and club-fitting studios drive the highest equipment refresh rates among developed golf economies, while emerging course development in India and Southeast Asia redirects procurement volumes toward value-tier manufacturers.
United States
Destination golf clusters in Arizona, Florida, and California absorb premium four-piece urethane volumes through resort-based amateur programs. The EPA enforces rubber compounding emission standards at domestic manufacturing facilities, elevating compliance costs for smaller producers. Ball Plant-scale operations in Massachusetts anchor professional-grade batch consistency for tour validation channels.
Japan
Domestic demand concentrates in Kansai and Chubu regions where aging club memberships prioritize compression-matched fitting over handicap-based purchasing. METI oversees chemical handling standards at urethane casting facilities, reinforcing legacy manufacturing expertise concentration. Osaka-based technical institutes supply specialized molding technicians to regional producers.
Germany
REACH-compliant polyurethane reformulation enables European manufacturers to capture recreational players migrating toward softer compression covers. ECHA chemical registration requirements govern cross-border resin shipments from compounding facilities. Bavarian industrial clusters near Munich host precision mold fabrication suppliers serving continental ball producers.
Thailand
Value-tier Surlyn ionomer production scales through Bangkok and Eastern Seaboard manufacturing zones serving Asian export markets. The country's Board of Investment incentivizes rubber processing facility expansion for golf component supply chains. Controlled manufacturing scale in Chonburi Province lowers unit economics for mid-market urethane penetration.
India
Greenfield resort construction in Karnataka and Maharashtra creates first-mover equipment partnership opportunities with emerging club operators. The Bureau of Indian Standards certifies recreational-grade ball imports for municipal course procurement. Bangalore-based junior academies drive reduced-compression training ball demand through development program expansion.
Golf Ball Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price-performance segments compressed by multi-layer urethane casting advances. The structure consolidates around scale-driven manufacturers with captive Ball Plant operations and rubber compound R&D integration. Three archetypes dominate: integrated tire-to-golf conglomerates leveraging material science cross-pollination, dedicated golf equipment pure-plays optimizing professional validation channels, and Asian value-tier specialists exploiting controlled manufacturing scale. Competitive moves center on REACH-compliant polyurethane reformulation partnerships and direct-to-consumer fitting platform development bypassing traditional pro-shop markups.
Among integrated conglomerates, Bridgestone Golf exemplifies material science leverage through parent-division rubber compound R&D partnerships. Titleist anchors the professional validation archetype with concentrated Ball Plant manufacturing sustaining batch-to-batch conformance for tour equipment managers. Srixon occupies the value-tier urethane position, representing Asian manufacturing scale efficiency in mid-market penetration strategies.
| Leading Market Players |
|---|
| TaylorMade |
| PXG |
| Titleist |
| Wilson Golf |
| Mizuno |
| Bridgestone Golf |
| Srixon |
| Maxfli |
| Callaway Golf |
| Others |
Value Network & Pricing Analysis
Chonburi Province manufacturing clusters in Thailand anchor mid-market urethane capacity expansion, with controlled scale dynamics directly constraining pricing power for value-tier competitors seeking Asian export penetration. Ball Plant-scale operations in Massachusetts and legacy Japanese casting facilities retain premium-tier pricing authority through batch consistency certification for tour validation channels.
Pricing Analysis
Petrochemical-indexed cost-plus contracts with quarterly synthetic rubber and ionomer resin adjustments dominate raw material procurement, compressing margin stability when crude oil benchmarks fluctuate. Three-tier pricing structure across premium tour-grade, standard recreational, and economy bulk channels separates compression-matched urethane constructions from generic two-piece Surlyn alternatives. Pricing pressure intensifies in the amateur leisure segment as REACH-compliant European reformulations and Thai manufacturing scale erode traditional geographic premiums. Municipal course procurement teams exhibit highest price sensitivity through volume-driven replacement cycles, while Arizona and Florida resort operators absorb premium positioning for equipment inclusion in stay-and-play bundles.
Supply Chain Analysis
Export-control restrictions on precision dimple pattern molding equipment limit technology transfer to emerging manufacturing bases, concentrating advanced aerodynamic prototyping capacity in Japan, Germany, and the United States. Synthetic polybutadiene rubber cores and thermoset polyurethane cover resins draw from petrochemical feedstocks tethered to regional refinery output in Thailand, South Korea, and Texas. Single-source vulnerability concentrates in specialized urethane casting technician pools anchored to Osaka technical institutes and legacy Korean manufacturing bases. Distribution runs through green grass pro shops, big-box sporting goods retailers with interactive fitting stations, and direct-to-consumer platforms bypassing traditional markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-layer urethane casting advances are compressing traditional price-performance tiers, with EPA emission standards and REACH compliance mandates accelerating consolidation toward scale-driven manufacturers with captive environmental management infrastructure.
For Market Incumbents: Harden quality consistency protocols at Ball Plant-scale operations to defend tour validation channel positioning against emerging Asian value-tier urethane penetration. Deepen backward integration into rubber compounding through parent-division R&D partnerships, mirroring Bridgestone Golf's tire division material science leverage. Prioritize REACH-compliant polyurethane reformulation investment to capture migrating European recreational players before compliance costs exclude smaller competitors. For New Entrants and Emerging Players: Pursue white-space positioning in India greenfield resort partnerships across Karnataka and Maharashtra, where first-mover equipment relationships with emerging club operators remain unclaimed. Target biodegradable core research collaborations with EU municipal course procurement programs aligned with Green Deal sustainability mandates. Deploy swing-speed-matched direct-to-consumer fitting algorithms to bypass established pro-shop channel control and capture data-driven amateur self-selection. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EPA emission compliance burdens and USGA conformance timeline delays favor scale-driven producers with existing environmental infrastructure and captive regulatory affairs capacity. Acquisition candidates center on Asian value-tier specialists with controlled Thai or Vietnamese manufacturing scale and established European REACH-compliant reformulation capabilities. Watch for inflection signals in India course development permitting velocity and junior academy expansion rates across Texas and North Carolina.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Polyurethane Reformulation | European manufacturers capture recreational players migrating toward softer compression covers without US import premiums. |
| Direct-to-Consumer Fitting Platform Launch | Swing-speed-matched recommendation algorithms bypass traditional pro-shop markup structures and shift purchase authority to data-driven self-selection. |
| Biodegradable Core R&D Partnership | Corn-based rubber alternatives align with EU Green Deal mandates and attract sustainability-conscious municipal course procurement. |
| Controlled Asian Manufacturing Scale Expansion | Thailand and Vietnam production concentration lowers unit economics for mid-market urethane penetration against legacy Japanese and Korean bases. |
| Resort-Based Equipment Partnership Program | Arizona and Florida destination golf clusters accelerate refresh cycles through stay-and-play bundle inclusion, compressing brand switching costs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with golf equipment procurement managers at United States resort operators, compression molding technicians at Japanese and Korean manufacturing bases, EPA compliance officers at domestic Ball Plant facilities, and category buyers at big-box sporting goods retailers. Secondary validation drew from USGA conformance list archives, R&A equipment standard submissions, EPA rubber compounding emission enforcement records, and REACH chemical registration databases maintained by ECHA. Bottom-up unit volume estimates across construction types and cover materials triangulated against top-down market value assessments from customs trade data and channel shipment reports.
Calibration against historical price-performance tier compression and material substitution patterns informed projection modeling across the analysis window. Segmentation dimensions included construction layer count, cover chemistry, swing speed compression matching, end user category, and geographic regulatory cluster. CAGRs derived from regression analysis of equipment refresh cycle acceleration in resort-based amateur programs and participation rate trajectories in women and junior development initiatives. Industry-specific inputs incorporated USGA dimple pattern approval timeline distributions and petrochemical feedstock price volatility indices.
Sensitivities concentrate around EPA emission standard enforcement intensity, REACH chemical registration cost escalation, and India course development permitting velocity. Forecasts reflect documented assumptions regarding amateur participation demographic shifts and sustainable manufacturing mandate adoption timelines. Material shifts in USGA or R&A equipment conformance standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Rowing Machine Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Running Gear Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Europe Archery Equipment Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
North America Stand-Up Paddleboard Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Motocross Gears Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Mini Balance Beam Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Wetsuits Market