
 Inflatable Sleds Market | 2026-2036
Inflatable Sleds Market Size, Share, and Industry Trends Forecast 2026-2036
Inflatable Sleds Market Analytics
Heavy-duty specification tiers is unwinding across the inflatable sleds category as commercial operators replace fabric-based units with reinforced TPU constructions. Airhead Sports Group leverages its watersports manufacturing infrastructure to cross-apply seam-welding expertise into snow-grade inflatable sleds. Blue Wave Sports Inc. anchors its position through direct distribution to regional ski resorts across the Mountain West. Paricon Inc. specializes in hybrid rigid-inflatable designs that bridge consumer and commercial use cases.
Inflatable sleds are pneumatically supported sliding devices constructed from laminated polymer fabrics, typically incorporating multiple air chambers and welded seams to maintain structural integrity under dynamic loads and temperature cycling; their primary function is to transport riders across snow surfaces for recreation, competition, or emergency evacuation. Recreational sleds dominate unit volume through mass retail channels, while rescue sleds command premium pricing from emergency services procurement contracts. TPU material adoption is accelerating fastest among racing sleds where weight reduction and rebound resilience determine competitive outcomes.
FDA oversight of phthalate content in vinyl formulations shapes material selection for products marketed to children, while ASTM F963 toy safety standards govern impact resistance and labeling requirements for family-oriented sleds. The Consumer Product Safety Commission monitors incident reporting to inform recall thresholds and design mandates. Stakeholders must monitor evolving state-level liability frameworks for commercial tubing operations as insurance underwriters tighten risk assessment criteria.
Market Dynamics
Commercial tubing operators across the United States are replacing fabric-based units with reinforced TPU constructions, creating a specification upgrade cycle that compresses replacement intervals while elevating performance thresholds for puncture resistance and thermal stability.
Growth Catalysts
- TPU Material Innovation:Thermoplastic polyurethane laminates deliver superior rebound resilience and sub-zero flexibility, enabling racing sleds to achieve weight reductions that translate directly into competitive timing advantages.
- ASTM F963 Alignment:Toy safety standard compliance opens mass retail channels for family-oriented sleds, expanding addressable consumer segments beyond specialty winter sports outlets.
- Mountain West Resort Concentration:Ski resorts in Colorado, Utah, and Idaho drive procurement volume for heavy-duty commercial units, establishing regional demand clusters that anchor manufacturer distribution strategies.
Market Restraints
- Petrochemical Input Volatility:TPU and PVC resin prices fluctuate with crude oil derivatives, squeezing margin structures for manufacturers lacking backward integration into polymer compounding.
- Asian Supply Concentration:Laminated fabric and welded seam equipment production clusters in Guangdong and Zhejiang provinces, exposing procurement timelines to trans-Pacific logistics disruptions.
- Phthalate Regulatory Friction:FDA oversight of vinyl formulations restricts material options for children's products, forcing reformulation investments that delay product launches.
Strategic Opportunities
- Emergency Services Expansion:Rescue sled procurement contracts from alpine search-and-rescue units and ski patrol operations command premium pricing with multi-year service agreements.
- Hybrid Design Convergence:Rigid-inflatable combinations bridge consumer and commercial use cases, capturing buyers seeking durability without full commercial-grade specifications.
- Direct Resort Distribution:Bypassing traditional sporting goods retailers through direct sales agreements with regional winter parks captures margin and enables specification customization.
Industry Challenges
- Welding Technician Scarcity:RF and hot-air seam welding expertise for TPU laminates concentrates in watersports manufacturing regions, forcing sled producers to compete for skilled labor.
- Multi-Chamber Testing Complexity:ASTM pressure integrity validation for redundant air chamber designs extends certification timelines, delaying commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflatable Sleds Market |
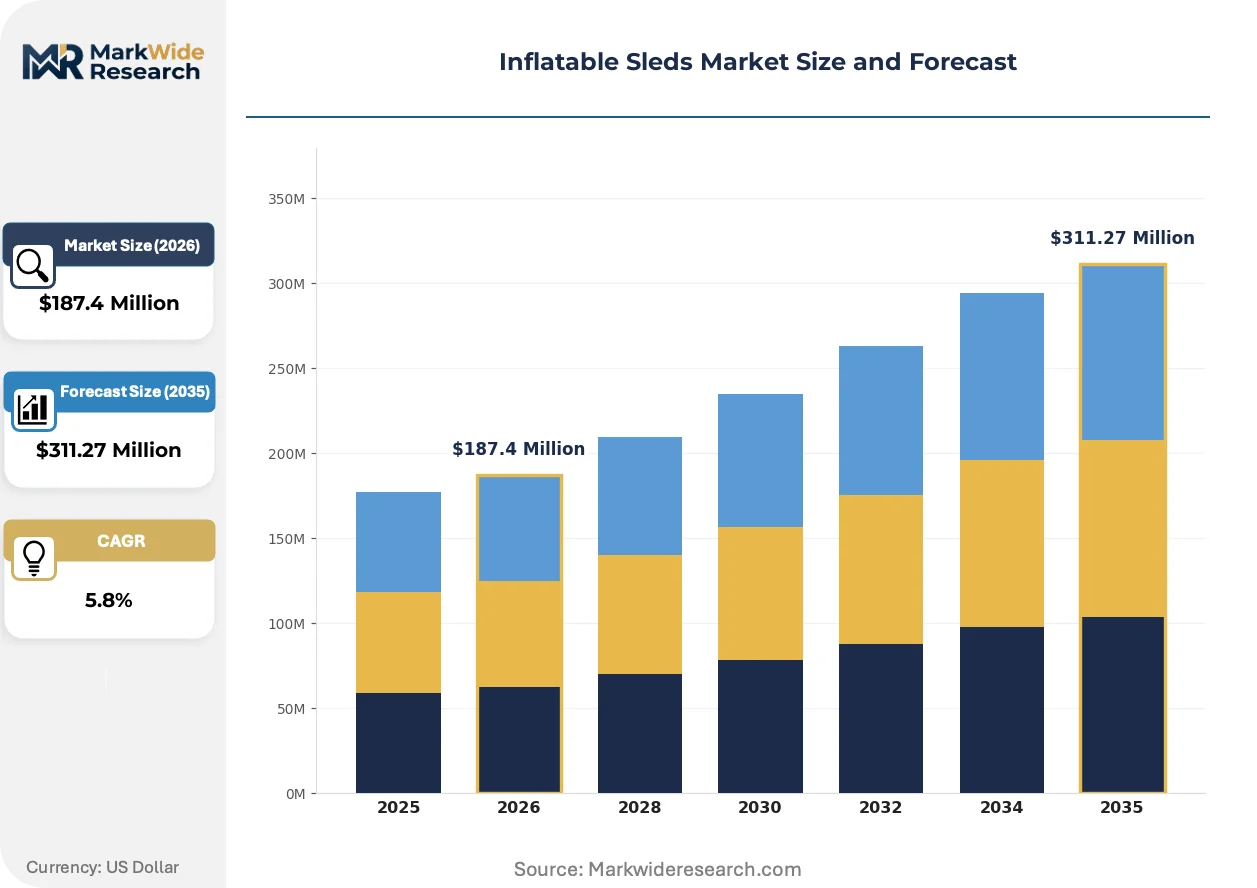
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recreational Sleds, Rescue Sleds, Racing Sleds, Heavy-Duty Sleds Material: Vinyl, PVC, Nylon, TPU Application: Leisure Activities, Emergency Response, Competitive Sports, Snow Recreation End User: Families, Outdoor Enthusiasts, Schools, Emergency Services |
| Companies Covered | Airhead Sports Group, Blue Wave Sports Inc., Paricon Inc., EMSCO Group, Sunkid, A-DUDU, L.L.Bean, Slippery Racer, KL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflatable Sleds Market Evolving Landscape
Material science advances and procurement model evolution are compressing product lifecycles while fragmenting the competitive landscape between mass-market and specialized performance tiers.
Seam-welding technology is bifurcating the manufacturing base. RF welding delivers hermetic bonds for racing and rescue applications where chamber integrity is non-negotiable. Commercial tubing operators adopt hot-air welded units for cost efficiency at scale. The technology split enables mid-tier producers to capture resort contracts while premium specialists dominate performance segments.
REACH substance restrictions in the European Union are accelerating phthalate-free formulation adoption. Manufacturers serving export markets must maintain dual material streams, increasing inventory complexity. Children's product lines face the steepest compliance burden, with reformulation cycles now matching seasonal production windows.
Resort procurement committees are consolidating vendor relationships around multi-year tubing fleet replacements. Direct manufacturer partnerships displace traditional sporting goods distributors in the Mountain West. Colorado and Utah operators lead this consolidation, negotiating specification customization in exchange for volume commitments.
Inflatable Sleds Market Segmentation
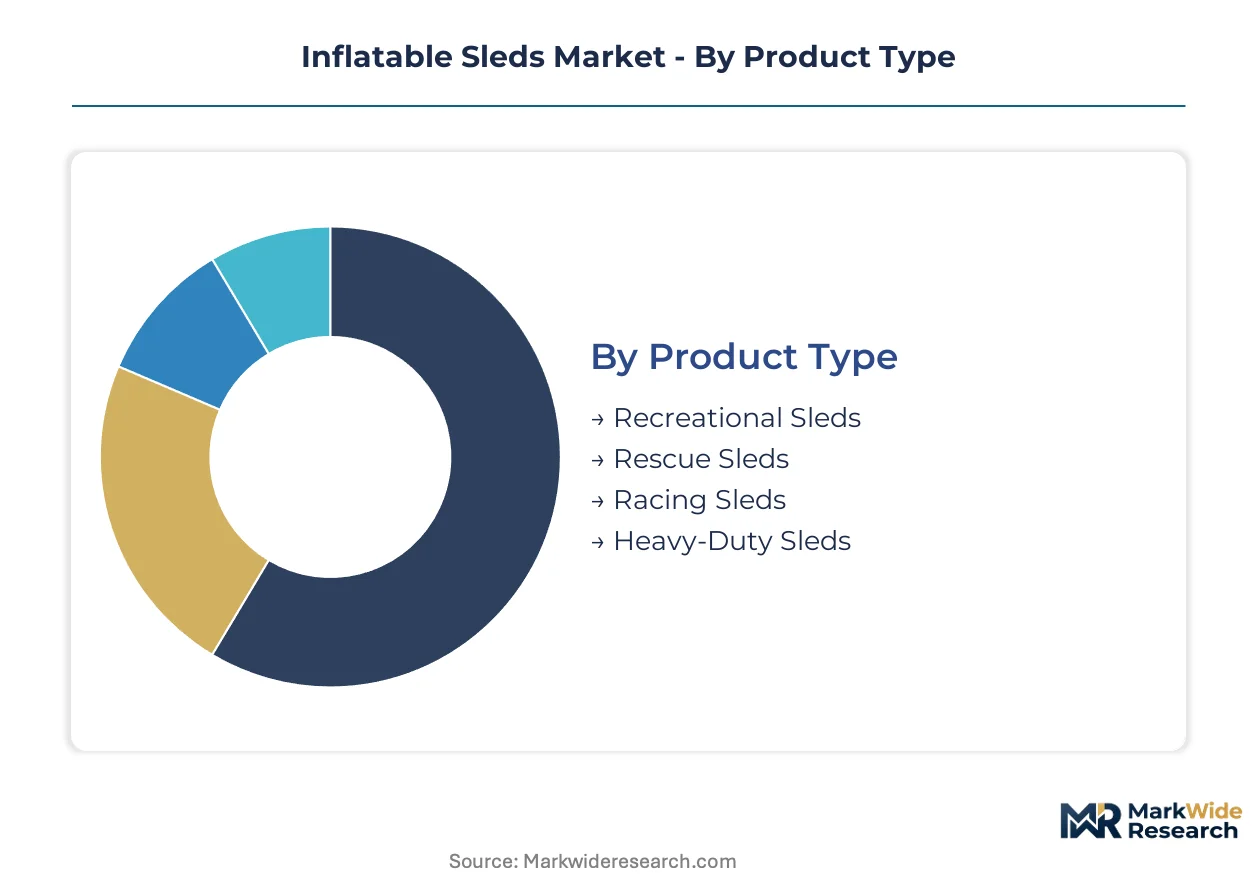
Segmentation in the inflatable sleds market reveals divergent margin structures across product tiers, with commercial-grade specifications commanding premium pricing while mass-market recreational units drive volume throughput. Material selection and end-user procurement patterns create distinct competitive arenas that manufacturers must navigate simultaneously.
Product Type:
Margin concentration pools in specialized performance tiers where certification requirements and durability specifications erect barriers to commodity competition.
- Recreational Sleds:Laminated polymer constructions with multiple air chambers target family consumers through mass retail channels. Demand clusters in the United States where seasonal replacement cycles align with winter park visitation patterns and holiday purchasing windows.
- Heavy-Duty Sleds:Reinforced TPU constructions with welded seam integrity support commercial tubing operations across Colorado, Utah, and Idaho ski resorts. Mountain West resort procurement committees are consolidating vendor relationships around multi-year fleet replacements that prioritize puncture resistance and thermal stability in sub-zero conditions.
- Rescue Sleds:Alpine search-and-rescue units and ski patrol operations drive procurement of rigid-inflatable hybrid designs with premium pricing structures.
- Racing Sleds:Weight-optimized TPU laminates serve competitive timing applications where rebound resilience determines outcomes.
Heavy-Duty Sleds holds installed capacity. Racing Sleds is rotating up the share rankings.
Material:
Cost tier stratification separates petrochemical-derived commodity inputs from engineered polymer laminates with specialized welding requirements.
- TPU:Thermoplastic polyurethane delivers superior sub-zero flexibility and rebound resilience for racing and commercial applications. FDA oversight of phthalate alternatives in children's products accelerates TPU adoption for family-oriented sleds seeking ASTM F963 compliance.
- Vinyl:PVC-based formulations face regulatory friction from FDA phthalate restrictions, forcing reformulation investments that compress margins on budget-tier recreational units.
- PVC:Standard laminated constructions serve cost-sensitive mass market segments with established supply chains.
- Nylon:Fabric-reinforced laminates bridge mid-tier performance requirements with moderate durability specifications.
TPU commands pricing premiums. Vinyl is losing share fastest to compliant alternatives.
Application:
Volume concentration sits in seasonal leisure consumption, while contract-based procurement stabilizes revenue for emergency and competitive segments.
- Snow Recreation:Commercial tubing operations and ski resort rentals drive the highest unit throughput with concentrated seasonal demand peaks.
- Emergency Response:Alpine rescue units and ski patrol services procure through multi-year service agreements with specification customization requirements.
- Leisure Activities:Family consumers purchase through mass retail channels with price sensitivity shaping material selection toward vinyl and PVC options.
- Competitive Sports:Racing organizations prioritize weight reduction and rebound resilience, creating technology leadership opportunities for TPU specialists.
Snow Recreation anchors volume throughput. Emergency Response is climbing the fastest on contract value expansion.
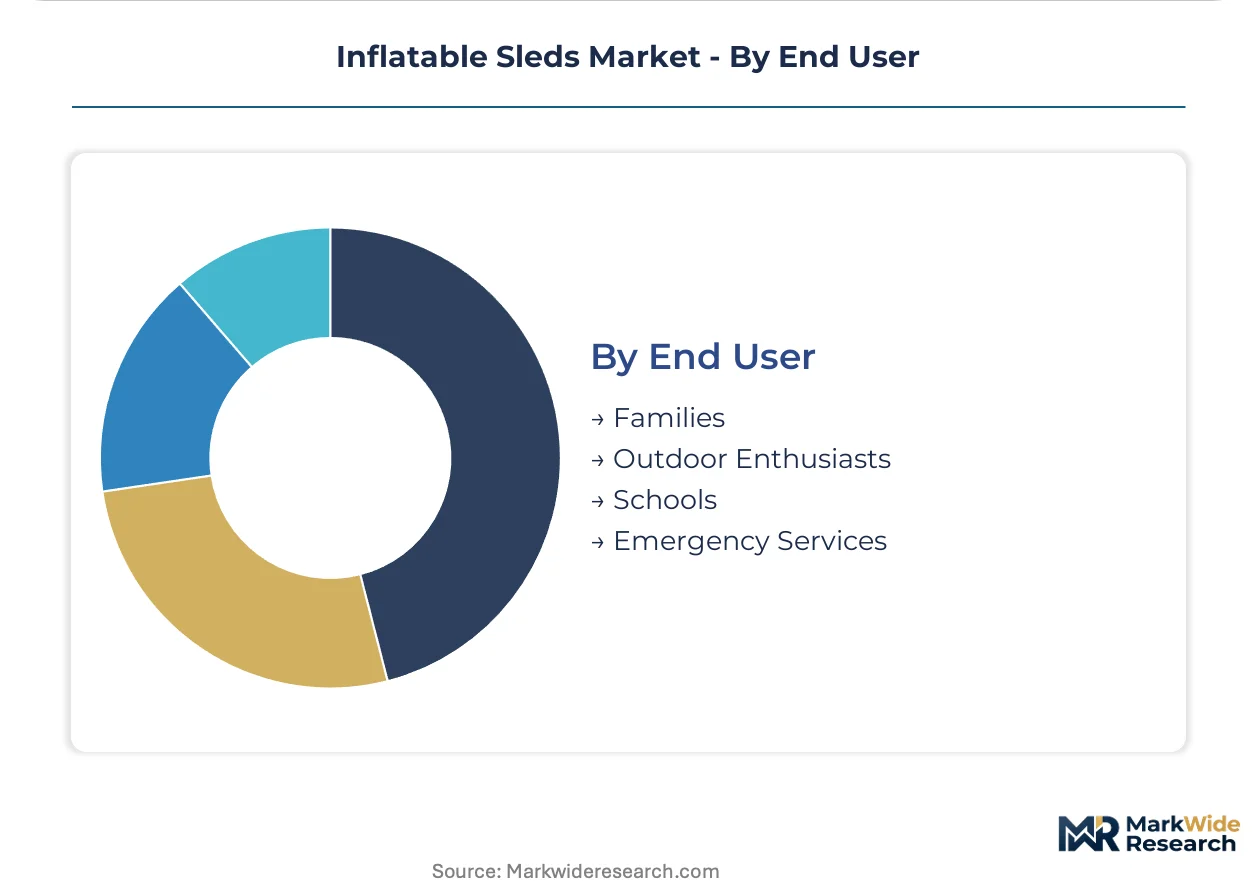
End User:
Customer type determines procurement channel access and compliance burden intensity, with institutional buyers demanding documentation that family consumers bypass.
- Emergency Services:Alpine search-and-rescue units and ski patrol operations require redundant air chamber designs with ASTM pressure integrity validation, extending certification timelines but securing multi-year agreements.
- Families:Mass retail purchasers drive seasonal volume through big-box sporting goods channels, with FDA phthalate restrictions shaping available material options for children's products.
- Outdoor Enthusiasts:Individual consumers seeking performance specifications bridge recreational and competitive use cases through specialty retailers.
- Schools:Institutional procurement with liability considerations favors documented safety compliance over price minimization.
Emergency Services holds contract value concentration. Families generates the steepest seasonal volume spikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of TPU-laminated fabrics and welded seam equipment concentrate in Asian manufacturing clusters, while import demand clusters in North American and European winter recreation markets where domestic fabrication capacity remains limited.
United States
Commercial tubing operators across Colorado, Utah, and Idaho drive procurement of heavy-duty TPU constructions with multi-year fleet replacement cycles. ASTM F963 toy safety standards govern impact resistance and labeling for family-oriented sleds sold through mass retail channels. Mountain West resort committees in Vail, Park City, and Jackson Hole anchor manufacturer distribution strategies through direct vendor consolidation.
Germany
Alpine rescue units in Bavaria and Baden-Württemberg procure rigid-inflatable hybrid designs for emergency evacuation contracts with premium pricing structures. REACH substance restrictions accelerate phthalate-free formulation adoption across children's product lines. Manufacturing clusters around Munich and Stuttgart specialize in RF welding equipment for racing and rescue applications.
China
Guangdong and Zhejiang provinces host laminated fabric production and welded seam equipment clusters serving export markets. NMPA oversight shapes material compliance for medical-adjacent rescue sled applications. Shenzhen-based fabricators supply TPU laminates to North American and European OEMs through established trans-Pacific logistics channels.
Canada
Ski patrol operations across British Columbia and Alberta drive seasonal procurement of rescue sleds with redundant air chamber designs. Health Canada monitors phthalate content in vinyl formulations marketed to children, aligning with FDA-equivalent safety thresholds. Quebec winter parks in Mont-Tremblant and Quebec City anchor regional distribution for commercial tubing equipment.
Japan
Competitive racing organizations prioritize weight-optimized TPU laminates where rebound resilience determines timing outcomes. METI industrial standards govern polymer material specifications for recreational equipment exports. Nagoya-area manufacturers specialize in hot-air welding systems for cost-efficient commercial-grade production.
Inflatable Sleds Market Competitive Landscape
Concentration sits with mid-tier specialists that bridge mass-market recreational units and premium commercial-grade specifications. The vendor base stratifies across three tiers: watersports cross-over manufacturers leveraging seam-welding infrastructure, dedicated winter recreation fabricators with resort distribution relationships, and emergency equipment specialists serving alpine rescue contracts. Dominant competitive moves include backward integration into polymer compounding to offset petrochemical input volatility, and direct sales agreements with regional winter parks that displace traditional sporting goods distributors.
Among North American recreational equipment manufacturers, Airhead Sports Group, Blue Wave Sports Inc., and Paricon Inc. occupy distinct positioning within the competitive structure. Airhead Sports Group exemplifies the watersports cross-over archetype, applying established manufacturing infrastructure to adjacent winter applications. Blue Wave Sports Inc. represents the resort-direct distribution model, anchoring relationships with Mountain West procurement committees. Paricon Inc. sits within the hybrid design specialization, bridging consumer durability expectations with commercial performance thresholds through rigid-inflatable construction approaches.
| Leading Market Players |
|---|
| Airhead Sports Group |
| Blue Wave Sports Inc. |
| Paricon Inc. |
| EMSCO Group |
| Sunkid |
| A-DUDU |
| L.L.Bean |
| Slippery Racer |
| KL Industries |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Guangdong and Zhejiang fabricators sits above seasonal norms, compressing lead times for TPU laminates while elevating price floors for North American resort procurement committees negotiating multi-year fleet replacements.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across heavy-duty and rescue sled tiers. Three-tier pricing structure across premium racing specifications, standard commercial tubing units, and economy recreational lines separates ASTM-certified chamber integrity from basic welded seam constructions. Cost compression in vinyl formulations is intensifying because FDA phthalate restrictions force reformulation investments without corresponding price recovery. Families purchasing through mass retail channels exhibit highest price sensitivity, while alpine search-and-rescue units prioritize documented pressure integrity over unit economics.
Supply Chain Analysis
Trans-Pacific container availability fluctuations from Shanghai to Long Beach directly impact landed costs for Mountain West resort procurement timelines. Guangdong and Zhejiang provinces host laminated fabric production clusters, while Germany and Japan supply RF and hot-air welding equipment. Raw material dependencies center on petrochemical-derived TPU and PVC resins, plus specialty polymer films from South Korea. Single-source vulnerability concentrates in welded seam equipment where Nagoya-area and Stuttgart-based manufacturers hold technical leadership. Distribution runs through direct manufacturer agreements with regional winter parks, displacing traditional sporting goods retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across recreational, commercial, and emergency tiers creates multiple viable positioning niches as resort procurement committees consolidate vendor relationships around performance customization.
For Market Incumbents: Fortify backward integration into polymer compounding to offset petrochemical input volatility threatening margin structures on TPU-heavy product lines. Deepen certification investments for ASTM F963 and REACH-aligned phthalate-free formulations to defend against emerging watersports cross-over manufacturers leveraging existing seam-welding infrastructure. Channel control through direct resort distribution agreements in Colorado and Utah anchors replacement cycle capture.
For New Entrants and Emerging Players: Anchor in hybrid rigid-inflatable design specialization where consumer durability expectations overlap with commercial performance thresholds, creating defensible positioning between mass retail and premium contract tiers. Target emergency response procurement in alpine regions of Germany and Canada where multi-year service agreements stabilize revenue. Pursue RF welding technician training partnerships with Nagoya-area equipment suppliers as a go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors TPU material specialists with demonstrated sub-zero flexibility validation and established resort distribution relationships. Long-term viability rests on racing and rescue tier concentration where certification barriers protect pricing power. Watch for inflection signals in Mountain West resort capital expenditure announcements indicating fleet replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| TPU Material Backward Integration | Captive supply of thermoplastic polyurethane laminates insulates margin structures from crude oil derivative volatility. |
| Direct Resort Distribution Expansion | Bypassing traditional sporting goods retailers captures margin and enables specification customization for Colorado and Utah procurement committees. |
| Phthalate-Free Formulation Investment | REACH and FDA compliance opens mass retail channels for family-oriented sleds while forcing vinyl-dependent competitors into costly reformulation cycles. |
| RF Welding Technician Training Programs | Addressing skilled labor scarcity in seam-welding expertise secures production capacity for racing and rescue tier contracts. |
| Emergency Services Contract Pursuit | Alpine search-and-rescue and ski patrol multi-year agreements command premium pricing with specification customization requirements. |
Research Methodology
A spread of perspectives from ski resort procurement managers, TPU laminate plant engineers, RF welding equipment specialists, and emergency services contract administrators converged on the working assumptions. Primary fieldwork combined with secondary validation drew from ASTM standards documentation, FDA phthalate restriction filings, customs trade data on polymer fabric imports, and SEC disclosures from recreational equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across product type, material, and end user dimensions.
Segmentation dimensions modeled include product tier, material composition, application context, and end user procurement channel across the projection horizon. CAGRs derived from historical replacement cycle analysis and forward-looking resort capital expenditure patterns. Industry-specific forecast inputs incorporated Mountain West snowpack variability correlations with seasonal demand peaks and welding technician availability constraints on production capacity expansion.
Material uncertainties — petrochemical price volatility, trans-Pacific logistics disruptions, and state-level liability framework evolution for commercial tubing operations — sit outside the modeled envelope. Forecasts reflect documented assumptions on replacement cycle compression and TPU adoption trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Padel Balls Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Asia-Pacific Bicycle Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Surface Water Sports Equipment Market