
 Mobile Tracking Software Market | 2026-2036
Mobile Tracking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Tracking Software Market Analysis
GDPR enforcement is shifting the cost-of-entry calculus for mobile tracking software vendors serving European enterprise clients. Geotab Inc. leverages its in-house telematics stack to sustain compliance advantages across regulated fleets. Verizon Connect anchors its position through channel control over North American commercial vehicle networks. Spireon, Inc. differentiates via specialization in asset recovery protocols for automotive finance verticals.
Mobile tracking software encompasses GPS, cellular, Wi-Fi, and RFID-enabled platforms that capture, transmit, and analyze location data in real time, typically operating through cloud architectures with sub-meter accuracy thresholds for commercial fleet coordination. The primary purpose centers on optimizing asset visibility, route efficiency, and regulatory compliance across logistics, public safety, and personal security operations. Cloud-based deployment models command the widest enterprise uptake due to lower infrastructure overhead and faster integration cycles. Real-Time Tracking solutions lead solution type revenue pools, while Fleet Management applications capture disproportionate margin concentration from large-scale logistics contracts. SaaS delivery formats within the deployment model category are expanding fastest among small business adopters seeking subscription flexibility.
The EU AI Act, GDPR, and FCC equipment authorization standards collectively shape product development roadmaps and market access conditions for tracking software vendors. GDPR's data localization mandates force architecture redesigns for cross-border fleet operators, while FCC certification requirements govern cellular module deployment across United States commercial vehicle fleets. Stakeholders must monitor emerging algorithmic transparency obligations under the EU AI Act that will soon classify predictive routing and driver behavior analytics as high-risk AI systems.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing vendors to reengineer predictive routing and driver behavior analytics as high-risk AI systems, compressing development timelines and certification costs for cross-border fleet operators.
Growth Catalysts
- GDPR data localization:Architecture redesigns for European enterprise fleets create recurring compliance service revenue streams for certified platform providers.
- Logistics digitization:United States freight carriers deploy cloud-native tracking to satisfy shipper visibility requirements and reduce dwell-time penalties.
- Public safety investments:Indian municipal governments expand GPS-enabled emergency response coordination across urban police and ambulance networks.
Market Restraints
- Cellular module supply concentration:FCC equipment authorization bottlenecks and semiconductor fab capacity limits constrain hardware deployment velocity for United States commercial vehicle fleets.
- Cross-border data friction:GDPR's territorial scope conflicts with fleet operators running unified global platforms, forcing redundant infrastructure spend.
- RFID range limitations:Indoor asset tracking in dense warehouse environments requires supplementary beacon deployments, elevating total cost of ownership.
Strategic Opportunities
- Small business SaaS penetration:Subscription flexibility models attract underpenetrated German Mittelstand logistics operators seeking pay-per-vehicle economics.
- EU Green Deal alignment:Carbon reporting mandates create demand for fuel-efficiency analytics modules that integrate route optimization with emissions tracking.
- AI-telemetrics convergence:Predictive maintenance algorithms fused with real-time location data open aftermarket service contracts for automotive finance verticals.
Industry Challenges
- Embedded systems engineering scarcity:Vendors struggle to hire firmware developers capable of optimizing sub-meter GPS accuracy on low-power cellular chipsets.
- Legacy fleet integration:Retrofitting CAN bus protocols into pre-2010 commercial vehicles demands custom hardware adapters that extend deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Tracking Software Market |
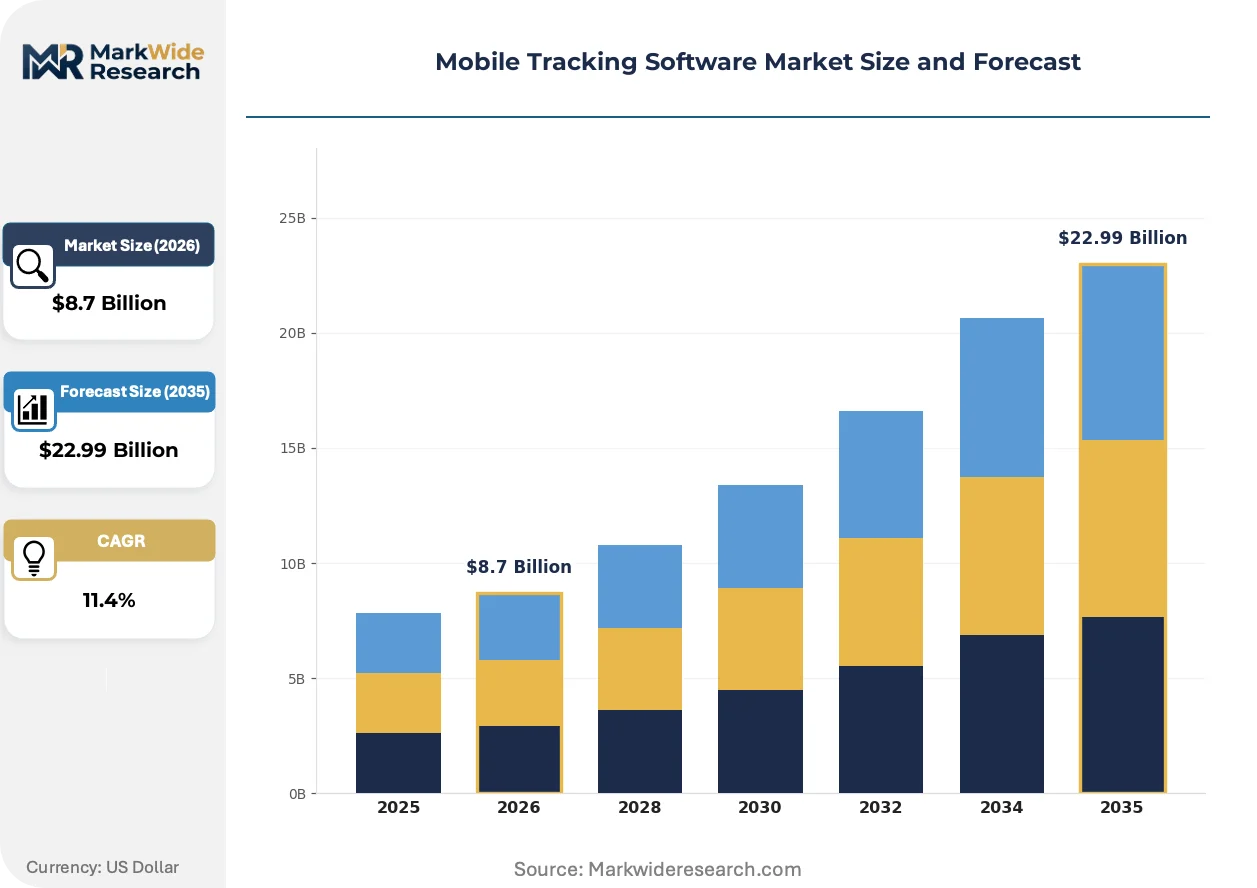
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
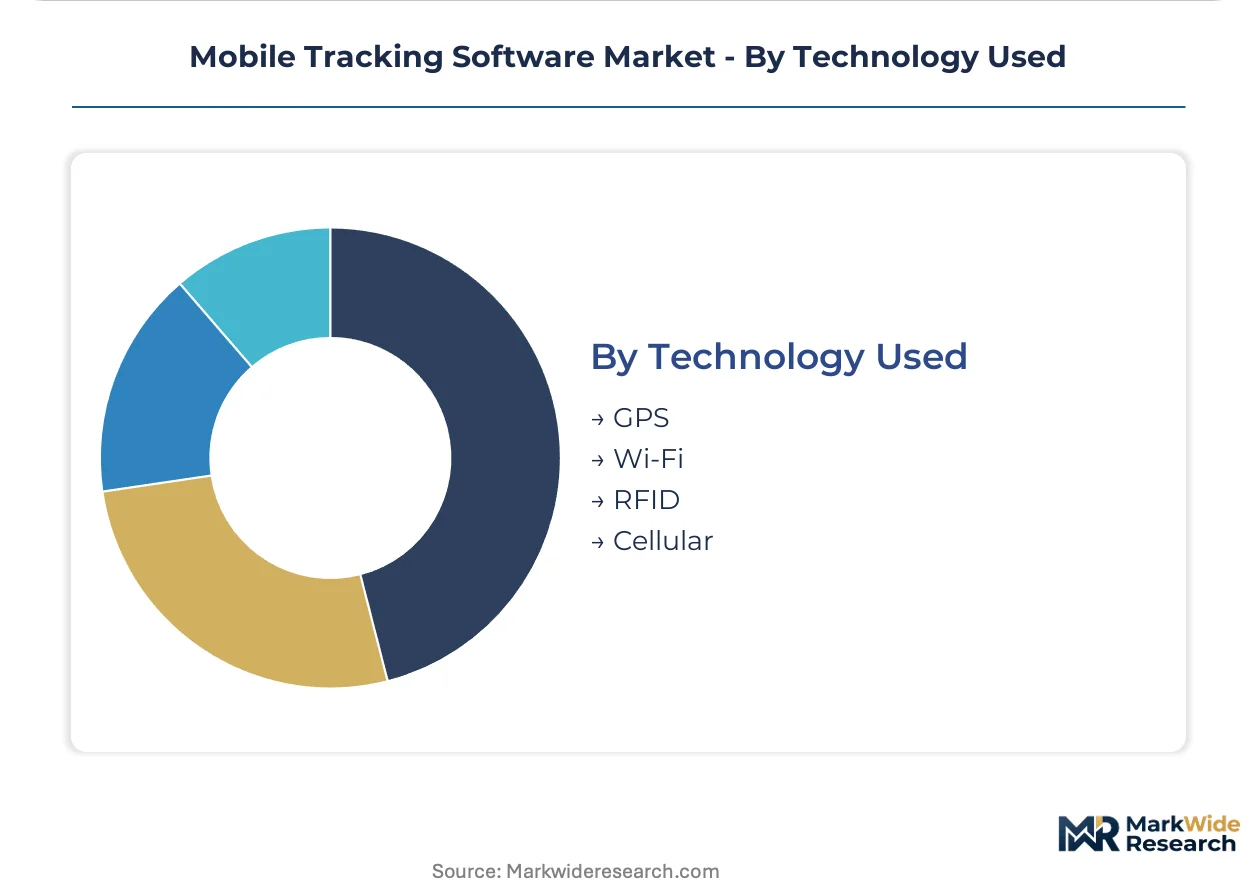
| Segmentation | Solution Type: Real-Time Tracking, Geofencing, Fleet Management, Personal Safety Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS End User Segment: Small Businesses, Enterprise, Government, Individuals Technology Used: GPS, Wi-Fi, RFID, Cellular |
| Companies Covered | ORBCOMM Inc., Verizon Connect, Spireon, Inc., Wasp Barcode Technologies, Geotab Inc., NFC Group, Vix Technology, CalAmp Corp., mSpy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Tracking Software Market Emerging Trajectories
Edge computing architectures are relocating processing from cloud data centers to vehicle-mounted gateways, reducing latency for safety-critical applications while complicating software update distribution logistics.
AI-driven predictive routing is rewriting fleet dispatch economics by anticipating traffic congestion and delivery window failures before they materialize. Large logistics operators in Germany and the United States are piloting these systems at scale. The technology is compressing margins for vendors selling static route optimization tools that lack real-time adaptive capabilities.
The EU AI Act's high-risk system classification will subject driver behavior scoring algorithms to conformity assessment procedures and human oversight requirements. Vendors serving European markets must document training data provenance and model interpretability. Fleet management platforms with embedded video telematics face the steepest compliance redesigns ahead of the 2026 enforcement deadline.
Subscription unbundling is fragmenting traditional all-in-one fleet software contracts into modular components. Small and mid-sized United States carriers now procure GPS tracking, fuel card integration, and compliance logging from separate specialists rather than single-vendor suites. This pattern concentrates price pressure on bundled platform providers while opening niche opportunities for best-of-breed analytics vendors.
Mobile Tracking Software Market Segmentation

Mobile tracking software segments diverge sharply by integration depth, with standalone applications serving personal safety use cases while embedded systems dominate fleet coordination. Vendors must calibrate architecture choices to deployment complexity, as cloud-native stacks displace on-premise installations across logistics operators.
Solution Type:
Real-Time Tracking and Fleet Management anchor enterprise deployments through deep ERP and telematics integration, while Geofencing and Personal Safety operate more frequently as standalone modules or mobile applications.
- Real-Time Tracking:Continuous location capture via GPS, cellular, and Wi-Fi triangulation with sub-meter accuracy thresholds for commercial vehicle coordination. Demand concentrates among United States freight carriers satisfying shipper visibility mandates and reducing dwell-time penalties under tightening service-level agreements.
- Fleet Management:Unified platforms integrating route optimization, driver behavior analytics, and regulatory compliance logging through cloud architectures. German logistics operators lead procurement volumes as EU Green Deal carbon reporting requirements fuse fuel-efficiency tracking with location data.
- Geofencing:Perimeter-based alerting systems triggering notifications when assets enter or exit defined boundaries. Construction equipment rental firms in India deploy these tools to mitigate theft exposure across dispersed job sites.
- Personal Safety:Consumer-facing applications delivering location sharing, emergency alerting, and journey monitoring for individual users. Indian municipal governments expand adoption through police-integrated emergency response networks in urban centers.
Volume placements concentrate in Fleet Management; the faster expansion belongs to Real-Time Tracking.
Deployment Model:
Cost tier stratification separates capital-intensive on-premise installations from subscription-based SaaS offerings, with hybrid architectures emerging as a compromise for security-conscious mid-market operators.
- Cloud-Based:Fully hosted platforms eliminating infrastructure ownership through multi-tenant architectures and API-first integration. United States small businesses drive fastest adoption as pay-per-vehicle economics replace upfront licensing commitments.
- SaaS:Subscription delivery with modular component selection allowing procurement of GPS tracking, fuel card integration, and compliance logging from separate specialists. German Mittelstand logistics operators favor this flexibility over bundled platform contracts.
- On-Premise:Self-managed installations retaining data sovereignty through private server infrastructure. Government agencies in India mandate these deployments for sensitive law enforcement and defense applications.
- Hybrid:Split architectures processing sensitive telemetry on-premise while leveraging cloud analytics for non-critical workloads. European fleet operators adopt this pattern to satisfy GDPR data localization without sacrificing scalability.
Cloud-Based deployments capture the widest enterprise uptake; SaaS formats are climbing the fastest among underpenetrated small business segments.
End User Segment:
Customer type determines feature complexity and sales cycle length, with Enterprise and Government clients demanding customization while Individuals and Small Businesses prioritize immediate deployment.
- Enterprise:Large-scale logistics, utilities, and telecommunications operators requiring multi-thousand vehicle visibility with predictive maintenance integration. These contracts concentrate margin pools through multi-year service agreements.
- Government:Municipal, state, and national agencies deploying tracking for emergency response, public transit, and defense logistics. Indian urban police and ambulance networks exemplify this segment's public safety orientation.
- Small Businesses:Regional carriers and service fleets with sub-hundred vehicle counts seeking rapid deployment without dedicated IT resources. United States freight brokers dominate this tier's procurement velocity.
- Individuals:Consumer subscribers accessing family safety, pet tracking, and personal security applications through mobile-first interfaces. This segment exhibits highest churn and lowest per-account revenue.
Enterprise contracts dominate absolute revenue; Small Businesses represent the steepest expansion trajectory as SaaS penetration accelerates.
Technology Used:
Maturity curves separate established GPS and cellular standards from emerging Wi-Fi and RFID implementations, with accuracy requirements and infrastructure costs driving selection patterns.
- GPS:Satellite-based positioning delivering outdoor location accuracy to commercial fleet standards through established receiver modules. United States commercial vehicle regulations mandate GPS integration for hours-of-service compliance logging.
- Cellular:Network triangulation and dedicated IoT connectivity enabling real-time data transmission across wide geographic coverage. FCC equipment authorization standards govern module deployment and constrain hardware supply velocity.
- Wi-Fi:Short-range positioning leveraging known access point locations for indoor and urban canyon accuracy supplementation. Warehouse operators deploy Wi-Fi fingerprinting where GPS signals degrade.
- RFID:Passive and active radio-frequency identification for proximity-based asset detection in controlled environments. Dense warehouse applications require supplementary beacon deployments due to range limitations.
GPS and Cellular installations command the installed base; Wi-Fi positioning is gaining share fastest as indoor tracking requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Karnataka are concentrating mobile tracking software deployment for automotive and logistics verticals, while enterprise demand clusters around regulatory compliance corridors in Germany and the United States.
United States
Freight carriers across Texas and California deploy cloud-native tracking platforms to satisfy shipper visibility mandates and reduce dwell-time penalties under tightening service-level agreements. FCC equipment authorization standards govern cellular module deployment and constrain hardware supply velocity for commercial vehicle fleets. Chicago and Atlanta anchor Midwest and Southeast logistics digitization clusters where regional carriers consolidate telematics procurement.
Germany
Mittelstand logistics operators in Bavaria and North Rhine-Westphalia favor SaaS delivery formats with pay-per-vehicle economics over bundled platform contracts. EU Green Deal carbon reporting mandates fuse fuel-efficiency tracking with location data, forcing architecture redesigns for cross-border fleet operators. Stuttgart and Munich host automotive finance verticals deploying asset recovery protocols for vehicle leasing portfolios.
India
Municipal governments in Maharashtra and Telangana expand GPS-enabled emergency response coordination across urban police and ambulance networks. TRAI spectrum allocation policies shape cellular connectivity economics for IoT tracking deployments in dense urban corridors. Bangalore and Hyderabad concentrate software development talent for indigenous platform vendors serving domestic logistics digitization.
United Kingdom
Logistics operators in the Midlands and Southeast England navigate GDPR data localization mandates that conflict with unified global fleet platforms, forcing redundant infrastructure spend. CSRD disclosure requirements extend carbon reporting obligations to mid-market carriers previously exempt from sustainability auditing. Manchester and Birmingham anchor regional distribution networks piloting predictive routing algorithms for last-mile optimization.
Japan
Automotive manufacturers in Aichi Prefecture integrate tracking software into connected vehicle platforms for domestic and export markets. METI industrial digitization subsidies accelerate SME fleet operator adoption of cloud-based coordination tools. Tokyo and Osaka metropolitan areas concentrate demand for personal safety applications through police-integrated emergency response networks.
Mobile Tracking Software Market Vendor Landscape
United States producers anchor one tier; German and Canadian specialists hold compliance-advantaged positions in regulated European markets. The vendor base stratifies across integrated telematics stacks, vertical-specific recovery protocols, and modular SaaS platforms. Three archetypes dominate: full-stack platform providers, automotive finance vertical specialists, and component-focused hardware-software bundlers. Competitive dynamics center on channel control over commercial vehicle networks and certification velocity under evolving AI governance regimes.
Within the integrated platform tier, Geotab Inc. and Verizon Connect exemplify divergent geographic anchoring strategies, with the former leveraging in-house telematics development and the latter exercising distribution control over North American commercial vehicle networks. Spireon, Inc. occupies a specialized position in asset recovery verticals where automotive finance customers demand predictive analytics fused with real-time location data. These three anchors illustrate how compliance architecture, channel configuration, and vertical depth separate sustainable positioning from commodity pressure in tracking software markets.
| Leading Market Players |
|---|
| ORBCOMM Inc. |
| Verizon Connect |
| Spireon, Inc. |
| Wasp Barcode Technologies |
| Geotab Inc. |
| NFC Group |
| Vix Technology |
| CalAmp Corp. |
| mSpy |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up telematics specialists anchor supply concentration across cellular module procurement, translating FCC certification bottlenecks into pricing discipline for cross-border fleet operators while compressing margins for hardware-dependent entrants.
Pricing Analysis
Short lead-time premiums separate certified FCC module inventory from spot-market cellular chipsets facing semiconductor fab constraints. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth—enterprise SaaS subscriptions command premium positioning against pay-per-vehicle economy tiers for small business adopters. Cost compression in economy tiers intensifies as German Mittelstand logistics operators unbundle bundled platform contracts. Small businesses exhibit highest price sensitivity; enterprise multi-year service agreements demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Illinois anchor hub-and-spoke patterns for United States commercial vehicle fleet deployment. Hardware assembly concentrates in China, Mexico, and Taiwan; cellular IoT modules draw from Qualcomm and MediaTek fabrication networks. Single-source vulnerability runs through FCC-authorized module suppliers facing backlog accumulation. Distribution runs through channel partners controlling commercial vehicle network access rather than direct vendor-to-fleet relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular module supply concentration props pricing power for certified vendors, creating a supply-constrained market where FCC authorization velocity determines competitive survival.
For Market Incumbents: Lock in channel control over North American commercial vehicle networks before EU AI Act compliance deadlines force architecture redesigns. Deepen backward integration into in-house telematics stack development to sustain GDPR certification advantages against modular SaaS competitors. Prioritize firmware engineering capacity retention as embedded systems talent scarcity intensifies. For New Entrants and Emerging Players: The mid-market pricing gap between Geotab's premium enterprise positioning and economy-tier pay-per-vehicle models offers white-space capture for vertical-specific recovery protocol specialists. German Mittelstand logistics operators represent the most penetrable segment given their preference for unbundled subscription flexibility. Pursue automotive finance verticals in Stuttgart and Munich through predictive analytics fused with real-time location data as the go-to-market anchor. For Investors and Strategic Acquirers: EU AI Act high-risk system classification enforcement is the leading indicator that compliance-architecture vendors will command acquisition premiums over commodity tracking providers. Five-to-ten year viability favors vendors with in-house telematics development and GDPR-certified data localization infrastructure. Target acquisition archetype: mid-cap specialists with automotive finance vertical depth and FCC certification velocity. Monitor TRAI spectrum allocation policy shifts in India as the inflection signal for emerging market platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Architecture Investment | Positions vendors ahead of 2026 high-risk system classification deadlines for predictive routing algorithms. |
| Backward Integration into Cellular Module Design | Mitigates FCC authorization bottlenecks constraining hardware deployment velocity for United States fleets. |
| Vertical SaaS Unbundling for Mittelstand Logistics | Captures German mid-market demand for pay-per-vehicle economics over bundled platform contracts. |
| Predictive Maintenance Algorithm Development | Opens aftermarket service contracts with automotive finance verticals in Stuttgart and Munich clusters. |
| Edge Computing Gateway Deployment | Reduces latency for safety-critical applications while complicating software update distribution logistics. |
Methodological Framework
Independent corroboration across fleet operations executives, telematics platform engineers, cellular module procurement leads, and regulatory compliance officers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through FCC equipment authorization databases, TRAI spectrum allocation filings, EU AI Act implementation guidance, and SEC 10-K disclosures from listed telematics vendors. Bottom-up segmentation modeling triangulated against top-down market sizing from logistics digitization investment flows.
Comparable-period anchoring to historical fleet management software adoption curves calibrated the projection framework across the analysis window. Deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster dimensions segmented volume and value outputs. CAGRs derived from logistic operator capex trajectories, public safety investment commitments, and SaaS subscription velocity patterns. Cellular module supply constraints and GDPR data localization mandates fed directly into forecast sensitivity bands.
Inputs from FCC certification databases and EU regulatory guidance were available through the study window; gaps in real-time fleet operator procurement intention data introduce uncertainty bands around small business SaaS penetration assumptions. Forecasts reflect documented assumptions about compliance timeline adherence and semiconductor fab capacity normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Orchestration Tools Market
Software & Services
Global PPC Software Market
Software & Services
Test Management Software Market
Software & Services
Geomechanics Software and Service Market
Software & Services
Europe Servicenow Store Apps Market
Software & Services
Photo Editor App Market
Software & Services
Life Sciences Software Market
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Proxy Services and Software Market
Software & Services
Tech Support Services Market
Software & Services
RFP Software Market
Software & Services
Consignment Software Market
Software & Services
Co-Browsing Software Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
Vacation Rental Software Market
Software & Services
Global Online OCR Software Market