
 Collaborative Applications Market | 2026-2036
Collaborative Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Collaborative Applications Market Analysis
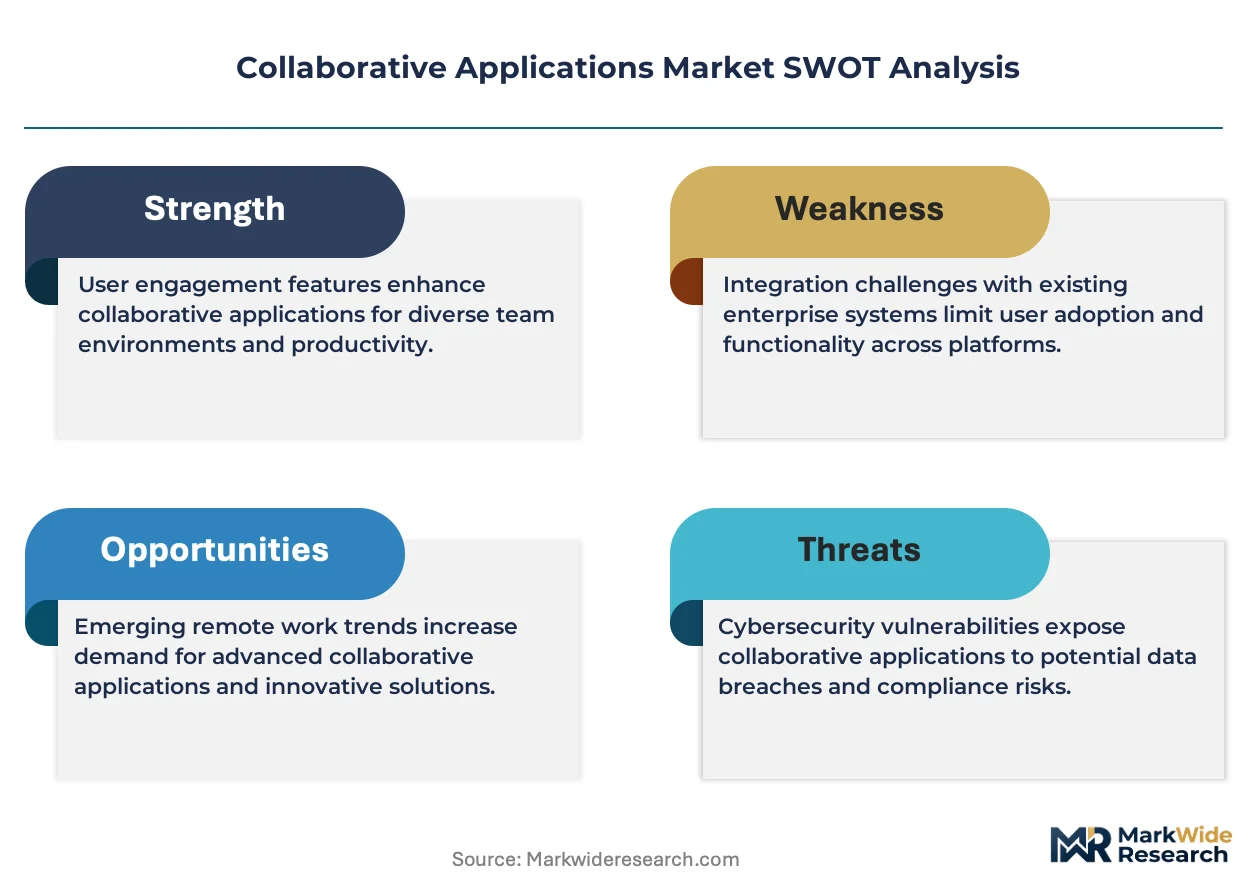
Buyer concentration among large enterprises is restructuring procurement patterns across the collaborative applications space. Microsoft leverages its Office 365 ecosystem to anchor enterprise-wide deployment contracts. Salesforce sustains competitive pressure through deep CRM integration with team messaging workflows. Atlassian specializes in developer-centric project management tools that dominate technical team adoption.
Collaborative applications encompass software platforms enabling real-time communication, shared document editing, task coordination, and synchronous video interaction across distributed users, typically delivered through cloud architectures with API-based interoperability. Their primary commercial purpose centers on reducing latency in organizational decision-making and eliminating siloed information flows. Video conferencing and project management represent the most mature revenue pools, while instant messaging segments capture faster growth among mobile-first small enterprises. Cloud-based deployment leads volume expansion, though hybrid configurations retain margin concentration in regulated industries requiring on-premise data residency.
FCC guidelines on broadband quality and GDPR data-localization mandates in Europe directly shape product architecture requirements for US and EU market access. ISO 27001 certification and SOC 2 compliance have become baseline gating factors for procurement by government agencies and healthcare organizations. Stakeholders must monitor how evolving AI transparency regulations redefine permissible automation features within document sharing and messaging platforms.
Market Dynamics
Enterprise migration from fragmented point solutions toward unified cloud-native platforms is compressing vendor margins while expanding addressable spend per seat. Procurement teams now bundle video conferencing, document collaboration, and workflow automation into single enterprise agreements, privileging ecosystem breadth over best-of-breed depth.
Growth Catalysts
- EU AI Act data governance:The European Union's artificial intelligence framework mandates algorithmic transparency in automated document processing, creating procurement urgency for compliant collaboration suites among multinationals with EU operations.
- Healthcare interoperability mandates:HIPAA-adjacent requirements for secure patient data sharing are accelerating deployment of FedRAMP-authorized platforms across United States hospital networks and telehealth providers.
- Developer toolchain convergence:Technical teams increasingly demand integrated code repositories, sprint planning, and real-time messaging within single environments, pulling spending toward unified DevOps platforms.
Market Restraints
- Data residency compliance costs:GDPR localization requirements and emerging sovereignty laws in India and China force redundant infrastructure deployment, elevating operational expenditure for cross-border collaboration services.
- Hyperscaler concentration:Cloud compute and storage provisioning concentrates among three dominant providers, exposing collaboration vendors to input price volatility and capacity allocation constraints.
- On-premise legacy entrenchment:Financial services and defense contractors maintain substantial investments in air-gapped systems, creating friction for full cloud migration despite security certification advances.
Strategic Opportunities
- India SME digitization:The country's Production-Linked Incentive schemes and TRAI broadband expansion are catalyzing first-time adoption of cloud collaboration among manufacturing small-and-medium enterprises previously reliant on consumer messaging tools.
- Conversational AI integration:Large language model deployment within meeting transcription and task extraction represents unpriced value capture for platforms that embed generative capabilities natively rather than through third-party APIs.
- Frontline worker enablement:Mobile-first messaging and shift coordination tools remain underpenetrated among retail, logistics, and hospitality workforces, offering expansion beyond knowledge-worker saturation.
Industry Challenges
- FedRAMP authorization timelines:Government and defense sector access requires 12-18 month certification cycles that delay revenue recognition and consume dedicated compliance engineering resources.
- Interoperability protocol fragmentation:Competing standards for real-time messaging and document formats create integration complexity for enterprises operating heterogeneous vendor environments.
- AI training data licensing:Ambiguous intellectual property frameworks around customer content used for model improvement generate legal exposure and procurement negotiation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collaborative Applications Market |
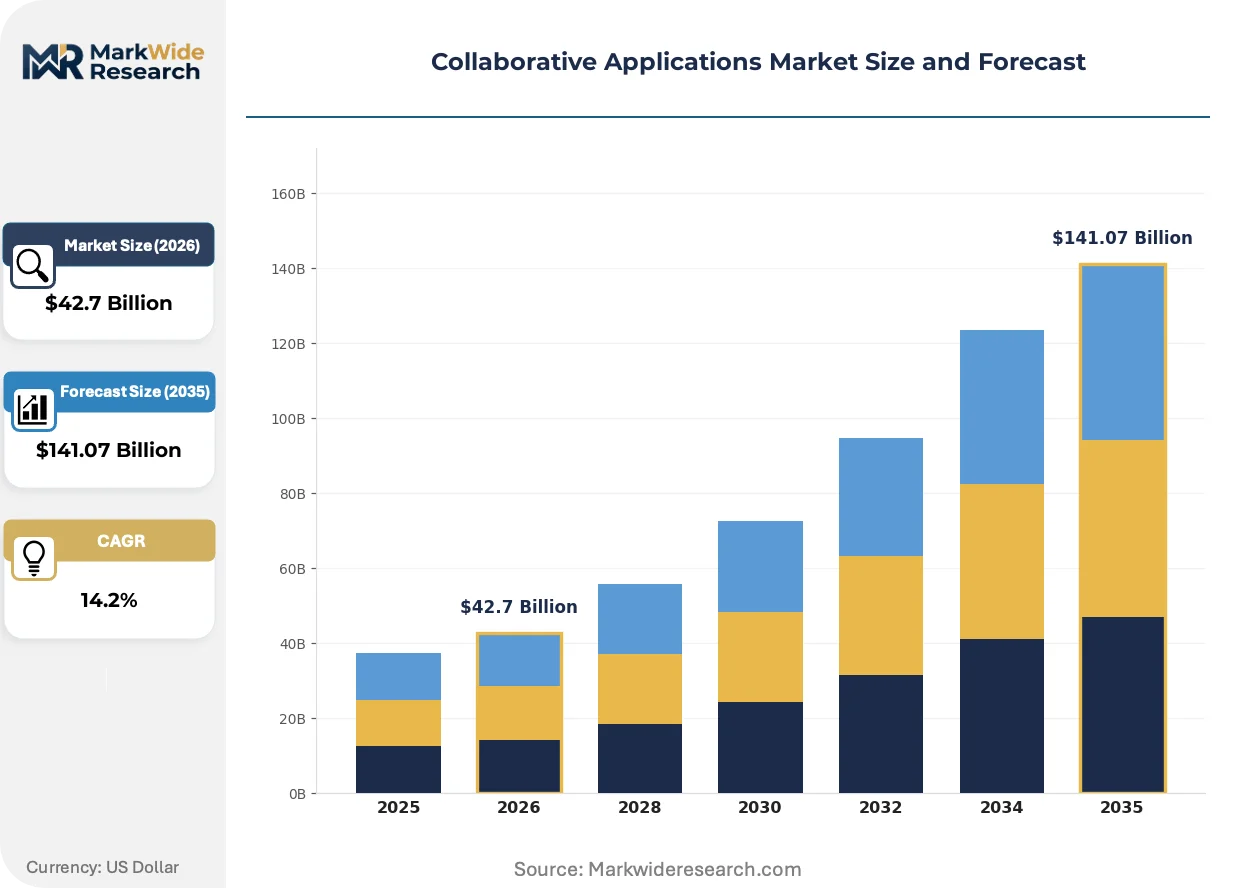
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $141.07 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Conferencing, Project Management, Document Sharing, Instant Messaging End User: Corporations, Educational Institutions, Nonprofits, Government Agencies Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Customer Type: Small Enterprises, Medium Enterprises, Large Corporations, Freelancers |
| Companies Covered | Microsoft, Google, Zoom, Salesforce, Cisco Systems, Atlassian, Slack Technologies, Zoho Corporation, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collaborative Applications Market Emerging Trajectories
Artificial intelligence capabilities are moving from peripheral features to core architectural components, restructuring how collaboration platforms capture and distribute organizational knowledge. This shift is compressing development cycles and redefining competitive differentiation around inference latency and contextual accuracy.
Embedded generative AI is consolidating meeting summarization, action item extraction, and draft document generation into unified workflow surfaces. Mid-market enterprises in the United States and United Kingdom are adopting these capabilities fastest, replacing standalone transcription services. The technology is consolidating previously discrete productivity tool categories into single-vendor subscriptions.
GDPR Article 17 right-to-erasure enforcement and the EU AI Act's risk classification system are forcing architectural redesign of retention policies and automated decision logging. European data protection authorities are imposing substantial administrative fines for inadequate audit trails in AI-assisted document routing. Healthcare and legal sectors across Germany, France, and the Netherlands are prioritizing platforms with built-in explainability dashboards and granular deletion controls.
Enterprise buying committees are consolidating vendor relationships and demanding outcome-based pricing tied to measurable productivity metrics rather than per-seat licensing. This compression is displacing departmental shadow IT proliferation and favoring platforms with robust usage analytics and success metric frameworks. The shift is most pronounced among Fortune 500 technology and professional services firms with mature procurement functions.
Collaborative Applications Market Segmentation
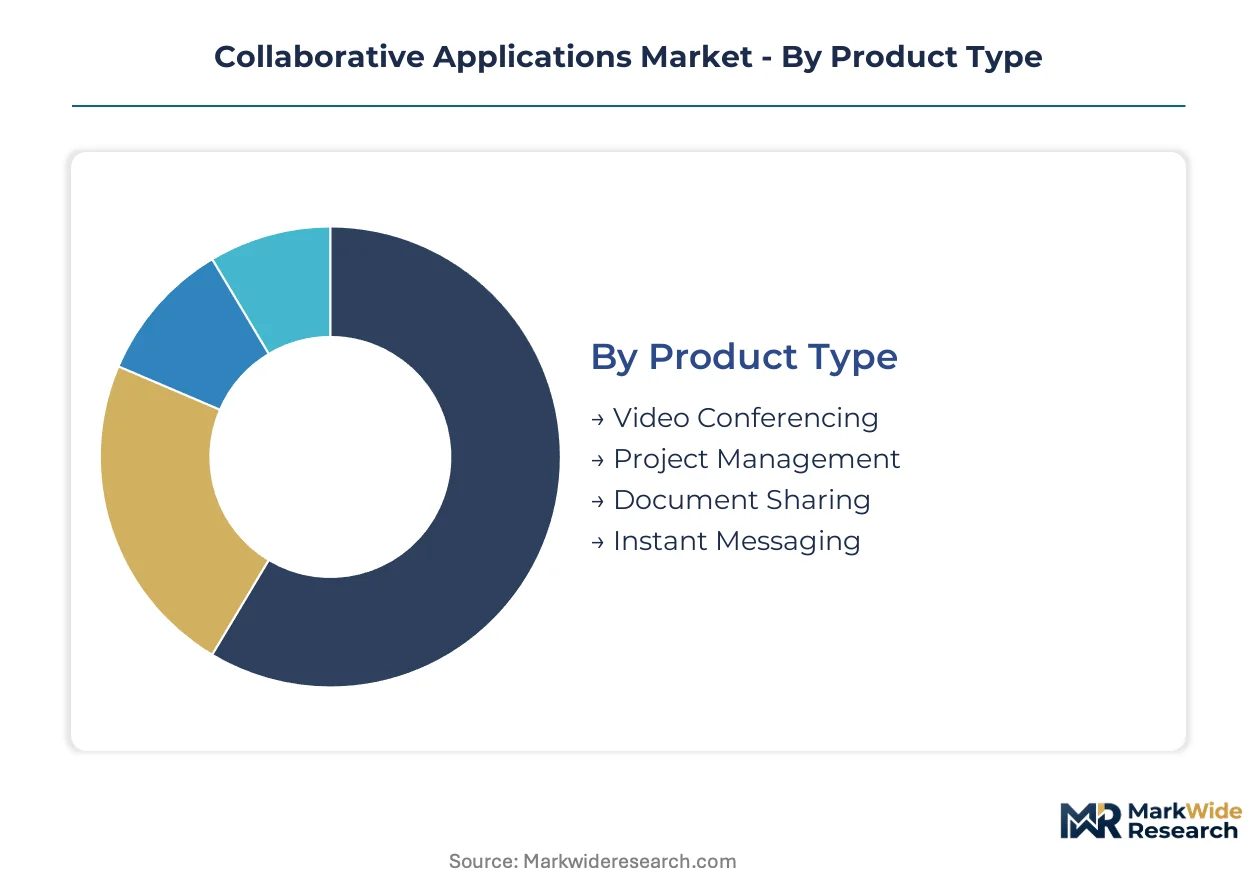
Segmentation in collaborative applications reveals how procurement patterns diverge across technical requirements, organizational scale, and regulatory exposure. Understanding these fault lines enables vendors to align product architecture with buyer constraints and pricing power.
Product Type:
Integration depth varies sharply across product categories, with some segments functioning as standalone entry points while others embed deeply into enterprise workflow stacks.
- Video Conferencing:Real-time audiovisual communication platforms with HD streaming, screen sharing, and recording capabilities. Demand concentrates among United States professional services firms replacing legacy telepresence systems, driven by hybrid work permanence and client-facing presentation requirements. HIPAA-compliant encryption and FedRAMP authorization now gate hospital and federal procurement.
- Project Management:Task scheduling, resource allocation, and milestone tracking platforms with Gantt visualization and dependency mapping. Technical teams in software development and construction verticals drive adoption, pulled by convergence with code repositories and sprint methodologies. API extensibility determines platform stickiness.
- Document Sharing:Cloud-native file storage with concurrent editing, version control, and granular permission structures. Legal and financial services in Germany and France prioritize GDPR Article 17 automated deletion and EU AI Act audit logging capabilities.
- Instant Messaging:Persistent chat channels with threading, search, and third-party bot integration. Mobile-first small enterprises in India and Southeast Asia adopt fastest, displacing consumer-grade WhatsApp and WeChat for business coordination.
Volume placements concentrate in Video Conferencing; the faster expansion belongs to Instant Messaging.
End User:
Organizational mission shapes security certification requirements and budget authorization thresholds across buyer categories.
- Corporations:Profit-driven enterprises with centralized IT procurement and multi-year enterprise agreements. Technology and financial services sectors in the United States and United Kingdom lead spending, prioritizing unified platforms over point solutions.
- Educational Institutions:K-12 districts and universities with FERPA compliance obligations and seasonal enrollment volatility. State funding cycles in the United States create lumped procurement patterns distinct from corporate SaaS subscriptions.
- Nonprofits:Mission-driven organizations with constrained IT budgets and volunteer-heavy staffing models. Grant-funded technology refresh cycles produce irregular upgrade timelines compared to commercial buyers.
- Government Agencies:Federal, state, and municipal entities with FedRAMP, StateRAMP, or CJIS certification mandates. Twelve-to-eighteen month authorization timelines delay vendor revenue recognition and require dedicated compliance engineering.
Revenue concentration sits with Corporations; Government Agencies present the steepest expansion trajectory for authorized vendors.
Deployment:
Infrastructure configuration determines data sovereignty compliance and operational expenditure structure for platform operators.
- Cloud-Based:Fully hosted SaaS delivery with automatic updates and elastic scaling. Dominates volume among United States mid-market enterprises lacking dedicated infrastructure teams.
- On-Premise:Self-managed server deployment within customer-controlled data centers. Defense contractors and European financial institutions maintain this model for air-gapped security and GDPR localization.
- Hybrid:Split architecture with sensitive data on-premise and compute-intensive functions cloud-hosted. German automotive manufacturers and Swiss pharmaceutical firms favor this pattern for R&D collaboration.
- Mobile:Native iOS and Android applications with offline synchronization and push notification delivery. Frontline workforces in retail, logistics, and hospitality drive adoption where desktop access is impractical.
Cloud-Based deployments capture the largest seat volumes; Mobile infrastructure is climbing the fastest among non-desk worker enablement.
Customer Type:
Organizational scale correlates with procurement sophistication, contract structure, and platform customization demands.
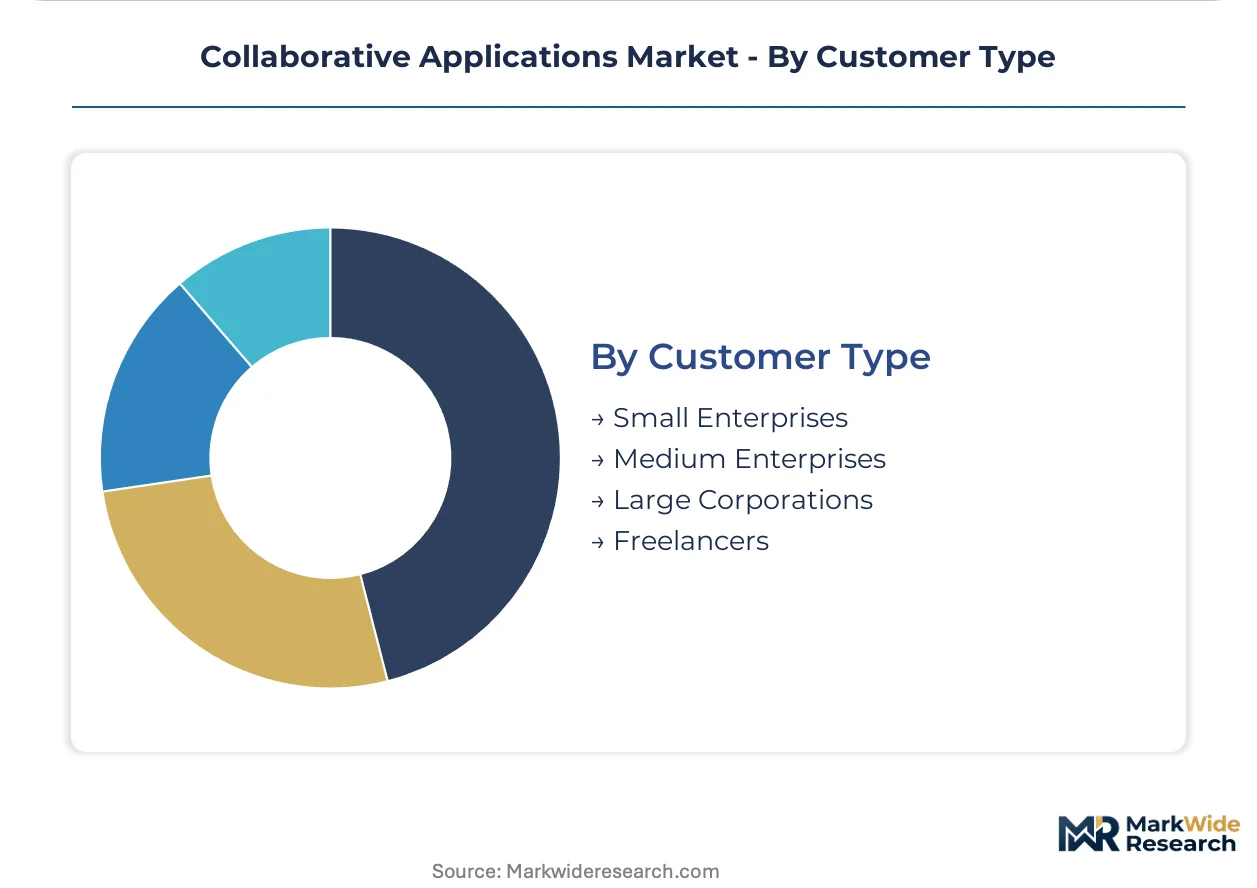
- Small Enterprises:Organizations under 50 employees with departmental purchasing authority and month-to-month subscription preferences. India's manufacturing SMEs, catalyzed by PLI scheme digitization, represent emerging demand concentration.
- Medium Enterprises:Companies with 50-999 employees and emerging IT governance functions. Outcome-based pricing pilots and productivity metric frameworks gain traction fastest in this tier.
- Large Corporations:Fortune 1000 entities with centralized procurement, security review committees, and multi-year enterprise agreements. Ecosystem breadth and API interoperability dominate vendor selection over feature depth.
- Freelancers:Independent contractors and micro-businesses with consumer-grade entry points and individual payment methods. Solopreneur growth in creative and consulting verticals sustains this segment.
Large Corporations anchor procurement value; Medium Enterprises are gaining share fastest as governance maturity spreads downward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States corporations anchor procurement volume for collaborative applications, though regulatory divergence across major economies is fragmenting vendor architecture requirements.
United States
Fortune 500 technology and financial services firms drive enterprise-wide platform consolidation, replacing fragmented point solutions with unified cloud suites. FCC broadband quality guidelines and HIPAA interoperability mandates shape product certification requirements for hospital networks and telehealth providers. Silicon Valley and Seattle metropolitan clusters concentrate vendor engineering resources and enterprise sales operations.
Germany
Automotive manufacturers and industrial conglomerates demand hybrid deployment architectures balancing cloud scalability with on-premise data residency. GDPR Article 17 automated deletion requirements and EU AI Act audit logging obligations force retention policy redesigns. Munich and Stuttgart industrial corridors prioritize platforms with built-in explainability dashboards for AI-assisted document routing.
United Kingdom
Professional services firms and fintech startups accelerate adoption of embedded generative AI for meeting summarization and contract drafting. Outcome-based pricing pilots gain traction among mid-market enterprises with mature procurement functions. London's financial district and Manchester's technology corridor represent concentrated demand for FedRAMP-authorized platforms serving government contractors.
India
Manufacturing small-and-medium enterprises catalyzed by PLI scheme digitization are adopting cloud collaboration for first-time workforce coordination. TRAI broadband expansion enables mobile-first messaging adoption among frontline workers in Gujarat and Tamil Nadu industrial belts. Bangalore and Hyderabad technology clusters drive developer-centric platform demand integrating code repositories with sprint planning workflows.
Japan
Large enterprises in electronics and automotive verticals maintain conservative procurement cycles favoring established vendors with localized support infrastructure. METI data governance guidelines influence cross-border document sharing architecture for multinationals with EU operations. Tokyo-Osaka corridor concentrates headquarters procurement decisions while regional manufacturing sites pilot mobile-first shift coordination tools.
Collaborative Applications Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded AI differentiation and frontline worker enablement. The market exhibits tiered concentration with ecosystem breadth privileging platform vendors over point solution specialists. Three strategic archetypes dominate: cloud-native suite providers anchoring enterprise-wide contracts, CRM-integrated workflow platforms capturing sales and service teams, and developer-centric tooling specialists dominating technical adoption. Competitive moves center on native generative AI embedding and vertical-specific compliance certification acceleration.
Within the ecosystem-anchored tier, Microsoft and Google exemplify platform breadth strategies binding video conferencing, document collaboration, and productivity tools into unified enterprise agreements. Salesforce occupies a position representing CRM-integrated workflow specialization, while Atlassian sits within the developer-centric archetype dominating technical team project management adoption. These three companies collectively illustrate how competitive positioning stratifies across organizational function rather than feature depth alone.
| Leading Market Players |
|---|
| Microsoft |
| Zoom |
| Salesforce |
| Cisco Systems |
| Atlassian |
| Slack Technologies |
| Zoho Corporation |
| IBM |
| Others |
Supply Flow & Price Mechanics
EU AI Act algorithmic transparency mandates gate qualified supply for premium-tier collaboration suites, compressing margins for non-compliant vendors while elevating pricing power for platforms with built-in explainability dashboards and automated audit logging. Procurement teams in Germany and France now treat GDPR Article 17 deletion capabilities as threshold requirements that separate qualified from disqualified suppliers.
Pricing Analysis
Volume concentrates in cloud-based per-seat subscriptions among United States mid-market enterprises, while margin accretion sits with hybrid deployment configurations serving European financial institutions. Pricing stratifies across FedRAMP-authorized, ISO 27001-certified, and uncertified tiers, with certification level commanding substantial premiums in government and healthcare verticals. Cost compression in standard cloud tiers is intensifying because hyperscaler compute pricing volatility feeds through to SaaS vendor cost bases. Small enterprises in India exhibit highest price sensitivity, while Fortune 500 technology firms prioritize ecosystem breadth over per-seat cost optimization.
Supply Chain Analysis
Cloud compute provisioning rests on United States, European, and Indian hyperscaler regions, with data center capacity expansion tethered to local energy grid constraints and permitting timelines. Critical inputs span GPU clusters for AI inference, submarine cable bandwidth for transatlantic latency, and specialized encryption hardware for FedRAMP compliance. Single-source vulnerability concentrates in NVIDIA GPU supply for generative AI features, exposing vendors to allocation rationing. Distribution runs through direct enterprise sales teams for large corporations and self-service web portals for small enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FedRAMP authorization queue bottlenecks prop pricing for compliant vendors, creating supply-constrained conditions that favor early certification investors over late entrants awaiting 12-18 month approval cycles.
For Market Incumbents: Hedge against hyperscaler pricing power by negotiating multi-year capacity reservations with alternative cloud providers and accelerating in-house AI model training infrastructure to reduce third-party API dependency. Defensive consolidation around vertical-specific compliance certifications—particularly HIPAA-adjacent healthcare interoperability and StateRAMP variants—creates moats against point-solution challengers. For New Entrants and Emerging Players: Capture frontline worker enablement white space in United States retail and logistics verticals where mobile-first shift coordination remains underpenetrated relative to knowledge-worker saturation. India's manufacturing SMEs, catalyzed by PLI scheme digitization, represent the most penetrable geography for first-time cloud collaboration adoption displacing consumer messaging tools. A vertical-specific compliance-fast-follow go-to-market angle—targeting sectors with recently clarified regulatory requirements—sidesteps direct confrontation with ecosystem-anchored incumbents. For Investors and Strategic Acquirers: First FedRAMP authorization announcements from previously uncertified vendors is the leading indicator that revenue recognition acceleration and government sector access expansion are imminent. Long-term viability across the projection horizon hinges on native generative AI embedding rather than third-party API dependency, favoring acquisition targets with in-house model development capabilities and proprietary training data licensing frameworks. Watch for EU AI Act enforcement actions imposing administrative fines as the signal that compliance infrastructure investments are translating into sustainable pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies video conferencing, document collaboration, and workflow automation into single enterprise agreements reducing procurement fragmentation. |
| Compliance Certification Acceleration | Shortens FedRAMP and StateRAMP authorization timelines to capture government sector revenue before competitor queue positions mature. |
| Native AI Embedding | Builds in-house generative capabilities for meeting transcription and task extraction rather than third-party API dependency. |
| Vertical-Specific Partnership | Aligns with hospital networks and telehealth providers navigating HIPAA interoperability mandates for secure patient data sharing. |
| Geographic Expansion | Establishes India data center presence to serve PLI-scheme manufacturing SMEs with localized latency and data residency compliance. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across CTOs, IT procurement officers, platform engineers, and channel partners. SEC 10-K disclosures, hyperscaler capex reports, and FedRAMP authorization databases provided vendor-specific operational metrics. Bottom-up seat-count modeling and top-down enterprise spend allocation were triangulated against cloud infrastructure provisioning data.
Granularity-level modeling deployed deployment mode, organization size, vertical industry, and integration complexity as core segmentation dimensions across the analysis window. CAGRs were derived from growth rate convergence analysis applied to historical adoption curves and projected regulatory enforcement timelines. Forecast inputs incorporated EU AI Act implementation pace, India PLI scheme disbursement schedules, and hyperscaler data center expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI training data licensing litigation, sovereign cloud mandates in India and China, and hyperscaler concentration risk. Assumptions underlying projections reflect current regulatory trajectories and procurement pattern stability. A small set of named triggers—FedRAMP authorization timeline shifts, EU AI Act fine precedents, and GPU supply allocation disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Forestry Software Market
Software & Services
Co-Browsing Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Asia-Pacific Text to Speech (TTS) Software Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
Global User Research and User Testing Software Market
Software & Services
Global Retail Execution Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Telecom IT Services Market
Software & Services
Global Order Management Software Market
Software & Services
Global Electronic Data Capture Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Estate Management Software Market
Software & Services
Global Electronic Lab Notebook (ELN) Market