
 Hair Colorants Market | 2026-2036
Hair Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Colorants Market Outlook
Plant-derived dye precursors and bond-building additive chemistry is tilting formulation roadmaps away from traditional oxidative systems. L'Oréal S.A. leverages its integrated raw-materials research to control pigment stability across climate zones. Henkel AG & Co. KGaA anchors European manufacturing with specialized alkali-free product lines. Shiseido Company Limited competes through advanced emulsion technologies tailored to Asian hair fiber structures.
Hair colorants are cosmetic preparations containing oxidative or direct dyes, coupling agents, alkalizers, and conditioning polymers designed to alter natural hair pigment through chemical reaction or surface deposition, typically formulated at pH 9–11 for permanent variants and pH 4–6 for temporary types. Permanent colorants dominate value pools due to higher per-application pricing and repeat purchase frequency, while semi-permanent formulations capture growing share among consumers seeking lower-commitment shade experimentation. Professional use applications command premium positioning through stylist-applied techniques requiring technical training, whereas at-home use segments sustain volume through mass retail distribution and subscription replenishment models.
FDA color additive regulations govern permitted dye substances in the United States, while REACH and the EU Cosmetics Regulation restrict certain aromatic amines and mandate safety dossier submission for new ingredients. India's BIS standards and CDSCO cosmetic labeling rules are tightening import scrutiny and domestic manufacturing compliance. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions and state-level clean beauty legislation that could force reformulation across multiple regional portfolios.
Market Dynamics
Professional salon channels are capturing disproportionate value as stylists abandon ammonia-based oxidative systems for gentler alkalizers, compressing legacy mass-market margins while elevating technical-service premiums.
Growth Catalysts
- REACH aromatic amine restrictions:European reformulation mandates are accelerating clean-label innovation cycles and opening premium positioning for compliant suppliers.
- Urban Indian middle-class expansion:Tier-1 and Tier-2 city consumers are driving dual-track demand for both accessible retail colorants and prestige salon treatments.
- Bond-building additive chemistry:Cysteamine and maleic acid derivatives are reducing fiber damage claims and extending color retention intervals.
Market Restraints
- Precursor chemical cost volatility:P-phenylenediamine and toluene-2,5-diamine sulfate face feedstock pressure from benzene derivative markets.
- East Asian pigment concentration:Specialty iron oxide and mica suppliers cluster in China's Zhejiang and Jiangsu provinces, creating single-source vulnerability.
- FDA color additive petition timelines:New direct dye approvals average 18-24 months, blocking rapid shade innovation for US portfolios.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer auto-ship programs are capturing recurring revenue from at-home colorant users in North America.
- India BIS certification alignment:Domestic manufacturing incentives under the PLI scheme are lowering import dependency for multinational brands.
- Plant-derived dye precursor convergence:Henna-lawsonia and indigo-woad extraction methods are merging with low-pH emulsion systems for natural-positioned lines.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in alkali-free oxidative systems remains concentrated among senior practitioners at established houses.
- Multi-jurisdiction dossier management:REACH safety data, FDA color additive petitions, and CDSCO cosmetic labeling rules require parallel compliance investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Colorants Market |
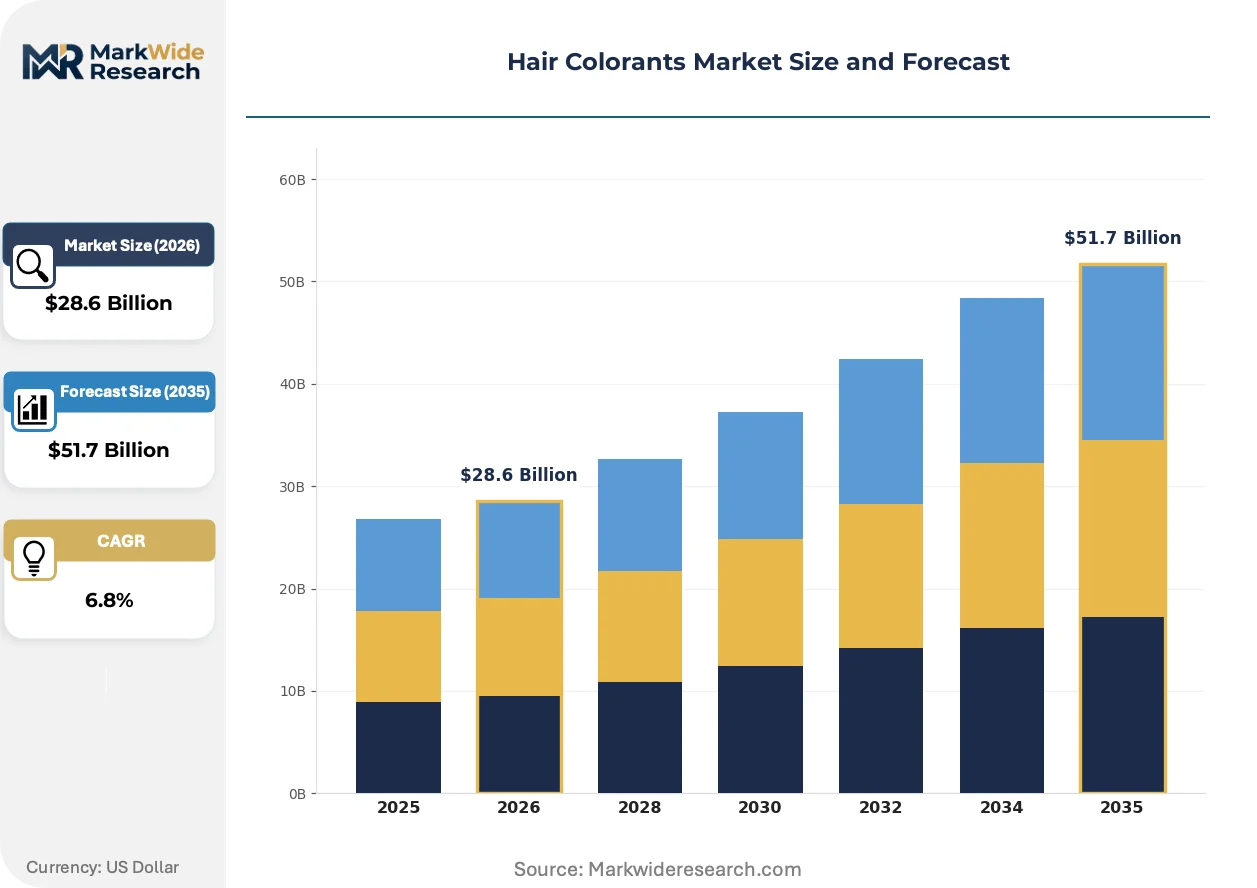
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent, Semi-Permanent, Temporary, Highlighting Application: At-Home Use, Professional Use, Retail Products, Salon Services Form: Cream, Gel, Liquid, Powder Color Type: Natural, Fashion, Gray Coverage, Others |
| Companies Covered | L'Oréal S.A, Henkel AG & Co. KGaA, Coty Inc., Revlon Inc., Kao Corporation, Procter & Gamble, Shiseido Company Limited, Godrej Consumer Products Limited, Estée Lauder Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Colorants Market Strategic Shifts
Formulation science is bifurcating between high-performance oxidative permanents and clean-label naturals, with digital tools now mediating shade matching and personalized regimen design across both tracks.
Artificial intelligence-driven spectrophotometry is digitizing the shade consultation process. Salon chains and direct-to-consumer platforms are deploying smartphone-based color-matching algorithms to reduce in-person consultation time. This compression of the shade-selection workflow is digitizing inventory forecasting and enabling just-in-time pigment blending at regional distribution hubs.
REACH Annex XVII restrictions on sensitizing aromatic amines are tightening permissible dye precursor lists. The European Chemicals Agency's 2023-2024 dossier updates have forced reformulation of several oxidative couplers. Professional colorant portfolios targeting EU distribution are responding with accelerated substitution programs for para-aminophenol derivatives.
Subscription-based replenishment is displacing episodic retail purchasing among at-home colorant users. E-commerce platforms and specialized beauty retailers are capturing recurring revenue through algorithmic shade-matching and scheduled delivery. This behavioral shift is most visible in the United States, where auto-ship penetration in hair colorant categories now exceeds that of comparable cosmetic segments.
Hair Colorants Market Segmentation
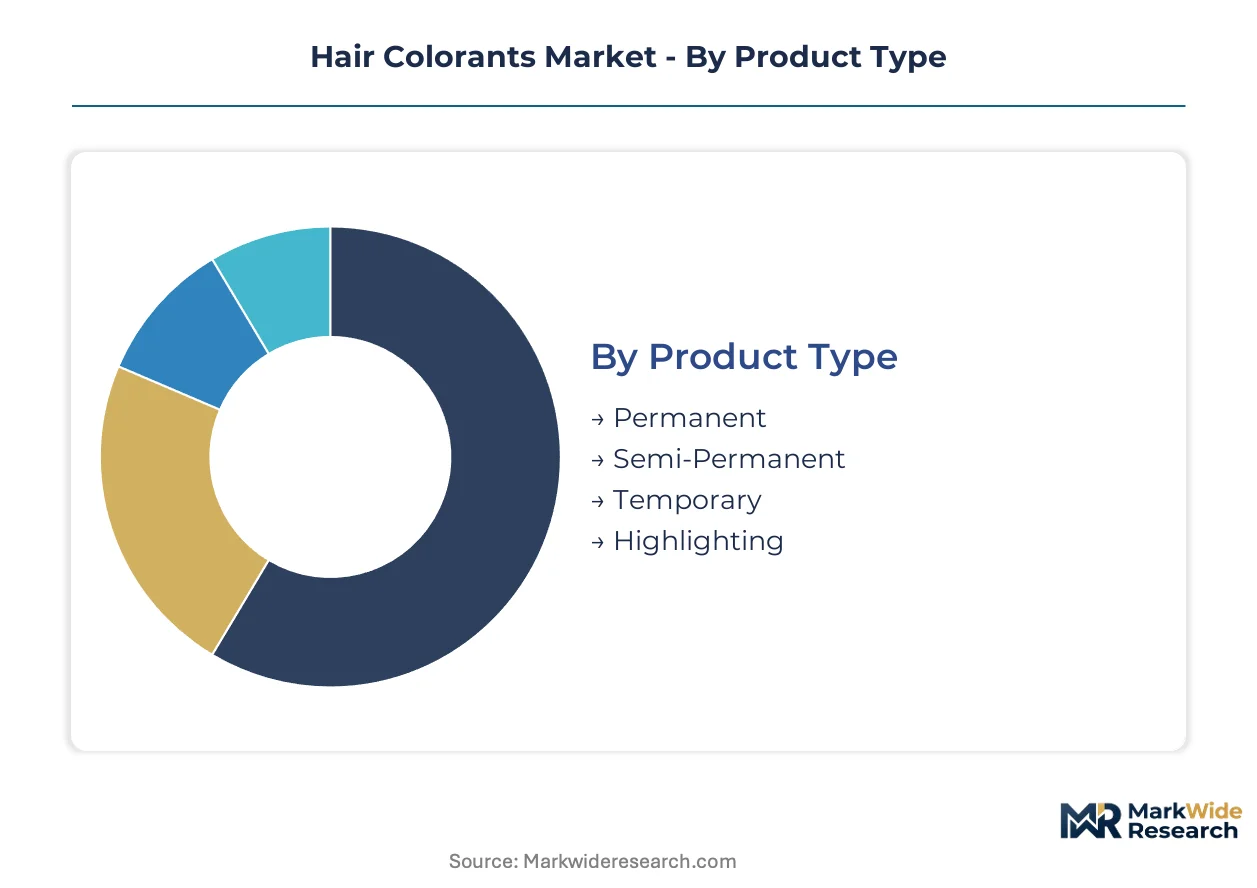
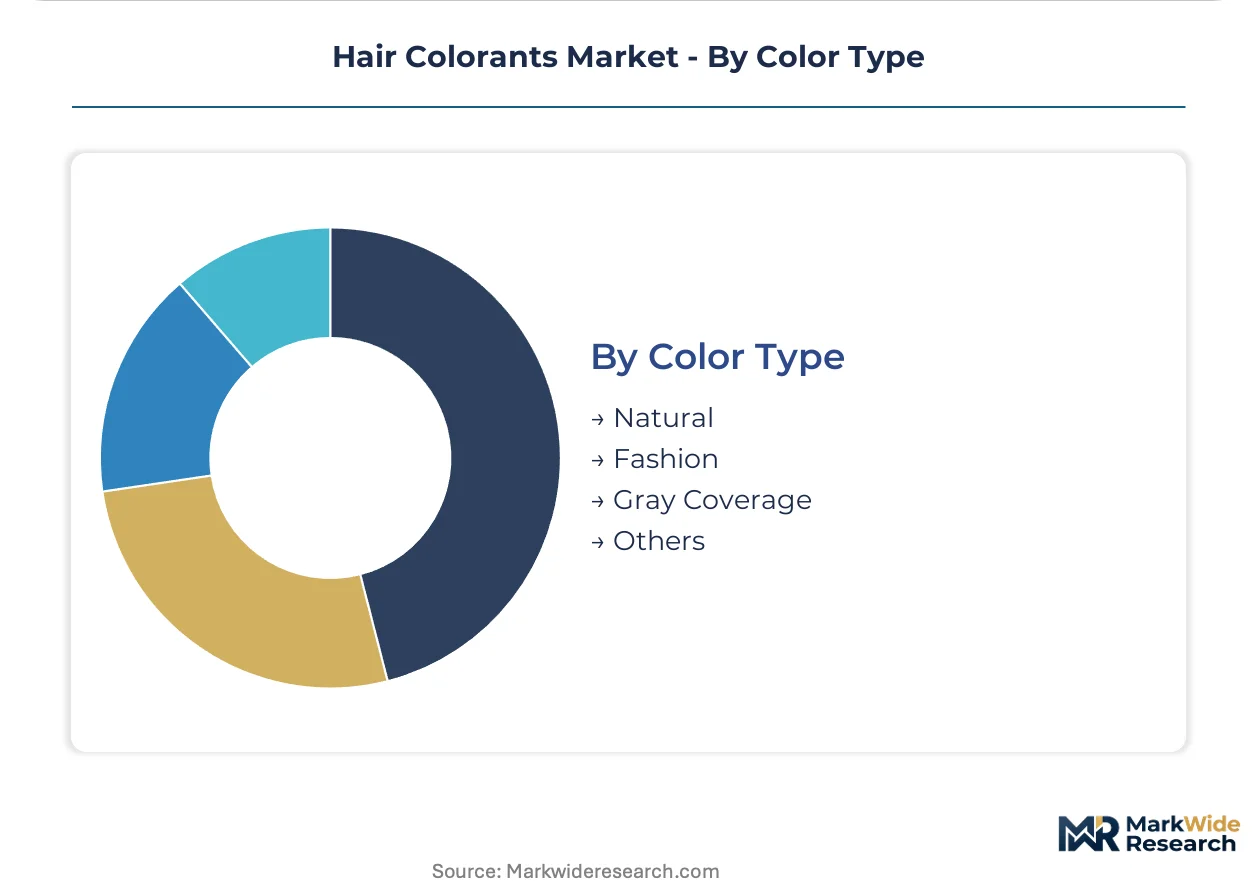
Hair colorant segmentation reflects divergent consumer commitment levels and technical complexity requirements. Product permanence, application setting, physical form, and color intent each create distinct margin profiles and regulatory exposure tiers.
Product Type:
Mature oxidative systems anchor value pools while emerging low-damage alternatives capture reformulation-driven premiums.
- Permanent:Ammonia or MEA-based oxidative formulations penetrate the cortex to permanently alter melanin structure. Professional salons in India and the United States drive disproportionate volume for ammonia-free variants as stylists abandon legacy alkalizers. REACH aromatic amine restrictions are compressing margins for non-compliant portfolios.
- Semi-Permanent:Direct dyes deposit without peroxide oxidation, offering 4-12 week fade cycles that appeal to shade experimenters. Urban Indian middle-class consumers and North American subscription replenishment programs represent the steepest demand concentration for these lower-commitment formats.
- Temporary:Surface-coating colorants wash out within 1-3 shampoos, formulated at acidic pH with high molecular weight pigments. Festival and event-driven purchases in Tier-1 Indian cities sustain seasonal volume spikes.
- Highlighting:Bleach-based lightening systems with tonal overlays require precise developer concentration control. Professional application dominates given the technical risk of fiber damage.
Permanent retains volume leadership; semi-permanent holds the steepest expansion curve.
Application:
Cost tier stratification separates technical-service premiums from mass-retail velocity.
- At-Home Use:Mass-market kits with pre-measured developer and conditioning aftercare dominate unit economics. Subscription auto-ship models in the United States are displacing episodic retail purchasing through algorithmic shade matching.
- Professional Use:Salon-applied colorants command 3-5x per-application pricing through stylist expertise and customized formulation blending. Bond-building additive chemistry is accelerating technician preference for alkali-free oxidative systems.
- Retail Products:Drugstore and specialty beauty channels sustain volume through impulse placement and shade range breadth. India's BIS certification alignment is lowering import dependency for multinational brand distribution.
- Salon Services:Integrated color-and-styling packages capture recurring appointment revenue. Technical training requirements create barriers to substitution by at-home alternatives.
Professional use captures margin leadership; at-home use maintains the broadest volume base.
Form:
Application precision and manufacturing complexity create differentiated supply chain configurations.
- Cream:Viscous emulsions with controlled spreadability dominate permanent colorant formulations. Professional stylists prefer cream rheology for root-to-tip precision.
- Gel:Thixotropic systems cling to vertical hair surfaces without dripping, suited for highlighting and precision application. Asian hair fiber structures favor gel penetration profiles.
- Liquid:Low-viscosity solutions enable spray or brush application for temporary colorants and toners. Rapid drying characteristics suit time-constrained at-home users.
- Powder:Bleach-lightening bases require on-site developer activation, limiting shelf stability risk. Professional salons control inventory through just-in-time mixing protocols.
Cream retains formulation dominance; gel gains share fastest in precision-application segments.
Color Type:
Customer lifecycle stage and aesthetic intent partition demand across natural-positioned and fashion-forward portfolios.
- Natural:Melanin-mimicking browns, blacks, and auburns formulated with PPD-derived precursors. Gray coverage requirements among aging populations in the United States and Europe sustain repeat purchase frequency.
- Fashion:Vivid direct dyes in non-natural blues, pinks, and pastels requiring pre-lightened bases. Social media-driven shade experimentation concentrates among urban Indian and North American younger demographics.
- Gray Coverage:Specialized oxidative systems with enhanced white-hair uptake and resistant gray targeting. Professional color correction services command premium positioning for stubborn gray patterns.
- Others:Niche categories including corrective color, color removers, and specialty toners. Low volume but high margin through technical complexity.
Natural shades retain volume leadership; fashion colors climb the fastest among younger consumer cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports specialty dye precursors and emulsion technologies to India, where urban consumption is accelerating fastest. Germany ships bond-building additive chemistry to professional salon networks across Western Europe. Japan supplies precision pigment dispersion systems to South Korean and Chinese manufacturers.
United States
Subscription auto-ship penetration exceeds comparable cosmetic categories as algorithmic shade-matching reduces consultation friction. FDA color additive petitions average 18-24 months, blocking rapid shade innovation. Manufacturing clusters concentrate in New Jersey and California for proximity to East and West Coast distribution hubs.
India
Tier-1 and Tier-2 city consumers drive dual-track demand for mass-market retail kits and prestige salon treatments. BIS certification alignment under PLI scheme incentives lowers import dependency for multinational brands. Mumbai and Delhi-NCR anchor domestic manufacturing expansion for ammonia-free oxidative systems.
Germany
Professional stylists accelerate abandonment of ammonia-based systems for alkali-free alternatives with bond-building additives. REACH Annex XVII aromatic amine restrictions force reformulation of para-aminophenol derivatives. Düsseldorf and Hamburg host specialized manufacturing for compliant European distribution.
Japan
Advanced emulsion technologies target Asian hair fiber structures with gel penetration profiles suited to precision application. METI standards govern cosmetic safety dossier preparation for regional export. Osaka and Tokyo metropolitan areas concentrate R&D for low-pH natural-positioned lines.
France
Integrated raw-materials research controls pigment stability across climate zones from humid Southeast Asia to arid Middle East. ANSM cosmetic labeling rules align with REACH disclosure requirements. Paris-region facilities export formulation expertise to Indian and Brazilian subsidiary operations.
Hair Colorants Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent margin structures. Salon-service integration captures premium positioning through technical training barriers, while mass-retail velocity depends on shade range breadth and shelf placement economics. Three archetypes dominate: multinational beauty conglomerates with captive raw-materials research, regional specialists in alkali-free formulations, and direct-to-consumer platforms with algorithmic replenishment. Competitive moves concentrate on M&A for clean-label technology access and geographic expansion into Indian manufacturing zones.
Among multinational conglomerates, L'Oréal S.A. and Henkel AG & Co. KGaA exemplify divergent strategic positions. L'Oréal occupies a channel-integrating role through salon-distribution control and climate-zone pigment stability expertise. Henkel anchors European manufacturing specialization with alkali-free product lines serving REACH-compliant markets. Shiseido Company Limited represents the Asia-Pacific technology vector, with emulsion systems tailored to regional hair fiber structures.
| Leading Market Players |
|---|
| L'Oréal S.A |
| Henkel AG & Co. KGaA |
| Coty Inc. |
| Revlon Inc. |
| Kao Corporation |
| Procter & Gamble |
| Shiseido Company Limited |
| Godrej Consumer Products Limited |
| Estée Lauder Companies Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Zhejiang pigment cluster is compressing spot prices for iron oxide precursors while forcing European formulators to absorb premium freight costs for REACH-compliant alternatives, tightening margins across both mass-market and professional tiers.
Pricing Analysis
Technology-generation pricing gaps separate legacy ammonia-based oxidative systems from next-generation alkali-free formulations with bond-building additives. Three-tier pricing structure across premium salon-service, standard retail-kit, and economy private-label levels stratifies the market, with certification grade and stylist-applied technical service as primary differentiation drivers. Cost compression in mass-market retail channels is intensifying because of subscription auto-ship displacement of episodic purchasing. At-home users show highest price sensitivity, while professional salon clients demonstrate lowest sensitivity due to service-attach bundling.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk planning for specialty pigment procurement. Geographic supply concentration centers on China for iron oxide and mica, Germany for bond-building additive chemistry, and India for henna-lawsonia extraction. Raw material dependencies include P-phenylenediamine precursors, cysteamine derivatives, and emulsion stabilizers. Single-source vulnerability in Zhejiang province pigment processing creates concentration risk. Distribution runs through professional salon networks for premium tiers and mass retail channels for at-home segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hair colorants market functions as a service-attach opportunity where subscription replenishment revenue and salon technical-service premiums expand faster than hardware-only product sales.
For Market Incumbents: Build captive raw-materials moats through backward integration into dye precursor synthesis and climate-zone pigment stability testing. Defensive consolidation should prioritize REACH-compliant formulation portfolios to preempt regulatory displacement, while capacity addition in Indian manufacturing zones captures PLI scheme incentives and reduces import dependency exposure. For New Entrants and Emerging Players: Establish a beachhead in India's Tier-2 city professional salon channel where multinational brand presence remains thin and BIS certification creates manageable compliance barriers. The most penetrable segment is ammonia-free oxidative systems for gray coverage, with go-to-market execution through stylist training partnerships and localized shade-matching algorithms. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer platforms with algorithmic auto-ship programs and professional salon chains with integrated color-and-styling memberships. Long-term viability over the next decade favors acquisition targets with clean-label technology portfolios and Indian manufacturing footprints. The signal to watch is CDSCO cosmetic labeling rule enforcement tightening as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Precursor Synthesis | L'Oréal's captive pigment stability research reduces feedstock volatility exposure across climate zones. |
| REACH-Compliant Formulation Repositioning | Henkel's alkali-free product lines capture professional stylist preference shifts in European markets. |
| Subscription Auto-Ship Platform Launch | Direct-to-consumer algorithmic shade-matching displaces episodic retail purchasing in North America. |
| Indian Manufacturing Footprint Expansion | Godrej's domestic production under PLI incentives lowers import dependency for multinational distribution. |
| Professional Stylist Training Partnership | Shiseido's technical education programs create switching costs through Asian hair fiber expertise. |
Study Parameters
Cross-validation between primary interviews with cosmetic chemists, salon chain procurement directors, and retail category buyers anchors the qualitative findings against secondary validation from customs records, BIS certification databases, and FDA color additive petition filings. Bottom-up triangulation of formulation-level cost structures converges with top-down trade flow analysis across the analysis window.
Calibration against historical volume trajectories and regulatory announcement timelines shapes the analytical framework across product permanence, application setting, physical form, and color intent segmentation dimensions. CAGRs were derived from modeled adoption curves for bond-building additive chemistry and subscription replenishment penetration rates, with inputs from REACH aromatic amine restriction timelines and Indian urban middle-class expansion patterns.
Sensitivities concentrate around CDSCO enforcement intensity, benzene derivative feedstock volatility, and stylist preference shifts between ammonia-free and traditional oxidative systems. Forecasts reflect documented assumptions on regulatory implementation pace and consumer behavioral stickiness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
Pigment Dispersions Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Color Retention Agents Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Ultramarine Pigments Market
Dyes and Pigments
Europe Pigments Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Pigment Dispersion Resin Market